
 Mucous Membrane Pemphigoid Treatment Market | 2026-2036
Mucous Membrane Pemphigoid Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mucous Membrane Pemphigoid Treatment Market Foresight
Specialty pharmacies is redrawing the distribution hierarchy for mucous membrane pemphigoid therapeutics, pulling volume away from traditional hospital outpatient channels. Genentech leverages its biologic manufacturing infrastructure to dominate the rituximab supply position for severe cases. Pfizer competes through its immunology portfolio breadth, while AbbVie anchors its position with adalimumab access programs for refractory patients.
Mucous membrane pemphigoid treatment encompasses pharmacologic interventions targeting autoimmune blistering at mucosal surfaces, primarily employing corticosteroids, immunosuppressants, and biologics to suppress pathogenic antibody production against basement membrane zone proteins. Biologics command the fastest expansion trajectory among product types, driven by rituximab and emerging B-cell targeted mechanisms. Intravenous administration routes sustain premium pricing positions despite patient inconvenience, while topical corticosteroids occupy the high-volume, lower-margin tier for ocular and oral maintenance therapy.
The FDA's orphan drug designation framework shapes development economics by granting exclusivity and tax incentives for rare disease indications, while the EMA's parallel pathway accelerates European market access for biologic therapies. Clinicians and procurement officers must monitor biosimilar entry timelines for reference biologics and evolving payer prior authorization criteria for off-label immunosuppressant use.
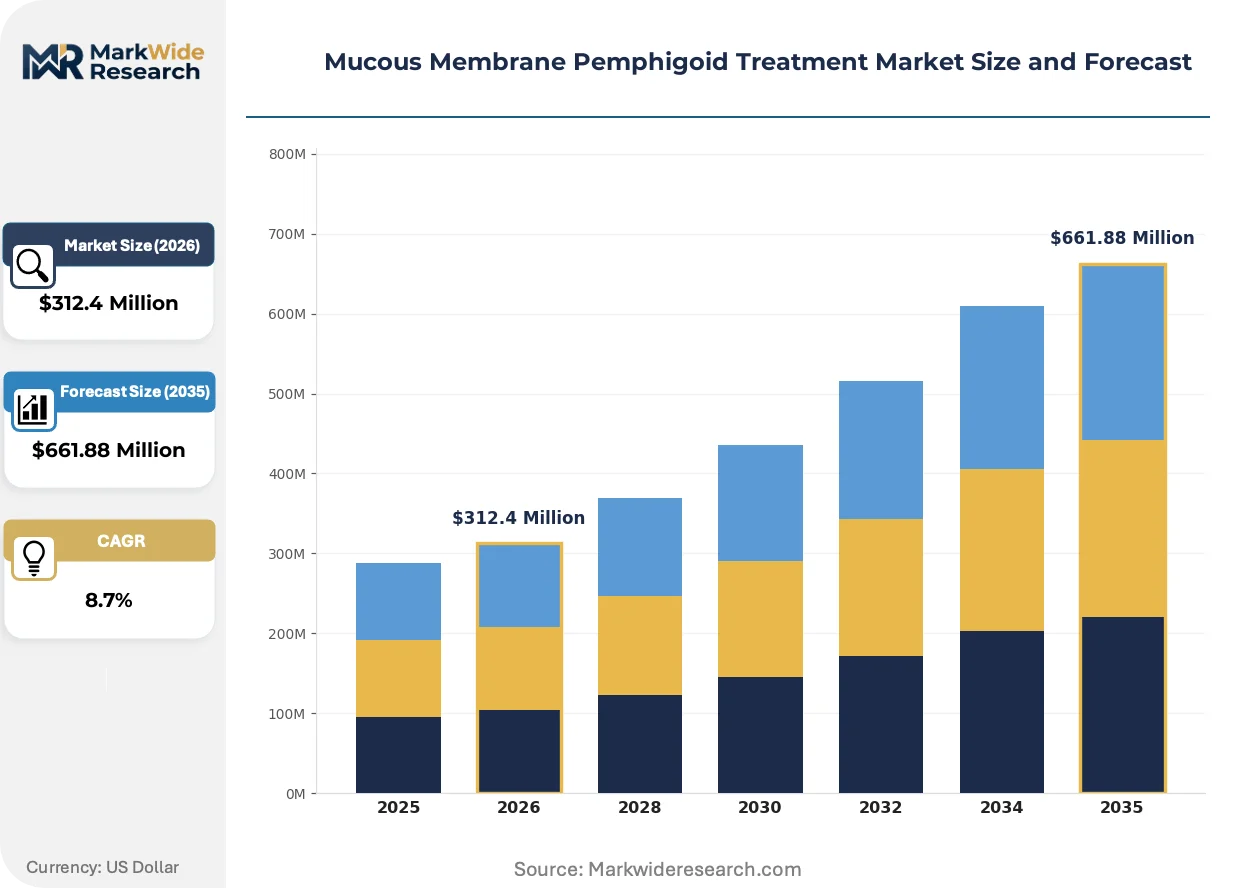
Market Dynamics
Specialty pharmacies are consolidating distribution control for mucous membrane pemphigoid therapeutics, displacing hospital outpatient channels through direct-to-patient logistics and reimbursement navigation services that biologic manufacturers now prefer.
Growth Catalysts
- FDA Orphan Drug Exclusivity:The seven-year market exclusivity provision accelerates biologic development timelines for rare autoimmune indications, incentivizing sponsors to pursue B-cell targeted mechanisms.
- Ocular Manifestation Prevalence:Rising diagnosis rates of cicatricial pemphigoid among aging populations in the United States drive demand for maintenance immunosuppression protocols.
- Rituximab Mechanism Validation:CD20-directed B-cell depletion has established durable remission benchmarks in refractory cases, expanding prescriber confidence beyond corticosteroid-first approaches.
Market Restraints
- Biologic Manufacturing Concentration:Single-source dependence on mammalian cell culture facilities in Switzerland and Massachusetts creates supply vulnerability for monoclonal antibody production.
- Prior Authorization Friction:Payer step-therapy requirements for off-label immunosuppressants delay treatment initiation by 30-90 days in commercial insurance plans.
- Topical Corticosteroid Substitution:High-potency ophthalmic drops and intralesional triamcinolone provide lower-cost maintenance alternatives that compress biologic penetration in mild-to-moderate cases.
Strategic Opportunities
- Brazil Regulatory Pathway:ANVISA's simplified rare disease registration framework offers accelerated entry for biosimilar rituximab products targeting Latin American ophthalmology networks.
- Subcutaneous Formulation Development:Self-administered delivery mechanisms for B-cell modulators would displace intravenous infusion centers and expand community-based treatment access.
- Teledermatology Integration:Remote mucosal monitoring platforms enable rural patient enrollment in specialty pharmacy programs previously limited to academic medical centers.
Industry Challenges
- Histopathology Skill Scarcity:Direct immunofluorescence interpretation for basement membrane zone antibody patterns requires specialized dermatopathology training that community hospitals lack.
- Multidisciplinary Care Coordination:Synchronizing ophthalmology, dermatology, and oral medicine schedules creates patient drop-off between diagnostic confirmation and treatment initiation.
- Biosimilar Switching Complexity:Immunogenicity monitoring protocols for reference biologic transitions demand enhanced pharmacovigilance infrastructure that smaller infusion centers cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mucous Membrane Pemphigoid Treatment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Corticosteroids, Immunosuppressants, Biologics, Antibiotics Administration Route: Topical, Intravenous, Oral, Subcutaneous End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Treatment Frequency: Daily, Weekly, Monthly, As Needed |
| Companies Covered | Genentech (Roche), Pfizer, Novartis, Merck & Co., GlaxoSmithKline, Sanofi, Bristol-Myers Squibb, AbbVie, Regeneron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mucous Membrane Pemphigoid Treatment Market Shifts & Advancements
Autoimmune blistering disease management is fragmenting across precision medicine pathways, with molecular diagnostics and targeted biologics displacing empiric immunosuppression protocols in academic referral networks.
B-cell depletion therapy is bifurcating the severe disease segment into rituximab-responsive and rituximab-refractory cohorts, enabling personalized retreatment scheduling based on CD19+ cell recovery kinetics. Academic medical centers in Germany and the United States are adopting these biomarker-guided protocols fastest. This stratification is compressing market share for cyclophosphamide-based regimens that previously dominated refractory case management.
EMA's PRIME designation pathway is compressing assessment timelines for novel biologics targeting mucosal pemphigoid subsets, with rolling review mechanisms reducing time-to-market by 12-18 months for qualifying sponsors. The industrial consequence is accelerated European launch sequencing that precedes United States commercialization for select development programs. Ocular and oral manifestations are attracting disproportionate development investment under this framework due to clearer endpoint validation.
Patient advocacy organizations are reshaping trial enrollment patterns by mandating decentralized visit options and direct travel reimbursement, forcing sponsors to redesign Phase III protocols around home health nursing and local laboratory networks. This displacement of site-centric models is most visible in the United States, where the National Organization for Rare Disorders has established preferred site partnerships that concentrate recruitment in 12 metropolitan hubs.
Mucous Membrane Pemphigoid Treatment Market Segmentation
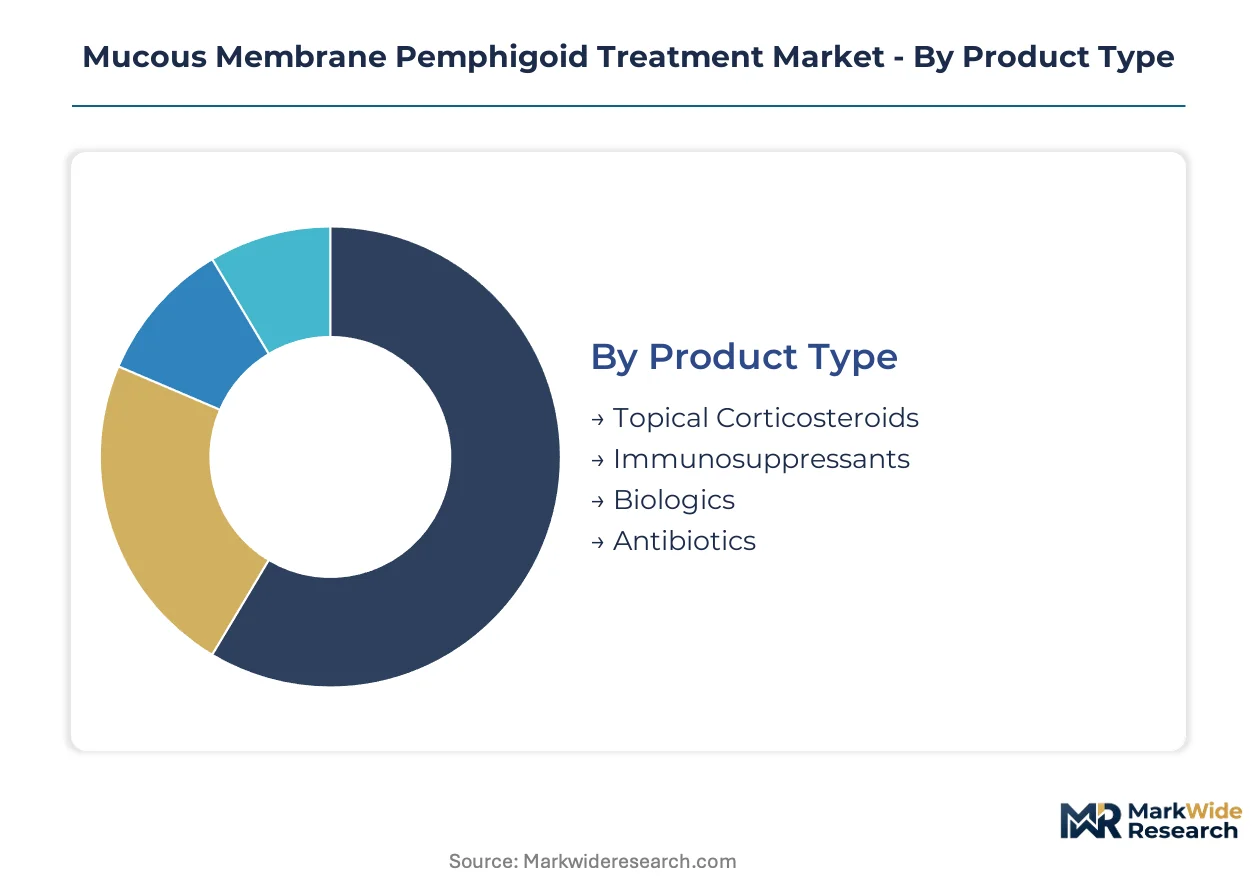
Treatment modality selection for mucous membrane pemphigoid varies sharply by disease severity and anatomical involvement. Segmentation reveals how biologics command premium positioning while corticosteroids sustain volume leadership across maintenance protocols.
Product Type:
Geographic demand patterns split sharply: topical corticosteroids dominate domestic maintenance prescriptions, while biologics concentrate in United States and German export markets where reimbursement infrastructure supports infusion-based protocols.
- Topical Corticosteroids:High-potency ophthalmic drops and oral rinses form the first-line maintenance tier. Prescribing concentrates in community dermatology practices across the United States and Southern Europe where mild ocular manifestations predominate; cost sensitivity and established safety profiles limit biologic displacement in this cohort.
- Biologics:CD20-directed monoclonal antibodies, primarily rituximab, target refractory cases with cicatricial complications. Demand clusters in academic medical centers in Boston, Berlin, and Zurich where multidisciplinary ophthalmology-dermatology units manage severe disease; FDA orphan drug exclusivity sustains premium positioning against biosimilar pressure.
- Immunosuppressants:Cyclophosphamide and mycophenolate mofetil serve as bridge therapy between corticosteroid failure and biologic escalation.
- Antibiotics:Doxycycline and minocycline address secondary infection prophylaxis in erosive oral disease.
Topical corticosteroids hold the largest share; momentum sits with biologics.
Administration Route:
Cost tier stratification drives route selection: intravenous delivery commands the highest reimbursement rates, while oral generics compete on acquisition price in cash-pay markets.
- Intravenous:Infusion center administration of rituximab and cyclophosphamide requires specialized nursing infrastructure. Utilization concentrates in hospital outpatient departments across Germany and the United States where prior authorization workflows are streamlined; patient travel burden limits penetration in rural geographies.
- Topical:Ophthalmic drops, oral gels, and intralesional injections enable self-directed maintenance. Adoption spreads through community pharmacies in France, Italy, and Spain where primary care physicians manage stable disease; formulation stability concerns constrain tropical market expansion.
- Oral:Systemic corticosteroids and immunosuppressants suit patients without infusion access.
- Subcutaneous:Emerging delivery mechanisms for B-cell modulators target home administration.
Intravenous routes retain revenue concentration; subcutaneous development programs are expanding most quickly.
End User:
Customer type fragmentation reflects care complexity: academic hospitals manage diagnostic confirmation, while specialty pharmacies capture ongoing biologic dispensing.
- Specialty Pharmacies:Dedicated rare disease distributors coordinate prior authorization, patient assistance enrollment, and cold-chain logistics for biologic therapies. Growth concentrates in United States metropolitan hubs where hub-and-spoke models link urban infusion centers to rural dermatology practices; manufacturer preference programs accelerate channel shift from hospital outpatient.
- Hospitals:Academic medical centers handle diagnostic biopsy, direct immunofluorescence interpretation, and initial immunosuppression titration. Volume clusters in tertiary referral networks across Germany, Switzerland, and the northeastern United States where dermatopathology expertise concentrates; multidisciplinary care coordination requirements sustain institutional anchoring despite pharmacy channel encroachment.
- Clinics:Community dermatology and ophthalmology practices manage stable maintenance patients.
- Homecare Settings:Nurse-administered infusion and patient self-injection protocols target mobility-limited elderly populations.
Hospitals anchor diagnostic and acute care revenue; specialty pharmacies are gaining share fastest in maintenance biologic dispensing.
Treatment Frequency:
Volume scale differentiates frequency tiers: daily regimens generate prescription volume, while monthly infusions concentrate value.
- Monthly:Rituximab retreatment schedules follow CD19+ cell recovery kinetics in severe refractory disease. Protocol adoption spreads through German and United States academic centers implementing biomarker-guided personalization; infusion center capacity constraints limit expansion in smaller metropolitan markets.
- Daily:Topical corticosteroid maintenance for ocular and oral disease requires sustained patient adherence. Prescribing dominates in Southern European community settings where generic ophthalmic drops compete on pharmacy reimbursement tiers; generic substitution pressures compress margin despite volume scale.
- Weekly:Methotrexate and mycophenolate mofetil titration protocols bridge acute and maintenance phases.
- As Needed:Acute flare management with systemic corticosteroid bursts.
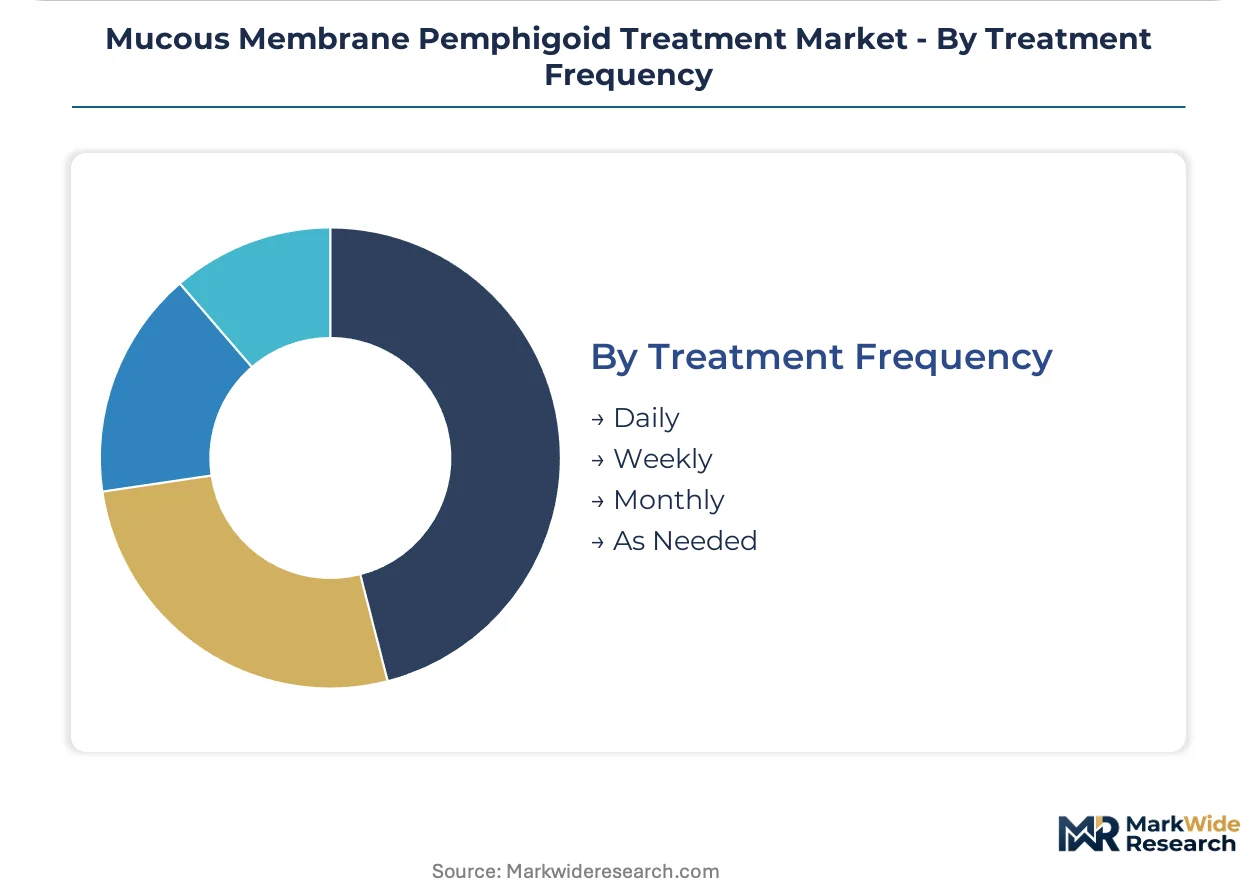
Daily regimens hold the largest share; monthly biologic protocols show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution primacy for temperature-sensitive biologics, while the Boston-to-Basel pharmaceutical corridor anchors transatlantic clinical trial coordination for rare autoimmune indications.
United States
FDA orphan drug exclusivity provisions accelerate biologic development timelines for rare disease sponsors. The National Institutes of Health maintains specialized dermatopathology training networks that concentrate diagnostic expertise in academic medical centers. Greater Boston hosts the densest cluster of ophthalmology-dermatology multidisciplinary units managing severe cicatricial pemphigoid cases.
Germany
EMA PRIME designation pathways compress assessment timelines for novel biologics targeting mucosal pemphigoid subsets. The country's statutory health insurance system reimburses rituximab retreatment protocols without prior authorization friction. Berlin and Heidelberg anchor biomarker-guided B-cell depletion therapy adoption, with CD19+ monitoring protocols spreading through university hospital networks.
Switzerland
Swissmedic's parallel scientific advice mechanisms synchronize regulatory submissions with EMA and FDA pathways. The Basel-Zurich corridor concentrates mammalian cell culture manufacturing capacity for monoclonal antibody production. Roche's Genentech affiliate leverages this infrastructure to dominate rituximab supply positioning for severe refractory cases across European export markets.
Japan
PMDA's sakigake designation system grants priority review for rare disease biologics with domestic development evidence. Aging demographic concentration in Tokyo-Osaka metropolitan corridors drives diagnosis rates for ocular manifestation subsets. Japanese ophthalmology societies have established maintenance immunosuppression protocols that favor topical corticosteroid-first approaches before biologic escalation.
Brazil
ANVISA's simplified rare disease registration framework offers accelerated entry for biosimilar rituximab products targeting Latin American markets. The São Paulo-Rio de Janeiro axis concentrates ophthalmology referral networks managing cicatricial pemphigoid complications. Public procurement programs through the Unified Health System create volume concentration for generic immunosuppressant bridge therapies.
Mucous Membrane Pemphigoid Treatment Market Competitive Landscape
Concentration sits with integrated biologic manufacturers possessing mammalian cell culture infrastructure and orphan drug exclusivity portfolios. The competitive terrain divides between reference biologic sponsors defending premium positioning and biosimilar entrants exploiting regulatory pathway simplifications. Three archetypes dominate: large-cap diversified immunology players, rare disease specialists leveraging FDA exclusivity mechanisms, and emerging biosimilar manufacturers targeting Latin American and European markets. Consolidation pressure manifests through biologic manufacturing asset acquisitions and specialty pharmacy distribution partnerships that displace hospital outpatient channels.
Among large-cap diversified players, Genentech and Pfizer exemplify contrasting strategic postures. Genentech anchors the severe disease segment through rituximab supply control and academic medical center relationships. Pfizer competes through immunology portfolio breadth spanning corticosteroid, immunosuppressant, and emerging biologic mechanisms. AbbVie occupies a distinct position with patient access program infrastructure for refractory cases requiring adalimumab off-label protocols.
| Leading Market Players |
|---|
| Genentech (Roche) |
| Pfizer |
| Novartis |
| Merck & Co. |
| GlaxoSmithKline |
| Sanofi |
| Bristol-Myers Squibb |
| AbbVie |
| Regeneron |
| Others |
Supply & Pricing Matrix
FDA orphan drug exclusivity provisions gate both supply qualification and price differentiation simultaneously, granting seven-year market exclusivity that sustains premium positioning for biologic developers while concentrating manufacturing investment in validated mammalian cell culture facilities.
Pricing Analysis
Volume-discount tiering structures separate originator biologics from biosimilar entrants from generic immunosuppressants, with FDA exclusivity status and infusion center certification levels driving price differentiation. Cost compression in the biosimilar tier is intensifying as ANVISA and EMA pathway simplifications accelerate entrant supply, while academic medical centers show least price sensitivity due to prior authorization insulation and patient assistance program capture.
Supply Chain Analysis
Swissmedic-coordinated mammalian cell culture capacity in Switzerland and Massachusetts anchors monoclonal antibody production, drawing from recombinant protein feedstocks and single-use bioreactor components. Single-source dependence on cold-chain logistics through the Port of Rotterdam creates tariff-exposed vulnerability, while distribution runs through specialty pharmacy hub-and-spoke networks displacing hospital outpatient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA orphan drug exclusivity and EMA PRIME designation pathways create seven-to-ten year barriers that compound manufacturing qualification costs and concentrate prescriber relationships.
For Market Incumbents: Shield rituximab positioning through backward integration into fill-finish capacity in Basel and Boston, while locking in specialty pharmacy exclusive distribution agreements that block biosimilar sample access. Genentech-scale manufacturers must secure CD19+ monitoring protocol sponsorships in German and United States academic centers to entrench biomarker-guided retreatment schedules ahead of subcutaneous formulation entrants. For New Entrants and Emerging Players: Teledermatology-enabled rural patient enrollment gaps offer white-space access where incumbent hub-and-spoke models under-serve community dermatology practices. ANVISA's simplified rare disease registration framework provides the most penetrable regulatory entry point for biosimilar rituximab manufacturers targeting São Paulo-Rio ophthalmology networks, with direct-to-patient logistics partnerships as the critical go-to-market angle. For Investors and Strategic Acquirers: EMA PRIME designation reshapes the acquisition landscape by compressing time-to-revenue for novel B-cell modulators, favoring mid-cap developers with biomarker-guided protocol data. Target acquisition archetypes include subcutaneous formulation specialists and teledermatology platform operators, with the signal to watch being CD19+ monitoring protocol adoption rates across German university hospital networks as inflection indicator for personalized retreatment scheduling viability.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Self-administered B-cell modulators would displace infusion center dependence and expand community access. |
| Specialty Pharmacy Partnership | Exclusive distribution agreements with hub-and-spoke operators block biosimilar sampling and capture prior authorization workflows. |
| Biomarker Protocol Sponsorship | CD19+ monitoring standardization in German and United States academic centers entrenches retreatment scheduling preferences. |
| Biosimilar Regulatory Pathway | ANVISA and EMA simplifications accelerate Latin American and European market entry for rituximab alternatives. |
| Teledermatology Platform Integration | Remote mucosal monitoring enables rural patient enrollment previously limited to metropolitan academic centers. |
Research Methodology
A standing panel of dermatology-ophthalmology multidisciplinary unit directors, specialty pharmacy operations executives, payer formulary directors, and regulatory affairs leads provided ongoing calibration across primary interviews, validated against FDA orphan drug designation databases, EMA PRIME submission records, ClinicalTrials.gov protocol filings, and ANVISA rare disease registration frameworks, with bottom-up prescription volume modeling and top-down manufacturer revenue triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product type, administration route, end user channel, and treatment frequency tiers. CAGRs were derived from patient population epidemiology, diagnosis rate trends, and biologic penetration assumptions, incorporating infusion center capacity constraints and prior authorization approval velocity as disease-specific forecast inputs.
Forecasts assume regulatory continuity in FDA orphan drug exclusivity and EMA PRIME designation regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as biosimilar interchangeability guidance and subcutaneous formulation approval timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Buruli Ulcer Treatment Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Monoclonal Antibody Therapy Market