
 Cystic Fibrosis Market | 2026-2036
Cystic Fibrosis Market Size, Share, and Industry Trends Forecast 2026-2036
Cystic Fibrosis Market Analysis
The cystic fibrosis therapeutics landscape is rebalancing between premium CFTR modulator portfolios and commodity antibiotic maintenance segments. Vertex Pharmaceuticals dominates the high-value modulator tier with its sustained R&D intensity in triple-combination therapies. AbbVie competes through its anchored position in anti-inflammatory and combination protocols for residual function mutations.
Cystic fibrosis constitutes a genetic disorder caused by CFTR gene mutations producing defective chloride ion transport, resulting in thick mucus accumulation across pulmonary, pancreatic, and hepatobiliary systems; therapeutics target ion channel restoration, mucus clearance, and infection control through specialized formulations requiring precise stability profiles and bioavailability engineering. Oral therapies command the largest revenue pool due to patient adherence advantages and pharmacy benefit structures, while inhaled medicines represent the fastest-expanding delivery category driven by nebulizer technology advances and lung-targeted deposition science. The intravenous segment retains critical share for acute pulmonary exacerbation management in hospital settings.
The FDA maintains stringent chemistry-manufacturing-controls standards for CFTR modulators, while the EMA's orphan drug framework shapes European access timelines and pricing negotiations for novel entrants. Health Canada and the TGA enforce comparable clinical evidence thresholds that filter which manufacturers achieve reimbursed market entry across North America and Oceania. Stakeholders must monitor evolving payer evidence requirements for combination therapy value demonstration as gene-editing platforms advance toward registrational studies.
Market Dynamics
The cystic fibrosis therapeutics sector is rebalancing around gene-editing platforms that promise functional cures, forcing incumbent modulator manufacturers to defend high-margin portfolios against potentially curative alternatives entering registrational studies.
Growth Catalysts
- Orphan drug incentives:The FDA's breakthrough therapy designation compresses development timelines for novel CFTR correctors, accelerating patient access to next-generation triple combinations.
- Neonatal screening expansion:State-level mandated newborn testing in the United States identifies patients before pulmonary damage accumulates, expanding the addressable treated population for early intervention protocols.
- Inhaled formulation advances:Lipid nanoparticle delivery systems improve lung deposition efficiency, enabling once-daily dosing that reduces treatment burden and improves adherence metrics.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthetic CFTR modulator precursors rely on contract manufacturing organizations clustered in Switzerland and Singapore, creating single-source vulnerability for critical intermediates.
- Reimbursement complexity:Pharmacy benefit managers in the United States impose step-therapy requirements that delay access to combination regimens until generic antibiotic failures are documented.
- Mutation-specific efficacy ceilings:Approximately ten percent of patients carry rare CFTR variants that respond poorly to existing potentiators, limiting addressable market expansion for current portfolios.
Strategic Opportunities
- Sub-Saharan Africa diagnosis infrastructure:Underdeveloped genetic testing capacity in Nigeria and South Africa conceals a significant undiagnosed patient pool that mobile screening units could unlock.
- Antisense oligonucleotide convergence:Combining mRNA repair technologies with existing modulator frameworks offers a pathway to treat nonsense mutations currently unaddressable by small-molecule approaches.
- Specialty pharmacy direct distribution:Bypassing wholesale intermediaries to ship temperature-controlled biologics directly to patients reduces cold-chain failure risk and captures margin previously lost to channel partners.
Industry Challenges
- Gene therapy manufacturing scale-up:Viral vector production capacity constraints limit batch sizes for CRISPR-based candidates, forcing sponsors to reserve manufacturing slots years ahead of anticipated approval dates.
- Real-world evidence collection:Payer demands for long-term pulmonary function data require expensive post-marketing surveillance infrastructure that strains mid-cap developer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystic Fibrosis Market |
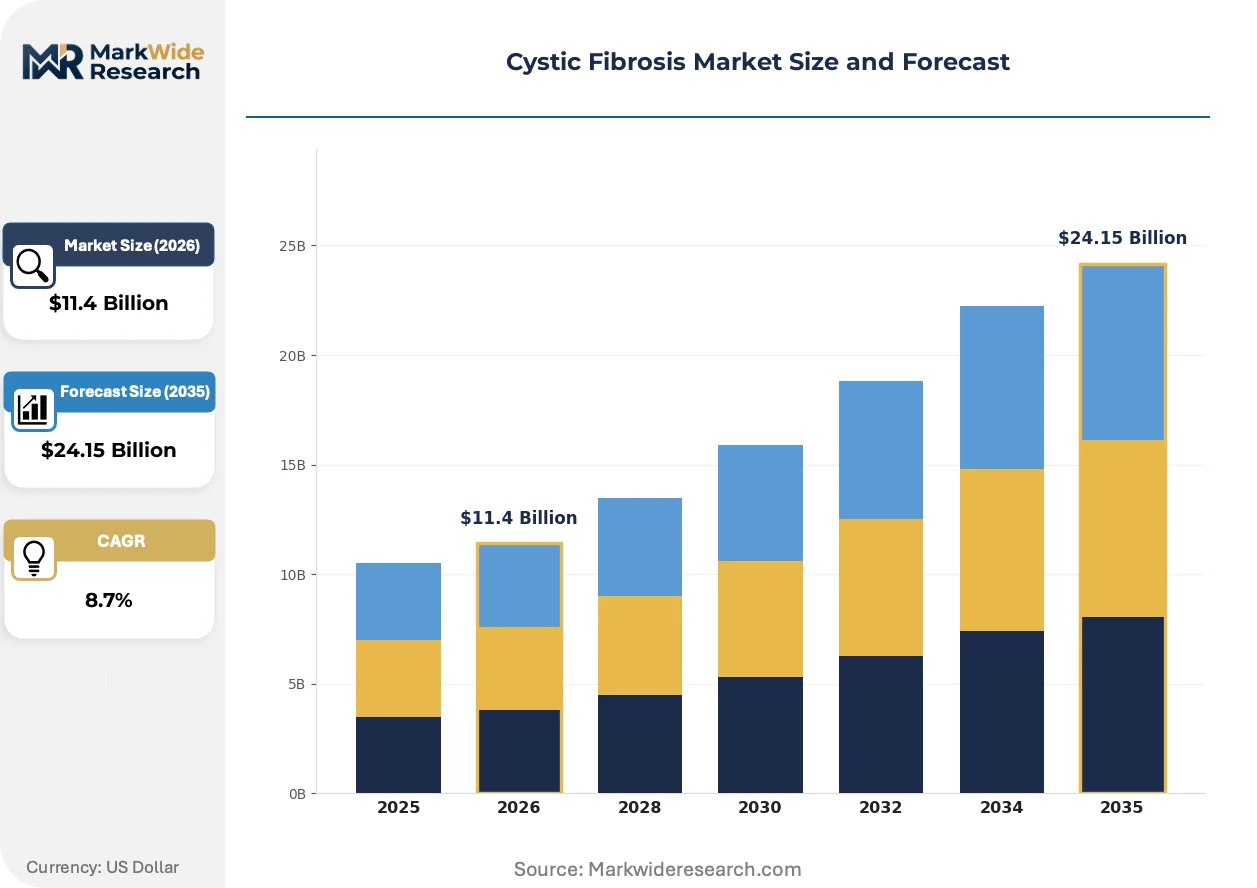
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Therapies, Antibiotics, Mucolytics, Inhaled Medicines Delivery Mode: Intravenous, Inhalation, Oral, Nebulization End User: Hospitals, Specialty Clinics, Home Care, Research Institutions Indication: Chronic Lung Infection, Nutrition Deficiencies, Sinusitis, Pulmonary Exacerbation |
| Companies Covered | Vertex Pharmaceuticals, AbbVie, Novartis AG, Gilead Sciences, F. Hoffmann-La Roche Ltd, Teva Pharmaceutical Industries, Sanofi, AstraZeneca, Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystic Fibrosis Market Emerging Trajectories
Biological engineering is compressing development timelines for cystic fibrosis interventions while regulatory frameworks adapt to evaluate one-time curative therapies against chronic maintenance standards.
mRNA-based CFTR replacement therapies are electrifying preclinical pipelines by enabling transient but repeated expression of functional ion channels without permanent genomic alteration. Academic medical centers in Boston and San Diego are establishing dedicated manufacturing suites for lipid nanoparticle encapsulation. This platform is compressing the traditional small-molecule development cycle from twelve years toward six, forcing portfolio managers to accelerate internal gene therapy investments.
The EMA's adaptive pathway framework now permits rolling review of gene-editing candidates based on surrogate biomarker endpoints rather than forced expiratory volume alone. European sponsors can submit modular applications as Phase I/II data mature, reducing regulatory lag between readout and market access. This mechanism particularly benefits developers of base-editing platforms targeting the most prevalent delta-F508 mutation across Germany, France, and the United Kingdom.
Hospital procurement committees are consolidating antibiotic purchasing for pulmonary exacerbations into multi-year sole-source agreements that bundle nebulized therapies with laboratory monitoring services. This displaces traditional multi-vendor antibiotic rotation protocols with integrated stewardship contracts. The shift is most visible in United States academic medical centers where infection control departments now control formulary decisions previously managed by pharmacy directors.
Cystic Fibrosis Market Segmentation
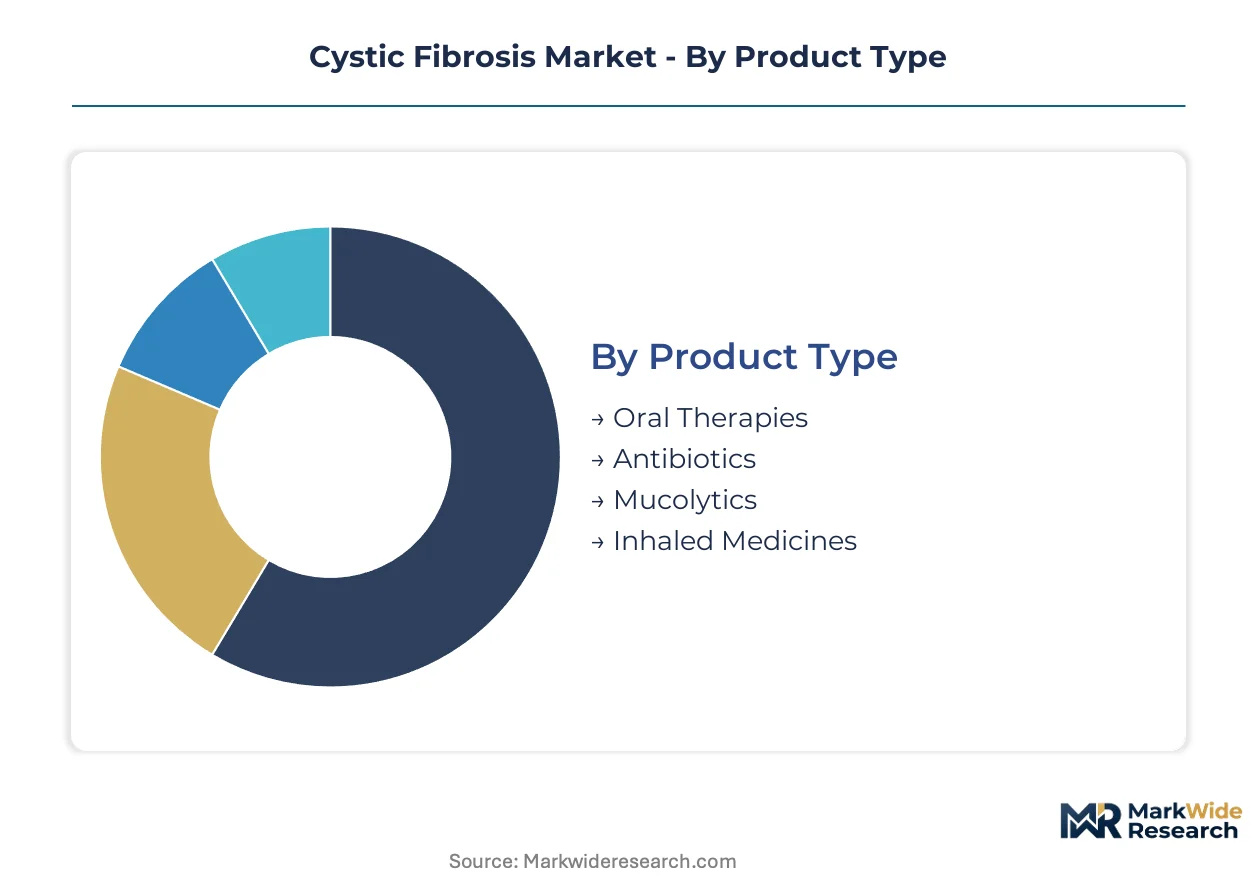
Cystic fibrosis therapeutics fragment across molecular mechanisms, anatomical targets, and care settings. Segmentation reveals where pricing power concentrates and which delivery innovations reshape adherence economics.
Product Type:
Customization intensity varies sharply across this category, from patient-specific mutation-matched modulators to standardized antibiotic protocols.
- Oral Therapies:CFTR modulators in tablet and capsule forms dominate revenue due to pharmacy benefit structures favoring self-administered chronic regimens. Demand concentrates in United States specialty pharmacies where prior authorization workflows favor oral maintenance over hospital-based alternatives.
- Inhaled Medicines:Lipid nanoparticle and dry powder formulations achieve direct lung deposition with reduced systemic exposure. Nebulized tobramycin and hypertonic saline drive fastest category expansion in Germany and United Kingdom where home nebulizer penetration exceeds North American benchmarks.
- Antibiotics:Chronic suppressive and acute exacerbation protocols target Pseudomonas aeruginosa and Staphylococcus aureus colonization patterns.
- Mucolytics:Dornase alfa and hypertonic saline agents reduce sputum viscosity through enzymatic and osmotic mechanisms.
Most installed capacity flows through Oral Therapies. Expansion is steepest in Inhaled Medicines.
Delivery Mode:
Cost tier separation distinguishes hospital-administered acute interventions from patient-managed chronic maintenance.
- Inhalation:Dry powder inhalers and metered-dose systems deliver bronchodilators and corticosteroids with portable convenience. Pediatric adoption in France and Italy outpaces adult markets due to school-based nursing support infrastructure.
- Intravenous:Aminoglycoside and beta-lactam infusions manage refractory pulmonary exacerbations requiring inpatient monitoring. Tertiary centers in Boston and London maintain dedicated CF infusion suites that reduce emergency department utilization.
- Oral:Small-molecule absorption profiles vary by pancreatic enzyme supplementation status, complicating bioavailability prediction.
- Nebulization:Compressor-driven and vibrating mesh devices generate respirable particle fractions for mucolytic and antibiotic deposition.
Hospital procurement favors Intravenous bundling. Home care migration accelerates Inhalation and Nebulization fastest.
End User:
Application maturity separates established hospital protocols from emerging home infusion and telemedicine models.
- Specialty Clinics:Accredited CF centers coordinate multidisciplinary care across pulmonology, nutrition, and endocrinology. United States Cystic Fibrosis Foundation-accredited programs in Chicago and San Diego capture highest per-patient revenue through integrated modulator dispensing.
- Home Care:Nursing services administer IV antibiotics and monitor spirometry remotely. Expansion in Ontario and Victoria follows reimbursement code expansions for home infusion therapy.
- Hospitals:Acute exacerbation management and surgical interventions for pneumothorax or hemoptysis.
- Research Institutions:Gene therapy trials and natural history registries drive protocol development.
Patient volume concentrates in Specialty Clinics. Capacity addition runs fastest through Home Care networks.
Indication:
Volume distribution across this category reflects disease progression staging from early nutritional deficit through end-stage pulmonary failure.
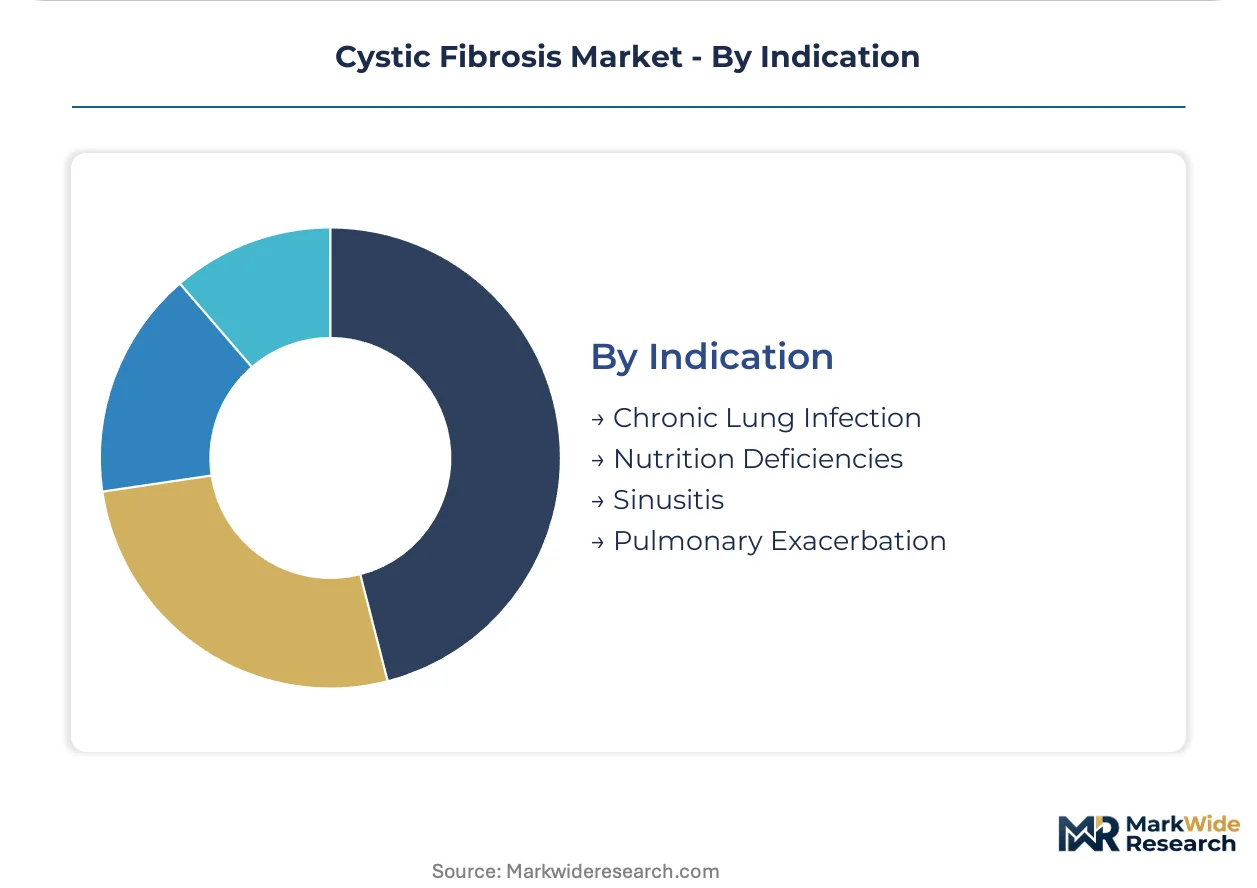
- Chronic Lung Infection:Persistent bacterial colonization drives maintenance antibiotic and anti-inflammatory prescribing. Pseudomonas eradication protocols in Denmark and Netherlands achieve lower chronic infection prevalence through aggressive early treatment.
- Pulmonary Exacerbation:Acute FEV1 decline events trigger IV antibiotic escalation and hospitalization. Exacerbation frequency in United States Medicaid populations exceeds commercially insured cohorts by substantial margins.
- Nutrition Deficiencies:Pancreatic insufficiency and malabsorption require enzyme replacement and fat-soluble vitamin supplementation.
- Sinusitis:Nasal polyposis and chronic rhinosinusitis precede lower respiratory involvement in many patients.
Therapeutic investment concentrates on Chronic Lung Infection. Unmet need expands most rapidly in Pulmonary Exacerbation prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized CF care centers concentrate clinical expertise and patient volumes in specific metropolitan clusters, with reimbursement density and regulatory pathways determining where novel therapies achieve commercial traction first.
United States
The Cystic Fibrosis Foundation accredits over 130 care centers that coordinate modulator dispensing with nutritional and pulmonary support. FDA breakthrough therapy designations compress review timelines for triple-combination candidates. Boston and San Diego host the densest concentrations of gene therapy trial infrastructure.
Germany
EMA centralized procedures enable rapid adoption of novel CFTR modulators across statutory health insurance funds. Bavaria and North Rhine-Westphalia maintain dedicated CF centers with integrated home infusion programs. German payers demand robust pharmacoeconomic evidence for combination therapy reimbursement.
United Kingdom
NICE technology appraisals set access thresholds for high-cost modulators through confidential discount arrangements. London and Manchester anchor the NHS specialist commissioning network for rare diseases. Post-Brexit MHRA reliance procedures now run parallel to EMA reviews for CF candidates.
France
ANSM expedited pathways align with EMA adaptive frameworks for gene-editing therapies entering rolling review. Île-de-France and Auvergne-Rhône-Alpes concentrate the national CF patient registry and natural history data collection. French hospital pharmacists control formulary placement through therapeutic committee voting.
Australia
TGA priority review vouchers accelerate orphan drug assessment for residual function mutations. New South Wales and Victoria operate state-based newborn screening programs with near-universal coverage. Australian reimbursement requires demonstrated FEV1 improvement against standard of care benchmarks.
Cystic Fibrosis Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the CF therapeutics sector, with integrated biopharmaceutical manufacturers maintaining manufacturing scale advantages over development-stage gene therapy specialists. The market structure concentrates revenue generation among three to four established modulator developers while fragmenting antibiotic maintenance supply across generic manufacturers. Strategic archetypes include mutation-specific portfolio builders, infection control specialists, and platform technology licensors. Competitive dynamics center on combination regimen patent estates and manufacturing capacity reservations for viral vector production.
Within the integrated biopharmaceutical tier, Vertex Pharmaceuticals and AbbVie occupy positions defined by CFTR modulator depth versus anti-inflammatory breadth. Novartis AG exemplifies the diversified portfolio approach spanning inhaled antibiotics and diagnostic platforms. These anchors represent contrasting R&D intensity models—targeted rare disease focus against broad respiratory franchise integration—while competing for specialty pharmacy distribution relationships and payer value demonstration contracts.
| Leading Market Players |
|---|
| Vertex Pharmaceuticals |
| AbbVie |
| Novartis AG |
| Gilead Sciences |
| F. Hoffmann-La Roche Ltd |
| Teva Pharmaceutical Industries |
| Sanofi |
| AstraZeneca |
| Viatris |
| Others |
Supply Flow & Price Mechanics
Specialty pharmacy benefit managers in the United States anchor purchasing concentration for CFTR modulators, imposing value-based contracting that bundles drug reimbursement with adherence monitoring and clinical outcome guarantees. This buyer archetype concentration forces manufacturers toward outcomes-linked pricing models rather than traditional per-pill transactional structures.
Pricing Analysis
Bundled service contracts dominate high-value CFTR modulator tiers, while unbundled antibiotic maintenance protocols compete on commodity spot dynamics. Price differentiation hinges on mutation-specific efficacy certification and integrated care program inclusion, with rare variant coverage commanding substantial premiums. Cost compression in generic antibiotic segments intensifies as hospital procurement committees consolidate to sole-source agreements. Medicaid populations exhibit highest price sensitivity due to prior authorization burden, while commercially insured patients through specialty pharmacies show lowest sensitivity to out-of-pocket costs.
Supply Chain Analysis
Specialized biochemistry PhD concentrations in Basel and Singapore determine synthetic precursor manufacturing capacity for CFTR modulator active pharmaceutical ingredients. Contract manufacturing organizations in Switzerland, Singapore, and Ireland produce critical chloride channel corrector intermediates that feed formulation facilities in the United States and Germany. Single-source vulnerability pervades lipid nanoparticle lipid component supply, with tariff exposure on Swiss specialty chemicals creating downstream cost pressure. Distribution runs through temperature-controlled specialty pharmacy networks that bypass wholesale intermediaries for direct-to-patient cold-chain delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States reimbursement density and European manufacturing cost bases defines viable expansion economics, with FDA breakthrough therapy designation timelines offering faster returns than EMA centralized procedures despite higher clinical trial investment requirements.
For Market Incumbents: Hedge gene-editing platform displacement risk by reserving viral vector manufacturing slots and accelerating internal mRNA therapy investments before CRISPR-based candidates reach registrational studies. Secure backward integration into lipid nanoparticle component supply to reduce single-source exposure on Swiss specialty chemical imports. Deepen relationships with United States Cystic Fibrosis Foundation-accredited centers through integrated adherence monitoring contracts that lock in formulary placement against emerging triple-combination competitors. For New Entrants and Emerging Players: Antisense oligonucleotide convergence technologies targeting nonsense mutations offer the most penetrable white-space entry, as approximately ten percent of patients carry variants unaddressable by existing Vertex Pharmaceuticals potentiators. Sub-Saharan Africa mobile screening infrastructure represents the least contested geography, with Nigeria and South Africa concealing substantial undiagnosed populations absent genetic testing capacity. Pursue specialty pharmacy direct distribution partnerships that bypass wholesale intermediaries and capture margin through temperature-controlled logistics capabilities. For Investors and Strategic Acquirers: Large-cap biopharmaceuticals seeking rare disease portfolio expansion are the most active acquirer in this space, with gene therapy platform specialists commanding premium valuations against traditional small-molecule developers. Acquisition targets should display registrational-stage gene-editing assets with delta-F508 mutation addressing capability and reserved manufacturing capacity. Monitor EMA adaptive pathway rolling review acceptances as the critical inflection signal for European market access velocity and corresponding valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Viral vector production reservations at CDMOs in Massachusetts and North Carolina secure batch capacity years ahead of anticipated FDA approval dates. |
| Specialty Pharmacy Direct Distribution | Bypassing wholesale intermediaries reduces cold-chain failure risk and captures margin previously lost to channel partners in United States markets. |
| mRNA Platform Pipeline Expansion | Transient CFTR expression without genomic alteration compresses development timelines from traditional twelve-year small-molecule cycles toward six-year horizons. |
| Antisense Oligonucleotide Development | Nonsense mutation addressing creates addressable market expansion into the ten percent of patients with variants unresponsive to existing potentiators. |
| Sub-Saharan Africa Screening Infrastructure | Mobile genetic testing units in Nigeria and South Africa unlock concealed patient pools absent newborn screening mandate coverage. |
Methodological Framework
Direct dialogue with drug development executives, regulatory affairs leads at EMA and FDA, formulary directors at United States pharmacy benefit managers, and hospital procurement managers at Cystic Fibrosis Foundation-accredited centers grounded qualitative assessment. Secondary validation drew from FDA breakthrough therapy designation filings, EMA centralized procedure submissions, ClinicalTrials.gov gene therapy protocol registrations, and United States Cystic Fibrosis Foundation patient registry data. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-validated market sizing across the analysis window.
Segmented projections across oral therapies, inhaled medicines, intravenous formulations, and nebulization delivery modes integrated mutation-specific addressable population estimates with reimbursement density indices by country. CAGRs derived from patient cohort growth, neonatal screening expansion trajectories, and therapy penetration curves by disease severity stage. Forecast inputs incorporated pharmacy benefit manager prior authorization trend data and specialty pharmacy dispensing volume patterns without specifying annual figures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene-editing platform clinical readouts and CRISPR regulatory acceptance thresholds. Practitioners should monitor EMA adaptive pathway rolling review decisions and United States gene therapy manufacturing capacity reservation announcements for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Atrial Septal Defect Market