
 Chronic Smell and Flavor Loss Treatment Market | 2026-2036
Chronic Smell and Flavor Loss Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Smell and Flavor Loss Treatment Market Outlook
Aftermarket service revenue from patient monitoring and adherence programs is reshaping how chronic smell and flavor loss therapies capture lifetime value. Regeneron Pharmaceuticals leverages its biologics infrastructure to sustain R&D intensity in olfactory receptor pathways. Cyrano Therapeutics anchors its position through specialized intranasal delivery platforms. Novartis AG competes by extending its neurology franchise into chemosensory disorder indications.
Chronic smell and flavor loss treatment encompasses pharmacological and non-pharmacological interventions targeting persistent olfactory and gustatory dysfunction, typically administered via intranasal corticosteroid suspensions with particle sizes below 10 microns to optimize olfactory cleft deposition. These therapies restore chemosensory function for patients suffering from post-viral damage, traumatic brain injury, or neurodegenerative progression, thereby improving nutritional intake, safety awareness, and quality of life. Oral medications dominate current prescription volumes due to established payer familiarity and pharmacy distribution reach, while intranasal delivery commands premium positioning through direct-to-site pharmacokinetics. Supplements represent the fastest-growing product category as consumers self-direct toward zinc, vitamin A, and omega-3 formulations before seeking clinical intervention. Homecare settings are capturing expanding margin pools as telehealth protocols enable remote olfactory training and treatment adjustment.
The FDA maintains stringent requirements for olfactory endpoint validation in clinical trials, while the EMA's MDR framework governs device-based delivery systems across European markets. Japan's PMDA has accelerated review pathways for post-COVID chemosensory therapeutics, creating differentiated market access timelines. Stakeholders must monitor evolving biomarker standards for objective smell loss quantification and calibrate portfolio investments against regulatory jurisdiction-specific evidentiary thresholds.
Market Dynamics
The FDA's expanded guidance on olfactory dysfunction therapeutics is compressing clinical trial timelines while forcing sponsors to adopt objective biomarker endpoints, fundamentally restructuring how chemosensory drug development captures regulatory value.
Growth Catalysts
- Post-viral syndrome protocols:Hospital systems are standardizing smell disorder management pathways, creating institutional demand pull for reimbursable therapeutic interventions.
- PMDA accelerated review:Japan's streamlined pathways for post-COVID chemosensory therapeutics are shortening market access timelines relative to Western jurisdictions.
- Intranasal deposition technology:Particle engineering below 10 microns is improving olfactory cleft targeting and expanding addressable patient populations.
Market Restraints
- EMA MDR compliance costs:Device-based delivery systems face elevated certification burdens across European markets, raising fixed cost thresholds for market entry.
- Specialist ENT concentration:Treatment administration concentrates in academic medical centers and specialized clinics, limiting geographic accessibility.
- Zinc supplementation substitution:Consumer self-direction toward over-the-counter mineral formulations delays clinical intervention and compresses addressable prescription volumes.
Strategic Opportunities
- Telehealth-enabled homecare:Remote olfactory training protocols are expanding margin pools beyond traditional clinic-based administration.
- Neurology franchise extension:Chelation of smell disorder indications into existing neurodegenerative therapeutic portfolios creates cross-selling infrastructure.
- Objective quantification standards:Evolving biomarker frameworks for smell loss measurement are opening regulatory differentiation pathways for validated diagnostic-therapeutic bundles.
Industry Challenges
- Olfactory endpoint validation expertise:FDA stringent requirements for chemosensory clinical trial design are creating talent scarcity in specialized biostatistics and sensory science functions.
- Cross-jurisdictional evidentiary calibration:Divergent regulatory thresholds between FDA, EMA, and PMDA are forcing redundant study designs and inflating development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Smell and Flavor Loss Treatment Market |
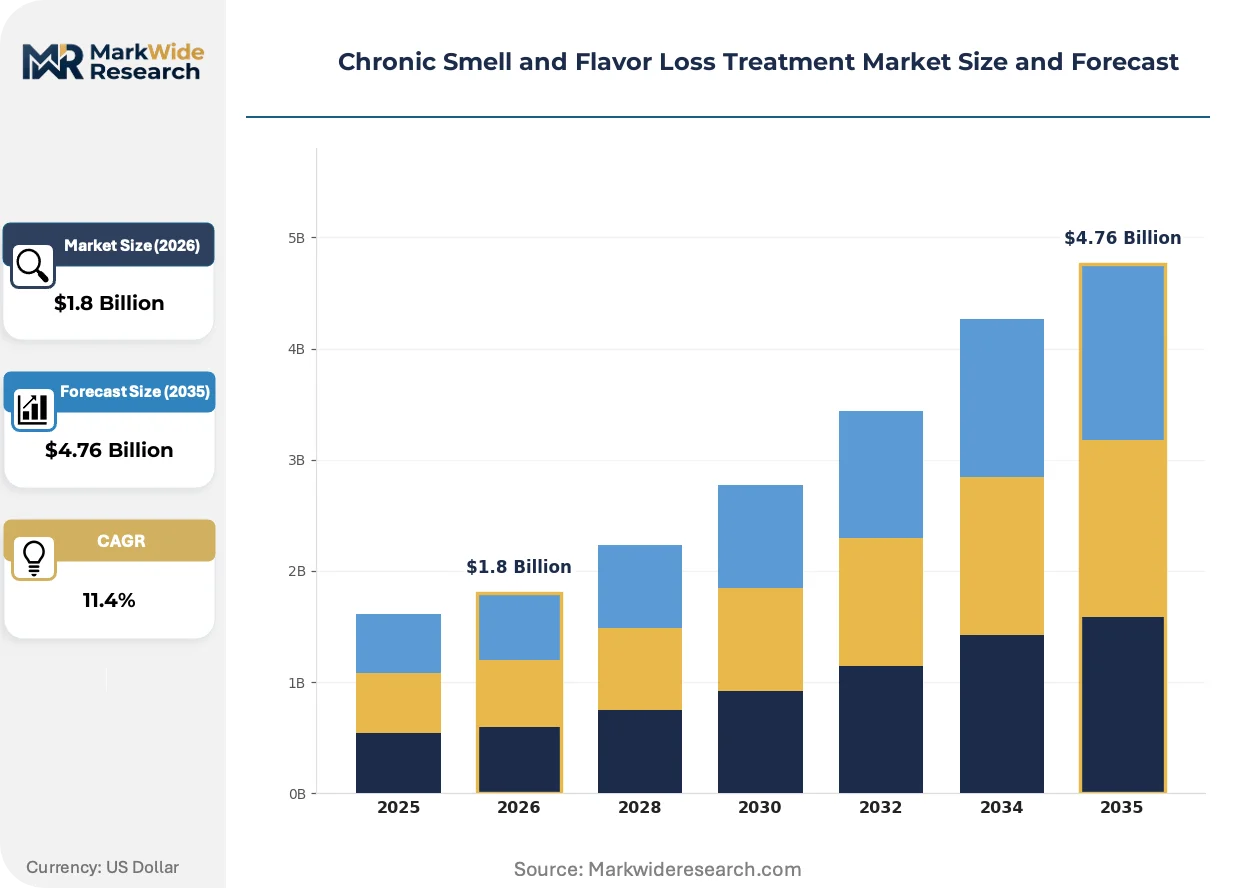
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasal Sprays, Supplements, Topical Treatments, Oral Medications Delivery Mode: Intranasal, Oral, Topical, Injectable End User: Clinics, Hospitals, Homecare, Specialty Centers Application: Post-Viral Syndromes, Neurological Disorders, Inflammatory Conditions, Aging |
| Companies Covered | Regeneron Pharmaceuticals, Novartis AG, GlaxoSmithKline plc, Cyrano Therapeutics, Pfizer Inc., Sanofi S.A., Otsuka Pharmaceutical Co., Ltd., Bayer AG, AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Smell and Flavor Loss Treatment Market Strategic Shifts
Digital olfactory training platforms and objective smell assessment technologies are converging to displace subjective patient-reported outcomes, compressing the feedback loop between therapeutic intervention and measurable functional restoration.
High-resolution olfactory cleft imaging combined with machine learning-based pattern recognition is rendering obsolete traditional paper-and-pencil smell identification tests in academic medical centers. ENT specialists and neurology departments are adopting these platforms at accelerating cadence. The technology is rendering obsolete decades-old subjective assessment methodologies that previously dominated chemosensory diagnosis.
REACH substance restrictions on certain intranasal excipients are forcing reformulation of established corticosteroid suspensions across European markets. Manufacturers are pivoting toward alternative delivery vehicles and cleaner excipient profiles. Device-based delivery systems face the steepest compliance recalibration as they fall under concurrent MDR governance.
Patient self-advocacy through direct-to-consumer genetic testing is compressing the diagnostic pathway for hereditary smell disorders. Individuals are presenting to specialized clinics with pre-validated genetic markers, bypassing traditional referral delays. This behavioral shift concentrates in the United States where direct-access testing frameworks are most permissive.
Chronic Smell and Flavor Loss Treatment Market Segmentation
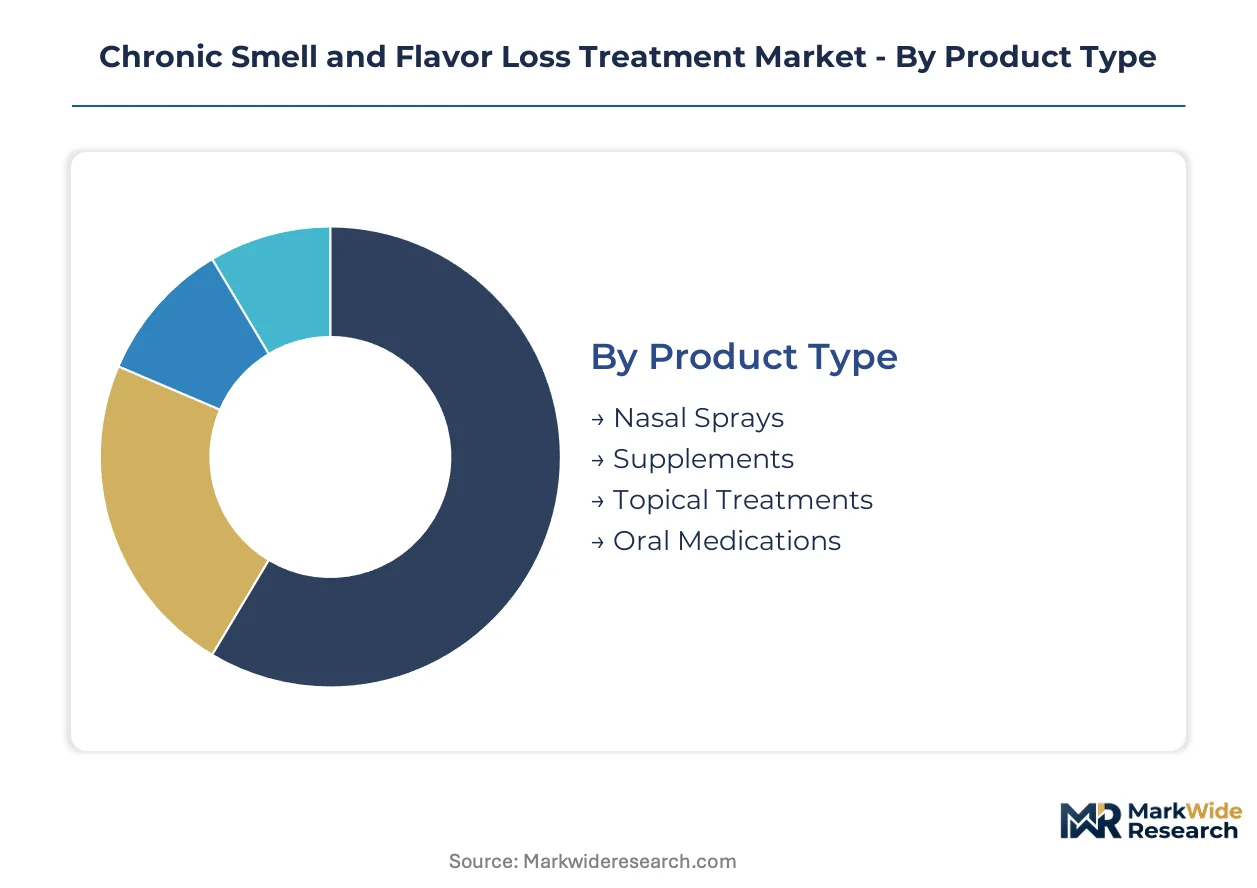
Segmentation in the Chronic Smell and Flavor Loss Treatment Market reveals divergent margin structures across administration settings and therapeutic modalities. Product lifecycle velocity varies sharply between consumer-directed supplements and clinic-administered intranasal formulations.
Product Type:
Nasal sprays and oral medications turn inventory fastest through established pharmacy channels, while supplements and topical treatments exhibit slower velocity tied to consumer education cycles.
- Nasal Sprays:Intranasal corticosteroid suspensions with sub-10-micron particle engineering target the olfactory cleft directly. ENT clinics in the United States concentrate demand for prescription-grade formulations as institutional protocols standardize post-viral syndrome management.
- Supplements:Zinc, vitamin A, and omega-3 formulations dominate over-the-counter self-directed purchasing. Consumer bypass of clinical channels in North American markets compresses prescription capture rates while expanding total addressable population reach.
- Topical Treatments:Dermal absorption formulations for gustatory nerve stimulation occupy niche positioning.
- Oral Medications:Systemic agents with established payer coding sustain volume leadership through pharmacy benefit coverage.
Oral medications dominate installed base. Supplements are where expansion concentrates.
Delivery Mode:
Cost stratification separates premium device-assisted intranasal delivery from commodity oral administration, with injectable and topical modalities occupying intermediate tiers.
- Intranasal:Direct-to-site pharmacokinetics command premium reimbursement through specialized deposition technology. Academic medical centers in Japan leverage PMDA accelerated pathways to compress access timelines for post-COVID chemosensory therapeutics.
- Oral:Tablet and capsule formulations benefit from universal pharmacy distribution infrastructure. Payer familiarity with systemic neurology drugs sustains prescription volume leadership across United States commercial and Medicare formularies.
- Topical:Transdermal and mucosal applications serve adjuvant therapy positioning.
- Injectable:Parenteral biologics target refractory cases with elevated safety monitoring requirements.
Oral delivery sustains volume leadership. Intranasal platforms capture margin expansion.
End User:
Patient acuity and reimbursement intensity separate acute hospital encounters from longitudinal homecare relationships, with specialty centers occupying the highest-margin diagnostic-therapeutic bundling position.
- Hospitals:Inpatient smell disorder protocols for traumatic brain injury and post-viral damage drive institutional procurement. Standardized pathway adoption in United States health systems creates demand pull for reimbursable therapeutic bundles.
- Homecare:Telehealth-enabled remote olfactory training expands margin pools beyond clinic walls. Remote monitoring infrastructure in Germany and the United Kingdom supports adherence program revenue capture.
- Clinics:Community ENT practices handle initial diagnostic workup and maintenance therapy.
- Specialty Centers:Dedicated chemosensory programs concentrate objective quantification technology and research access.
Hospitals anchor institutional revenue. Homecare represents the steepest expansion trajectory.
Application:
Disease prevalence and therapeutic maturity stratify segments, with post-viral syndromes commanding immediate commercial attention while aging-related decline builds longitudinal pipeline value.
- Post-Viral Syndromes:SARS-CoV-2 sequelae and other viral etiologies concentrate near-term development investment. FDA expanded guidance on olfactory dysfunction endpoints is compressing trial timelines for sponsors targeting this indication.
- Neurological Disorders:Parkinson's and Alzheimer's disease progression drives neurology franchise extension strategies. Novartis AG and peer neurology specialists leverage existing prescriber relationships to cross-sell chemosensory indications.
- Inflammatory Conditions:Chronic rhinosinusitis and allergic etiologies overlap with established ENT therapeutic paradigms.
- Aging:Presbyosmia and related degenerative decline build addressable population through demographic shift.
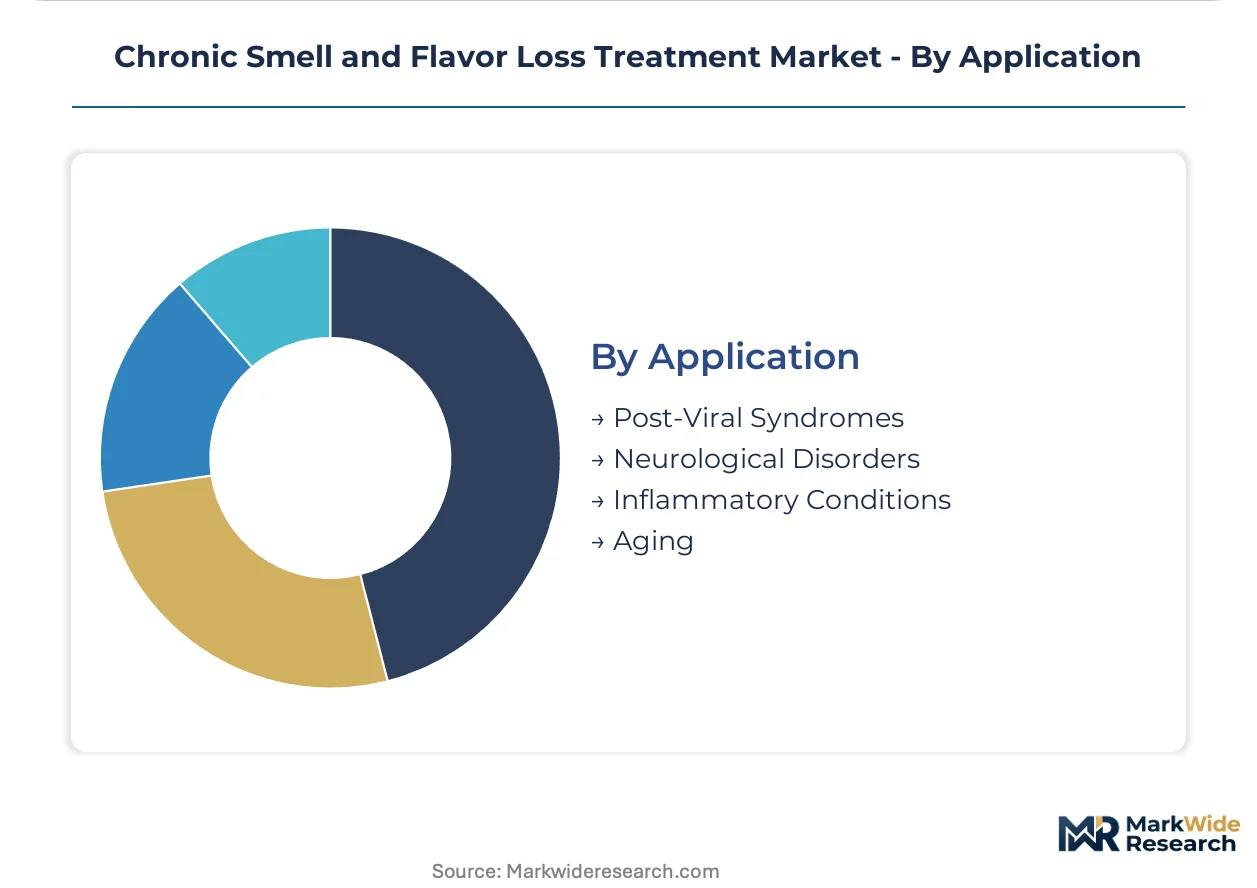
Post-viral syndromes dominate near-term development. Neurological disorders concentrate franchise extension investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity as academic medical centers prioritize clinical efficacy over acquisition cost, while German and Japanese purchasers exhibit moderate sensitivity tied to statutory reimbursement frameworks. Emerging demand in India and Brazil concentrates in self-directed supplement channels where over-the-counter price points dominate purchasing decisions.
United States
Specialized ENT clinics and dedicated smell disorder programs at Johns Hopkins, Stanford, and Mayo Clinic drive institutional procurement of intranasal deposition technologies. FDA expanded guidance on olfactory dysfunction endpoints compresses clinical trial timelines for sponsors targeting post-viral indications. The Boston-Cambridge biotech corridor anchors regenerative medicine R&D for chemosensory therapeutics.
Germany
Telehealth-enabled remote olfactory training expands margin pools beyond traditional clinic walls as statutory insurers pilot adherence program reimbursement. EMA MDR compliance costs elevate certification burdens for device-based delivery systems entering European markets. The Rhine-Ruhr metropolitan region concentrates medical device engineering talent for next-generation intranasal platforms.
Japan
PMDA accelerated review pathways for post-COVID chemosensory therapeutics shorten market access timelines relative to Western jurisdictions. METI funding for digital health infrastructure supports adoption of machine learning-based smell assessment technologies. The Kansai region around Osaka anchors pharmaceutical manufacturing partnerships for olfactory receptor pathway biologics.
India
Consumer self-direction toward zinc, vitamin A, and omega-3 formulations dominates addressable population reach before clinical intervention. CDSCO regulatory pathways for novel intranasal suspensions remain underdeveloped compared to mature markets. Mumbai and Bangalore concentrate direct-to-consumer supplement distribution networks serving price-sensitive households.
Brazil
Post-viral syndrome management protocols lag North American and European standardization, delaying institutional demand pull for reimbursable therapeutic bundles. ANVISA review timelines for device-based chemosensory therapeutics extend market entry horizons for multinational sponsors. São Paulo's private hospital networks pilot smell disorder screening programs for traumatic brain injury patients.
Chronic Smell and Flavor Loss Treatment Market Competitive Environment
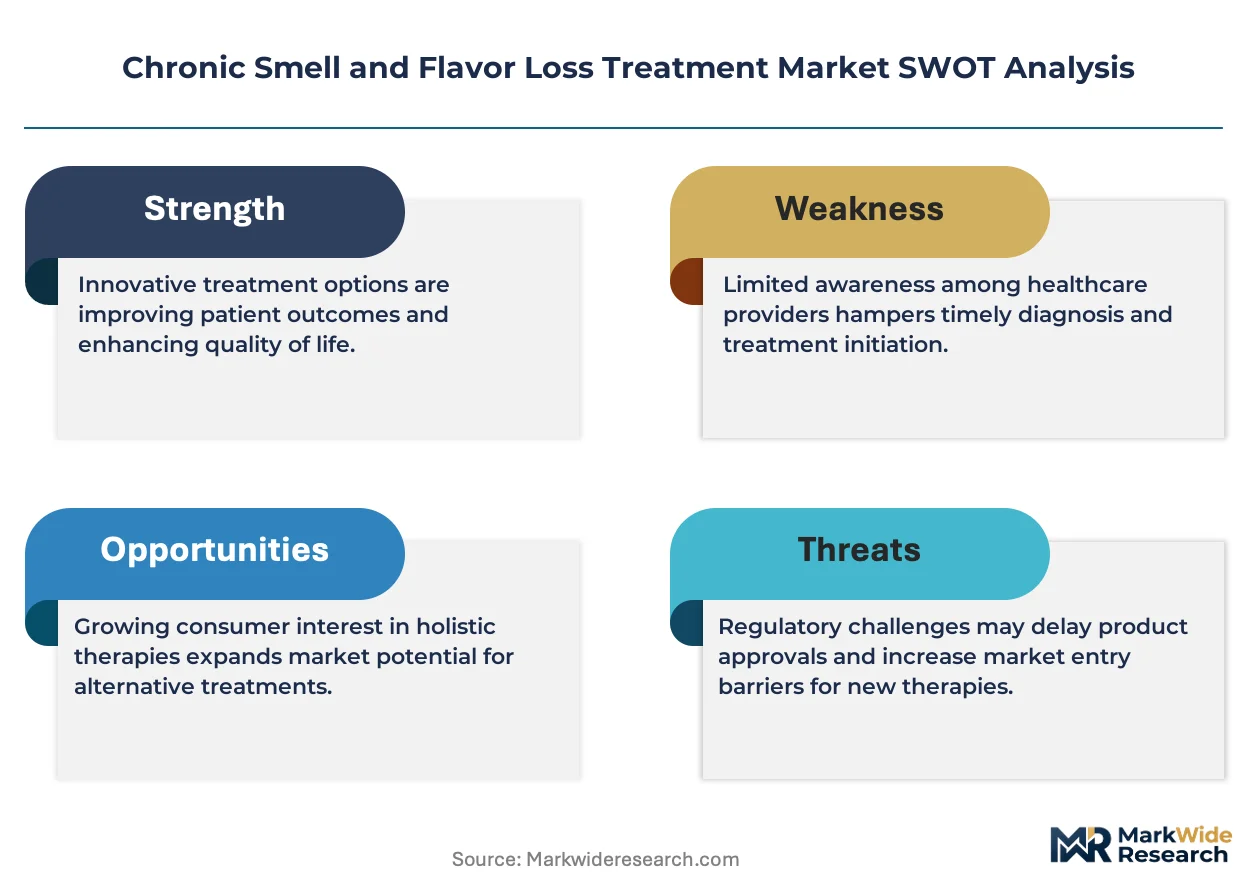
Biologics specialists and diversified neurology incumbents split the market between precision receptor-targeting platforms and franchise extension strategies. The competitive structure concentrates around three archetypes: intranasal delivery technology developers, systemic neurology drug manufacturers, and regenerative medicine biotechs. Consolidation pressures favor entities with captive biologics infrastructure or established prescriber relationships in adjacent neurodegenerative indications. Dominant competitive moves include neurology franchise extension into chemosensory disorders and strategic partnerships for objective biomarker validation.
Within the biologics infrastructure tier, Regeneron Pharmaceuticals and Novartis AG exemplify contrasting strategic postures—Tarrytown-based Regeneron anchors its position through sustained R&D intensity in olfactory receptor pathways, while Swiss-domiciled Novartis leverages existing prescriber networks to cross-sell chemosensory indications. Cyrano Therapeutics occupies a specialized position among intranasal delivery platform developers.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| Novartis AG |
| GlaxoSmithKline plc |
| Cyrano Therapeutics |
| Pfizer Inc. |
| Sanofi S.A. |
| Otsuka Pharmaceutical Co., Ltd. |
| Bayer AG |
| AstraZeneca PLC |
| Others |
Value Chain & Pricing Dynamics
India and China concentrate active pharmaceutical ingredient manufacturing for intranasal corticosteroid suspensions, anchoring cost structures for olfactory cleft deposition therapies and compressing margin capture for finished formulation marketers in North America and Europe.
Pricing Analysis
Aftermarket service revenue from patient monitoring and adherence programs drives lifetime value capture beyond initial prescription fulfillment. Three-tier pricing structure across premium intranasal devices, standard oral formulations, and economy supplement tiers stratifies the market by administration sophistication and reimbursement intensity. Cost compression in the supplement tier intensifies because consumer self-direction toward zinc and vitamin A formulations bypasses clinical channels entirely. Hospital procurement committees at academic medical centers demonstrate lowest price sensitivity, while direct-to-consumer supplement buyers in India and Brazil exhibit acute elasticity.
Supply Chain Analysis
Catalent, Thermo Fisher Scientific, and Lonza hold contract manufacturing capacity for sub-10-micron particle engineering used in olfactory cleft-targeting intranasal suspensions. Finished formulation supply concentrates in the United States, Germany, and Japan where specialized ENT clinic networks create institutional demand pull. Raw material dependencies rest on corticosteroid APIs, specialized excipients for mucosal adhesion, and precision spray pump components. Single-source vulnerability in particle size reduction technology creates supply chain risk for sponsors pursuing FDA olfactory endpoint validation. Distribution runs through hospital procurement systems and specialty pharmacy channels in developed markets, with direct-to-consumer e-commerce dominating supplement flow in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent pharmaceutical franchises must defend against substitution by over-the-counter mineral supplements that delay clinical intervention and erode prescription capture rates among price-sensitive patient segments.
For Market Incumbents: Harden formulary positioning through bundled diagnostic-therapeutic offerings that incorporate objective smell quantification technology alongside intranasal corticosteroid suspensions. Expand backward integration into sub-10-micron particle engineering capabilities to secure supply continuity for olfactory cleft deposition platforms. Deepen prescriber relationships in neurology departments to cross-sell chemosensory indications alongside existing Parkinson's and Alzheimer's portfolios.
For New Entrants and Emerging Players: Build out telehealth-enabled remote olfactory training infrastructure to capture margin pools beyond traditional clinic-based administration in Germany and the United Kingdom. Target homecare settings as the most penetrable end-user segment, where statutory insurers pilot adherence program reimbursement and remote monitoring technology lowers patient acquisition costs. Pursue PMDA accelerated review pathways in Japan to compress market access timelines relative to FDA and EMA jurisdictions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed intranasal delivery platform developers that have achieved CE marking under EMA MDR but require capital for US commercial scale-up. Long-term viability across the analysis window hinges on regulatory differentiation through objective biomarker endpoints rather than subjective patient-reported outcomes. Monitor FDA guidance evolution on olfactory dysfunction trial design as the critical inflection signal for portfolio rebalancing toward validated diagnostic-therapeutic bundles.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Olfactory Endpoint Validation | Regeneron Pharmaceuticals and peers compress trial timelines through biomarker adoption under expanded agency guidance. |
| CE Marking Pathway under EMA MDR | Device-based delivery systems face elevated certification burdens that favor sponsors with existing European infrastructure. |
| Hospital System Partnership for Protocol Standardization | Johns Hopkins and Mayo Clinic institutional procurement creates demand pull for reimbursable therapeutic bundles. |
| Software Companion Development for Remote Training | Digital olfactory training platforms expand margin pools beyond clinic walls through telehealth reimbursement pilots. |
| Reimbursement Strategy for Intranasal Premium Positioning | Direct-to-site pharmacokinetics command favorable coding through specialized deposition technology differentiation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ENT specialists, hospital procurement managers, regulatory affairs leads at biologics developers, and formulary directors at major US payers. Secondary validation drew from FDA guidance documents on olfactory dysfunction therapeutics, EMA MDR device classification rulings, PMDA accelerated review pathway determinations, ClinicalTrials.gov enrollment data, and hospital procurement database extracts. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Calibration against historical prescription volume patterns and regulatory approval velocity informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user setting, and application indication, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from fitted growth curves applied to normalized baseline data. Forecast inputs incorporated PMDA review timeline differentials, telehealth reimbursement policy trajectories, and supplement substitution elasticities by geography.
Stress conditions across FDA guidance stringency evolution, EMA MDR compliance cost inflation, and consumer supplement substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement policy continuity. Quarterly review of biomarker validation progress, telehealth coding decisions, and supplement market growth rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Bipolar Disorders Treatment Market