
 Toxic Shock Syndrome Treatment Market | 2026-2036
Toxic Shock Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Toxic Shock Syndrome Treatment Market Analytics
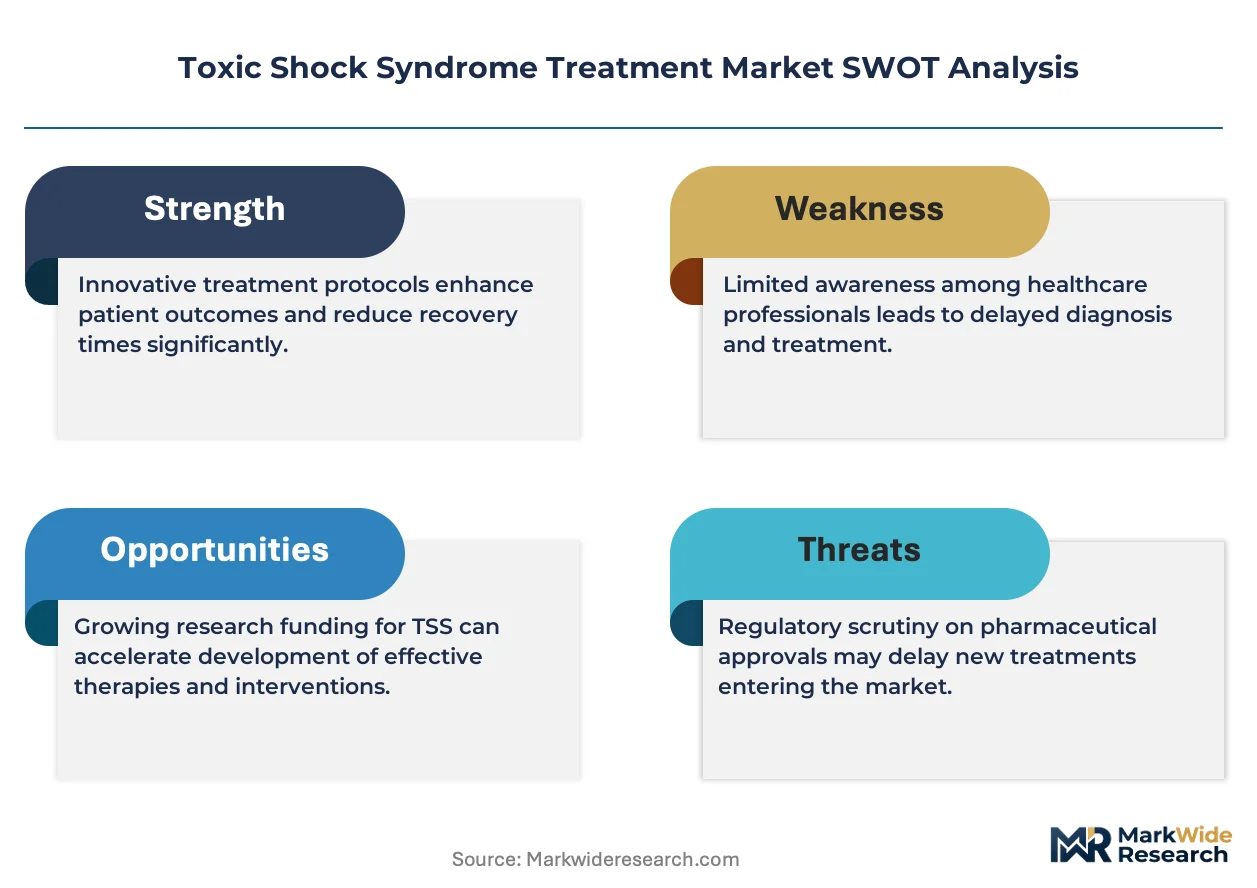
Hospital procurement of TSS therapies is decoupling from traditional group purchasing organizations as emergency departments and critical care units establish direct sourcing agreements with manufacturers. Pfizer Inc. leverages its established hospital distribution network to sustain formulary access across major academic medical centers. Sun Pharmaceutical Industries Ltd. anchors its position through cost-competitive generic antibiotic portfolios that compete on price in institutional tenders. Merck & Co., Inc. differentiates through targeted R&D investments in novel antimicrobial formulations.
Toxic shock syndrome treatment encompasses acute medical interventions targeting Staphylococcus aureus and Streptococcus pyogenes exotoxin-mediated systemic inflammatory responses, primarily administered through intravenous routes with rapid hemodynamic stabilization protocols. The primary commercial purpose centers on reducing mortality in septic shock presentations through source control, toxin neutralization, and organ perfusion support. Antibiotics occupy the largest revenue share within product type segmentation due to immediate empiric therapy requirements, while intravenous immunoglobulin represents the fastest-expanding category as adjunctive protocols gain clinical traction. Hospitals dominate distribution channels by volume, though emergency medicine as a therapy area commands premium pricing through time-sensitive administration requirements.
The FDA regulates TSS biologics and antimicrobials through BLA and NDA pathways, while the EMA's MDR framework governs device-drug combination products in European markets. These agencies shape demand through accelerated approval designations for life-threatening infectious disease indications and stringent post-market surveillance requirements. Stakeholders must monitor evolving IVIG shortage mitigation strategies and antimicrobial stewardship mandates that will reshape procurement priorities and therapeutic sequencing decisions.
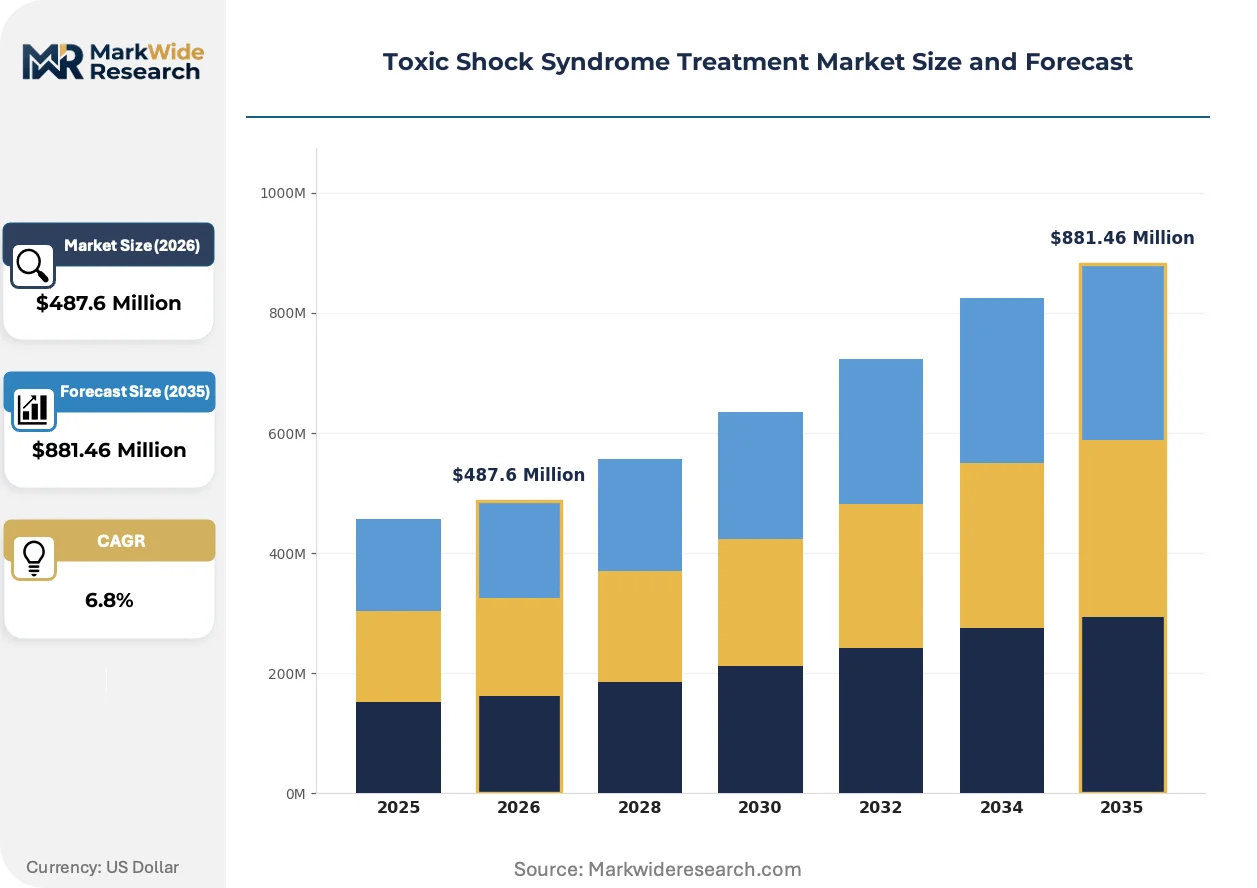
Market Dynamics
Emergency departments are bypassing traditional procurement channels to secure rapid access to IVIG and antimicrobial therapies, creating a bifurcated sourcing structure that separates acute-care purchasing from standard hospital formulary processes.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's expanded access programs for life-threatening infectious diseases compress development timelines for novel toxin-neutralizing biologics, pulling forward commercial availability.
- Critical Care Infrastructure Expansion:Tertiary medical centers in the United States are adding dedicated toxic shock rapid-response units, expanding the installed base for advanced hemodynamic support devices.
- Clostridioides difficile Co-infection Protocols:Rising awareness of polymicrobial sepsis presentations is broadening empiric antibiotic coverage requirements in emergency medicine.
Market Restraints
- Plasma Collection Concentration:IVIG raw material supply concentrates among fractionators dependent on US-based plasma collection networks, exposing manufacturers to geographic supply shocks.
- Antimicrobial Stewardship Mandates:The CDC's Core Elements of Hospital Antibiotic Stewardship programs restrict broad-spectrum empiric prescribing, narrowing initial therapy options.
- Reimbursement Compression:CMS inpatient prospective payment systems bundle TSS treatment into DRG classifications, limiting standalone therapy pricing flexibility.
Strategic Opportunities
- Pre-Hospital Administration:Emergency medical services in the United States are piloting IVIG initiation during transport, creating a new channel between manufacturers and ambulance-based clinicians.
- Companion Diagnostic Integration:Rapid toxin identification assays converging with PCR-based pathogen detection enable targeted therapy selection within the first hour of presentation.
- IRA Domestic Manufacturing Incentives:Federal production credits for critical medicines are enabling reshoring of sterile injectable antibiotic fill-finish capacity.
Industry Challenges
- Specialized Critical Care Pharmacy Expertise:Health systems face acute shortages of pharmacists trained in high-dose IVIG dosing protocols and drug interaction management in septic patients.
- Legacy EHR Integration:Emergency department information systems require expensive customization to incorporate real-time TSS severity scoring and automated antibiotic decision support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toxic Shock Syndrome Treatment Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Intravenous Immunoglobulin, Corticosteroids, Vasopressors Therapy Area: Infectious Diseases, Autoimmune Disorders, Critical Care, Emergency Medicine Distribution Channel: Hospitals, Clinics, Retail Pharmacies, Online Pharmacies End User: Healthcare Providers, Patients, Research Institutions, Emergency Services |
| Companies Covered | Zydus Pharmaceuticals Inc., Sun Pharmaceutical Industries Ltd., Mylan N.V., Merck & Co., Inc., Pfizer Inc., Teva Pharmaceuticals Ltd., Advanz Pharmaceuticals, Sanofi S.A., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toxic Shock Syndrome Treatment Market Evolving Landscape
Clinical practice is pivoting toward earlier immunomodulatory intervention, with protocols compressing the window between presentation and IVIG administration while simultaneously narrowing antibiotic de-escalation timelines.
Monoclonal antibody therapies targeting staphylococcal superantigens are consolidating the adjunctive treatment landscape for refractory toxic shock cases. Academic medical centers in the United States are adopting these agents within 18 months of Phase III readout. The technology is consolidating market share previously distributed across polyclonal immunoglobulin and experimental plasma exchange protocols.
The FDA's updated guidance on IVIG use in toxic shock protocols is mandating post-market cardiovascular safety surveillance for high-dose regimens. Hospital pharmacy and therapeutics committees are revising automatic substitution policies in response. Emergency medicine departments bear the primary compliance burden, with tertiary centers investing in dedicated adverse event monitoring infrastructure.
Direct sourcing agreements between emergency departments and manufacturers are displacing group purchasing organization intermediaries for time-critical therapies. Critical care units in the United States are negotiating manufacturer-held consignment inventory with usage-based reconciliation. This pattern concentrates procurement authority within individual hospitals rather than health system central offices.
Toxic Shock Syndrome Treatment Market Segmentation
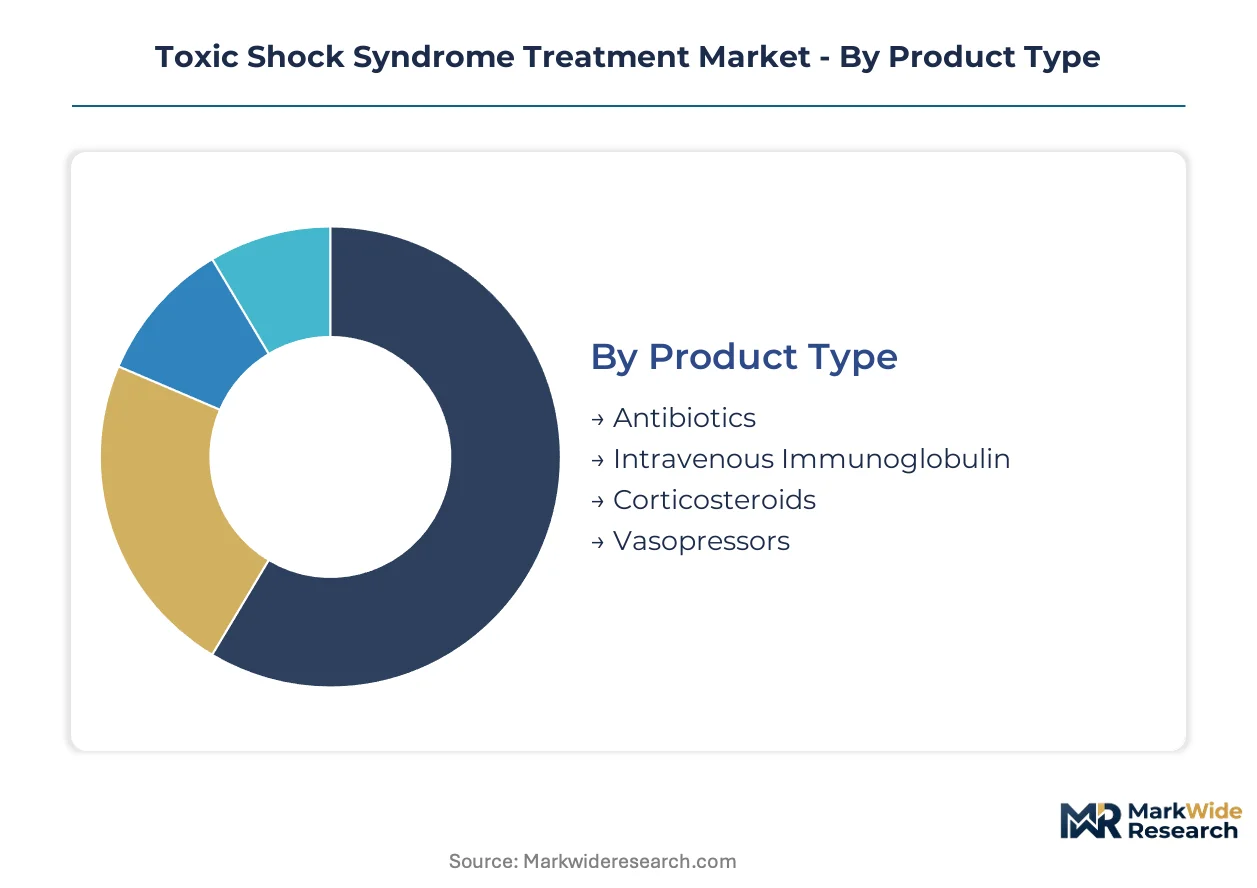
Toxic shock syndrome treatment segmentation reveals acute procurement pressures that separate high-volume antibiotic commoditization from premium biologic positioning. Product mix decisions cascade through therapy area prioritization, distribution channel selection, and end-user targeting with distinct margin profiles.
Product Type:
Volume concentration sits with empiric antibiotics while premium capture flows through immunomodulatory biologics requiring specialized handling protocols.
- Antibiotics:Broad-spectrum beta-lactams and clindamycin combinations dominate initial empiric protocols for Staphylococcus aureus and Streptococcus pyogenes coverage. Tertiary care centers in the United States drive procurement volume through rapid initiation mandates in emergency departments, constrained by antimicrobial stewardship restrictions on broad-spectrum selection.
- Intravenous Immunoglobulin:Polyclonal immunoglobulin G preparations neutralize circulating superantigens through Fc-mediated mechanisms and complement pathway modulation. Demand concentrates in academic medical centers with established high-dose protocols, accelerated by FDA guidance expanding adjunctive use in refractory presentations.
- Corticosteroids:Hydrocortisone and methylprednisolone pulse therapy addresses refractory hypotension in septic shock presentations.
- Vasopressors:Norepinephrine and vasopressin infusions maintain organ perfusion pressure during hemodynamic collapse.
Today's leader: Antibiotics. Tomorrow's challenger: Intravenous Immunoglobulin.
Therapy Area:
Emergency medicine commands premium pricing through time-sensitive administration requirements while infectious diseases anchors volume through protocol standardization.
- Emergency Medicine:Rapid-response protocols compress the therapeutic window to under 60 minutes from presentation, requiring pre-positioned inventory and immediate access pathways. United States emergency departments are establishing direct manufacturer consignment arrangements to bypass procurement delays.
- Critical Care:Intensive care units manage multi-organ dysfunction through integrated hemodynamic support and continuous renal replacement therapy coordination.
- Infectious Diseases:Specialist consultation guides de-escalation decisions and source control timing in complex presentations.
- Autoimmune Disorders:Overlapping cytokine storm presentations in established autoimmune patients require differentiated immunosuppression protocols.
Emergency medicine captures the steepest expansion trajectory as pre-hospital administration pilots expand the addressable intervention window.
Distribution Channel:
Hospital procurement authority is fragmenting between centralized pharmacy committees and emergency department direct sourcing.
- Hospitals:Inpatient pharmacies manage formulary placement, inventory positioning, and stewardship compliance for acute sepsis protocols.
- Clinics:Outpatient infusion centers handle stable post-acute IVIG continuation and antibiotic completion courses.
- Retail Pharmacies:Oral antibiotic step-down therapy and discharge prescription fulfillment serve recovery-phase patients.
- Online Pharmacies:Specialty biologic home delivery supports prolonged outpatient immunoglobulin regimens.
Hospital dominance persists in acute-phase biologics while online channels gain traction in chronic maintenance segments.
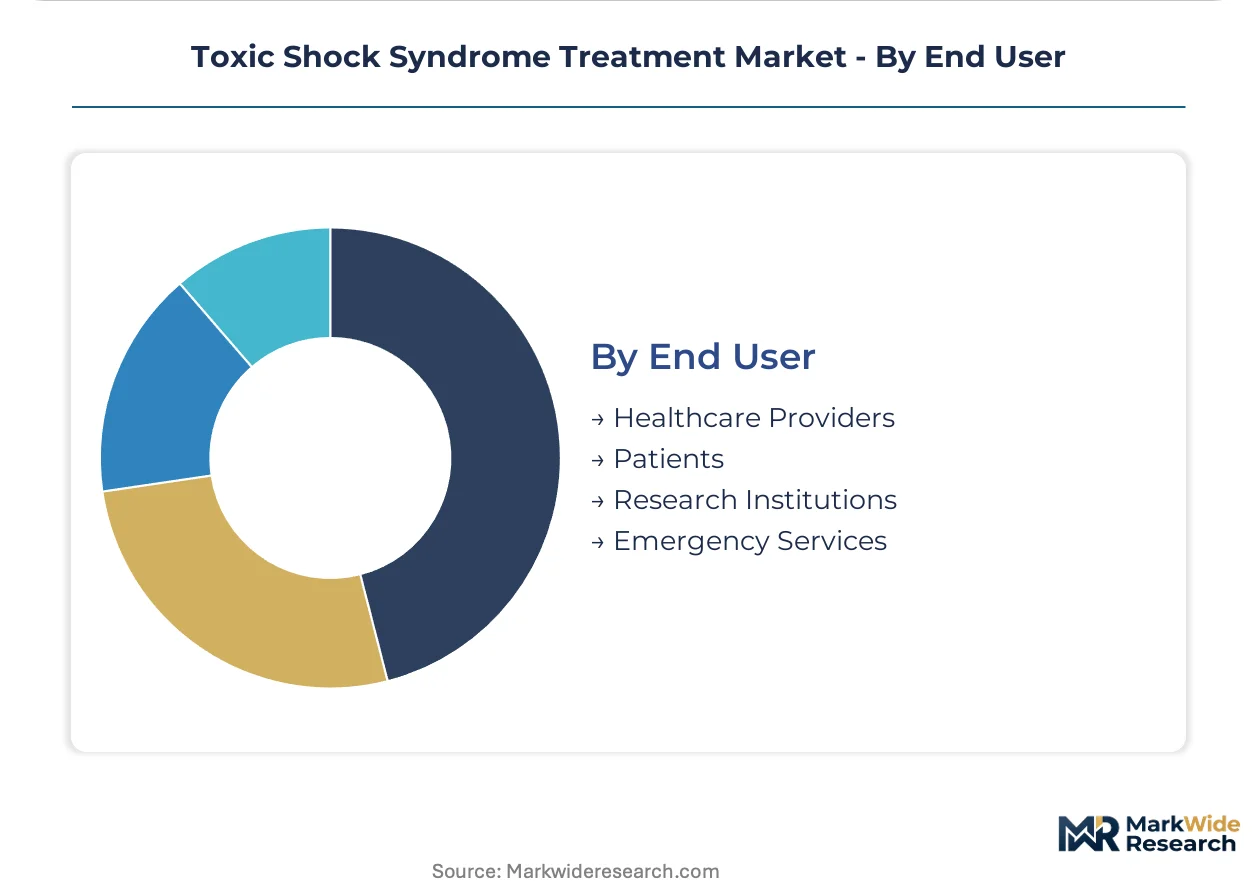
End User:
Procurement influence concentrates with healthcare providers though emergency services are emerging as a distinct purchasing constituency.
- Healthcare Providers:Hospital systems and physician groups control formulary decisions, dosing protocols, and vendor selection through pharmacy and therapeutics committees.
- Emergency Services:Ambulance-based clinicians in the United States are piloting IVIG initiation during transport, creating manufacturer-direct procurement relationships outside hospital supply chains.
- Patients:Out-of-pocket costs for prolonged IVIG courses and oral antibiotic copayments influence adherence and completion rates.
- Research Institutions:Academic medical centers drive protocol innovation and post-market surveillance for novel biologic interventions.
Healthcare providers retain current purchasing authority. Emergency services represent the fastest-climbing influence segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States emergency departments drive higher IVIG consumption per capita than German hospitals, reflecting divergent protocol adoption timelines between North American and European critical care systems.
United States
Tertiary care centers in Boston and Houston anchor demand through dedicated toxic shock rapid-response units. FDA accelerated approval pathways compress commercialization timelines for novel toxin-neutralizing biologics. The Cleveland Clinic and Mayo Clinic systems pilot pre-hospital IVIG administration protocols with regional emergency medical services.
Germany
EMA MDR framework compliance costs slow device-drug combination product introductions compared to US timelines. Baden-Württemberg and Bavaria host concentrated critical care infrastructure with standardized sepsis protocols. University hospitals in Heidelberg and Munich coordinate antimicrobial stewardship mandates through the German Sepsis Society.
Japan
PMDA regulatory requirements extend review periods for IVIG label expansions in infectious disease indications. Tokyo and Osaka metropolitan areas concentrate advanced hemodynamic support device utilization. The Japanese Association for Infectious Diseases revises empiric therapy guidelines to address rising Streptococcus pyogenes resistance patterns.
United Kingdom
NICE technology appraisals constrain premium biologic adoption within NHS England budget frameworks. London and Manchester academic medical centers maintain specialized toxic shock registries for post-market surveillance. The UK Sepsis Trust advocates for standardized IVIG dosing protocols across intensive care networks.
India
CDSCO manufacturing facility inspections create supply bottlenecks for imported plasma-derived therapies. Maharashtra and Gujarat host expanding hospital pharmacy infrastructure serving tertiary referral patterns. Apollo Hospitals and Max Healthcare systems in Delhi-NCR establish direct sourcing agreements for time-critical antimicrobial procurement.
Toxic Shock Syndrome Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across antibiotic commoditization and biologic premiumization vectors. Market structure bifurcates between high-volume generic antimicrobial manufacturers and concentrated plasma fractionators controlling IVIG supply. Three archetypes dominate: integrated pharmaceutical conglomerates with hospital distribution networks, generic antibiotic specialists competing on institutional tender pricing, and biologic-focused developers of novel immunomodulatory therapies. Capacity expansion in sterile injectable fill-finish and strategic partnerships for plasma collection access represent the dominant competitive moves.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. occupy positions anchoring hospital formulary access through established critical care distribution infrastructure. Sun Pharmaceutical Industries Ltd. exemplifies the generic antibiotic specialist archetype, competing on cost positioning within institutional procurement frameworks. These three companies represent distinct strategic postures without overlapping core competitive territories.
| Leading Market Players |
|---|
| Zydus Pharmaceuticals Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Teva Pharmaceuticals Ltd. |
| Advanz Pharmaceuticals |
| Sanofi S.A. |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
FDA's post-market cardiovascular safety surveillance mandate for high-dose IVIG regimens gates both qualified supply and premium-tier pricing access, separating manufacturers with adverse event monitoring infrastructure from commodity-positioned competitors.
Pricing Analysis
Capacity additions in the United States for sterile injectable fill-finish are reshaping price floors for empiric antibiotic therapies. Three-tier pricing structure across premium biologic, standard antimicrobial, and economy generic levels dominates the market, with FDA certification tier and volume scale driving differentiation. Cost compression in generic beta-lactams is intensifying because institutional tender competition concentrates procurement authority. Hospital pharmacy committees exhibit highest price sensitivity, while emergency departments demonstrate lowest sensitivity due to time-critical administration requirements.
Supply Chain Analysis
Unused IVIG inventory returns from hospital consignment arrangements feed into plasma fractionator refurbishment programs for quality-controlled redistribution. Geographic supply concentration centers on the United States, Germany, and Japan for plasma-derived therapies and sterile injectable manufacturing. Raw material dependencies rest on US-based plasma collection networks, specialized cold-chain logistics infrastructure, and pyrogen-free vial supply. Single-source vulnerability in plasma fractionation exposes manufacturers to geographic supply shocks. Distribution runs through direct manufacturer-to-hospital agreements for time-critical biologics alongside traditional wholesale channels for stable antibiotics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toxic shock syndrome treatment market functions as a stable compounder, with emergency department direct sourcing agreements driving steady volume expansion across tertiary care networks.
For Market Incumbents: Cement formulary lock-in through captive plasma collection partnerships that secure IVIG raw material independence from geographic supply shocks. Expand backward integration into sterile injectable fill-finish capacity to defend margin position against generic antibiotic specialists competing on institutional tender pricing. For New Entrants and Emerging Players: Begin with emergency medical services pre-hospital administration pilots in the United States, the most penetrable channel outside established hospital supply chains. Target rapid toxin identification assay integration as a differentiated go-to-market angle that enables targeted therapy selection within the first hour of presentation. For Investors and Strategic Acquirers: Roll-up economics work for regional plasma collection networks because FDA shortage mitigation strategies concentrate bargaining power with fractionators possessing geographic supply diversification. Long-term viability spans the mid-term window for manufacturers with cardiovascular safety surveillance infrastructure. Monitor IVIG label expansion decisions by the FDA as the critical inflection indicator for biologic premiumization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive supply from US-based collection centers insulates against geographic shortage shocks. |
| Emergency Department Consignment Agreements | Manufacturer-held inventory with usage-based reconciliation bypasses GPO procurement delays. |
| Companion Diagnostic Development | Rapid toxin identification assays enable premium positioning through targeted therapy protocols. |
| Sterile Injectable Fill-Finish Capacity | IRA domestic manufacturing incentives support reshoring of critical antibiotic production. |
| Pre-Hospital Administration Pilots | EMS-based IVIG initiation creates new channel relationships outside hospital supply chains. |
Research Methodology
Bottom-up emergency department procurement modeling reconciled against top-down plasma fractionator production tracking forms the analytical core of this study. Primary interviews with hospital pharmacy directors, critical care physicians, plasma collection facility operators, and emergency medical services administrators combined with secondary validation from FDA filings, ClinicalTrials.gov, CMS Medicare reimbursement data, and hospital procurement databases.
Historical trendline analysis of IVIG utilization patterns and antibiotic prescribing volumes informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, therapy area, distribution channel, and regional regulatory cluster. CAGRs derived from weighted average of bottom-up volume builds and top-down market sizing reconciliation, incorporating antimicrobial stewardship compliance rates and IVIG shortage frequency as industry-specific inputs.
Several conditions sit outside the modeled scope, including experimental monoclonal antibody therapies pending Phase III readout and plasma exchange protocol adoption in non-academic centers. Forecasts reflect documented assumptions regarding FDA guidance stability and plasma collection network expansion timelines. Practitioners should monitor CDC stewardship mandate enforcement intensity and IVIG cardiovascular safety surveillance outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market