
 Idiopathic Short Stature Market | 2026-2036
Idiopathic Short Stature Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Short Stature Market Outlook
Biologics manufacturing capacity in South Korea is decoupling from traditional North American and European supply dependencies. Novo Nordisk leverages its recombinant protein platform to sustain leadership in long-acting growth hormone formulations. BioMarin Pharmaceutical anchors its position through rare disease specialization and pediatric metabolic expertise. Pfizer competes via established hospital channel relationships and broad endocrinology portfolio breadth.
Idiopathic short stature denotes a condition of unexplained diminished linear growth in children, defined clinically as height more than two standard deviations below the mean for age and sex without identifiable hormonal, genetic, or systemic cause; recombinant human growth hormone (somatropin) remains the primary pharmacologic intervention, administered via subcutaneous injection to stimulate insulin-like growth factor-1 production and epiphyseal plate activity. Growth hormones dominate current revenue pools given decades of clinical validation and payer familiarity, while genetic therapies represent the fastest-expanding segment as CRISPR-based approaches advance through early-stage trials. Injectable delivery mode retains the largest volume share, though transdermal formulations are attracting development capital aimed at reducing pediatric injection burden and improving adherence profiles.
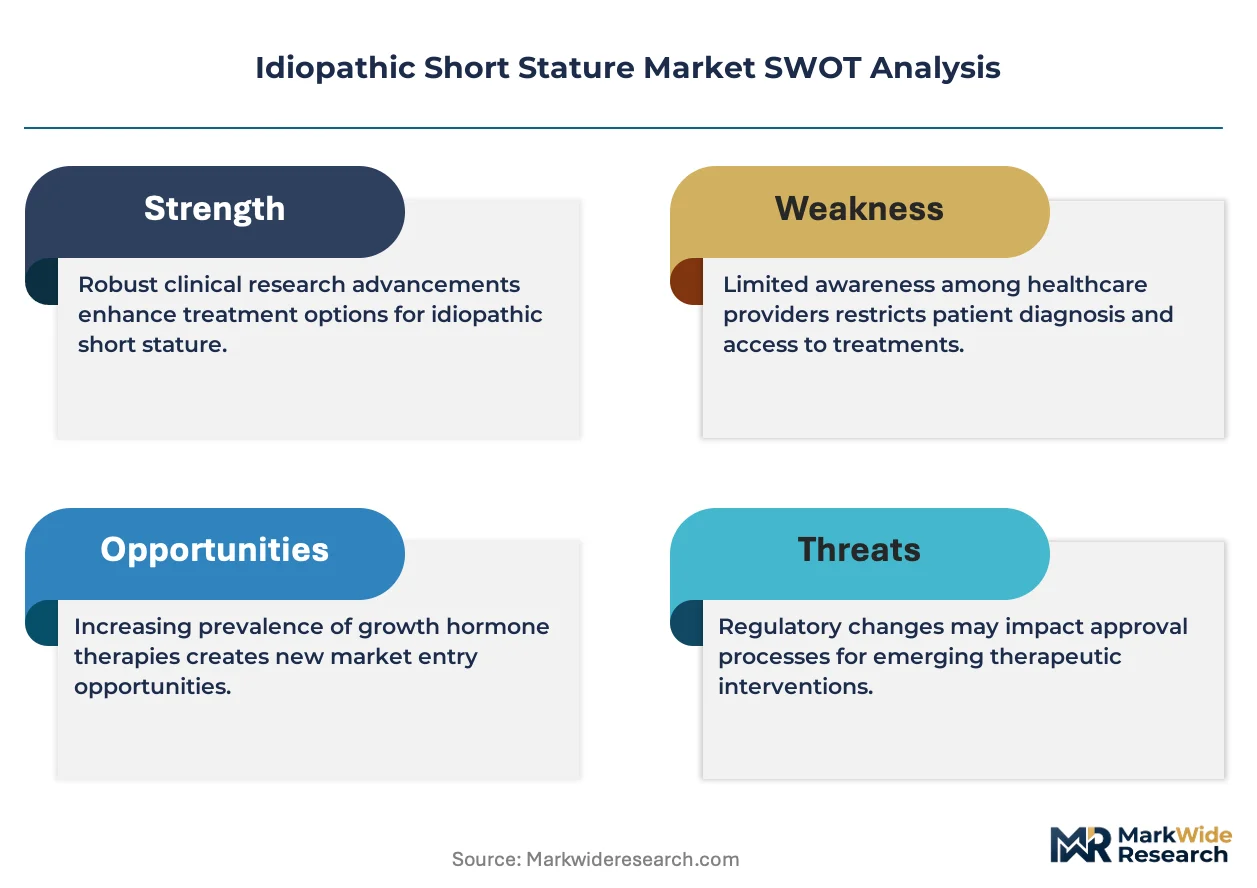
FDA pediatric study requirements and EMA's Paediatric Investigation Plans shape trial design and market access timelines for novel therapies, with Japan's PMDA adding distinct local efficacy benchmarks that manufacturers must satisfy. The country's national pharmaceutical regulator in India and CDSCO are tightening import quality standards for biosimilars, altering competitive entry calculus for multinational suppliers. Stakeholders must monitor gene therapy regulatory pathways and real-world evidence requirements that will determine which modalities secure priority reimbursement status across major markets.
Market Dynamics
FDA pediatric exclusivity incentives are redirecting clinical trial investment toward long-acting growth hormone formulations, compressing development timelines while EMA Paediatric Investigation Plans impose parallel compliance burdens that reshape competitive entry sequencing.
Growth Catalysts
- PMDA pediatric efficacy benchmarks:Japan's distinct local requirements for somatropin analogs create dedicated development pathways that reward early regulatory engagement with accelerated market access.
- Recombinant protein platform maturation:Advances in E. coli and mammalian cell expression systems are reducing biologics manufacturing costs for pediatric endocrinology applications.
- Specialist referral network densification:Concentrated pediatric endocrinologist presence in the United States, Germany, and Japan concentrates diagnosis velocity and treatment initiation rates.
Market Restraints
- Recombinant protein input volatility:Cell culture media and chromatography resin supply concentration in South Korean and German suppliers creates cost unpredictability for biosimilar manufacturers.
- Epiphyseal closure biology:Fundamental physiological limits on treatment windows compress revenue duration per patient and constrain dosing optimization.
- EMA Paediatric Investigation Plan friction:Mandatory pediatric study requirements for novel formulations extend development timelines by 24-36 months without guaranteed exclusivity returns.
Strategic Opportunities
- Transdermal delivery convergence:Microneedle array technology combined with sustained-release polymers offers needle-free administration that addresses pediatric adherence barriers.
- CDSCO import pathway liberalization:India's tightening biosimilar quality standards simultaneously create premium positioning opportunities for compliant multinational suppliers.
- Gene therapy regulatory tailwinds:CRISPR-based height augmentation approaches advancing through early-stage trials may unlock orphan-disease-style incentives if PMDA and FDA pathways align.
Industry Challenges
- Pediatric endocrinology talent scarcity:Fellowship-trained specialists concentrate in academic medical centers, limiting community-based diagnosis and referral throughput.
- Real-world evidence infrastructure gaps:Longitudinal height velocity tracking systems remain fragmented across hospital networks, complicating post-market efficacy demonstration for novel modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Short Stature Market |
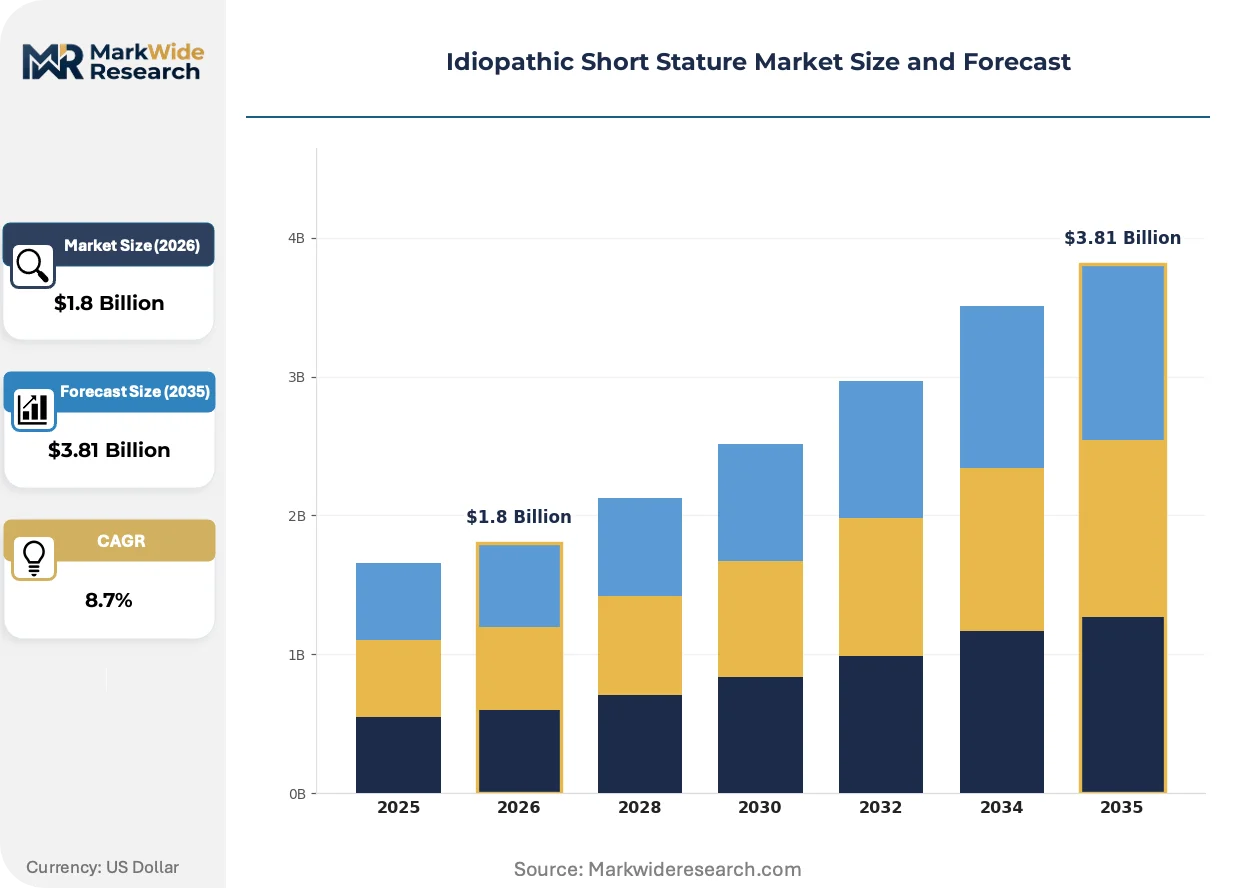
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Hormones, Nutritional Supplements, Genetic Therapies, Recombinant Proteins Delivery Mode: Injectable, Oral, Transdermal, Intranasal End User: Pediatrics, Endocrinology Clinics, Hospitals, Homecare Settings Application: Growth Disorders, Short Stature Management, Pediatric Care, Research Applications |
| Companies Covered | Tercica, BioMarin Pharmaceutical, Novo Nordisk, Merck, Daewoong Pharmaceutical, Pfizer, Insmed, Teva Pharmaceuticals, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Short Stature Market Strategic Shifts
Long-acting growth hormone formulations are compressing injection frequency from daily to weekly, while gene therapy platforms and transdermal delivery systems simultaneously challenge the injectable paradigm that has dominated pediatric endocrinology for three decades.
Automated glycoengineering platforms are automating the optimization of N-linked glycan structures on recombinant somatropin, enabling biosimilar manufacturers to match innovator pharmacokinetic profiles with reduced analytical burden. South Korean contract development organizations are adopting these systems fastest, cutting cell line development timelines by half. The technology is automating quality-attribute matching that previously required iterative manual screening, compressing biosimilar entry costs.
EMA's revised Paediatric Investigation Plans now mandate long-term adult metabolic outcome tracking for growth hormone therapies approved in childhood, extending post-authorization study obligations through patient maturation. This regulatory expansion increases trial infrastructure requirements and favors sponsors with established real-world evidence platforms. European pediatric endocrinology networks are consolidating data-sharing agreements to distribute compliance costs.
Hospital procurement committees are consolidating growth hormone purchasing through centralized pharmacy and therapeutics committees, displacing individual prescriber preference with formulary-driven selection criteria. This behavioral shift concentrates volume with suppliers demonstrating total-cost-of-care advantages including adherence support programs. The United States exhibits this pattern most acutely as integrated delivery networks expand pediatric specialty pharmacy control.
Idiopathic Short Stature Market Segmentation
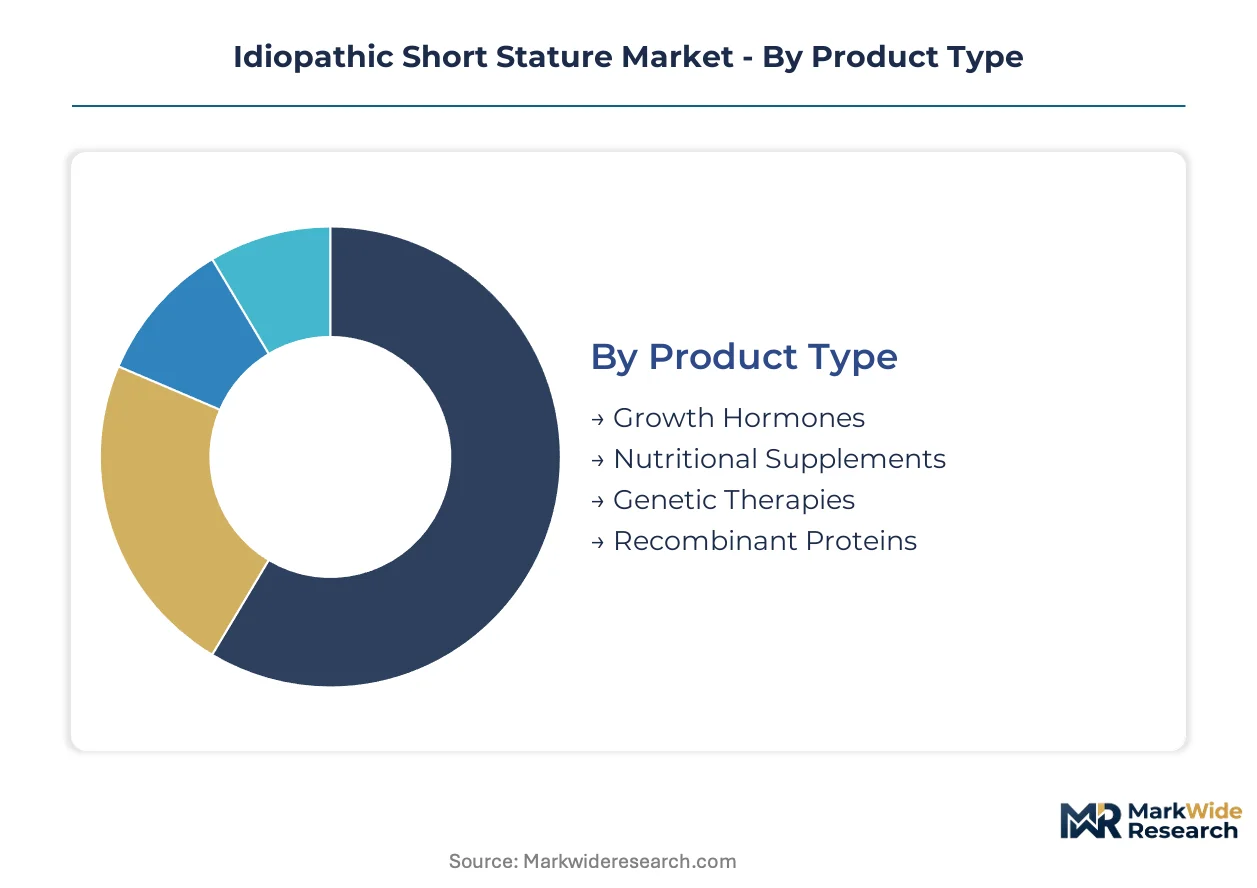
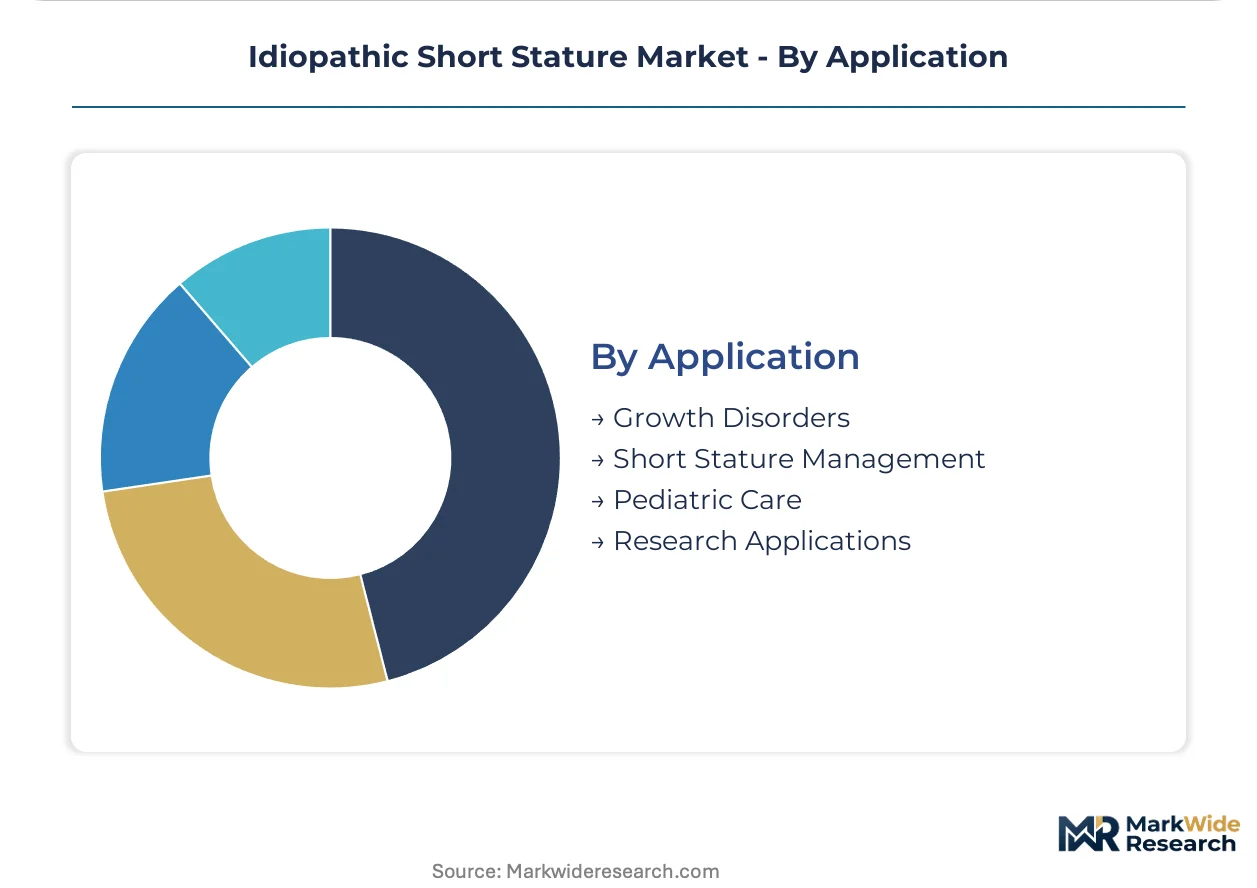
Segmentation in idiopathic short stature therapeutics reveals divergent buyer priorities across treatment modalities, administration preferences, and care settings. Understanding these distinctions enables suppliers to align development investments with where clinical and economic value concentrates.
Product Type:
Cost tier differentiation separates blockbuster biologics from emerging modalities, with reimbursement bandwidth and manufacturing complexity driving portfolio decisions.
- Growth Hormones:Recombinant somatropin formulations dominate current prescribing, leveraging decades of FDA and EMA safety data to secure broad payer coverage. Demand concentrates in pediatric endocrinology clinics across the United States, Germany, and Japan where specialist density accelerates diagnosis-to-treatment intervals.
- Genetic Therapies:CRISPR-based height augmentation approaches target underlying growth plate biology through permanent genetic modification rather than chronic hormone replacement. Research applications in academic medical centers represent the primary demand concentration as regulatory pathways mature.
- Nutritional Supplements:Adjunctive amino acid and micronutrient formulations support growth velocity in milder cases.
- Recombinant Proteins:Next-generation IGF-1 analogs and growth hormone releasing hormone mimetics expand mechanistic options.
Growth hormones lead volumes today; genetic therapies are gaining share fastest.
Delivery Mode:
Patient age and needle tolerance shape administration preferences, with adherence economics tilting investment toward less invasive alternatives.
- Injectable:Subcutaneous somatropin via pen devices retains the largest volume share, though daily injection burden drives discontinuation in adolescent populations. Homecare settings in Japan and Germany exhibit highest persistence rates where nurse educator support is embedded in reimbursement.
- Transdermal:Microneedle arrays and sustained-release polymers eliminate needle anxiety, addressing the primary adherence barrier in pediatric populations. Development capital is concentrating in South Korean contract manufacturing organizations with automated patch production capabilities.
- Oral:Growth hormone secretagogues and small-molecule IGF-1 pathway modulators offer needle-free alternatives with reduced bioavailability.
- Intranasal:Pulmonary and nasal absorption formulations target rapid onset for acute growth hormone stimulation testing.
Injectable administration retains volume leadership; transdermal delivery is expanding most quickly.
End User:
Care setting determines reimbursement mechanics and prescribing authority, with channel consolidation reshaping supplier access strategies.
- Pediatrics:General pediatricians serve as gatekeepers for specialist referral, concentrating initial diagnostic encounters in community practice. The United States exhibits highest conversion rates to endocrinology referral where integrated delivery network protocols standardize growth velocity tracking.
- Endocrinology Clinics:Fellowship-trained specialists control treatment initiation and dosing optimization for complex cases. Germany's dense academic medical center network produces the shortest wait times for subspecialty consultation.
- Hospitals:Inpatient growth hormone stimulation testing and surgical co-management occur in tertiary centers.
- Homecare Settings:Self-administration and family-managed injection protocols reduce clinic visit burden.
Endocrinology clinics lead volumes today; homecare settings are climbing the fastest.
Application:
Clinical indication severity and evidence requirements segment development pathways, with regulatory incentives favoring orphan-designation strategies.
- Short Stature Management:Idiopathic cases without identifiable etiology represent the addressable market core, requiring height velocity documentation and bone age assessment. Japan's PMDA mandates distinct local efficacy benchmarks that extend development timelines for multinational sponsors.
- Growth Disorders:Organic causes including growth hormone deficiency and Turner syndrome carry established reimbursement codes. EMA Paediatric Investigation Plans impose parallel study requirements that reshape competitive entry sequencing.
- Pediatric Care:Preventive growth monitoring and early intervention protocols expand addressable population.
- Research Applications:Gene therapy platforms and novel mechanism trials concentrate in academic-industry partnerships.
Short stature management leads volumes today; research applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting biologics manufacturing toward jurisdictions with streamlined pediatric trial frameworks and concentrated contract manufacturing capacity. South Korean CDMOs capture investment flows as North American and European sponsors seek cost-compliant production alternatives.
United States
Pediatric endocrinology specialist density and integrated delivery network consolidation accelerate diagnosis-to-treatment velocity. FDA pediatric exclusivity incentives compress development timelines for long-acting growth hormone formulations. Boston and Philadelphia academic medical centers anchor gene therapy trial infrastructure.
Germany
Dense referral networks and statutory health insurance reimbursement stability sustain high treatment initiation rates. EMA Paediatric Investigation Plans impose parallel compliance burdens that reshape competitive entry sequencing. Baden-Württemberg and Bavaria host the shortest subspecialty wait times in Europe.
Japan
PMDA mandates distinct local efficacy benchmarks for somatropin analogs, rewarding early regulatory engagement with accelerated access. National health insurance maintains broad growth hormone coverage with embedded nurse educator support. Tokyo and Osaka metropolitan clusters concentrate pediatric endocrinology fellowship programs.
South Korea
Contract manufacturing organizations exploit automated glycoengineering platforms to cut biosimilar development timelines. MFDS alignment with ICH standards enables simultaneous global filing strategies. Seoul and Incheon bioclusters attract multinational biologics outsourcing from North American sponsors.
India
CDSCO import pathway tightening for biosimilars creates premium positioning opportunities for quality-compliant multinational suppliers. Domestic pediatric endocrinology capacity remains concentrated in Delhi-NCR and Mumbai academic centers. Central government pediatric growth screening programs expand addressable patient identification.
Idiopathic Short Stature Market Competitive Environment
Danish and Swiss producers anchor the premium formulation tier; South Korean and Indian specialists hold contract manufacturing and emerging market access positions. The market exhibits consolidated leadership in long-acting biologics alongside fragmented biosimilar supply. Three archetypes dominate: vertically integrated biopharma conglomerates, rare disease specialists, and CDMO-dependent challengers. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Within the rare disease specialist tier, BioMarin Pharmaceutical occupies a position exemplifying pediatric metabolic expertise concentration. Novo Nordisk anchors the long-acting formulation leadership archetype through recombinant protein platform extension. Pfizer sits within the hospital channel consolidation tier, representing broad endocrinology portfolio breadth.
| Leading Market Players |
|---|
| Tercica |
| BioMarin Pharmaceutical |
| Novo Nordisk |
| Merck |
| Daewoong Pharmaceutical |
| Pfizer |
| Insmed |
| Teva Pharmaceuticals |
| Eli Lilly |
| Others |
Value Chain & Pricing Dynamics
Vertically integrated biopharma conglomerates anchor pricing discipline through captive recombinant protein production, while CDMO-dependent challengers absorb margin compression from South Korean and German chromatography resin suppliers. This ownership pattern concentrates cost control with platform holders and exposes price-tiers to input volatility from concentrated biologics manufacturing inputs.
Pricing Analysis
Distributor margins on recombinant somatropin formulations compress toward direct-to-hospital contracting as integrated delivery networks consolidate pediatric pharmacy purchasing. Three-tier pricing structure across premium long-acting formulations, standard daily-injection biologics, and economy-tier biosimilars tracks FDA certification status and glycoengineering sophistication. Pricing pressure stems from EMA Paediatric Investigation Plan compliance costs extending development timelines without guaranteed exclusivity returns. Hospital procurement committees exhibit highest price sensitivity, while academic medical centers with embedded research funding demonstrate lowest sensitivity to per-dose differentials.
Supply Chain Analysis
FDA and EMA current Good Manufacturing Practice certifications gate contract manufacturing access for recombinant growth hormone production, filtering supplier pools to established biologics specialists. Manufacturing concentration centers on South Korea, Germany, and the United States for cell culture media and automated glycoengineering platforms. Raw material dependencies include mammalian cell expression systems, N-linked glycan optimization reagents, and sustained-release polymer feedstocks. Single-source vulnerability in chromatography resin supply from German specialty chemical producers creates disruption exposure. Distribution runs through hospital-centered pharmacy and therapeutics committees with embedded specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The idiopathic short stature market functions as a regulatory compounder where FDA pediatric exclusivity incentives and EMA Paediatric Investigation Plans mechanically expand addressable revenue pools for compliant sponsors. These frameworks reward early regulatory engagement with extended market protection windows.
For Market Incumbents: Deepen recombinant protein platform control through backward integration into cell line development and automated glycoengineering capabilities. Incumbent sponsors must secure captive supply of chromatography resins and cell culture media to defend margin position against South Korean CDMO cost advantages. Long-acting formulation leadership requires sustained investment in real-world evidence infrastructure to satisfy EMA's expanded post-authorization study obligations. For New Entrants and Emerging Players: Microneedle array transdermal delivery technology offers a technology-first wedge against injectable-dominant incumbents by addressing pediatric adherence barriers. White-space targets include homecare settings in Japan and Germany where nurse educator support infrastructure enables premium positioning. The most penetrable segment comprises adolescent populations discontinuing daily injection regimens. A go-to-market angle anchored on needle-free administration and family-managed protocols bypasses hospital formulary gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among rare disease specialists with pediatric metabolic expertise but limited manufacturing scale. Long-term viability over a multi-year horizon rests on gene therapy platform optionality and regulatory pathway clarity for CRISPR-based height augmentation. Acquisition target archetypes include CDMO-dependent challengers with transdermal delivery assets and established PMDA engagement histories. The signal to watch is alignment between FDA and PMDA gene therapy approval frameworks, which would unlock orphan-disease-style incentive stacking.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | FDA pediatric exclusivity incentives compress development timelines for weekly-injection somatropin analogs. |
| Transdermal Delivery Investment | Microneedle array technology addresses pediatric adherence barriers and enables homecare expansion. |
| PMDA Early Engagement | Japan's distinct local efficacy benchmarks reward preemptive regulatory dialogue with accelerated market access. |
| Automated Glycoengineering Adoption | South Korean CDMOs cut biosimilar development timelines through N-linked glycan structure optimization platforms. |
| Real-World Evidence Infrastructure | EMA's expanded post-authorization obligations favor sponsors with longitudinal height velocity tracking systems. |
Study Parameters
Direct dialogue with pediatric endocrinologists, hospital pharmacy directors, regulatory affairs specialists, and biosimilar manufacturing executives grounded qualitative findings in clinical and operational realities. Secondary validation drew from FDA pediatric exclusivity filings, EMA Paediatric Investigation Plan submissions, ClinicalTrials.gov growth hormone trial registries, and national health insurance reimbursement databases across the United States, Germany, and Japan. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates.
Bottom-up volume projections tracked diagnosis-to-treatment conversion rates by country, dosing duration limits imposed by epiphyseal closure biology, and formulation-specific adherence profiles. Segmentation dimensions encompassed treatment modality, delivery mechanism, care setting, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical biosimilar entry patterns and long-acting formulation adoption trajectories. Forecast inputs included specialist referral network density, hospital procurement consolidation velocity, and gene therapy regulatory pathway maturation.
The model holds under stable FDA and EMA pediatric incentive frameworks; deviation in gene therapy approval timelines or biosimilar quality-standard harmonization would shift competitive entry sequencing and revenue concentration. Forecasts reflect assumptions regarding epiphyseal biology constraints, reimbursement stability in statutory health insurance systems, and manufacturing cost curves for recombinant protein platforms. A model refresh is warranted upon material change in PMDA-FDA gene therapy pathway alignment or CDSCO import standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Global Occupational Medicines Market