
 Idiopathic Pulmonary Fibrosis Management Market | 2026-2036
Idiopathic Pulmonary Fibrosis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Pulmonary Fibrosis Management Market Foresight
Antifibrotic biomarker integration into clinical workflows is reshaping how physicians stage disease progression and time therapeutic intervention. Boehringer Ingelheim International GmbH leverages its nintedanib franchise to anchor market presence across major prescriber networks. F. Hoffmann-La Roche Ltd sustains competitive intensity through its pirfenidone portfolio and companion diagnostic investments. FibroGen Inc. differentiates via its connective tissue growth factor inhibitor platform, positioning for late-stage clinical validation.
Idiopathic Pulmonary Fibrosis Management encompasses pharmacologic and non-pharmacologic interventions targeting progressive, irreversible lung scarring of unknown etiology, with antifibrotic agents functioning to slow forced vital capacity decline by modulating tyrosine kinase and TGF-beta signaling pathways. The therapeutic objective centers on prolonging transplant-free survival while managing acute exacerbations and comorbid gastroesophageal reflux. Antifibrotic Agents command the dominant value share as first-line standards of care, while Inhalation delivery modes represent the fastest-growing structural category as developers pursue localized pulmonary deposition with reduced systemic exposure. Homecare end users are expanding fastest as oral antifibrotic regimens enable decentralized disease management outside hospital settings.
The FDA maintains stringent evidentiary thresholds for IPF drug approval through its Division of Pulmonology, Allergy, and Critical Care, while the EMA's Committee for Medicinal Products for Human Use applies parallel but distinct benefit-risk frameworks that influence multinational trial design. These regulatory architectures directly shape development costs, label indications, and post-marketing surveillance obligations for commercialized therapies. Stakeholders must monitor how real-world evidence requirements and health technology assessment methodologies evolve across reimbursement authorities to anticipate access and pricing dynamics.
Market Dynamics
The FDA's accelerated approval pathway for breakthrough therapies is compressing development timelines while simultaneously intensifying competitive pressure on established antifibrotic protocols across specialty pulmonology networks.
Growth Catalysts
- Medicare Coverage Expansion:United States reimbursement decisions for oral antifibrotic regimens are decentralizing patient access toward homecare settings and reducing hospital dependency.
- Biomarker-Guided Staging:Integration of forced vital capacity decline metrics and genetic risk profiling into clinical workflows is sharpening therapeutic timing precision.
- Companion Diagnostic Investment:Pharmaceutical developers are embedding predictive testing infrastructure to stratify patient populations and accelerate enrollment efficiency.
Market Restraints
- Specialty Prescriber Concentration:IPF diagnosis and antifibrotic initiation remain concentrated among tertiary academic medical centers, creating geographic access inequities.
- High-Risk Trial Design:The FDA's stringent evidentiary thresholds for survival endpoints inflate Phase III costs and extend validation timelines for novel mechanisms.
- Generic Pirfenidone Entry:Patent cliff dynamics in major markets are eroding branded pricing power and compressing revenue per treated patient.
Strategic Opportunities
- Inhalation Delivery Platforms:Localized pulmonary deposition technologies with reduced systemic exposure are opening differentiation pathways beyond oral kinase inhibitors.
- EMA Parallel Scientific Advice:Coordinated FDA-EMA development programs are enabling synchronized multinational launches and reducing regulatory redundancy costs.
- Acute Exacerbation Prevention:Prophylactic antifibrotic intensification protocols represent an underdeveloped clinical endpoint with payer differentiation potential.
Industry Challenges
- Interstitial Lung Disease Differential Diagnosis:Distinguishing IPF from hypersensitivity pneumonitis and connective tissue disease-associated fibrosis delays appropriate antifibrotic initiation.
- Real-World Evidence Infrastructure:Post-marketing surveillance obligations under FDA and EMA frameworks require costly patient registry maintenance and long-term safety database management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Pulmonary Fibrosis Management Market |
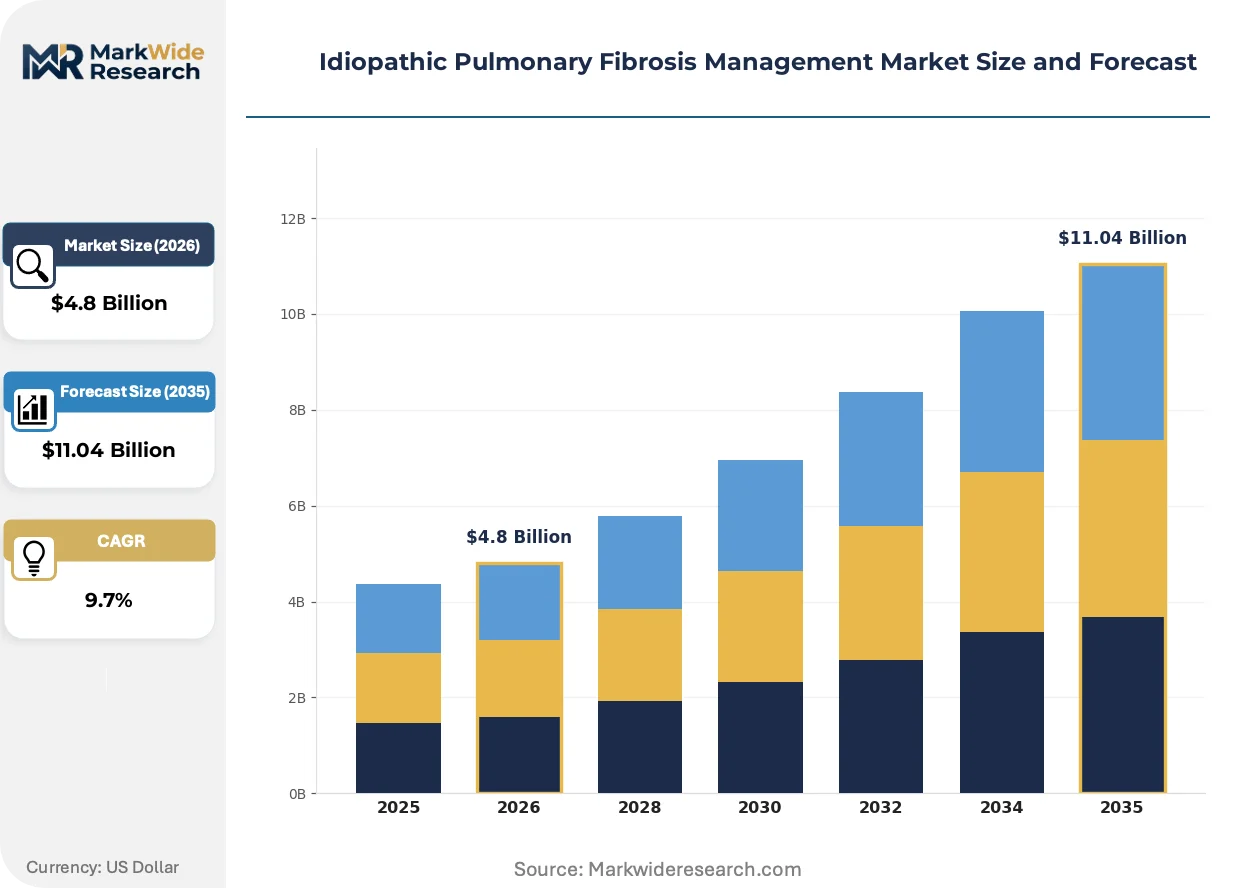
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Corticosteroids, Immunosuppressants, Supportive Care Delivery Mode: Oral, Injectable, Inhalation, Intravenous End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Application: Diagnosis, Treatment Monitoring, Patient Education, Clinical Trials |
| Companies Covered | Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd, FibroGen Inc., Horizon Therapeutics plc, United Therapeutics Corporation, Bristol-Myers Squibb Company, Galapagos NV, Pliant Therapeutics Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Pulmonary Fibrosis Management Market Shifts & Advancements
Antifibrotic development is pivoting from broad tyrosine kinase inhibition toward precision modulation of connective tissue growth factor and integrin signaling pathways with improved tolerability profiles.
Quantitative high-resolution CT fibrosis scoring algorithms are rendering obsolete reliance on qualitative radiologist interpretation for disease progression monitoring. Large academic pulmonology centers in the United States and Germany are adopting vendor-neutral AI platforms for volumetric lung density analysis. This automation is compressing inter-reader variability and enabling decentralized clinical trial endpoint adjudication.
The EMA's Committee for Medicinal Products for Human Use has tightened benefit-risk frameworks for IPF therapies with marginal survival effects, forcing sponsors to enrich trial populations with rapid progressors. This regulatory recalibration is elevating biomarker stratification from exploratory to mandatory. Developers are responding by embedding genetic risk scores and plasma protein signatures into Phase II/III protocols.
Specialty pharmacy distribution is displacing traditional hospital outpatient dispensing for oral antifibrotic maintenance therapy. United States Medicare Part D plans and commercial payers are mandating mail-order fulfillment with adherence monitoring. This channel migration is concentrating fulfillment volume among three national specialty pharmacy networks and reducing prescriber control over patient touchpoints.
Idiopathic Pulmonary Fibrosis Management Market Segmentation
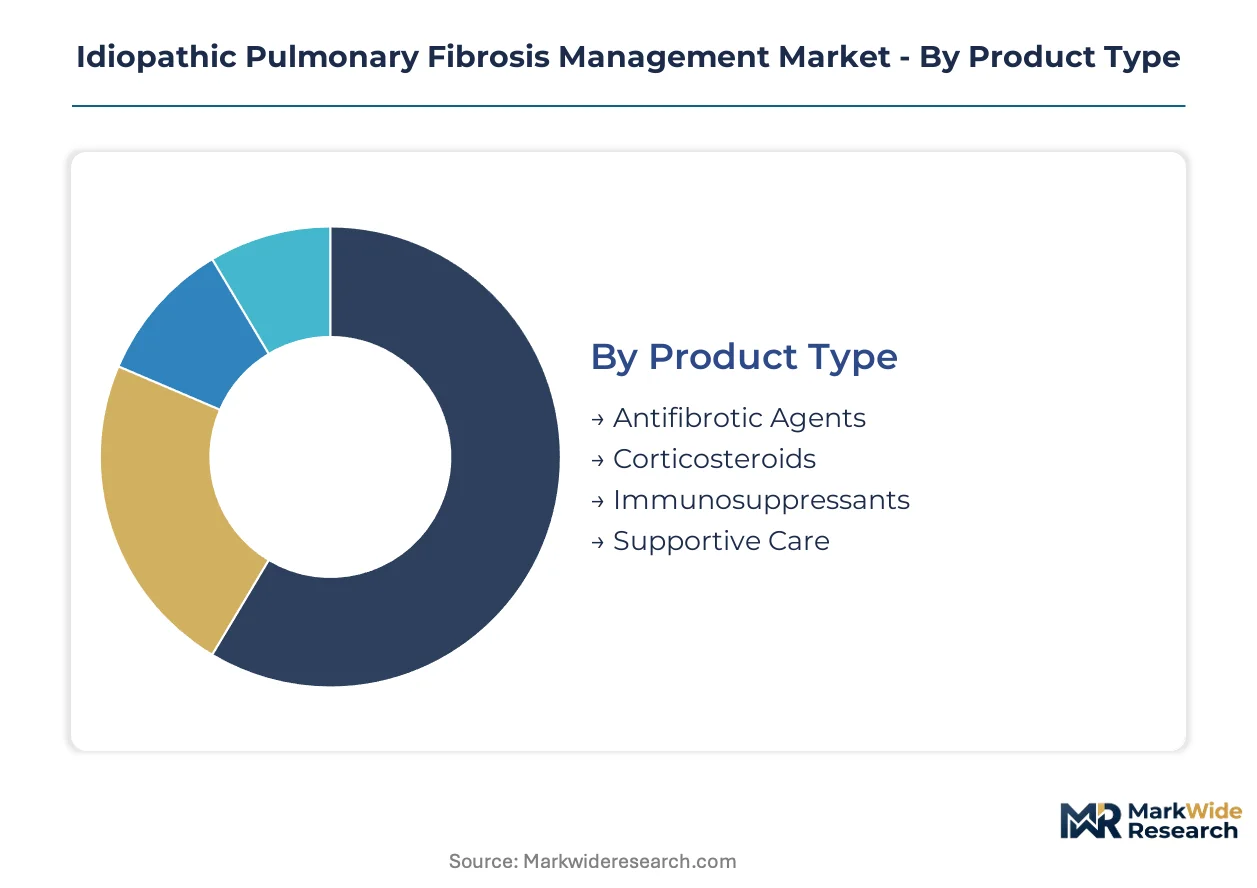
IPF management segmentation reveals how therapeutic value flows through distinct clinical pathways. Product type stratification separates disease-modifying agents from symptomatic interventions, while delivery mode choices determine systemic exposure profiles and site-of-care economics.
Product Type:
Cost tier stratification across pharmacologic classes reflects divergent development complexity and reimbursement positioning.
- Antifibrotic Agents:Tyrosine kinase inhibitors and TGF-beta modulators constitute the premium therapeutic tier, with nintedanib and pirfenidone establishing first-line standards. United States Medicare Part D coverage decisions have concentrated demand among oral kinase inhibitor formulations that slow forced vital capacity decline.
- Corticosteroids:Systemic anti-inflammatory protocols serve acute exacerbation management rather than disease modification, with pulsed methylprednisolone regimens reserved for hospital-based decompensation events. German pulmonology centers emphasize corticosteroid-sparing approaches to minimize infection risk in fibrotic lungs.
- Immunosuppressants:Azathioprine and mycophenolate protocols target connective tissue disease-associated ILD differential diagnoses, requiring rheumatology-pulmonology co-management.
- Supportive Care:Oxygen supplementation, pulmonary rehabilitation, and gastroesophageal reflux management address comorbidity burden without altering fibrotic progression.
Antifibrotic Agents hold installed capacity. Supportive Care is rotating up the share rankings as bundled payment models emphasize total cost of care.
Delivery Mode:
Application-specific delivery choices balance pulmonary deposition precision against systemic tolerability tradeoffs.
- Oral:Twice-daily capsule regimens dominate maintenance therapy, with bioavailability profiles supporting decentralized home administration. Japanese patients demonstrate higher adherence to oral nintedanib versus European cohorts in post-marketing surveillance.
- Inhalation:Nebulized and dry-powder platforms enable localized drug deposition with reduced systemic exposure, attracting development investment for next-generation CTGF inhibitors. United Kingdom specialist centers pilot inhaled pirfenidone formulations to mitigate gastrointestinal adverse events.
- Injectable:Subcutaneous biologic delivery remains investigational for IPF-specific indications, with current use limited to comorbid autoimmune conditions.
- Intravenous:Hospital-confined administration serves acute exacerbation rescue protocols and clinical trial inpatient phases.
Oral formulations anchor current prescribing patterns. Inhalation platforms are climbing the fastest as developers pursue differentiation through reduced systemic toxicity.
End User:
Customer type concentration reflects diagnostic complexity requirements and reimbursement site-of-care differentials.
- Hospitals:Tertiary academic medical centers manage diagnostic workup through high-resolution CT and surgical lung biopsy, with antifibrotic initiation concentrated at United States transplant referral hubs.
- Homecare:Oral maintenance regimens and portable oxygen systems enable decentralized disease management, with United States specialty pharmacy networks capturing fulfillment volume under Medicare Part D mandates.
- Clinics:Community pulmonology practices handle stable patient monitoring and prescription renewal, constrained by geographic distance from academic ILD centers.
- Rehabilitation Centers:Structured exercise and breathing retraining programs address functional capacity preservation, with German statutory health insurance funding six-week inpatient pulmonary rehabilitation cycles.
Hospitals retain diagnostic gatekeeper status. Homecare is expanding most quickly as oral antifibrotic protocols mature.
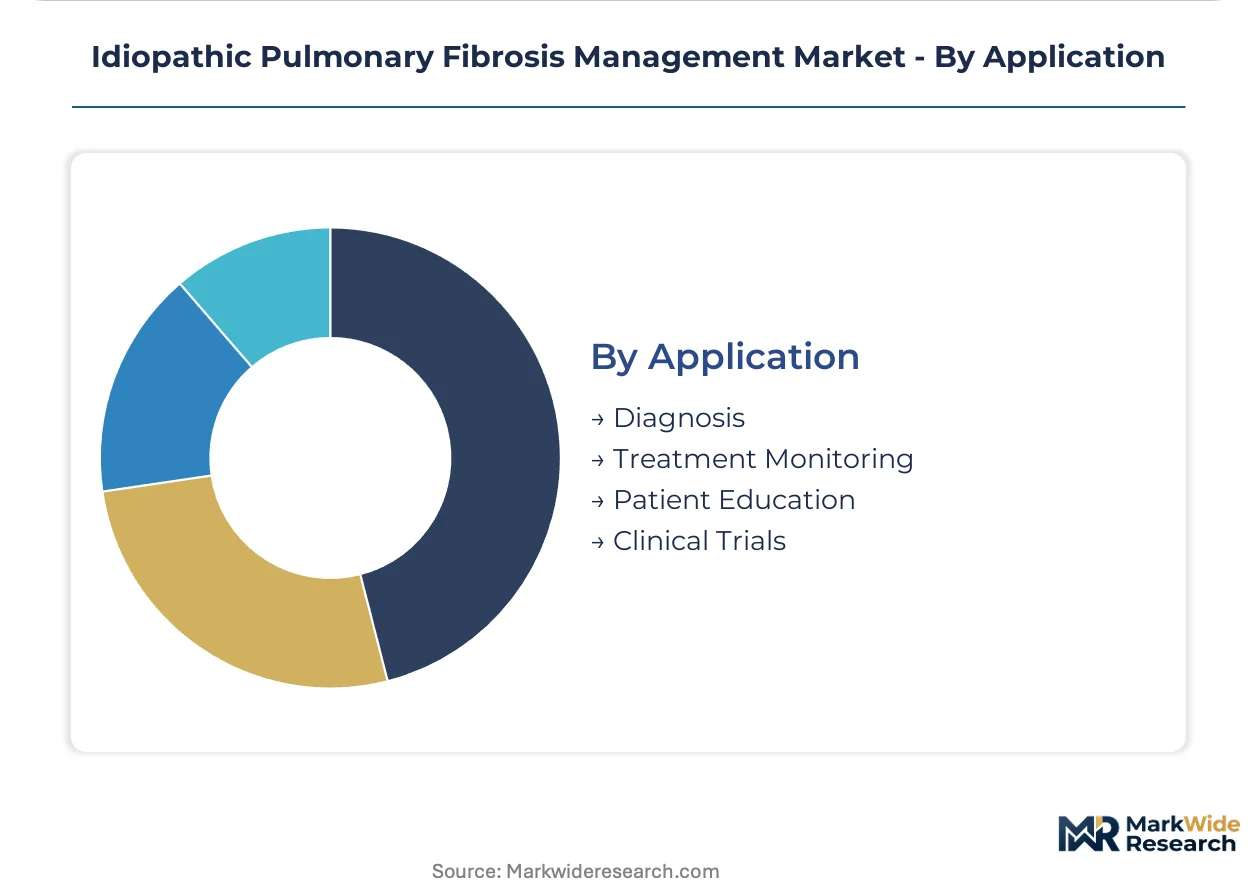
Application:
Maturity gradients separate established clinical workflows from emerging technology-enabled capabilities.
- Diagnosis:Multidisciplinary discussion boards integrating radiology, pathology, and pulmonology expertise render final IPF verdicts, with French reference centers mandating MDD consensus for antifibrotic reimbursement authorization.
- Treatment Monitoring:Forced vital capacity serial measurement and quantitative CT fibrosis scoring track therapeutic response, with AI-powered volumetric analysis displacing qualitative radiologist interpretation at Stanford and Heidelberg centers.
- Patient Education:Structured counseling on adverse event management and exacerbation warning signs improves adherence, delivered through nurse-led programs at Cleveland Clinic and Royal Brompton.
- Clinical Trials:Academic sites with established ILD registries dominate Phase II/III enrollment, with sponsors targeting rapid progressor biomarker-enriched populations.
Diagnosis commands fixed infrastructure investment. Treatment Monitoring is gaining share fastest through digital biomarker platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized antifibrotic formulations to United States transplant centers, while Japanese developers supply clinical trial materials to European academic networks. This trade corridor shapes how regulatory approvals synchronize across major prescriber markets.
United States
Medicare Part D coverage decisions and specialty pharmacy networks concentrate patient access in transplant referral hubs. The FDA's Division of Pulmonology maintains stringent survival endpoint requirements for novel agent approvals. Cleveland Clinic and University of California San Francisco anchor clinical trial enrollment for rapid progressor populations.
Germany
Statutory health insurance funds six-week inpatient pulmonary rehabilitation cycles with antifibrotic maintenance protocols. The EMA's Committee for Medicinal Products for Human Use applies distinct benefit-risk frameworks that influence multinational trial design. Heidelberg and Munich academic centers deploy AI-powered volumetric CT analysis for decentralized endpoint adjudication.
Japan
PMDA accelerated approval pathways compress development timelines for breakthrough kinase inhibitors. Post-marketing surveillance demonstrates higher adherence to oral nintedanib versus European cohorts. Tokyo and Osaka specialist centers pioneer biomarker-guided staging with genetic risk profiling integration.
United Kingdom
NHS England commissioning frameworks bundle antifibrotic costs within interstitial lung disease specialist networks. Royal Brompton and Harefield NHS Foundation Trust mandates multidisciplinary discussion consensus for treatment authorization. Specialist centers pilot inhaled pirfenidone formulations to mitigate gastrointestinal adverse events.
France
Reference center networks require multidisciplinary discussion consensus for antifibrotic reimbursement authorization. ANSM pharmacovigilance systems track real-world safety outcomes for EMA post-marketing obligations. Paris and Lyon academic pulmonology departments concentrate diagnostic workup through high-resolution CT and surgical lung biopsy protocols.
Idiopathic Pulmonary Fibrosis Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented prescriber networks where academic medical centers gatekeep antifibrotic initiation. The structure consolidates around established kinase inhibitor franchises and emerging CTGF platform developers. Two archetypes dominate: large-cap pharmaceutical incumbents with companion diagnostic infrastructure, and mid-cap biotechs pursuing inhalation delivery differentiation. Competitive moves center on biomarker-enriched trial enrollment and specialty pharmacy distribution partnerships.
Within the incumbent tier, Boehringer Ingelheim International GmbH and F. Hoffmann-La Roche Ltd occupy positions anchoring prescriber network presence through established oral antifibrotic regimens. Among platform developers, FibroGen Inc. represents the connective tissue growth factor inhibition archetype targeting late-stage clinical validation. These three entities exemplify how competitive positioning stratifies between mature franchise defense and novel mechanism validation.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche Ltd |
| FibroGen Inc. |
| Horizon Therapeutics plc |
| United Therapeutics Corporation |
| Bristol-Myers Squibb Company |
| Galapagos NV |
| Pliant Therapeutics Inc. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Air freight corridors connecting Frankfurt to Chicago and Tokyo to Los Angeles carry temperature-controlled biologics and active pharmaceutical ingredients with fuel surcharge indexation tied to Brent crude movements. These logistics cost dynamics concentrate pricing power among integrated manufacturers with captive cold-chain infrastructure while forcing smaller developers toward third-party logistics markups that compress margins on oral antifibrotic maintenance therapies.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers incorporate quarterly indexation to Indian and Chinese bulk chemical benchmarks. Pricing stratifies across branded kinase inhibitors, authorized generics, and compounded alternatives with differentiation driven by FDA therapeutic equivalence ratings and Medicare Part D tier placement. Cost compression in the generic pirfenidone segment is intensifying because of patent cliff dynamics across major markets. Community pulmonology practices exhibit highest price sensitivity due to reimbursement lag and inventory carrying costs, while transplant centers demonstrate lowest sensitivity given bundled payment structures.
Supply Chain Analysis
Contract manufacturing concentration rests with Lonza, Catalent, and Samsung Biologics for fill-finish and packaging of oral antifibrotic capsules. Active pharmaceutical ingredient production draws from India, China, and Switzerland for nintedanib intermediates and pirfenidone precursors. Supply chain risk centers on single-source dependencies for tyrosine kinase inhibitor starting materials subject to environmental regulatory enforcement in Zhejiang province. Distribution runs through three national specialty pharmacy networks under Medicare Part D mandates, displacing traditional hospital outpatient dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent antifibrotic franchises face substitution pressure from inhaled delivery platforms and connective tissue growth factor inhibitors that promise improved tolerability profiles. Defense of market position requires strategic repositioning around biomarker-guided patient stratification and channel control.
For Market Incumbents: Insulate oral kinase inhibitor franchises by embedding companion diagnostic infrastructure into prescriber workflows and securing exclusive specialty pharmacy distribution partnerships. Acquire or license rapid progressor biomarker platforms to preempt competitor enrollment in enriched trial populations. Deepen relationships with Cleveland Clinic and University of California San Francisco transplant hubs that gatekeeper antifibrotic initiation.
For New Entrants and Emerging Players: Inhalation delivery development programs targeting gastrointestinal adverse event mitigation represent the most penetrable entry point for differentiation against established oral regimens. United Kingdom specialist centers piloting nebulized formulations demonstrate receptive prescriber appetite for localized pulmonary deposition. Pursue EMA parallel scientific advice to synchronize FDA-EMA development timelines and reduce regulatory redundancy costs for multinational launch.
For Investors and Strategic Acquirers: Platform biotechs with Phase II CTGF inhibitor data and established inhalation device partnerships offer the most attractive acquisition target archetype for large-cap pharmaceutical incumbents seeking pipeline optionality. Long-term viability hinges on successful biomarker-enriched trial execution and payer willingness to premium-price tolerability advantages. Watch FDA Division of Pulmonology survival endpoint guidance revisions as the critical inflection signal for novel mechanism validation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Investment | Biomarker stratification accelerates enrollment efficiency and sharpens therapeutic timing precision. |
| Inhalation Delivery Platform Development | Localized pulmonary deposition opens differentiation pathways beyond oral kinase inhibitors with reduced systemic toxicity. |
| Specialty Pharmacy Distribution Partnership | Medicare Part D mandates concentrate fulfillment volume among three national networks. |
| EMA Parallel Scientific Advice Engagement | Coordinated FDA-EMA programs enable synchronized multinational launches reducing regulatory redundancy. |
| Real-World Evidence Infrastructure Buildout | Patient registry maintenance satisfies FDA and EMA post-marketing surveillance obligations. |
Research Methodology
A standing panel of ILD clinical trial investigators, specialty pharmacy operations directors, Medicare coverage policy specialists, and formulary access managers provided ongoing calibration throughout the study period. Primary interview data triangulated against FDA Division of Pulmonology guidance documents, EMA Committee for Medicinal Products for Human Use assessment reports, ClinicalTrials.gov enrollment records, and Medicare Part D formulary databases. Bottom-up patient-flow modeling and top-down therapeutic class expenditure analysis converged on segment-level estimates.
Scenario-bracketing around regulatory approval timing, generic entry assumptions, and biomarker adoption curves bounded the projection range across the analysis window. Segmentation dimensions modeled include product pharmacologic class, delivery mode, end-user site of care, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to diagnosed prevalent population estimates and treatment penetration assumptions, with antifibrotic therapy initiation rates and transplant referral patterns serving as key demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, statutory health insurance funding levels, or pharmaceutical tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding clinical trial success probabilities and regulatory pathway timelines. Quarterly review of FDA breakthrough therapy designation grants, EMA accelerated assessment pathway activations, and CMS national coverage determination schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market