
 Muscle Wasting Disorders Market | 2026-2036
Muscle Wasting Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Muscle Wasting Disorders Market Foresight
Specialty clinics is reorganizing procurement priorities for muscle wasting therapeutics, shifting volume toward integrated care models that combine pharmaceutical intervention with physical rehabilitation. Biogen leverages its established neuromuscular franchise to sustain R&D pipelines across multiple indications. Pfizer competes through manufacturing scale that anchors global supply chains for parenteral formulations. Cytokinetics specializes in cardiac muscle biology, differentiating its clinical focus from broader neuromuscular competitors.
Muscle wasting disorders encompass pathological loss of skeletal muscle mass and function arising from chronic disease, disuse, or primary neuromuscular pathology, with diagnostic criteria typically quantifying appendicular lean mass below two standard deviations of healthy population means via dual-energy X-ray absorptiometry or computed tomography. These conditions drive substantial clinical burden through reduced mobility, metabolic dysfunction, and elevated mortality risk across oncology, cardiology, and geriatric medicine. Pharmaceuticals commands the largest revenue pool given biologic pricing power and chronic administration requirements, while rehabilitation equipment represents the fastest-expanding segment as payors emphasize functional outcome metrics over pharmaceutical-only protocols. Nutritional supplements occupy a mature, fragmented tier where margin compression from private-label competition constrains branded growth.
FDA orphan drug incentives and EMA's priority medicines scheme jointly shape clinical trial investment, with accelerated review pathways rewarding developers addressing prevalence thresholds below specified patient populations. The EU MDR imposes stricter clinical evidence requirements on rehabilitation equipment, elevating compliance costs for device manufacturers seeking European market access. Stakeholders must monitor evolving CMS coverage determinations for combination therapy protocols, as reimbursement ambiguity around simultaneous pharmaceutical and device deployment threatens to constrain real-world adoption rates regardless of clinical efficacy signals.
Market Dynamics
Specialty clinics are consolidating muscle wasting therapeutic procurement around integrated care models that bundle pharmaceutical intervention with neuromuscular rehabilitation, compressing traditional siloed purchasing channels.
Growth Catalysts
- FDA Orphan Drug Designation:Accelerated review timelines and extended exclusivity periods incentivize biopharmaceutical investment in rare neuromuscular indications with small patient populations.
- Geriatric Oncology Expansion:Cancer centers are formalizing cachexia management protocols, creating dedicated revenue streams for muscle preservation therapeutics alongside chemotherapy regimens.
- Digital Biomarker Integration:Wearable accelerometry and smartphone-based functional assessments are decomposing reliance on episodic clinic visits for disease progression monitoring.
Market Restraints
- Biologic Manufacturing Concentration:Parenteral formulation production clusters among contract manufacturers in Switzerland and Ireland, exposing supply continuity to single-site disruption risks.
- EU MDR Compliance Burden:Stricter clinical evidence requirements for rehabilitation equipment elevate European market entry costs for device developers.
- Plasma-Derived Protein Volatility:Immunoglobulin and albumin input costs fluctuate with donor collection volumes, compressing margins for nutritional supplement formulators.
Strategic Opportunities
- Home-Based Rehabilitation:Remote therapeutic monitoring platforms enable payor-preferred site-of-care shifts for stable patients, bypassing facility-based reimbursement constraints.
- Cardiac-Muscle Crossover:Skeletal muscle biology insights from heart failure drug development are accelerating repurposing candidates for neuromuscular wasting conditions.
- Japan's SAKIGAKE Pathway:Priority review designation for regenerative medicines offers faster commercialization timelines for gene therapy developers targeting muscular dystrophies.
Industry Challenges
- Gene Therapy Manufacturing Scale-Up:Viral vector production capacity constraints limit batch sizes for AAV-based muscle-targeted treatments, extending patient wait times.
- Combination Therapy Reimbursement Coding:CMS lacks discrete billing mechanisms for simultaneous pharmaceutical and device deployment, forcing providers into administrative workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muscle Wasting Disorders Market |
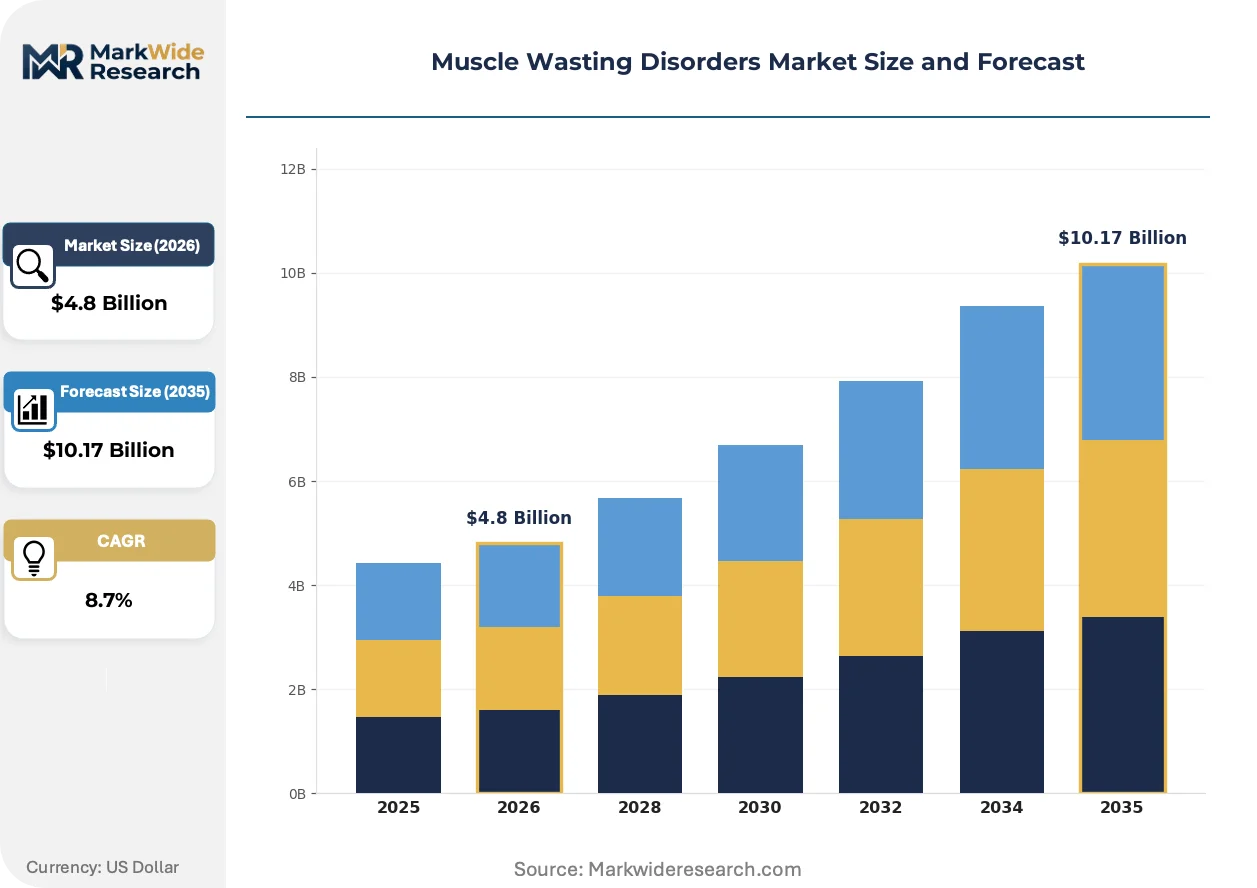
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Nutritional Supplements, Medical Devices, Rehabilitation Equipment End User: Hospitals, Specialty Clinics, Home Care, Rehabilitation Centers Therapy Area: Cancer Cachexia, Sarcopenia, Neuromuscular Disorders, Heart Failure Delivery Mode: Oral, Injectable, Intravenous, Transdermal |
| Companies Covered | Biogen, Pfizer, Eli Lilly, Cytokinetics, Scholar Rock, Regeneron Pharmaceuticals, Novartis, Keros Therapeutics, Roche Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muscle Wasting Disorders Market Shifts & Advancements
Muscle wasting therapeutics are converging with digital health infrastructure and precision medicine frameworks, reshaping how interventions are prescribed, monitored, and reimbursed across care settings.
RNA-targeted oligonucleotides are decomposing the traditional small-molecule dominance in neuromuscular drug development. Biogen and Ionis Pharmaceuticals have advanced antisense candidates through Phase III for spinal muscular atrophy variants, with specialty pharmacies now building cold-chain distribution capabilities for these temperature-sensitive biologics. The technology is decomposing historical barriers to addressing genetic root causes rather than symptomatic management.
The EU Medical Device Regulation imposes post-market surveillance mandates that force rehabilitation equipment manufacturers to maintain clinical registries. German and French notified bodies are applying stricter interpretations of biocompatibility testing for electromyography-triggered stimulation devices, extending certification timelines by 8-14 months. European distributors are responding by consolidating supplier relationships to reduce compliance fragmentation.
Payor contracts are increasingly conditioning reimbursement on six-minute walk test improvements rather than pharmaceutical adherence alone. UnitedHealth and CVS Caremark have piloted bundled payment models in Florida and Texas that tie provider compensation to functional outcome trajectories. This behavioral shift is most visible in Medicare Advantage plans, where star ratings now incorporate patient-reported mobility metrics.
Muscle Wasting Disorders Market Segmentation
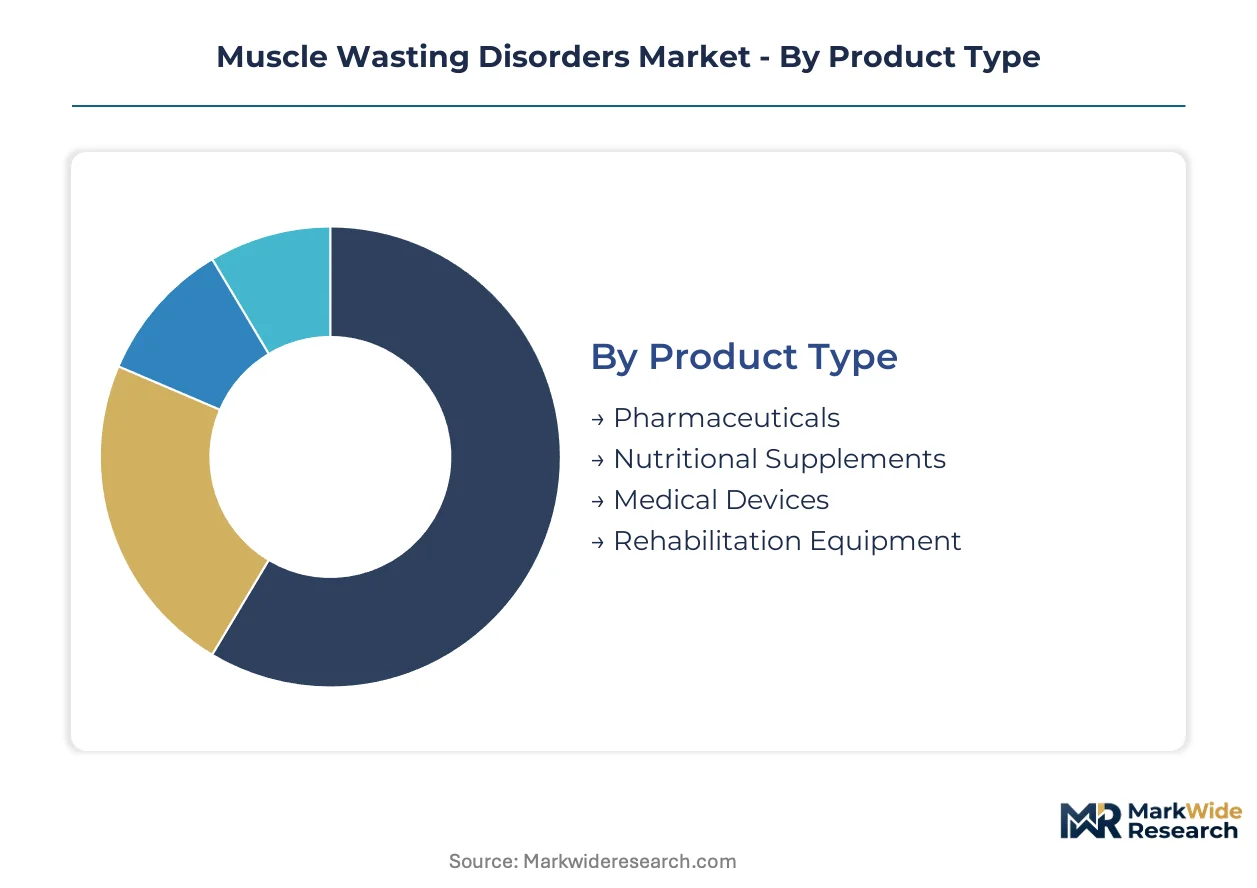
Muscle wasting therapeutics fragment across distinct value capture mechanisms, with biologic pricing power, care setting economics, and disease-specific reimbursement pathways determining where margin pools concentrate. Understanding these segment boundaries clarifies where capital deployment yields sustainable returns versus commodity exposure.
Product Type:
Margin pools concentrate in chronic administration categories where patent protection and manufacturing complexity sustain pricing power, while equipment segments face faster commoditization pressure.
- Pharmaceuticals:Biologic and small-molecule formulations targeting myostatin inhibition, selective androgen receptor modulation, and appetite stimulation command premium pricing through orphan drug designation. Demand clusters in United States specialty pharmacy channels where Medicare Part D and commercial payor contracts anchor reimbursement stability for parenteral biologics.
- Nutritional Supplements:Branched-chain amino acid formulations, HMB derivatives, and protein-fortified medical foods occupy a crowded competitive landscape. German and Japanese reimbursement authorities apply stricter clinical evidence standards than FDA medical food pathways, compressing margin expansion in regulated European and Asian markets.
- Medical Devices:Electromyography sensors and neuromuscular electrical stimulation units serve diagnostic and therapeutic monitoring functions.
- Rehabilitation Equipment:Resistance training systems, body-weight support treadmills, and robotic exoskeletons face EU MDR compliance cost escalation.
The dominant share belongs to Pharmaceuticals, while Rehabilitation Equipment is closing the gap fastest as bundled payment models reward functional outcome improvements.
End User:
Procurement authority is shifting toward sites of care where payor contracts increasingly condition reimbursement on documented functional gains rather than service volume alone.
- Specialty Clinics:Neuromuscular centers and geriatric oncology units are consolidating muscle wasting therapeutic procurement around integrated care models. United States-based networks like the Muscular Dystrophy Association care centers combine pharmaceutical dispensing with on-site physical therapy, capturing margin from both drug distribution and professional service billing.
- Hospitals:Inpatient oncology and cardiology departments administer acute cachexia interventions during chemotherapy or post-surgical recovery episodes. CMS's hospital outpatient prospective payment system creates reimbursement ceiling constraints that limit adoption of higher-cost combination therapy protocols in United States acute care settings.
- Home Care:Skilled nursing visits and remote therapeutic monitoring platforms are expanding as Medicare Advantage plans favor site-of-care shifts.
- Rehabilitation Centers:Post-acute facilities face staffing shortages that constrain intensive neuromuscular program scalability.
Specialty Clinics capture the highest margin per patient encounter, though Home Care is expanding most quickly as remote monitoring technology matures.
Therapy Area:
Prevalence thresholds and regulatory pathway availability determine addressable market size, with rare disease designations enabling faster development timelines but constraining volume.
- Cancer Cachexia:Systemic inflammation-driven muscle loss affects advanced oncology populations across solid tumor types. United States cancer centers are formalizing dedicated cachexia management protocols, creating parallel revenue streams for muscle preservation therapeutics alongside chemotherapy administration in academic medical centers.
- Sarcopenia:Age-related muscle decline in geriatric populations lacks unified diagnostic criteria across regulatory jurisdictions. Japan's Ministry of Health, Labour and Welfare has advanced specific sarcopenia reimbursement codes faster than CMS, making Japanese geriatric care facilities an earlier adoption market for targeted interventions.
- Neuromuscular Disorders:Spinal muscular atrophy, Duchenne muscular dystrophy, and amyotrophic lateral sclerosis represent genetically defined populations eligible for orphan drug incentives.
- Heart Failure:Cardiac cachexia overlaps with skeletal muscle wasting biology, enabling drug repurposing from cardiovascular development pipelines.
Cancer Cachexia holds the largest addressable population, yet Neuromuscular Disorders is gaining share fastest through gene therapy pipeline expansion.
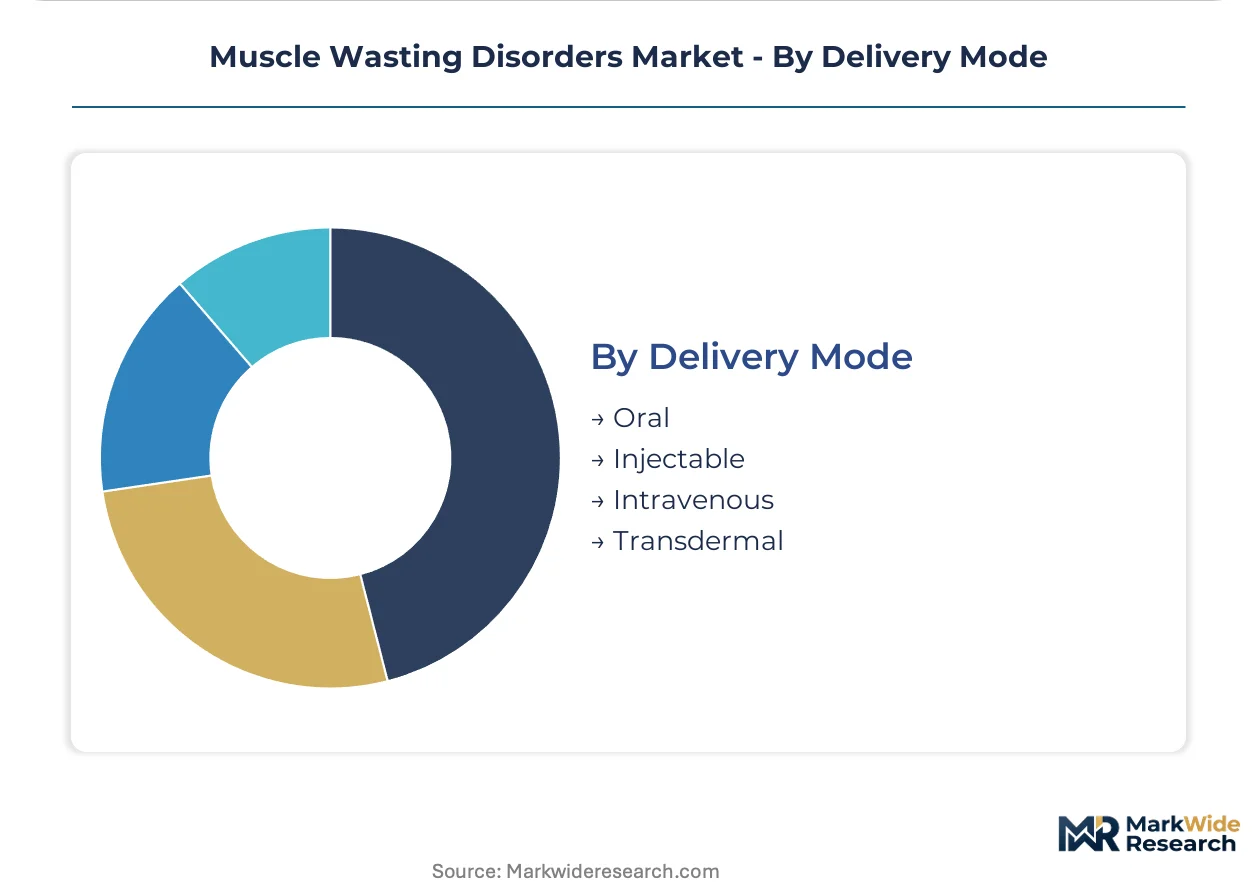
Delivery Mode:
Route of administration dictates manufacturing investment requirements, cold-chain infrastructure, and patient compliance economics across chronic disease management.
- Injectable:Subcutaneous biologics including monoclonal antibodies and antisense oligonucleotides require specialty pharmacy distribution networks. Cold-chain logistics providers in Switzerland and Ireland have concentrated capacity for temperature-sensitive parenteral formulations, creating supply bottleneck risks for AAV-based gene therapies.
- Oral:Small-molecule appetite stimulants and selective androgen receptor modulators offer patient convenience advantages in chronic administration scenarios. FDA's streamlined approval pathway for drugs addressing unmet medical needs in serious conditions has accelerated oral formulation development timelines relative to European EMA processes.
- Intravenous:Hospital-administered biologics and nutritional support solutions require infusion center infrastructure.
- Transdermal:Patch-based hormone delivery and iontophoresis systems remain limited by skin permeability constraints for large-molecule therapeutics.
Injectable formulations dominate revenue concentration, while Oral delivery is climbing fastest as patient preference drives formulation development priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland exports parenteral biologics to United States specialty pharmacy networks, anchoring transatlantic supply chains for temperature-sensitive muscle wasting therapeutics. Cold-chain logistics providers in Basel and Zurich coordinate batch releases for North American distribution.
United States
Medicare Advantage plans in Florida and Texas pilot bundled payments tying provider compensation to six-minute walk test improvements. FDA orphan drug designation accelerates timelines for spinal muscular atrophy candidates. Boston's biotech corridor concentrates antisense oligonucleotide development, with specialty pharmacies building cold-chain infrastructure for temperature-sensitive distribution.
Germany
Notified bodies in Berlin and Munich apply stricter EU MDR interpretations for electromyography-triggered stimulation devices, extending certification timelines. German cancer centers formalize dedicated cachexia management protocols alongside chemotherapy regimens. The Rhine-Ruhr industrial region hosts rehabilitation equipment manufacturers consolidating supplier relationships to reduce compliance fragmentation.
Japan
Japan's Ministry of Health, Labour and Welfare advanced sarcopenia reimbursement codes faster than CMS, making Japanese geriatric care facilities an earlier adoption market. METI's SAKIGAKE pathway offers priority review designation for regenerative medicines targeting muscular dystrophies. The Kansai region around Osaka concentrates gene therapy manufacturing investments for AAV-based muscle-targeted treatments.
Switzerland
Swissmedic regulates biologic manufacturing concentration in Basel and Geneva, where contract manufacturers anchor global supply chains for parenteral formulations. Swiss plasma collection volumes fluctuate, compressing margins for immunoglobulin-dependent nutritional supplements. The Lake Geneva biotech cluster specializes in monoclonal antibody production for neuromuscular indications.
United Kingdom
NHS England coverage determinations for combination therapy protocols create reimbursement ambiguity around simultaneous pharmaceutical and device deployment. The MHRA operates under retained EU law post-Brexit, maintaining alignment with EMA orphan drug incentive structures. London's academic medical centers combine pharmaceutical dispensing with on-site physical therapy, capturing margin from integrated care models.
Muscle Wasting Disorders Market Competitive Landscape
Player mix skews toward diversified biopharmaceutical conglomerates with established neuromuscular franchises. The vendor base concentrates around three strategic archetypes: gene therapy developers leveraging viral vector platforms, antisense oligonucleotide specialists with ionis partnerships, and cardiac muscle biology researchers repurposing heart failure insights. Dominant competitive moves include strategic partnerships for cold-chain distribution capabilities and portfolio diversification into rare disease adjacent indications.
Within the diversified biopharmaceutical tier, Biogen, Pfizer, and Cytokinetics occupy positions reflecting distinct strategic emphases. Biogen exemplifies the neuromuscular franchise archetype through its established spinal muscular atrophy presence. Pfizer represents scale-driven manufacturing concentration anchoring global parenteral supply chains. Cytokinetics sits within the cardiac-skeletal muscle crossover specialization, differentiating clinical focus from broader neuromuscular competitors. Eli Lilly, Regeneron Pharmaceuticals, and Novartis occupy adjacent positions in appetite stimulation and inflammation modulation, while Roche Holding AG and Scholar Rock represent European and emerging-player archetypes respectively.
| Leading Market Players |
|---|
| Biogen |
| Pfizer |
| Eli Lilly |
| Cytokinetics |
| Scholar Rock |
| Regeneron Pharmaceuticals |
| Novartis |
| Keros Therapeutics |
| Roche Holding AG |
| Others |
Supply & Pricing Matrix
Ninety-day cold-chain inventory buffers for parenteral biologics concentrate pricing power with Swiss and Irish contract manufacturers, while plasma-derived input volatility feeds directly into nutritional supplement margin compression across tiered buyer segments.
Pricing Analysis
Next-generation antisense oligonucleotides command premium positioning against legacy small-molecule appetite stimulants and prior-generation myostatin inhibitors. Three-tier pricing structure across orphan-designated biologics, standard-of-care pharmaceuticals, and private-label nutritional supplements reflects FDA certification tier and manufacturing complexity. Pricing pressure stems from EU MDR compliance cost escalation for rehabilitation equipment manufacturers. Hospital procurement committees exhibit highest price sensitivity due to CMS reimbursement ceiling constraints, while specialty clinics absorb premium pricing for integrated care bundles.
Supply Chain Analysis
Switzerland and Ireland anchor parenteral biologic manufacturing, with Basel and Dublin facilities feeding United States specialty pharmacy networks. Viral vector production for AAV-based gene therapies draws from Kansai-region manufacturing investments, while plasma collection for immunoglobulin formulations rests on Swiss and Austrian donor volumes. Single-source vulnerability concentrates in cold-chain logistics providers for temperature-sensitive antisense oligonucleotides. Distribution runs through integrated specialty pharmacy channels that combine drug dispensing with professional service billing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Muscle wasting therapeutics are cycling through post-pandemic normalization as deferred neuromuscular diagnoses rebound and cancer center patient volumes recover toward pre-disruption baselines.
For Market Incumbents: Secure viral vector manufacturing capacity through captive production or exclusive contract manufacturing agreements to preempt AAV supply bottlenecks. Lock in long-term plasma supply contracts with Austrian and Swiss collection networks before donor volume volatility intensifies. FDA orphan drug exclusivity windows remain the priority lever for margin defense against biosimilar encroachment. For New Entrants and Emerging Players: Japan's SAKIGAKE priority review pathway offers fastest commercialization timelines for regenerative medicine developers targeting muscular dystrophies. Home-based rehabilitation monitoring platforms represent the most penetrable white-space segment as Medicare Advantage plans accelerate site-of-care shifts. Lead with digital biomarker integration to differentiate from facility-based incumbent protocols. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because gene therapy manufacturing scarcity and antisense oligonucleotide cold-chain infrastructure will concentrate value in platform-integrated mid-caps. Target developers with Phase II-ready cardiac-skeletal muscle crossover candidates. Watch for FDA breakthrough therapy designation announcements as inflection signals for acquisition premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated review timelines compress development risk for spinal muscular atrophy candidates. |
| Cold-Chain Infrastructure Investment | Specialty pharmacy networks in Boston and Basel build temperature-controlled distribution for antisense oligonucleotides. |
| Integrated Care Model Deployment | Neuromuscular centers capture margin from combined pharmaceutical dispensing and physical therapy billing. |
| Gene Therapy Manufacturing Scale-Up | AAV viral vector capacity constraints in Kansai region limit batch sizes and extend patient wait times. |
| Digital Biomarker Platform Development | Wearable accelerometry enables payor-preferred remote monitoring for stable muscle wasting patients. |
Research Methodology
Desk research of FDA orphan drug filings, EMA priority medicines submissions, and ClinicalTrials.gov neuromuscular trial registries preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors at United States payors, and hospital procurement managers. Secondary validation drew from CMS Medicare data, GPO contracts, and specialty pharmacy distribution records. Bottom-up patient population estimates and top-down therapeutic class revenue assessments underwent cross-triangulation.
Variance decomposition across therapy area, delivery mode, and end-user setting informed analytical framework construction over the projection horizon. Segmentation dimensions modeled included administration route, patient population prevalence tier, and regional regulatory cluster designation. CAGRs derived from historical growth rate patterning and pipeline probability-adjusted revenue forecasting. Forecast inputs incorporated gene therapy manufacturing capacity buildout timelines and EU MDR certification backlog projections.
Decision-makers should treat outputs as directional under assumptions of stable FDA orphan drug incentive structures and continued Medicare Advantage bundled payment expansion; material deviation in CMS coverage determinations or viral vector production breakthroughs would warrant model refresh. Recalibration cycles align with material shifts in regulatory pathway availability and gene therapy manufacturing yield improvements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market