
 Dermatomyositis Treatment Market | 2026-2036
Dermatomyositis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatomyositis Treatment Market Intelligence
Revenue from targeted biologic therapies is fragmenting the traditional market's reliance on broad-spectrum immunosuppressants. This shift creates new value pools for companies mastering novel mechanisms of action. Pfizer leverages its extensive immunology research and development capabilities. Argenx specializes in antibody-based therapies targeting specific autoimmune pathways, while Novartis positions its portfolio to address a wide range of inflammatory conditions.
Dermatomyositis treatment encompasses therapies designed to manage the autoimmune-mediated inflammation of muscles and skin. These treatments often involve immunomodulatory agents that target specific cytokines or B-cell pathways to suppress the aberrant immune response. Biologics represent the highest-margin product segment due to their specificity and development costs. Intravenous delivery remains a primary mode for these advanced therapies, with administration concentrating in specialty clinics and rheumatology centers.
Regulatory pathways like the US FDA's orphan drug designation and the EMA's PRIME scheme are critical for market entry. These frameworks provide incentives and expedited reviews for therapies addressing rare diseases like dermatomyositis. The ability to navigate these distinct regulatory processes in the United States, Europe, and Japan dictates the speed of commercialization for new treatments. Future market share will be determined by the strategic choice between incremental improvements and disruptive therapeutic platforms.
Market Dynamics
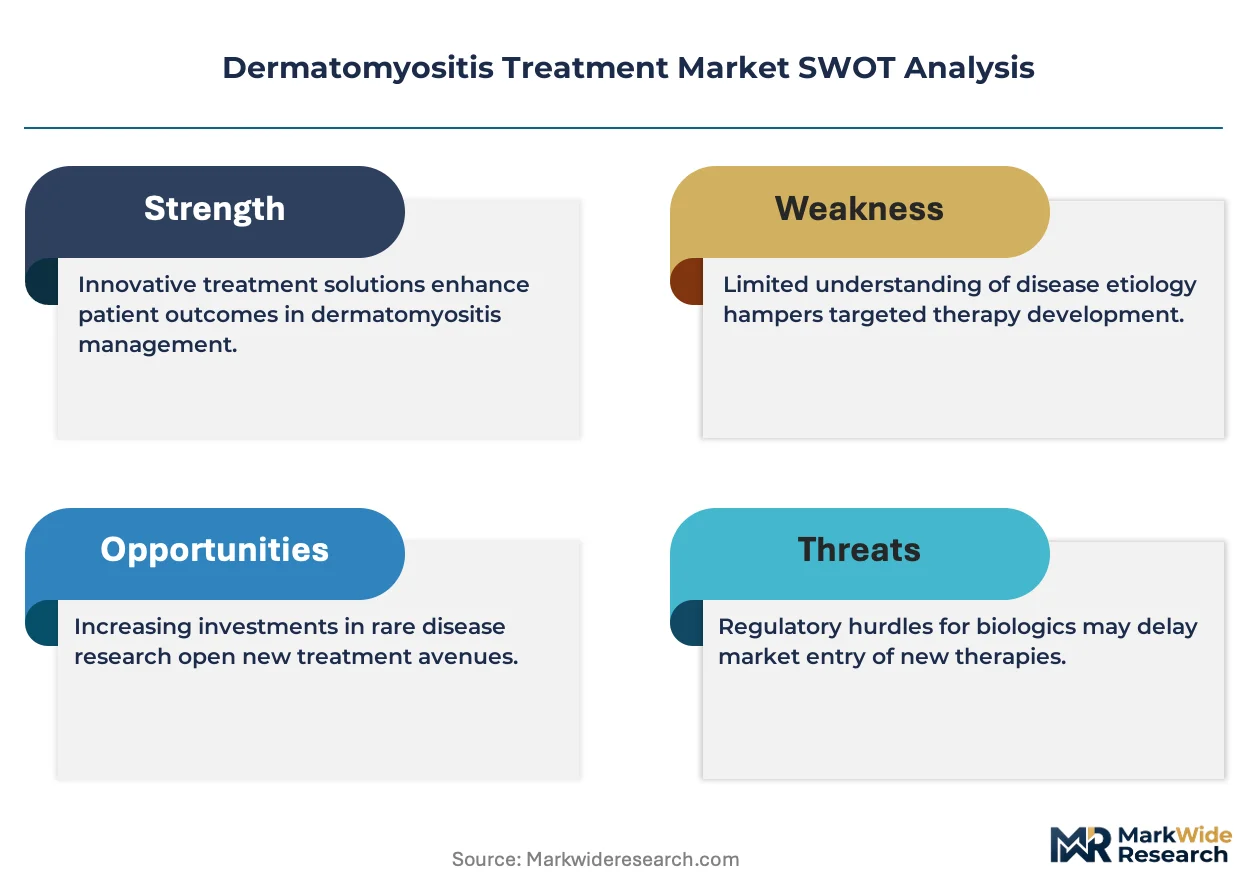
The central force shaping the dermatomyositis treatment market is the technological shift from broad-spectrum immunosuppressants to targeted biologic therapies. This transition fragments the market landscape, creating distinct value pools around novel mechanisms of action that target specific autoimmune pathways.
Growth Catalysts
- Regulatory Incentives:Frameworks like the FDA's orphan drug designation and the EMA's PRIME scheme provide expedited review pathways and market exclusivity, lowering barriers for therapies targeting rare diseases like dermatomyositis.
- Advancements in Immunology:A deeper understanding of cytokine and B-cell pathways enables the development of highly specific monoclonal antibodies and small molecules, improving efficacy and safety profiles over traditional treatments.
- Concentrated Research Ecosystems:The United States, with its robust biopharmaceutical research infrastructure and influential patient advocacy networks, drives significant investment and accelerates clinical trial recruitment for new dermatomyositis therapies.
Market Restraints
- High Treatment Costs:The significant research, development, and manufacturing costs associated with biologic therapies translate to high prices, limiting patient access and creating reimbursement hurdles for healthcare systems.
- Disease Heterogeneity:Dermatomyositis presents with diverse clinical and serological subtypes, making it difficult for a single targeted therapy to achieve efficacy across the entire patient population, thus complicating clinical trial design.
- Specialized Administration Requirements:The reliance on intravenous infusions for many advanced biologics restricts treatment to specialty clinics and hospitals, creating access and logistical barriers for patients in rural or underserved areas.
Strategic Opportunities
- Subcutaneous Formulations:Developing subcutaneous delivery methods for existing or new biologics presents a major opportunity to improve patient convenience, reduce healthcare system burden, and expand treatment outside of specialized infusion centers.
- Underserved Patient Subtypes:Targeting therapies toward specific, genetically or serologically defined patient subgroups with high unmet needs offers a clear path for clinical development and regulatory approval.
- Expansion in Asia-Pacific:Increasing healthcare expenditure and improving diagnostic capabilities in countries like Japan and South Korea create opportunities for market entry, especially for therapies with established safety records in Western markets.
Industry Challenges
- Clinical Trial Recruitment:The rarity of dermatomyositis makes recruiting a statistically significant number of patients for pivotal Phase III trials a persistent operational challenge, often requiring multi-national, multi-center study designs.
- Complex Regulatory Navigation:Successfully commercializing a new therapy requires navigating the distinct and evolving regulatory requirements of the FDA in the US, the EMA in Europe, and the PMDA in Japan simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatomyositis Treatment Market |
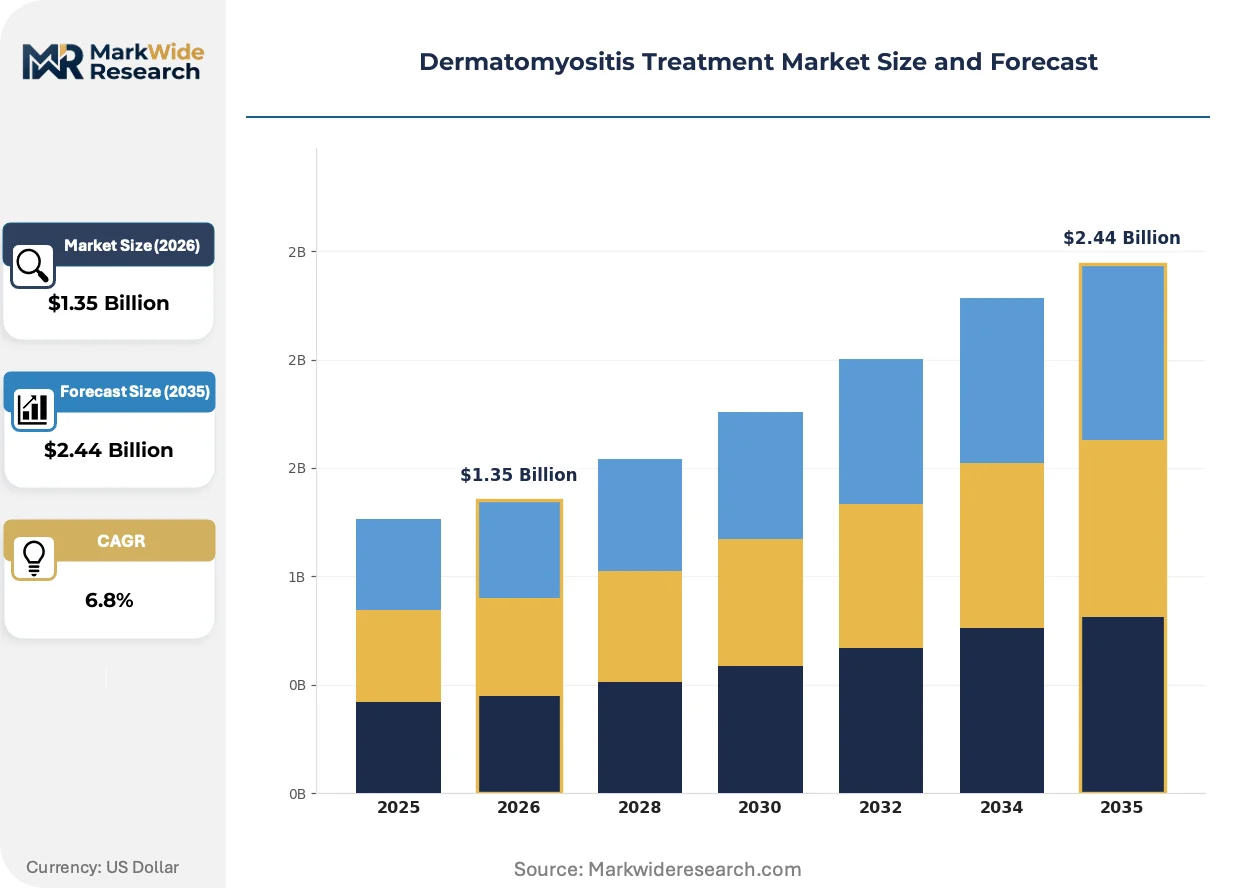
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Corticosteroids, Intravenous Immunoglobulin, Biologics, Anti-inflammatory Agents Therapy Area: Muscle Inflammation, Skin Rash, Lung Involvement, Joint Pain, Dysphagia End User: Specialty Clinics, Neurology Centers, Rheumatology Hospitals, Dermatology Clinics, Rehabilitation Facilities Delivery Mode: Oral, Injectable, Intravenous, Topical, Subcutaneous |
| Companies Covered | Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Bristol Myers Squibb Company, Argenx, Priovant Therapeutics, AstraZeneca Plc., CSL Behring, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatomyositis Treatment Market Strategic Shifts & Innovations
The evolution of dermatomyositis treatment is defined by a move toward precision medicine. This involves leveraging molecular diagnostics to tailor therapies and integrating patient-centric endpoints into clinical development, shifting focus from broad immunosuppression to personalized care pathways.
Companion diagnostics are increasingly used to identify patient subsets most likely to respond to a specific targeted therapy. Clinical research organizations and biopharmaceutical firms are rapidly adopting these biomarker platforms in late-stage trials to improve success rates. This technology is digitizing patient stratification, moving the process from reliance on clinical presentation to a more precise, molecular-level analysis for treatment selection.
Europe's regulatory environment is shaped by the EMA's PRIority MEdicines (PRIME) scheme, which offers enhanced support for drugs targeting unmet needs. This framework accelerates the assessment of promising therapies, potentially shortening the path to market authorization for innovative dermatomyositis treatments. Developers of novel biologics for severe disease are most affected, aligning clinical trial designs with PRIME criteria to gain early dialogue with regulators.
Patient advocacy groups are exerting greater influence on the design of clinical trials, particularly regarding the selection of study endpoints. This change promotes the inclusion of patient-reported outcomes, such as fatigue, pain, and quality-of-life metrics, alongside traditional clinical measures. This behavioral shift is most prominent in the United States, where strong patient networks collaborate directly with researchers and regulatory bodies.
Dermatomyositis Treatment Market Segmentation
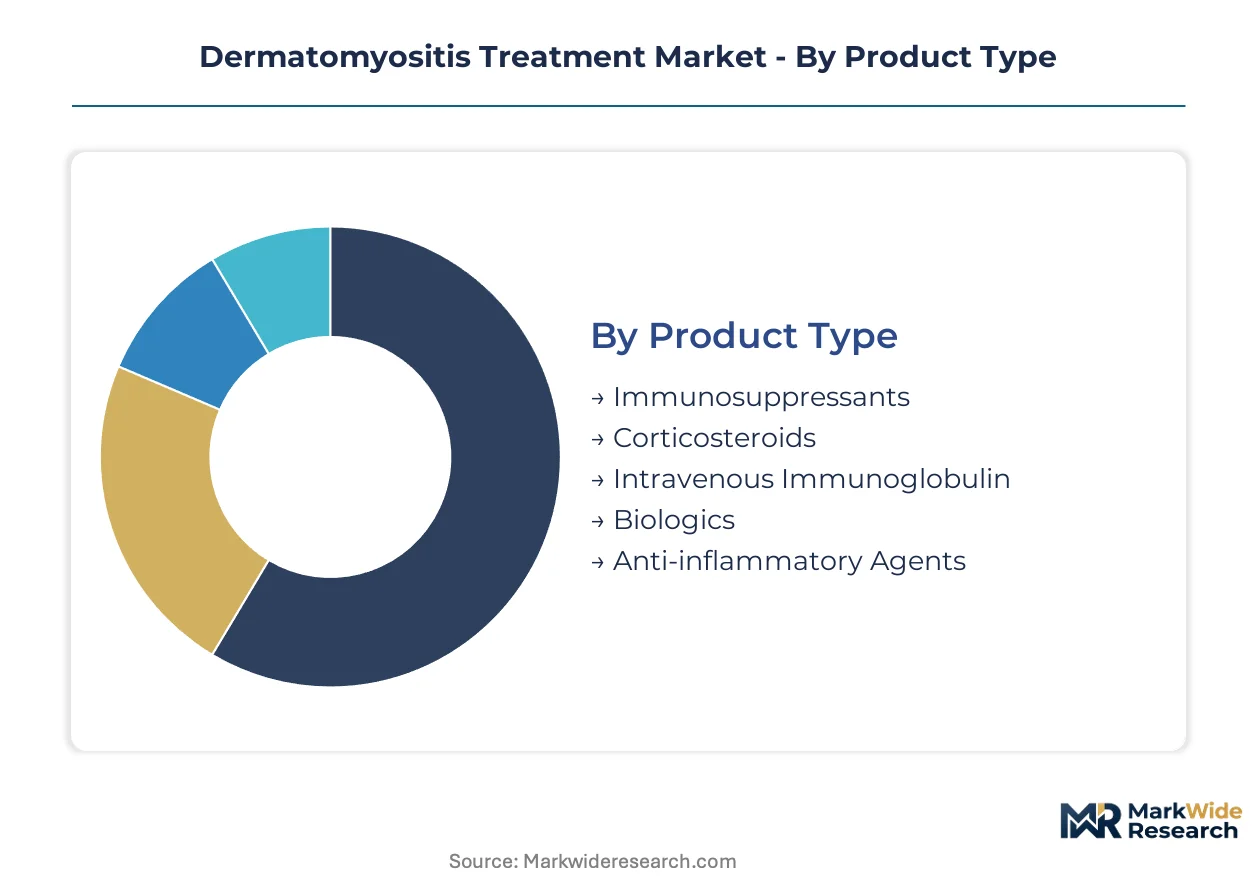
Segmentation provides a granular view of the dermatomyositis treatment market, dissecting it by product types, therapy areas, end-users, and delivery modes. This analysis helps stakeholders understand the evolving landscape of patient care and identify areas of unmet clinical need. Each segment reflects distinct therapeutic approaches and operational considerations for market participants.
Product Type:
The dermatomyositis treatment market categorizes therapies across a diverse use-case spectrum, addressing various disease mechanisms.
- Biologics:These advanced therapies are genetically engineered proteins that target specific immune pathways, such as cytokines or B-cell receptors, to modulate the aberrant immune response. Demand concentrates in the United States, driven by significant biopharmaceutical research and a willingness for high-value treatments.
- Immunosuppressants:These broad-spectrum agents, including methotrexate and azathioprine, reduce overall immune system activity to control inflammation and prevent tissue damage. Their demand remains substantial across Europe due to established clinical guidelines and lower acquisition costs compared to newer biologics.
- Corticosteroids:Potent anti-inflammatory drugs like prednisone are often first-line treatments for acute flares, rapidly suppressing immune activity.
- Intravenous Immunoglobulin:IVIG therapy involves administering pooled human antibodies to modulate the immune system, particularly for refractory cases.
- Anti-inflammatory Agents:Non-steroidal anti-inflammatory drugs (NSAIDs) address pain and inflammation, providing symptomatic relief for patients.
Established volume favors Immunosuppressants; emerging adoption favors Biologics.
Therapy Area:
Therapy area segmentation reflects the specific patient needs and clinical manifestations requiring targeted interventions.
- Muscle Inflammation:This core manifestation involves autoimmune-mediated damage to muscle fibers, leading to weakness and fatigue, requiring therapies to restore muscle function. Treatment strategies often focus on systemic immunomodulation in rheumatology hospitals.
- Skin Rash:Characterized by distinct erythematous rashes, particularly on sun-exposed areas, this symptom significantly impacts patient quality of life and often requires topical and systemic treatments. Dermatology clinics manage a large portion of these cases.
- Lung Involvement:Interstitial lung disease is a serious complication requiring aggressive immunosuppression to prevent progressive fibrosis.
- Joint Pain:Arthralgia and arthritis can occur, necessitating anti-inflammatory or immunomodulatory approaches for symptomatic relief.
- Dysphagia:Difficulty swallowing due to muscle weakness in the pharynx and esophagus requires specialized management to prevent aspiration.
Therapeutic strategies increasingly differentiate based on Muscle Inflammation while Lung Involvement requires specialized interventions.
End User:
End-user segmentation highlights the specialized healthcare settings where dermatomyositis treatment is administered.
- Rheumatology Hospitals:These specialized facilities manage complex autoimmune conditions, providing comprehensive diagnostic services, advanced therapeutic options, and multidisciplinary care for dermatomyositis patients. They represent a primary hub for initiating and monitoring biologic therapies.
- Specialty Clinics:Offering focused expertise in autoimmune and inflammatory diseases, specialty clinics provide advanced diagnostics and administer complex treatments, including intravenous infusions. Patient access to these clinics is crucial for ongoing management.
- Dermatology Clinics:These clinics focus on skin manifestations, providing diagnostic biopsies and managing topical and systemic treatments for cutaneous symptoms.
- Neurology Centers:Neurologists may manage patients with significant muscle weakness or neurological complications associated with dermatomyositis.
- Rehabilitation Facilities:These centers assist patients in regaining muscle strength and functional independence through physical and occupational therapy.
The demand for advanced therapies primarily routes through Rheumatology Hospitals and Specialty Clinics.
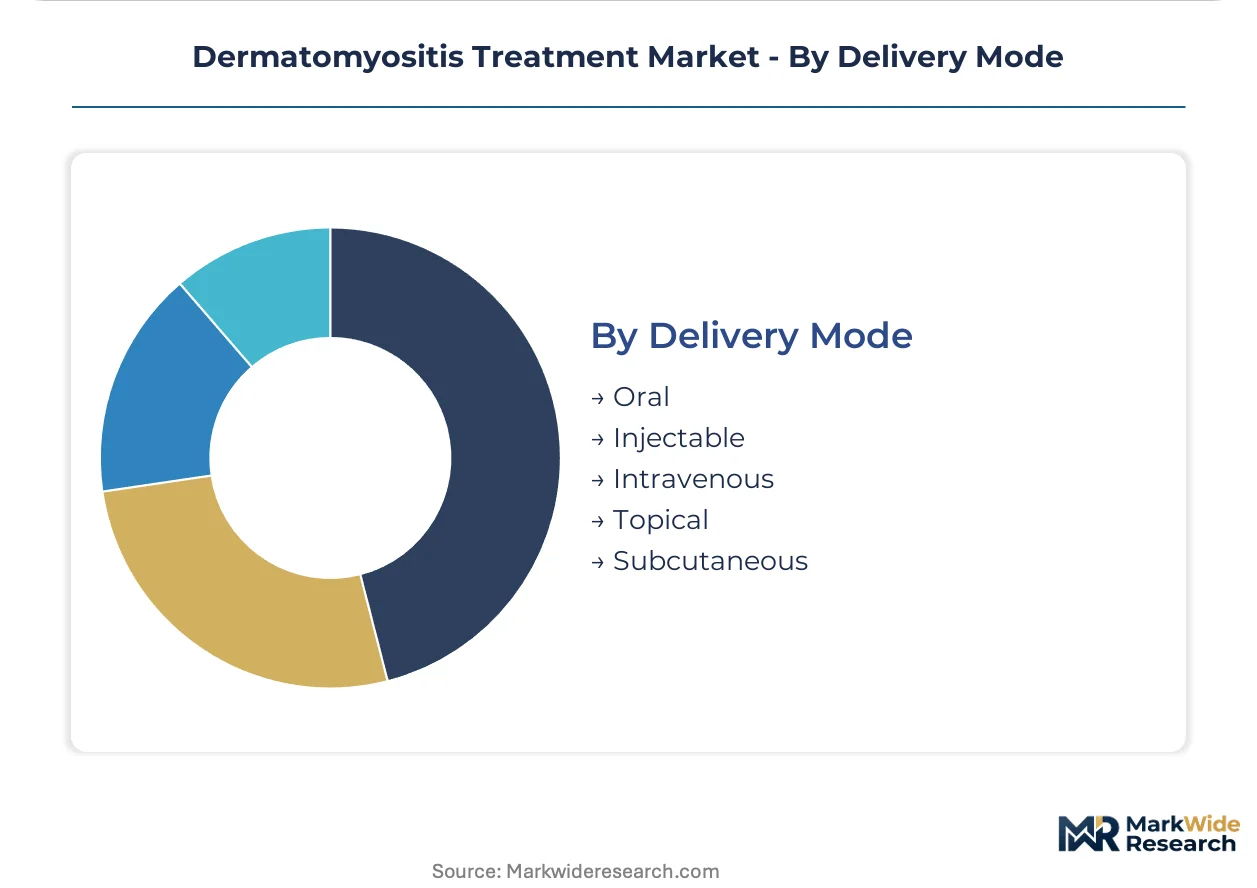
Delivery Mode:
Delivery mode segmentation considers patient convenience, therapeutic efficacy, and administration logistics for various treatments.
- Intravenous:This mode involves direct infusion into a vein, ensuring rapid systemic distribution and high bioavailability, commonly used for biologics and IVIG in hospital settings. It remains a primary mode for advanced therapies requiring precise dosing.
- Subcutaneous:Administered as an injection under the skin, this mode offers increased patient convenience and the potential for self-administration, reducing the burden on healthcare facilities. Development of subcutaneous formulations for biologics is a strategic opportunity.
- Oral:Medications taken by mouth offer ease of administration and are common for corticosteroids and many immunosuppressants.
- Injectable:This category encompasses intramuscular and subcutaneous injections, providing systemic drug delivery outside of intravenous access.
- Topical:Applied directly to the skin, topical agents primarily treat cutaneous manifestations, minimizing systemic side effects.
Patient preference for Subcutaneous delivery is growing, while Intravenous delivery remains critical for acute management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for dermatomyositis treatments varies significantly across geographies. Markets with established public healthcare systems and restrictive formularies often exhibit higher price sensitivity for advanced biologics, while regions with robust private insurance models readily adopt high-value therapies.
United States
The United States drives significant demand for dermatomyositis treatments due to its advanced healthcare infrastructure and high adoption of novel therapies. Robust biopharmaceutical research and influential patient advocacy networks accelerate clinical trial recruitment. The FDA's orphan drug designation provides critical incentives and expedited review pathways for innovative treatments. Major biotech hubs in Boston and San Francisco are centers for developing and commercializing targeted immunotherapies.
Germany
Germany's healthcare system supports a strong market for dermatomyositis treatments, particularly within its well-established rheumatology centers. High healthcare expenditure facilitates access to both traditional immunosuppressants and newer biologics. The EMA's PRIME scheme, with Germany as a key member state, accelerates the assessment of promising therapies. Pharmaceutical research clusters in cities like Munich and Berlin contribute to European innovation in autoimmune disease management.
Japan
Japan's aging population and sophisticated medical technology infrastructure generate consistent demand for effective dermatomyositis therapies. The country's strong commitment to rare disease research supports the development of specialized treatments. The PMDA's expedited review pathways facilitate rapid market entry for drugs addressing unmet medical needs. Tokyo and Osaka remain critical centers for pharmaceutical innovation and clinical research in immunology.
India
India represents an emerging market for dermatomyositis treatments, driven by increasing healthcare access and a growing awareness of autoimmune conditions. The demand for affordable therapeutic options remains substantial across the country. The CDSCO focuses on ensuring drug availability and promoting local manufacturing capabilities. Hyderabad and Bengaluru are developing into significant biopharmaceutical hubs, attracting investment in clinical research.
Dermatomyositis Treatment Market Key Industry Players
Targeted biologic innovators and established pharmaceutical giants split the dermatomyositis treatment market. The landscape is characterized by a tiered structure, with specialized biotechnology firms focusing on novel mechanisms and larger pharmaceutical companies leveraging extensive R&D pipelines. Strategic partnerships for pipeline expansion and geographic market penetration represent dominant competitive moves.
Within the diversified pharmaceutical archetype, Pfizer Inc. and Novartis AG exemplify companies with broad immunology portfolios. These firms leverage extensive research capabilities to develop both small molecules and biologics for various inflammatory conditions. Argenx represents a specialized biotechnology firm, focusing on antibody-based therapies for specific autoimmune pathways. These companies occupy positions across the therapeutic spectrum, from traditional immunosuppression to highly targeted biologic interventions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Bristol Myers Squibb Company |
| Argenx |
| Priovant Therapeutics |
| AstraZeneca Plc. |
| CSL Behring |
| Abbott |
| Others |
Cost & Logistics Intelligence
Single-source dependency for complex biologics determines both pricing tier spreads and the overall supply chain shape within the dermatomyositis treatment market. This reliance on specialized manufacturing facilities and proprietary processes creates significant barriers to entry and influences market access.
Pricing Analysis
The continuous prescription of high-value biologics drives lifetime value for manufacturers in dermatomyositis treatment. Value-based pricing models dominate for novel targeted therapies, while established immunosuppressants operate on more transactional, per-unit pricing. Price differentiation stems from clinical efficacy, specificity of the therapeutic target, and orphan drug designation status. Pricing pressure arises from healthcare system budget constraints, particularly for high-cost biologics. Payers and national health systems represent the most price-sensitive buyers, balancing efficacy with overall treatment cost.
Supply Chain Analysis
Specialized contract development and manufacturing organizations (CDMOs) in the United States and Europe hold significant capacity for biologic production. The supply chain for dermatomyositis treatments concentrates geographically, with active pharmaceutical ingredient (API) manufacturing also prominent in India and China. Raw material dependencies include specialized cell lines and purification reagents for biologics, alongside specific chemical precursors for small molecule immunosuppressants. Single-source vulnerability for proprietary biologic components poses a structural supply chain risk. Distribution runs through specialized pharmaceutical distributors and direct-to-hospital or specialty clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dermatomyositis treatment market is experiencing a cyclical recovery, driven by renewed investment in targeted therapies and a deeper understanding of disease pathophysiology.
For Market Incumbents: Build intellectual property moats around novel mechanisms of action to defend against emerging biosimilars. Diversify treatment pipelines by acquiring specialized assets addressing distinct dermatomyositis subtypes. Leverage regulatory navigation expertise to secure expedited approvals for innovative therapies, mitigating the threat of disruptive gene therapies. Invest in R&D for next-generation precision medicine approaches.
For New Entrants and Emerging Players: Asia-Pacific represents a geographic underpenetration for advanced dermatomyositis therapies, offering significant growth opportunities. Target underserved patient subtypes, such as those with specific serological markers or severe interstitial lung disease, where unmet needs remain high. Focus on developing subcutaneous delivery methods to enhance patient convenience and expand market reach. Leverage orphan drug designation pathways for expedited market entry.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized biopharmaceutical firms with late-stage assets and proven clinical efficacy. Long-term viability remains strong due to the chronic nature of dermatomyositis and the shift towards precision medicine. Identify acquisition targets with robust intellectual property portfolios and strong regulatory track records. Clinical trial success for novel immunomodulatory targets is a critical signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Advancing Phase III trials for novel biologics validates efficacy and secures future market share for specialized firms. |
| Regulatory Approval Pathway | Expediting FDA and EMA approvals ensures rapid market entry and patient access for innovative dermatomyositis treatments. |
| Pipeline Diversification | Expanding therapeutic portfolios across different mechanisms of action reduces reliance on single-product success for large pharmaceutical companies. |
| Manufacturing Scale-Up | Increasing production capacity for complex biologics addresses growing demand and reduces potential supply chain bottlenecks. |
| Licensing Agreement | Securing partnerships for regional distribution expands geographic reach and commercialization opportunities for emerging biotechs. |
Research Approach
A spread of perspectives from rheumatologists, dermatology specialists, regulatory affairs leads, and patient advocacy group representatives converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were triangulated with extensive secondary validation from sources including FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed medical journals. This approach ensured a comprehensive bottom-up and top-down assessment of market dynamics.
The demand-supply-balance framing informed the quantitative analytical framework applied over the projection horizon. Segmentation dimensions modeled include product type, therapy area, end-user, delivery mode, and regional regulatory cluster. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected market dynamics, incorporating key industry-specific forecast inputs such as new drug approvals and patient prevalence rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized biopharmaceutical firms or large pharmaceutical conglomerates would shift outcomes. Forecasts reflect assumptions regarding clinical trial success rates and evolving regulatory landscapes. Quarterly review of new drug approvals and patient advocacy initiatives is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Immunology Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Global Cancer Immunotherapies Market