
 Subdural Haematoma Market | 2026-2036
Subdural Haematoma Market Size, Share, and Industry Trends Forecast 2026-2036
Subdural Haematoma Market Intelligence
A capital-intensity divergence between integrated neurosurgical device manufacturers and standalone pharmaceutical suppliers is bifurcating competitive returns in the Subdural Haematoma Market. Medtronic Plc leverages its vertically integrated cranial technologies portfolio to anchor premium pricing across neurocritical care settings. Integra LifeSciences Corporation specializes in regenerative tissue matrices and dural repair platforms that differentiate its position in surgical intervention workflows. Stryker Corporation competes through instrument and navigation ecosystems that sustain recurring revenue attachments in hospital operating rooms.
Subdural haematoma denotes an accumulation of blood between the dura mater and arachnoid membrane, typically arising from torn bridging veins following head trauma or cerebral atrophy in elderly patients, with mass effect and intracranial pressure elevation as primary pathophysiological concerns. The condition demands urgent intervention to prevent neurological deterioration, herniation, or mortality. Surgical intervention commands the dominant share of procedural value, while neurocritical care represents the fastest-growing segment as monitoring intensity and bundled payment models expand. Medication categories, particularly anticoagulation reversal agents and osmotherapy, occupy mature margin pools with limited pricing flexibility.
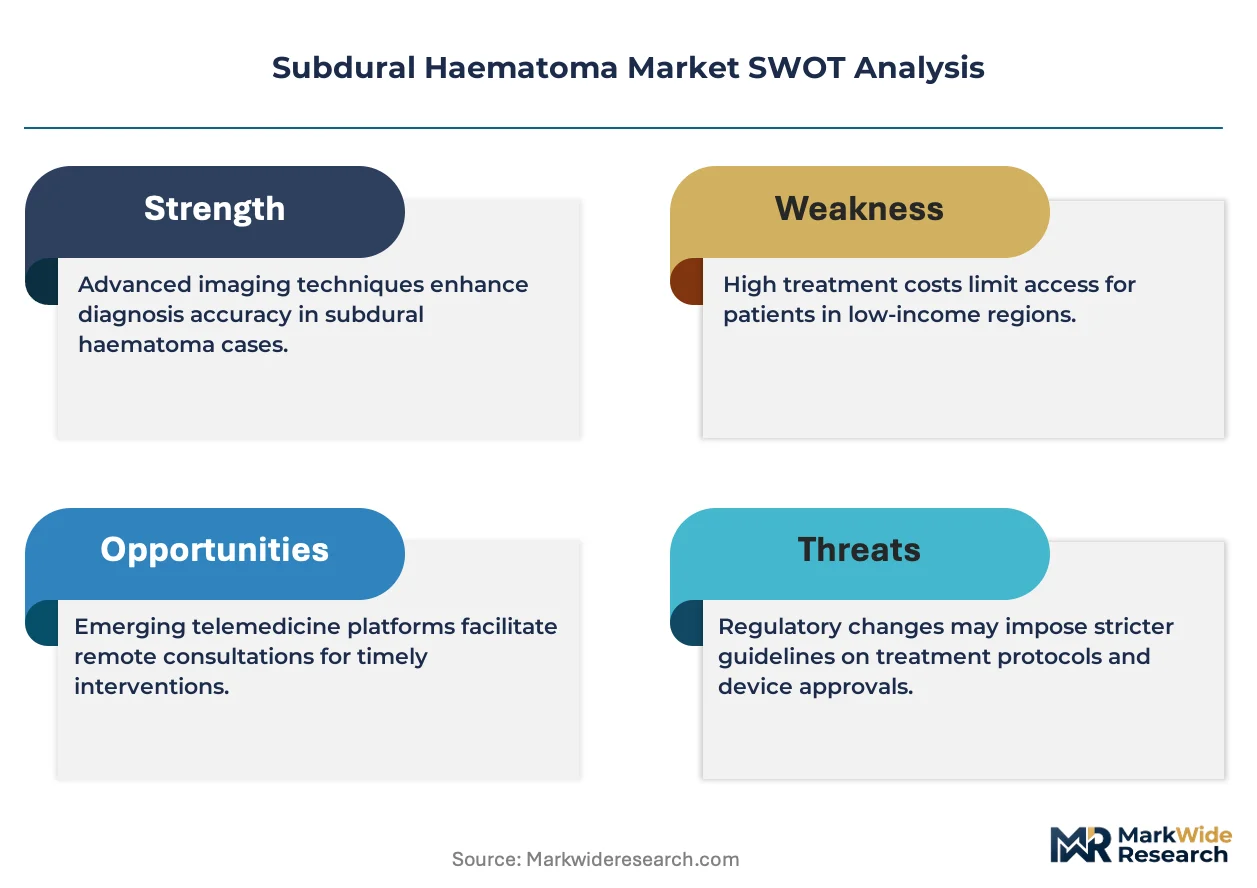
FDA premarket notification pathways for Class II cranial access devices, combined with EU MDR technical documentation requirements for implantable neurological products, elevate compliance costs and extend time-to-market for new entrants. The EU AI Act introduces additional scrutiny for algorithm-assisted diagnostic tools used in haematoma detection and volume quantification. Stakeholders must monitor evolving reimbursement thresholds for minimally invasive evacuation procedures versus conventional craniotomy, as coverage decisions will reshape capital allocation across product development portfolios.
Market Dynamics
EU MDR technical documentation requirements for implantable neurological products are compressing time-to-market for cranial drainage systems and forcing portfolio rationalization among mid-tier device manufacturers.
Growth Catalysts
- Aging demographics in OECD markets:Trauma center density in the United States sustains procedural volumes for chronic subdural haematoma evacuation as elderly populations expand.
- CE marking pathway tightening:EU MDR post-market surveillance mandates elevate quality thresholds for cranial access devices, filtering out marginal competitors and concentrating share among qualified suppliers.
- Neurocritical care bundling:Tertiary hospitals in Germany and the United Kingdom are consolidating monitoring intensity into standardized care pathways that expand device attach rates.
Market Restraints
- Polymer supply concentration:Medical-grade silicone for drainage catheters concentrates among German and US specialty chemical suppliers, exposing device manufacturers to input cost volatility.
- Anticoagulation reversal agent commoditization:Generic idarucizumab and andexanet alfa equivalents are eroding margin pools in pharmaceutical intervention categories.
- Technical limitation in minimally invasive evacuation:Recurrence rates for twist-drill craniostomy without membrane excision limit adoption in high-acuity cases requiring definitive intervention.
Strategic Opportunities
- Underpenetrated neurocritical care in India:CDSCO streamlined medical device registration pathways are opening access for cranial pressure monitoring systems in tier-2 city hospitals.
- Algorithm-assisted diagnostic convergence:Machine learning volume quantification tools paired with portable CT imaging are creating point-of-care detection capabilities outside radiology departments.
- Japan METI innovation procurement:PMDA breakthrough designation pathways for novel haematoma evacuation devices accelerate reimbursement listing for qualifying technologies.
Industry Challenges
- Neurocritical care specialist scarcity:Fellowship-trained intensivist recruitment bottlenecks in the United States and United Kingdom constrain capacity expansion for high-acuity monitoring units.
- EU MDR notified body capacity:Technical documentation review queues for Class III neurological implants extend certification timelines by 12-18 months beyond historical norms.
- Legacy EMR integration friction:Device data streams from intracranial pressure monitors require custom HL7 FHIR mapping to interface with hospital information systems, delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subdural Haematoma Market |
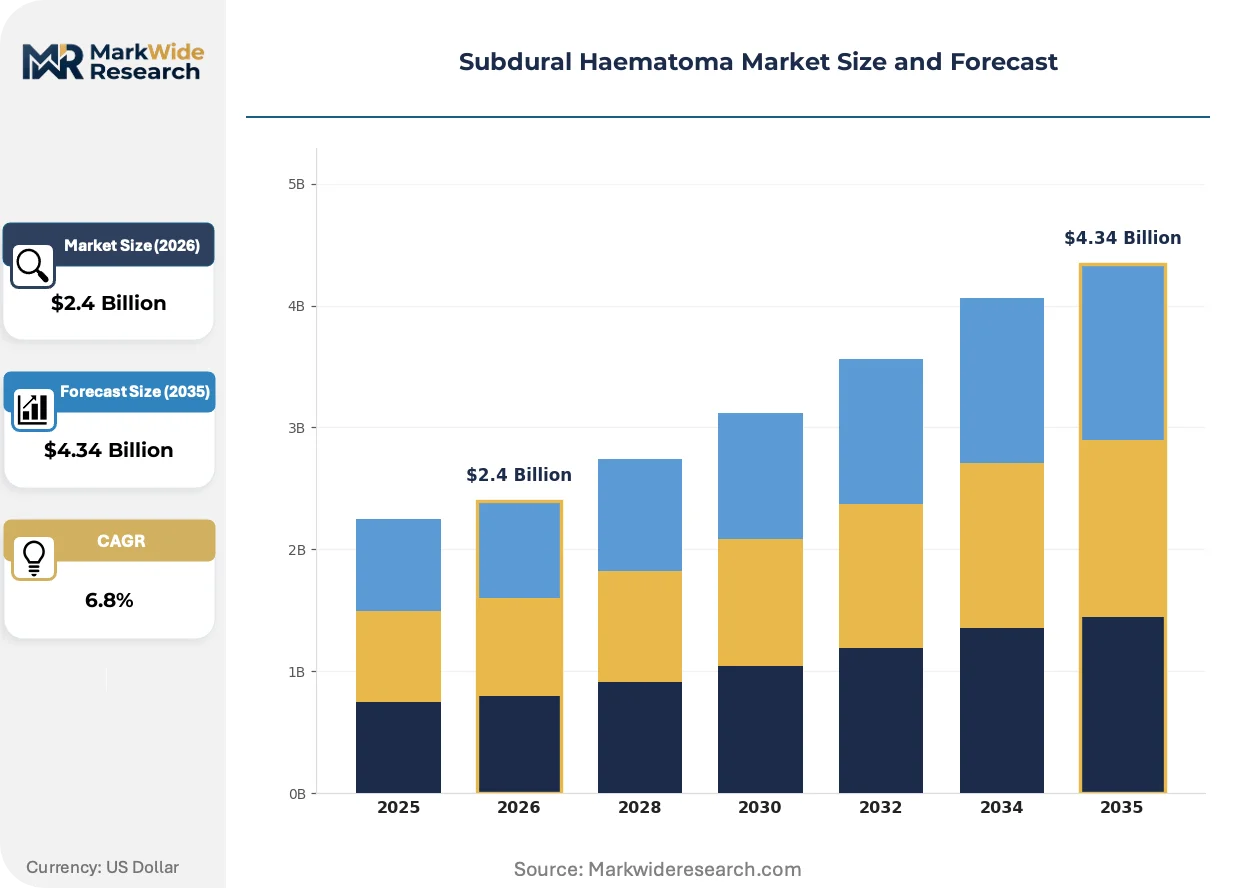
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conservative Treatment, Surgical Intervention, Medication, Neurocritical Care End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Long-term Care Facilities Delivery Mode: Intravenous, Oral, Inhalation, Topical Severity Level: Mild, Moderate, Severe, Critical |
| Companies Covered | Medtronic Plc, Integra LifeSciences Corporation, Stryker Corporation, Johnson & Johnson, B. Braun Melsungen AG, Smith & Nephew Plc, Baxter, Novartis AG, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subdural Haematoma Market Strategic Shifts & Innovations
Minimally invasive surgical platforms and algorithmic diagnostic tools are fragmenting the traditional craniotomy-centered intervention model while regulatory complexity reshapes competitive qualification barriers.
Middle meningeal artery embolization is decomposing the surgical intervention hierarchy for chronic subdural haematoma by offering catheter-based occlusion as an alternative to burr-hole drainage. Interventional neuroradiology departments in tertiary US and German hospitals are adopting the technique for recurrent cases. The technology is decomposing volume concentration among neurosurgical service lines and redistributing procedural economics toward angiography suites.
EU AI Act risk classification for algorithm-assisted diagnostic tools is imposing conformity assessment obligations on haematoma detection software that previously operated under lighter medical device frameworks. Manufacturers must now maintain post-market performance monitoring systems and algorithm change control protocols. The regulation most heavily affects European radiology AI vendors and is driving restructuring of quality management systems ahead of enforcement deadlines.
Hospital procurement committees are consolidating vendor relationships for cranial technologies into single-source contracts that bundle drainage systems, monitoring devices, and navigation platforms. Integrated neurosurgical device manufacturers capture preference through total cost-of-ownership guarantees. The United States exhibits the most pronounced concentration, with IDN purchasing organizations in Texas and California leading contract standardization efforts.
Subdural Haematoma Market Segmentation
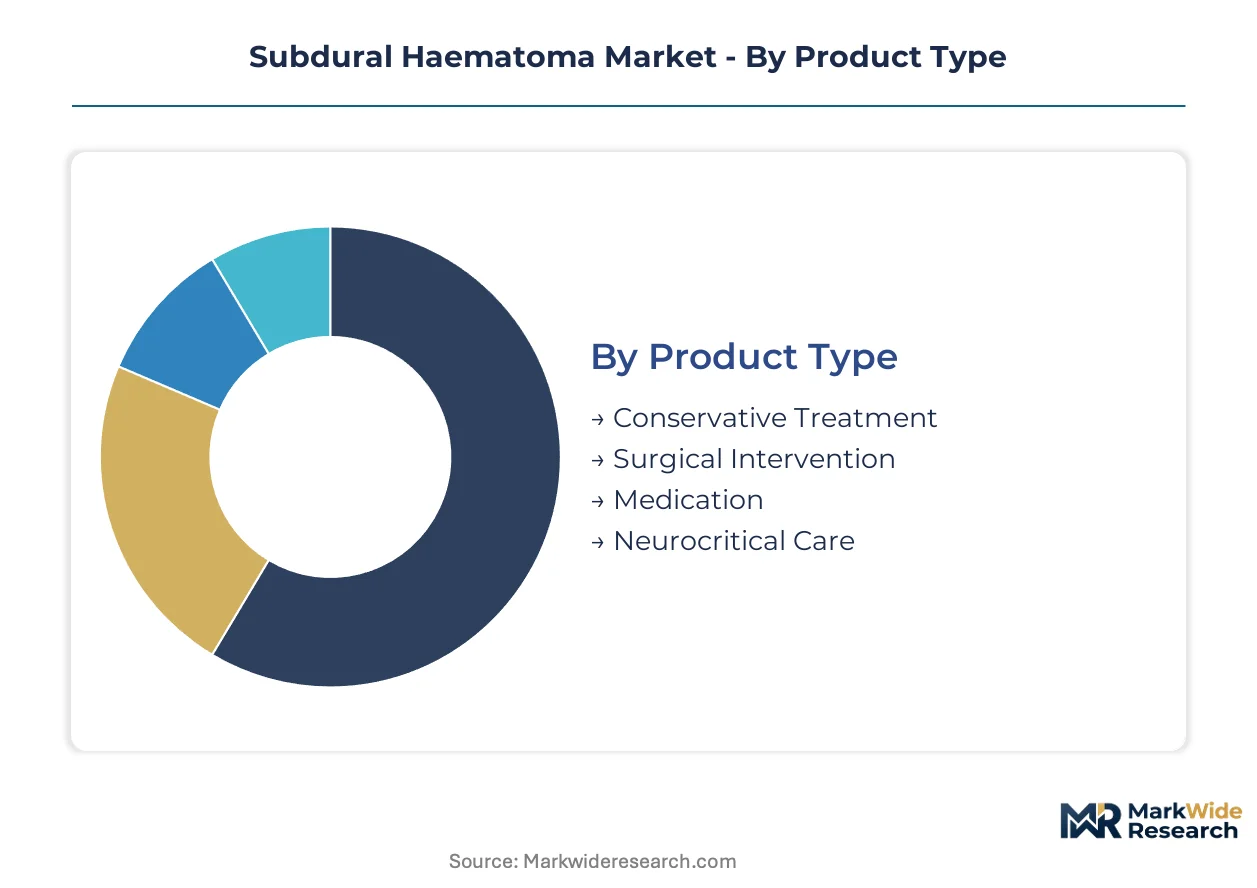
Subdural haematoma intervention spans acute surgical rescue, prolonged neurocritical monitoring, and pharmaceutical stabilization. Segmentation reveals where capital equipment, consumable drainage systems, and drug therapies compete for procedural economics and hospital procurement budgets.
Product Type:
Minimally invasive embolization techniques and algorithm-assisted monitoring platforms are displacing conventional craniotomy in select chronic cases, reshaping substitution dynamics across intervention categories.
- Surgical Intervention:Burr-hole drainage and craniotomy with membrane excision remain the definitive standard for acute and recurrent presentations. Tertiary trauma centers in the United States sustain the highest procedural volumes as aging populations expand eligible cohorts.
- Neurocritical Care:Intracranial pressure monitoring and ventilated support systems command premium attach rates in bundled payment environments. German and United Kingdom tertiary hospitals are consolidating these capabilities into standardized care pathways.
- Conservative Treatment:Observation protocols with serial imaging predominate in mild presentations and high-surgical-risk patients.
- Medication:Anticoagulation reversal agents and osmotic diuretics occupy mature margin pools with limited pricing flexibility.
Surgical Intervention retains volume leadership; Neurocritical Care holds the steepest expansion curve.
End User:
Site-of-care economics concentrate high-acuity intervention in centralized facilities while post-acute recovery disperses across lower-cost settings.
- Hospitals:Academic medical centers and designated trauma centers capture complex evacuations and neurocritical capacity. United States hospital networks are consolidating cranial technology procurement into single-source vendor contracts.
- Outpatient Clinics:Follow-up imaging and anticoagulation management for stable chronic cases concentrate in ambulatory neurology practices.
- Rehabilitation Centers:Post-surgical functional recovery and cognitive rehabilitation extend the care continuum outside acute settings.
- Long-term Care Facilities:Elderly residents with anticoagulation therapy represent a high-incidence detection population requiring rapid transfer protocols.
Hospitals dominate procedural value capture; Long-term Care Facilities generate the fastest-growing detection demand.
Delivery Mode:
Route selection follows acuity and intervention type, with intravenous administration anchoring emergency reversal and critical care.
- Intravenous:Idarucizumab and andexanet alfa for anticoagulation reversal, plus hypertonic saline and mannitol for osmotherapy, demand immediate vascular access in emergency departments.
- Oral:Maintenance anticoagulation management and corticosteroid tapers transition patients to outpatient protocols.
- Inhalation:Ventilatory support in neurocritical care units employs inhaled agents for sedation and pulmonary management.
- Topical:Surgical site preparation and wound care applications accompany cranial access procedures.
Intravenous dominates acute intervention; Oral routes expand most quickly in post-discharge management.
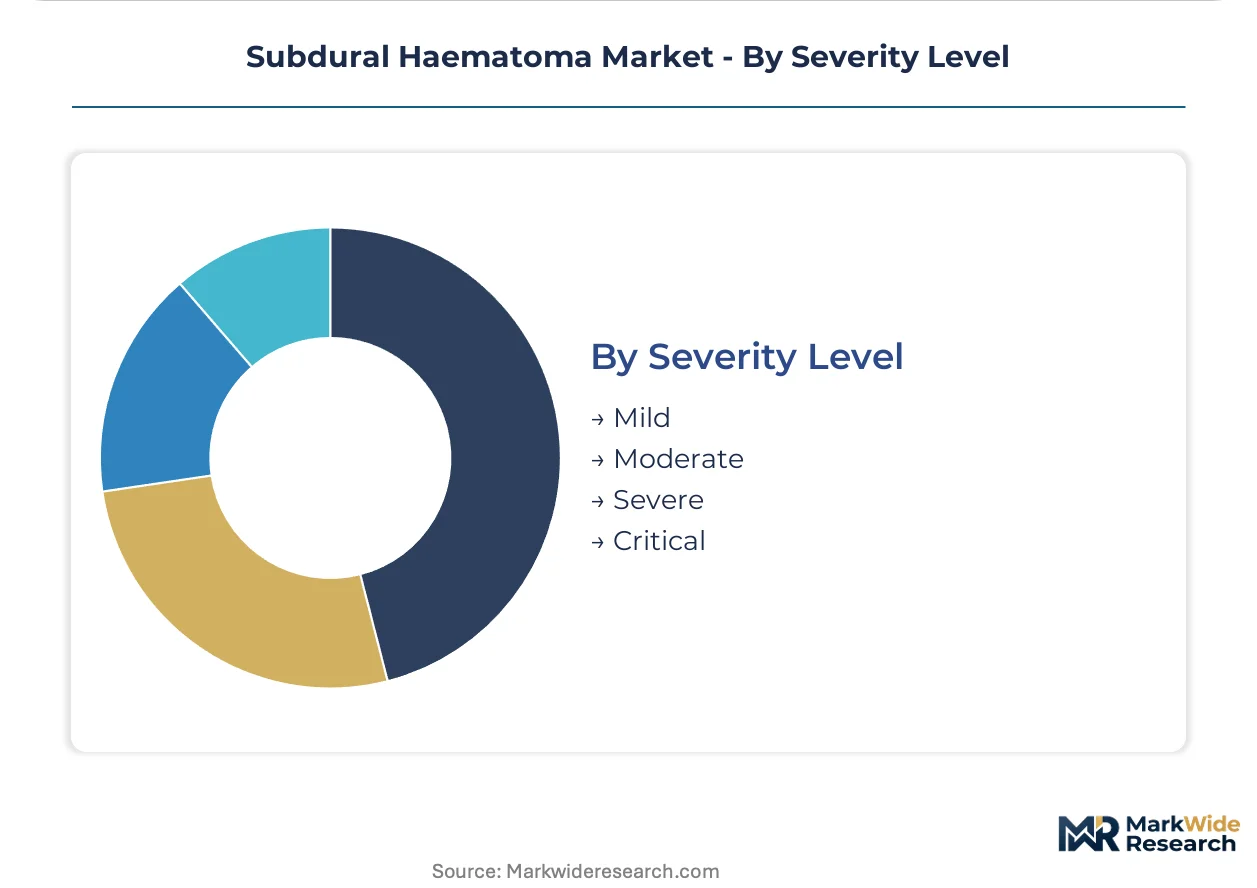
Severity Level:
Clinical stratification drives intervention intensity and reimbursement tiering across the care pathway.
- Severe:Coma, pupillary asymmetry, and significant midline shift mandate emergent surgical decompression. These presentations concentrate procedural value and mortality risk.
- Critical:Herniation signs and refractory intracranial hypertension require combined surgical and intensive medical management with highest resource consumption.
- Mild:Small volume collections with minimal mass effect permit conservative management with serial observation.
- Moderate:Neurological deficit without imminent herniation risk allows individualized surgical versus medical decision-making.
Severe presentations concentrate intervention economics; Critical cases demand the most rapid capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers absorb premium pricing for integrated neurosurgical systems, while Indian and Chinese procurement committees prioritize cost efficiency in drainage catheter selection.
United States
Trauma center density and aging demographics sustain the highest procedural volumes for chronic subdural haematoma evacuation. FDA premarket notification pathways for Class II cranial access devices shape device qualification timelines. Academic medical centers in Texas and California anchor single-source vendor contract consolidation for bundled cranial technologies.
Germany
Tertiary hospitals concentrate neurocritical care capacity with standardized monitoring-intensive care pathways. EU MDR post-market surveillance mandates for implantable neurological products elevate quality thresholds and filter marginal competitors. The Ruhr-Rhine industrial corridor hosts specialty chemical suppliers of medical-grade silicone for drainage catheter production.
Japan
METI innovation procurement programs accelerate PMDA breakthrough designation pathways for novel haematoma evacuation devices. Aging population dynamics expand eligible patient cohorts for chronic presentations. The Kanto region around Tokyo concentrates interventional neuroradiology departments adopting middle meningeal artery embolization techniques.
India
CDSCO streamlined medical device registration pathways open access for cranial pressure monitoring systems in tier-2 city hospitals. Underpenetrated neurocritical care infrastructure creates expansion opportunities for monitoring device vendors. Maharashtra and Karnataka state hospital networks lead procurement modernization for trauma care capabilities.
United Kingdom
NHS bundled payment models for neurocritical care consolidate monitoring intensity into standardized pathways. EU MDR technical documentation requirements extend certification timelines for Class III neurological implants. London and Southeast England tertiary centers concentrate fellowship-trained intensivist capacity and complex evacuation procedural volume.
Subdural Haematoma Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Subdural Haematoma Market. Vertically integrated cranial device manufacturers capture premium pricing through bundled system offerings, while pharmaceutical suppliers face margin compression from generic substitution. Three archetypes dominate: integrated neurosurgical technology conglomerates, standalone pharmaceutical intervention suppliers, and regional device fabricators with focused drainage catheter portfolios. Competitive moves concentrate on M&A for technology portfolio expansion and strategic partnerships for EMR integration capabilities.
Among integrated neurosurgical technology conglomerates, Medtronic Plc, Stryker Corporation, and Integra LifeSciences Corporation occupy positions defined by their cranial technology portfolios. Medtronic exemplifies the vertically integrated archetype with broad neurocritical care system offerings. Stryker represents the surgical navigation and instrument ecosystem approach. Integra LifeSciences sits within the regenerative tissue and dural repair specialization tier, differentiating through biomaterial platforms rather than capital equipment scale.
| Leading Market Players |
|---|
| Medtronic Plc |
| Integra LifeSciences Corporation |
| Stryker Corporation |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Smith & Nephew Plc |
| Baxter |
| Novartis AG |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at German and US specialty chemical plants for medical-grade silicone establishes minimum viable scale for drainage catheter manufacturers, concentrating supply-side pricing power among qualified suppliers while filtering out sub-scale competitors unable to absorb EU MDR compliance costs.
Pricing Analysis
After-sales service contracts for intracranial pressure monitoring systems drive lifetime customer value beyond initial hardware placement. Three-tier pricing structure across premium, standard, and economy levels separates integrated system vendors from standalone device suppliers and commodity catheter manufacturers. Price differentiation rests on FDA clearance tier and CE marking pathway complexity, with United States academic medical centers absorbing premium bundled offerings while Indian tier-2 hospitals prioritize economy-tier drainage systems. Cost compression in pharmaceutical intervention categories is intensifying because generic idarucizumab and andexanet alfa equivalents erode margin pools. Outpatient neurology clinics exhibit highest price sensitivity; tertiary trauma centers demonstrate lowest sensitivity due to bundled payment absorption.
Supply Chain Analysis
Ruhr-Rhine industrial corridor concentration of medical-grade silicone production underwrites global drainage catheter supply security. Manufacturing draws from German specialty chemical synthesis, US polymer finishing operations, and Japanese precision extrusion equipment. Raw material dependencies include platinum-cured silicone elastomers, radiopaque barium sulfate compounds, and antimicrobial silver ion additives. Single-source vulnerability concentrates in notified body capacity for EU MDR technical documentation review, extending certification timelines. Distribution runs through hospital procurement committees consolidating into single-source vendor contracts, with integrated neurosurgical device manufacturers capturing preference through total cost-of-ownership guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained neurocritical care specialist scarcity constrains capacity expansion for high-acuity monitoring units, creating a capability bottleneck that reshapes competitive returns toward technology-automation solutions and training-intensive service models.
For Market Incumbents: Compound defensive positioning through backward integration into medical-grade silicone supply and captive production of algorithm-assisted diagnostic modules. Lock in hospital system partnerships with EMR integration capabilities to raise switching costs against emerging entrants offering point-of-care detection tools. Prioritize certification investment for EU MDR Class III neurological implants to filter marginal competitors and concentrate share among qualified suppliers. For New Entrants and Emerging Players: Lead with algorithm-assisted volume quantification software paired with portable CT imaging as the most penetrable white-space target, bypassing capital-intensive hardware manufacturing. Target tier-2 city hospitals in Maharashtra and Karnataka states under CDSCO streamlined registration pathways for cranial pressure monitoring systems. Deploy software-as-a-service pricing with minimal upfront capital requirements to circumvent incumbent bundled contract lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithmic diagnostic tool developers with FDA breakthrough device designation momentum and established radiology AI vendor quality management systems. Long-term viability over the next decade hinges on reimbursement listing for minimally invasive evacuation procedures versus conventional craniotomy. Acquisition target archetype: European radiology AI vendors restructuring quality management systems ahead of EU AI Act enforcement deadlines. The signal to watch is PMDA breakthrough designation pathway acceleration under Japan METI innovation procurement programs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements for Class III implants extend certification timelines by 12-18 months, filtering competitors. |
| Hospital System Partnership | Single-source vendor contracts in Texas and California academic medical centers consolidate procurement for bundled cranial technologies. |
| Software Companion Development | Algorithm-assisted diagnostic tools paired with portable CT imaging create point-of-care detection capabilities outside radiology departments. |
| Reimbursement Strategy | Coverage decisions for middle meningeal artery embolization versus burr-hole drainage reshape capital allocation across product portfolios. |
| FDA Submission | Premarket notification pathways for Class II cranial access devices shape device qualification timelines and time-to-market for new entrants. |
Research Approach
A standing panel of neurocritical care intensivists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up procedure volume estimates triangulated against top-down market sizing from integrated device manufacturer revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including intervention type, end-user facility tier, severity level stratification, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to aging demographic expansion and trauma center density saturation. Industry-specific forecast inputs incorporated EU MDR notified body queue lengths and PMDA breakthrough designation pathway velocity.
The analysis sits within stated boundaries; outcomes outside sustained neurocritical care bundling adoption or accelerated minimally invasive technique diffusion would require recalibration. Forecasts reflect documented assumptions regarding reimbursement threshold evolution and specialist fellowship training pipeline expansion. Practitioners should keep alternative scenarios live as EU AI Act enforcement deadlines and CDSCO registration pathway streamlining evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market