
 Global Eye Allergy Therapeutics Market | 2026-2036
Global Eye Allergy Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Eye Allergy Therapeutics Market Foresight
Project finance for specialty pharmaceutical manufacturing is rewriting competitive dynamics in ophthalmic allergy care. Alcon leverages its vertically integrated supply chain for active pharmaceutical ingredients and finished dosage forms. Santen Pharmaceutical anchors its position through deep specialization in ocular surface disease portfolios across Asian and European markets.
Eye allergy therapeutics comprise pharmacological agents formulated for topical ocular administration, typically achieving therapeutic concentrations in tear film within minutes via drop or gel vehicles, designed to interrupt histamine-mediated or inflammatory pathways in conjunctival tissue. Antihistamines occupy the largest revenue share due to immediate symptom relief and strong physician familiarity in first-line settings. Mast cell stabilizers represent the fastest-expanding category as prophylactic regimens gain traction among refractory patients requiring sustained disease control.
The FDA's ophthalmic drug guidance, EMA's MDR requirements for combination devices, and Japan's PMDA review pathways for preservative-free formulations collectively elevate barriers to market entry while accelerating innovation in delivery technology. REACH compliance in Europe further constrains excipient selection, favoring suppliers with advanced toxicology dossiers. Stakeholders must monitor regulatory divergence between preservative standards in the United States and Europe to anticipate reformulation costs and timeline risks.
Market Dynamics
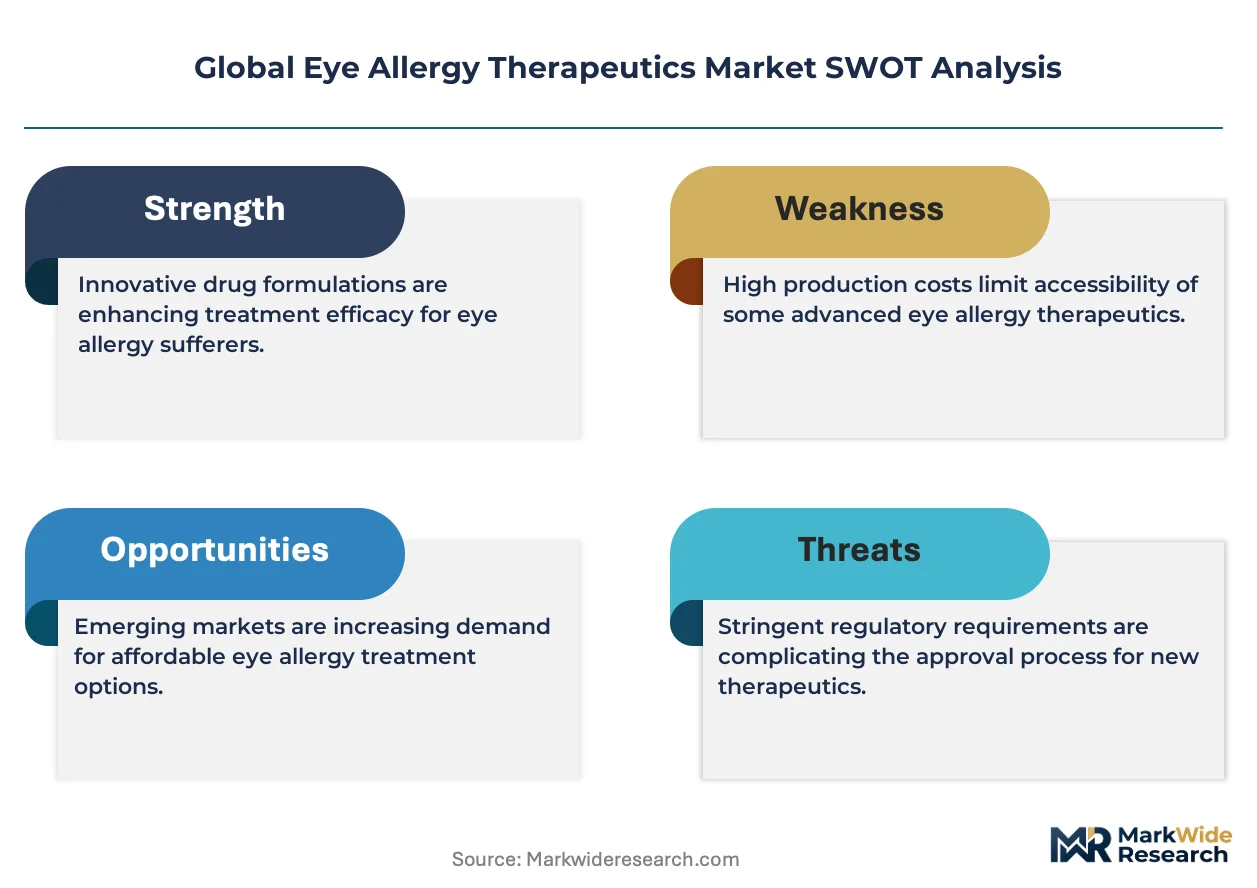
Preservative-free formulation mandates from the FDA and EMA are forcing manufacturers to abandon benzalkonium chloride-dependent supply chains and rebuild manufacturing footprints around novel delivery vehicles.
Growth Catalysts
- Seasonal Allergic Conjunctivitis Prevalence:United States metropolitan clusters report elevated diagnostic rates that sustain volume commitments for branded antihistamine therapies. Ophthalmology clinics in Atlanta, Phoenix, and Dallas anchor prescription volume.
- EMA MDR Requirements:Combination device regulations for drug-eluting contact lenses and punctal plugs are accelerating investment in integrated formulation-delivery platforms across European manufacturing sites.
- Mast Cell Stabilizer Prophylaxis:Refractory patient cohorts in Japan and Germany are adopting scheduled dosing regimens that extend treatment windows and reduce acute rescue medication dependence.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Three contract manufacturers in India and China control bulk ketotifen fumarate supply, exposing finished dose formulators to input volatility and qualification delays.
- Preservative-Free Manufacturing Capex:Aseptic filling lines and single-use containment systems require capital outlays that mid-tier generic manufacturers cannot deploy without strategic partnerships.
- Topical Corticosteroid Substitution:Severe allergic conjunctivitis cases in refractory populations are migrating toward short-course steroid protocols that compress antihistamine revenue per patient.
Strategic Opportunities
- Brazil and Mexico Undersupply:Latin American markets exhibit prescription volume growth without proportional expansion of preservative-free manufacturing capacity, creating first-mover positioning for compliant entrants.
- PMDA Review Pathway Acceleration:Japan's streamlined approval track for novel ocular surface delivery vehicles reduces timeline risk for hydrogel-based sustained-release formulations.
- Teleophthalmology Channel Integration:Direct-to-patient subscription models for seasonal prophylaxis kits are capturing prescription renewals outside traditional clinic-based dispensing.
Industry Challenges
- Aseptic Processing Talent Scarcity:Qualified personnel for closed-system filling operations are concentrated at legacy ophthalmic manufacturing sites in Switzerland and Ireland, constraining geographic expansion.
- Excipient Toxicology Dossier Gaps:REACH compliance for novel polymers used in preservative-free vehicles requires multi-year ECHA submission timelines that delay formulation launches.
- Legacy ERP Integration Friction:Track-and-trace serialization mandates for ophthalmic products are forcing mid-tier manufacturers to replace batch management systems ahead of depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Eye Allergy Therapeutics Market |
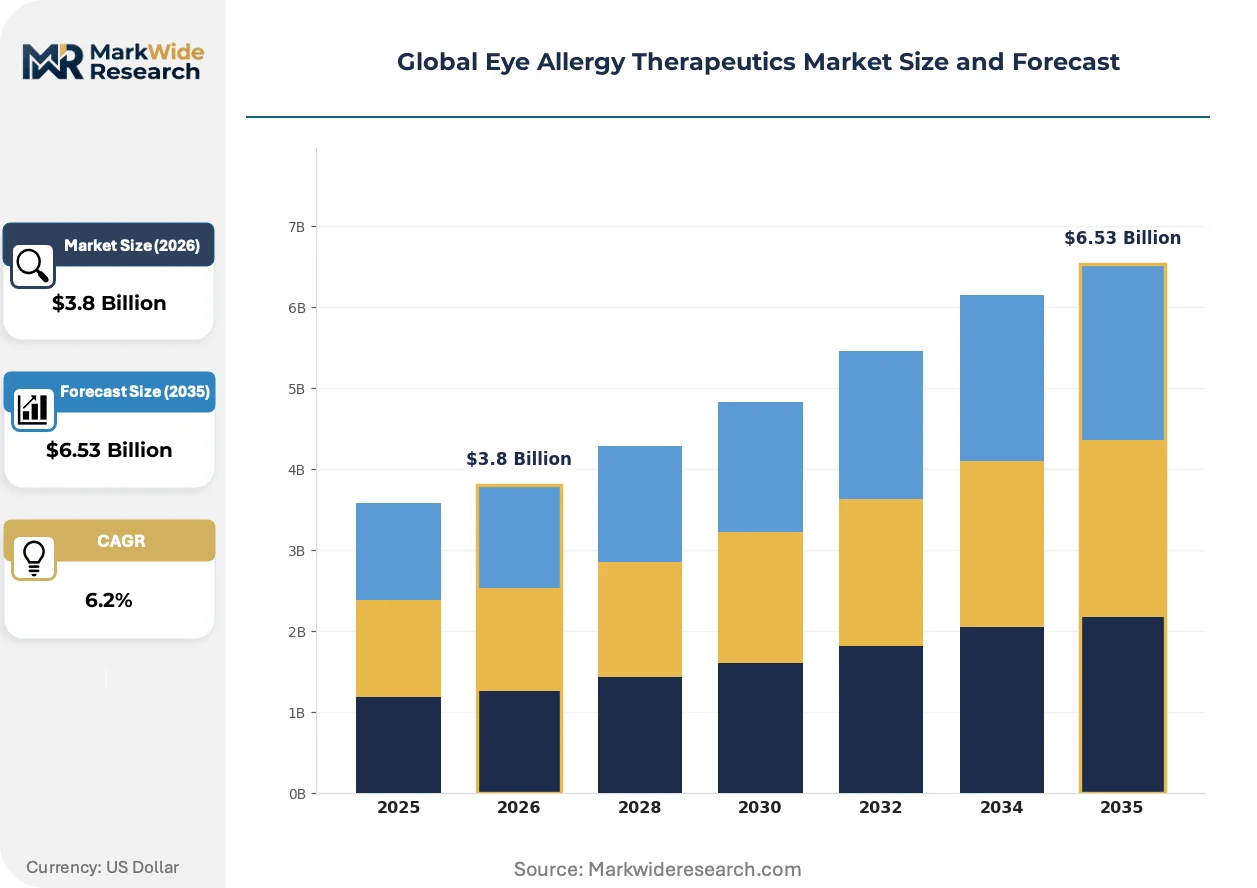
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Mast Cell Stabilizers, Corticosteroids, Decongestants, Non-Steroidal Anti-Inflammatory Drugs Therapy Area: Seasonal Allergic Conjunctivitis, Vernal Keratoconjunctivitis, Atopic Keratoconjunctivitis, Giant Papillary Conjunctivitis, Contact Dermatitis End User: Ophthalmology Clinics, Allergy Centers, Hospitals, Ambulatory Surgical Centers Formulation Type: Eye Drops, Ointments, Gels, Sprays, Emulsions |
| Companies Covered | Alcon, Santen Pharmaceutical, Bausch Health, Johnson & Johnson, AbbVie, Novartis, Sun Pharmaceutical Industries, Teva Pharmaceutical Industries, Nicox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Eye Allergy Therapeutics Market Shifts & Advancements
Novel delivery vehicles are compressing the competitive advantage of established drop formulations while regulatory divergence between preservative standards creates formulation complexity.
Nanostructured lipid carriers for ocular surface drug delivery are rendering obsolete conventional aqueous solutions that rely on frequent dosing intervals. Specialty ophthalmology practices in Germany and Japan are piloting these platforms for seasonal prophylaxis. The technology is rendering obsolete the volume-based revenue model tied to 30-day multi-dose bottles.
REACH Annex XVII restrictions on quaternary ammonium compounds are eliminating benzalkonium chloride from European formulations. Manufacturers serving EMA-regulated markets are qualifying polyquaternium-1 and stabilized oxychloro complexes as replacement preservatives. Hydrogel-based preservative-free vehicles are capturing share in France and the Netherlands where ANSM and national pharmacy boards have issued early compliance guidance.
Patients are consolidating prescription fulfillment through specialty pharmacy mail-order channels that bundle allergy therapeutics with diagnostic monitoring. This pattern is displacing independent retail pharmacy dispensing for chronic prophylaxis regimens. United States integrated delivery networks are negotiating exclusive formulary placement for preservative-free options in exchange for adherence data sharing.
Global Eye Allergy Therapeutics Market Segmentation
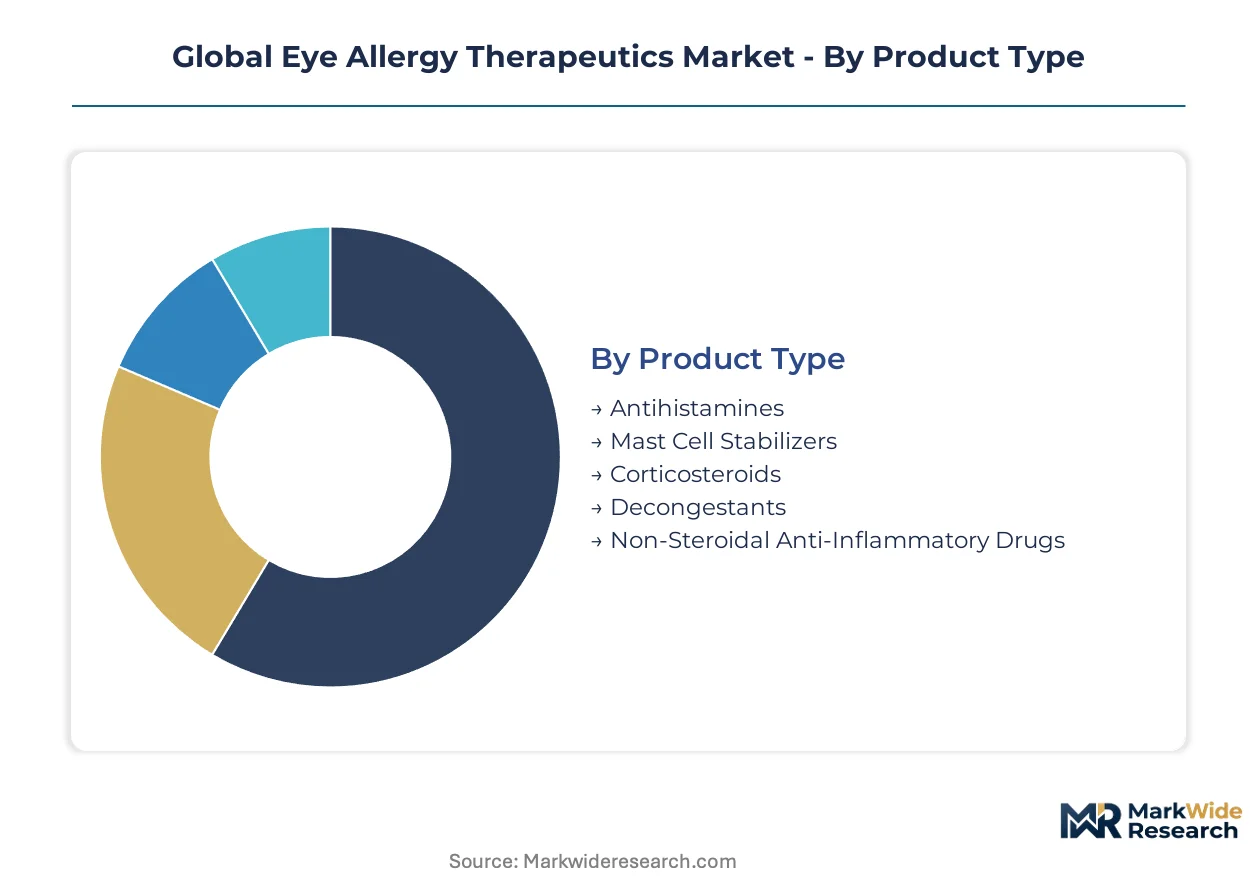
Segmentation in eye allergy therapeutics reveals how formulation technology and clinical setting reshape prescribing patterns. Product chemistry, therapy severity, and delivery vehicle each create distinct margin profiles and regulatory pathways that manufacturers must navigate.
Product Type:
Mature antihistamine formulations dominate first-line prescribing while emerging biologic mechanisms reshape prophylactic segments.
- Antihistamines:H1-receptor antagonists formulated as topical drops achieve therapeutic tear film concentrations within minutes, interrupting histamine-mediated vasodilation and pruritus. United States ophthalmology clinics in Atlanta, Phoenix, and Dallas sustain volume leadership through seasonal prescribing protocols for allergic conjunctivitis.
- Mast Cell Stabilizers:Cromolyn sodium and lodoxamide tromethamine prevent degranulation rather than blocking released mediators, requiring scheduled dosing before allergen exposure. Demand concentrates in Japan and Germany where refractory patient cohorts adopt prophylactic regimens that reduce acute rescue dependence.
- Corticosteroids:Potent anti-inflammatory agents reserved for severe or refractory cases requiring rapid immune suppression.
- Decongestants:Vasoconstrictor agents providing temporary redness relief without addressing underlying inflammatory mechanisms.
- Non-Steroidal Anti-Inflammatory Drugs:Dual cyclooxygenase inhibition for patients with steroid intolerance or contraindications.
Antihistamines retain volume leadership; mast cell stabilizers hold the steepest expansion curve.
Therapy Area:
Severity gradients from seasonal irritation to chronic corneal involvement dictate treatment duration, monitoring intensity, and reimbursement tier.
- Seasonal Allergic Conjunctivitis:IgE-mediated acute response to pollen, grass, and ragweed allergens affecting tear film stability and conjunctival hyperemia. United States metropolitan clusters drive prescription volume through defined allergy seasons that align with formulary placement negotiations.
- Vernal Keratoconjunctivitis:Severe bilateral inflammation of tarsal and limbal conjunctiva in pediatric and adolescent populations, threatening corneal shield ulcers and amblyopia. Specialist centers in Milan and Barcelona manage complex cases requiring immunomodulatory protocols beyond standard antihistamine therapy.
- Atopic Keratoconjunctivitis:Chronic Th2-mediated inflammation associated with atopic dermatitis, demanding long-term disease modification rather than symptomatic control.
- Giant Papillary Conjunctivitis:Mechanical and immunologic response to contact lens wear or ocular prosthetics, managed through lens material modification and mast cell stabilization.
- Contact Dermatitis:Delayed hypersensitivity to topical medications, preservatives, or cosmetics requiring allergen identification and avoidance.
Seasonal allergic conjunctivitis commands the largest patient pool; vernal keratoconjunctivitis generates the highest per-patient revenue intensity.
End User:
Site-of-care economics and prescriber specialization fragment demand across outpatient, institutional, and procedural settings.
- Ophthalmology Clinics:Dedicated ocular surface disease practices in Germany and Japan anchor premium prescribing for preservative-free formulations and novel delivery vehicles. These settings capture chronic prophylaxis patients through subscription-based seasonal kits integrated with diagnostic monitoring.
- Allergy Centers:Multidisciplinary facilities coordinating systemic and ocular immunotherapy, particularly for polysensitized patients requiring coordinated desensitization protocols.
- Hospitals:Inpatient and emergency settings managing acute severe presentations or complications requiring specialist consultation.
- Ambulatory Surgical Centers:Procedural sites addressing refractory cases through punctal plug insertion or other minor interventions.
Ophthalmology clinics concentrate branded volume; allergy centers are expanding fastest as integrated care models proliferate.
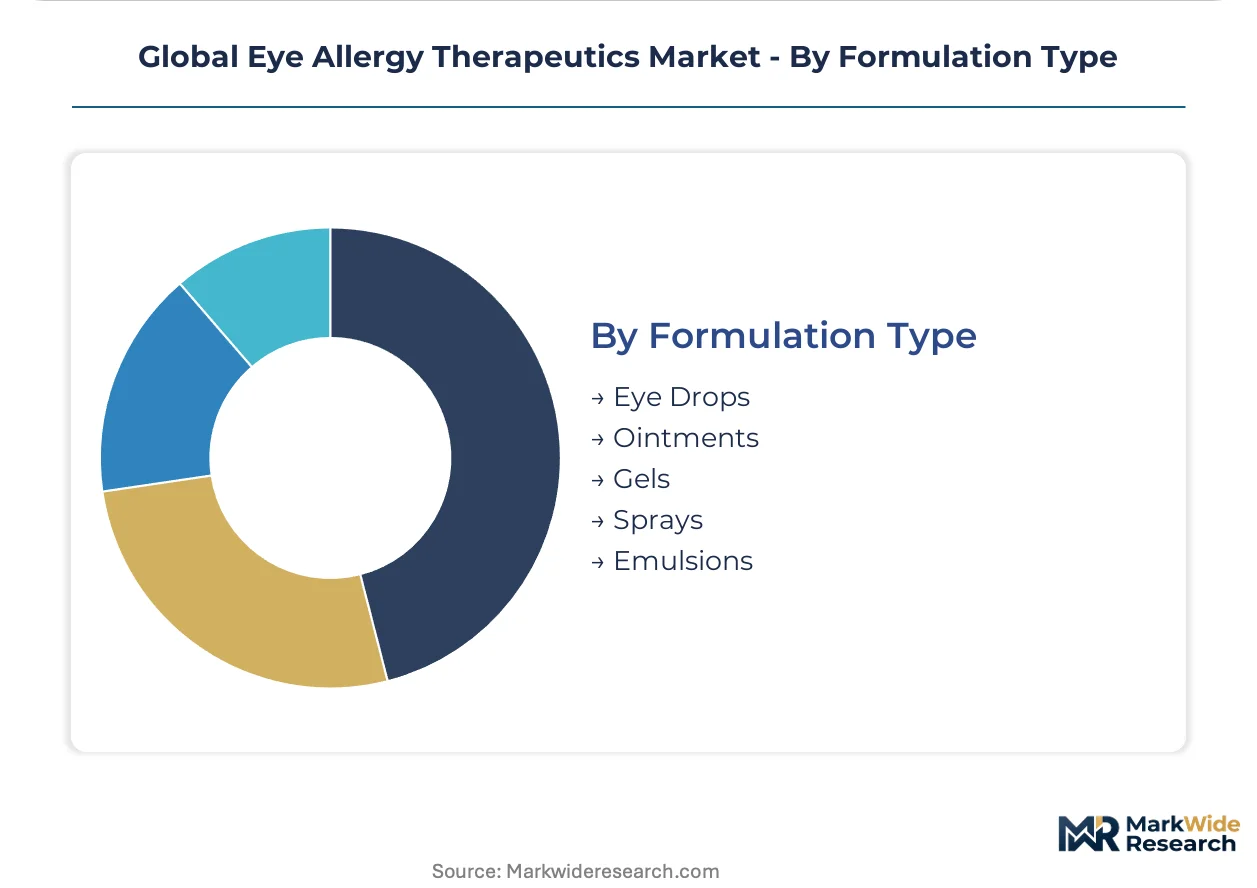
Formulation Type:
Delivery vehicle selection increasingly determines regulatory compliance cost and patient adherence profile.
- Eye Drops:Aqueous and emulsion-based solutions dominating unit volume, now pressured by preservative-free reformulation mandates from FDA and EMA.
- Ointments:Petrolatum-based vehicles providing prolonged ocular surface contact for nocturnal symptom control.
- Gels:Hydrogel and carbomer matrices extending residence time while enabling preservative-free positioning for EMA-regulated markets.
- Sprays:Novel mist delivery systems in development for patients with drop instillation difficulties or compliance barriers.
- Emulsions:Lipid-based formulations improving drug penetration across the tear film lipid layer for posterior segment indications.
Eye drops retain installed base dominance; gels are climbing fastest on preservative-free regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ophthalmology clinics in metropolitan clusters drive prescription volume through seasonal protocols. Germany, Japan, and the United States concentrate branded demand through specialized ocular surface disease practices. Regulatory divergence between FDA and EMA preservative standards fragments formulation strategies across manufacturing footprints.
United States
Atlanta, Phoenix, and Dallas anchor prescription volume for seasonal allergic conjunctivitis therapies through defined pollen seasons that align with formulary negotiations. FDA tightening of preservative-free formulation standards redirects R&D investment toward novel delivery vehicles. Ophthalmology clinics in these metropolitan clusters capture chronic prophylaxis patients through subscription-based seasonal kits.
Germany
Refractory patient cohorts in Munich and Berlin adopt scheduled mast cell stabilizer regimens that extend treatment windows beyond acute rescue dependence. EMA MDR requirements for combination devices accelerate investment in integrated formulation-delivery platforms at manufacturing sites in Baden-Württemberg and Bavaria. Specialty ophthalmology practices pilot nanostructured lipid carriers for seasonal prophylaxis.
Japan
PMDA review pathway acceleration reduces timeline risk for hydrogel-based sustained-release formulations targeting the Tokyo and Osaka metropolitan markets. Mast cell stabilizer prophylaxis gains traction among pediatric vernal keratoconjunctivitis patients in specialist centers across Kanto and Kansai regions. Santen Pharmaceutical anchors market position through deep specialization in ocular surface disease portfolios.
India
Contract manufacturers in Hyderabad and Ahmedabad control bulk ketotifen fumarate supply, exposing finished dose formulators to input volatility and qualification delays. CDSCO alignment with international preservative standards pressures domestic formulators to upgrade aseptic filling capabilities. Sun Pharmaceutical Industries and Teva Pharmaceutical Industries leverage Indian manufacturing infrastructure for cost-competitive antihistamine production.
Brazil
Latin American prescription volume growth outpaces proportional expansion of preservative-free manufacturing capacity, creating first-mover positioning for compliant entrants. ANVISA regulatory convergence with FDA standards elevates barriers for mid-tier generic manufacturers lacking aseptic processing infrastructure. São Paulo and Rio de Janeiro concentrate ophthalmology clinic demand for branded antihistamine therapies during extended pollen seasons.
Global Eye Allergy Therapeutics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented prescription fulfillment networks. Vertically integrated ophthalmic pharmaceutical conglomerates hold supply chain advantages in active pharmaceutical ingredient sourcing and finished dosage form distribution. Three archetypes dominate: diversified healthcare conglomerates with ophthalmology divisions, pure-play ocular surface disease specialists, and mid-tier generic manufacturers with regional manufacturing partnerships. Competitive moves concentrate on preservative-free manufacturing capacity expansion and teleophthalmology channel integration for direct-to-patient subscription models.
Among diversified healthcare conglomerates, Alcon leverages vertically integrated supply chain control over active pharmaceutical ingredients and finished dosage forms. Johnson & Johnson and Novartis occupy positions spanning consumer health and prescription ophthalmic segments. Santen Pharmaceutical exemplifies the pure-play specialist archetype through concentrated ocular surface disease portfolio depth across Asian and European markets. AbbVie and Bausch Health represent hybrid positioning between specialty pharmaceutical focus and broader therapeutic diversification.
| Leading Market Players |
|---|
| Alcon |
| Santen Pharmaceutical |
| Bausch Health |
| Johnson & Johnson |
| AbbVie |
| Novartis |
| Sun Pharmaceutical Industries |
| Teva Pharmaceutical Industries |
| Nicox |
| Others |
Supply & Pricing Matrix
Single-source dependency on Indian and Chinese ketotifen fumarate producers determines both pricing tier spreads and supply chain shape across finished dose markets. FDA and EMA preservative-free mandates compound this concentration risk by forcing capital-intensive manufacturing rebuilds that stratify cost structures between compliant and non-compliant tiers.
Pricing Analysis
Cost-plus contracts with API indexation to commodity chemical benchmarks dominate procurement between finished dose formulators and Indian contract manufacturers. Pricing stratifies across preservative-free premium tiers, standard benzalkonium chloride formulations, and economy generic substitutes. Cost compression in mid-tier generics is intensifying because aseptic filling capex requirements disqualify smaller manufacturers from contract eligibility. Hospital procurement committees exhibit highest price sensitivity; ophthalmology clinics in metropolitan United States clusters show lowest sensitivity due to branded formulary lock-ins.
Supply Chain Analysis
Tariff exposure between United States and China dominates risk planning for API-dependent formulators rebuilding around preservative-free compliance. Bulk ketotifen fumarate supply concentrates in Hyderabad and Ahmedabad, India, plus selected coastal Chinese provinces, with finished dose production anchored in Switzerland, Ireland, and Japan. The supply chain draws from quaternary ammonium compound feedstocks and specialized polymer excipients for hydrogel vehicles. Single-source vulnerability persists at the aseptic filling equipment tier. Distribution runs through specialty pharmacy mail-order channels displacing independent retail pharmacy dispensing for chronic prophylaxis regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified aseptic processing personnel constrains geographic expansion and creates defendable positioning for manufacturers with established training pipelines. The capability gap separates legacy ophthalmic sites from new entrants attempting preservative-free qualification.
For Market Incumbents: Build regulatory moat through early REACH Annex XVII compliance for novel polymer excipients ahead of ECHA submission timelines. Secure backward integration into ketotifen fumarate API through strategic partnerships with Indian manufacturers to defend against input volatility. Add aseptic filling capacity in Switzerland and Ireland where talent concentration supports operational excellence. Channel control through teleophthalmology subscription models locks in prescription renewals outside clinic-based dispensing. For New Entrants and Emerging Players: Latin American underpenetration in preservative-free manufacturing capacity offers first-mover positioning for ANVISA-compliant entrants targeting São Paulo and Rio de Janeiro ophthalmology clusters. Brazil's prescription volume growth without proportional compliant capacity expansion creates the most penetrable geography. Japan's PMDA accelerated review pathway for hydrogel vehicles provides regulatory differentiation for novel delivery platform specialists. Direct-to-patient seasonal prophylaxis kits integrated with diagnostic monitoring offer the clearest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pure-play ocular surface disease specialists with preservative-free manufacturing assets. Long-term viability over the next decade hinges on delivery technology differentiation rather than molecule exclusivity. Acquisition targets should demonstrate integrated formulation-delivery platform capabilities spanning Asian and European regulatory clusters. Watch for hydrogel-based sustained-release formulation approvals as the inflection signal indicating technology transition momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Manufacturing Scale-Up | Aseptic filling line deployment in Switzerland and Ireland captures scarce qualified personnel pools. |
| API Supply Agreement Restructuring | Dual-sourcing ketotifen fumarate from India and China reduces single-source exposure for finished dose formulators. |
| Teleophthalmology Channel Integration | Direct-to-patient subscription models displace independent retail pharmacy dispensing for seasonal prophylaxis. |
| Hydrogel Delivery Vehicle Development | PMDA accelerated review pathway reduces timeline risk for sustained-release formulations targeting Japanese markets. |
| REACH Excipient Compliance Program | Multi-year ECHA submission timelines for novel polymers must initiate immediately to preserve European market access. |
Research Methodology
The analysis maps antihistamine formulations, mast cell stabilizers, corticosteroid rescue therapies, and novel delivery vehicles, each validated through ophthalmology clinic directors, regulatory affairs specialists at EMA and FDA, formulary negotiation teams at United States integrated delivery networks, and procurement managers at Indian API contract manufacturers. Primary interviews combined with secondary validation against FDA ophthalmic drug guidance documents, EMA MDR combination device filings, PMDA review pathway disclosures, and CDSCO alignment notifications. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue disclosures across the analysis window.
Assumptions held FDA and EMA preservative-free mandates as fixed regulatory conditions while varying pricing power elasticity across metropolitan United States clusters, German refractory patient cohorts, and Japanese pediatric vernal keratoconjunctivitis populations. Segmentation dimensions modeled include product chemistry class, therapy severity gradient, end-user site-of-care economics, and formulation delivery vehicle type. CAGRs derived from patient population growth rates, seasonal allergy prevalence trends, and prophylactic regimen adoption curves. Forecast inputs incorporated REACH compliance timeline probabilities and aseptic processing talent availability constraints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by mid-tier generic manufacturers or accelerated PMDA approval timelines for novel vehicles would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market