
 Ragweed Pollen Allergy Treatment Market | 2026-2036
Ragweed Pollen Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ragweed Pollen Allergy Treatment Market Outlook
Pharmaceutical-grade allergen standardization is collapsing the gap between sublingual drops and injection-based protocols. ALK-Abello A/S dominates European immunotherapy supply chains through captive manufacturing of standardized extracts. Stallergenes Greer plc anchors North American distribution with vertically integrated pollen collection networks across multiple biomes. Thermo Fisher Scientific Inc. leverages diagnostic instrument placements to secure downstream reagent pull-through in allergy testing workflows.
Ragweed pollen allergy treatment encompasses pharmaceutical and biological interventions designed to mitigate type I hypersensitivity reactions triggered by Ambrosia artemisiifolia and related species, with standardized allergen extracts measured in bioequivalent allergy units (BAU) or major allergen content. These therapies function by blocking histamine receptors, reducing nasal mucosa inflammation, or inducing antigen-specific immune tolerance through repeated controlled exposure. Immunotherapy leads clinical value creation due to multi-year treatment cycles and durable symptom remission, while sublingual delivery captures the fastest expansion as patients reject injection burdens. Nasal sprays occupy a mature volume position in seasonal self-medication, though margin pools increasingly shift toward pharmacy-administered protocols with reimbursement attachment.
FDA allergen extract guidance and EMA immunotherapy quality guidelines jointly elevate manufacturing compliance costs for new market entrants, compressing the supplier base toward established extract houses. EPA ambient air monitoring requirements for pollen reporting indirectly shape treatment timing and geographic targeting by allergists and pharmacy benefit managers. Stakeholders must monitor whether FDA advances toward formal approval pathways for non-injection biologics will unlock new prescriber segments or entrench existing modality hierarchies.
Market Dynamics
Pharmaceutical-grade allergen standardization is collapsing the gap between sublingual drops and injection-based protocols, compressing modality hierarchies and redrawing competitive boundaries among extract manufacturers.
Growth Catalysts
- FDA label expansions for allergen extracts:Accelerated approval pathways for standardized Ambrosia formulations are unlocking new prescriber segments in ambulatory care settings.
- Pediatric allergy clinic expansion:Sublingual immunotherapy programs targeting younger patient cohorts are extending treatment initiation windows and multi-year revenue cycles.
- Vertically integrated pollen collection networks:Captive sourcing across multiple biomes secures supply continuity for high-potency extract production during seasonal variability.
Market Restraints
- EMA immunotherapy quality guidelines:Elevated manufacturing compliance costs compress the supplier base toward established extract houses with captive quality infrastructure.
- Raw material geographic concentration:Ragweed pollen harvesting concentrates in specific Midwest and Northeast corridors, creating climate-dependent supply vulnerabilities.
- Biologic substitution pressure:Monoclonal antibody therapies for allergic rhinitis threaten to displace extract-based protocols in severe patient segments.
Strategic Opportunities
- Underpenetrated sublingual protocols in Germany:Reimbursement alignment for pharmacy-administered drops lags injection penetration, creating white space for modality conversion.
- Diagnostic-reagent bundling:Instrument placement strategies in allergy testing workflows secure downstream extract pull-through and treatment protocol lock-in.
- EPA ambient air monitoring integration:Pollen count reporting requirements enable precision targeting of treatment timing and geographic deployment by pharmacy benefit managers.
Industry Challenges
- Bioequivalent allergy unit standardization:Variability in BAU measurement methodologies across extract houses creates dosing inconsistency and prescriber confusion.
- Multi-year patient adherence engineering:Immunotherapy protocols require sustained compliance across three-to-five year cycles, demanding behavioral intervention infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ragweed Pollen Allergy Treatment Market |
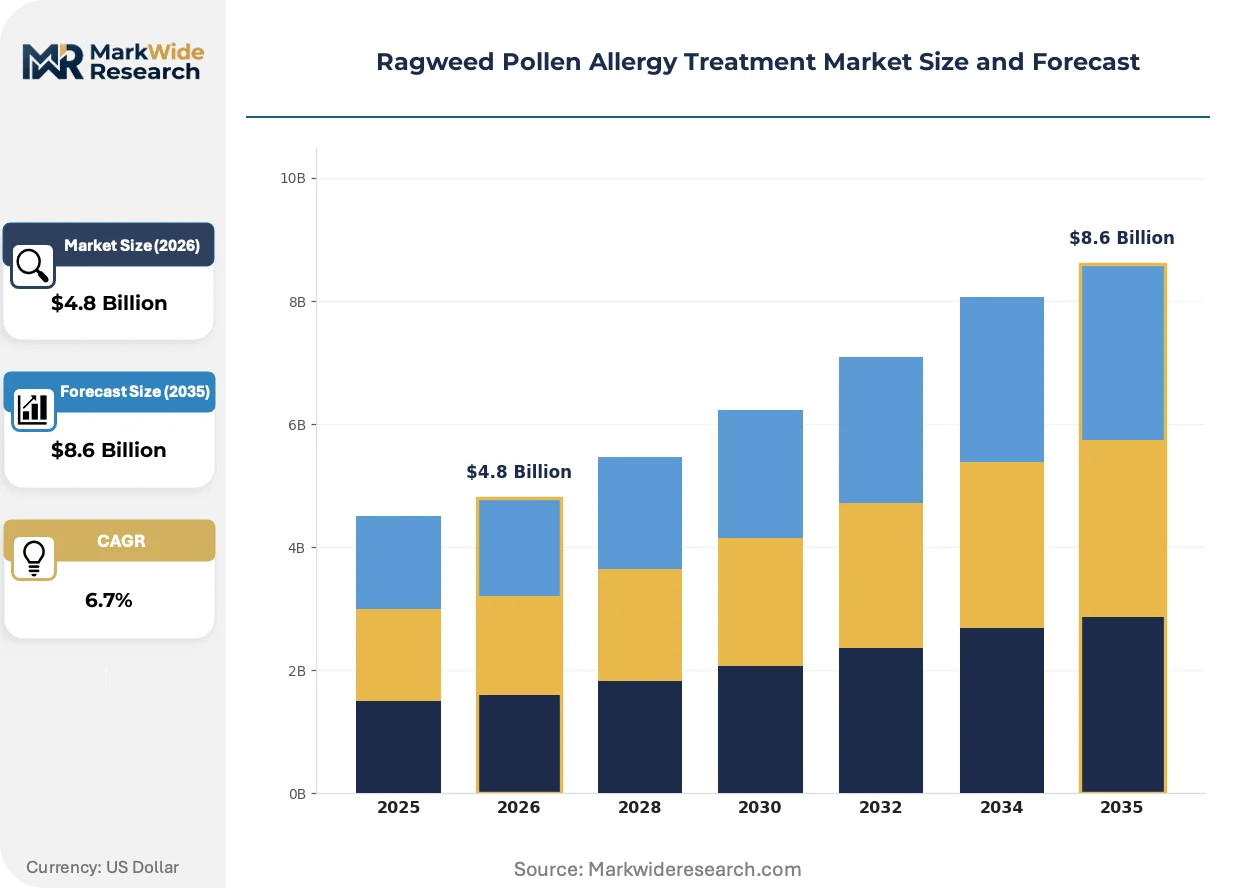
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Decongestants, Nasal Sprays, Immunotherapy Delivery Mode: Oral, Injectable, Sublingual, Topical End User: Hospitals, Clinics, Homecare, Pharmacies Treatment Duration: Short-term, Long-term, Seasonal, Continuous |
| Companies Covered | ALK-Abello A/S, Novartis AG, Sanofi S.A., GlaxoSmithKline plc, Merck & Co., Inc., Astellas Pharma Inc., Stallergenes Greer plc, Thermo Fisher Scientific Inc., ASIT Biotech SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ragweed Pollen Allergy Treatment Market Strategic Shifts
Sublingual delivery modalities are actively displacing injection burdens across patient segments, while regulatory frameworks on both sides of the Atlantic recalibrate manufacturing compliance thresholds and diagnostic integration deepens treatment protocol automation.
Recombinant allergen technology is decomposing the traditional extract manufacturing paradigm. Biologically standardized Ambrosia proteins eliminate batch-to-batch variability inherent in pollen-derived materials. Allergy specialty practices in Denmark and the Netherlands are piloting these formulations for precision dosing. The technology is decomposing reliance on geographic pollen harvesting networks and seasonal production constraints.
EMA immunotherapy quality guidelines now mandate enhanced characterization of major allergen content alongside bioequivalent allergy unit labeling. This dual-metric requirement elevates analytical chemistry investments for European market access. Smaller extract houses without in-house mass spectrometry capabilities face outsourcing dependencies or exit pressures.
Patient self-administration preferences are compressing clinical visit frequencies for maintenance dosing. Pharmacy benefit managers in the United States Midwest corridor are restructuring reimbursement to favor home-based sublingual protocols over office-administered injections. This behavioral pivot concentrates margin capture with extract manufacturers possessing direct-to-pharmacy distribution infrastructure rather than clinic-dependent sales models.
Ragweed Pollen Allergy Treatment Market Segmentation
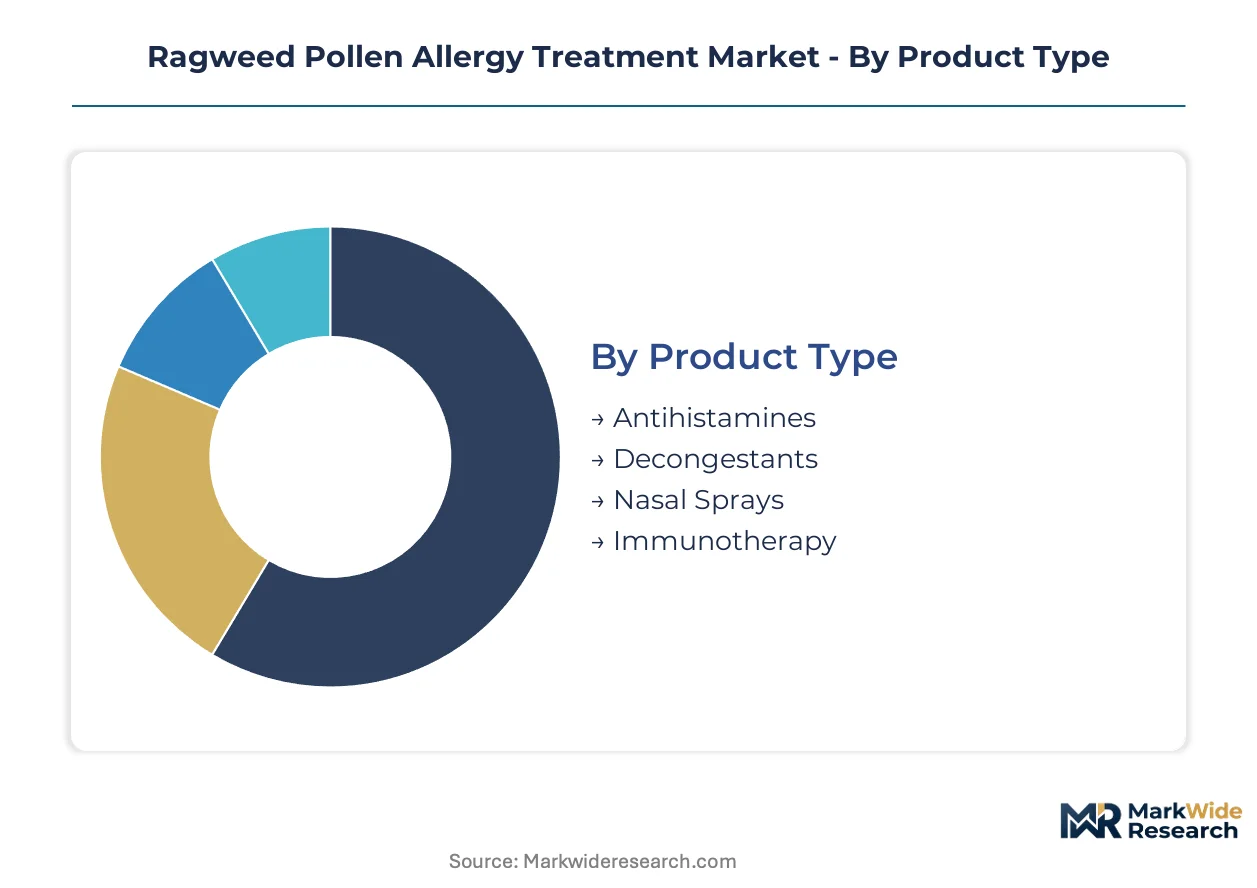
Treatment modality selection in ragweed allergy care hinges on symptom severity, patient age, and reimbursement architecture. Channel dynamics determine which formulations capture volume versus margin, with pharmacy-administered protocols increasingly diverging from clinic-based revenue models.
Product Type:
Channel mix varies sharply across pharmacologic categories, with prescription immunotherapy concentrates flowing through specialty distributors while nasal sprays and oral antihistamines dominate retail pharmacy shelves.
- Immunotherapy:Standardized allergen extracts measured in bioequivalent allergy units induce antigen-specific immune tolerance through repeated controlled exposure. Demand concentrates in pediatric allergy clinics across the United States Midwest where multi-year treatment cycles generate durable revenue streams, though EMA quality guidelines elevate manufacturing compliance costs for new extract suppliers.
- Nasal Sprays:Corticosteroid and antihistamine formulations deliver localized mucosal anti-inflammatory action. Volume clusters in seasonal self-medication channels, yet margin pools shift toward pharmacy-administered protocols with reimbursement attachment as patients reject clinical visit burdens.
- Antihistamines:Systemic histamine receptor antagonists provide rapid symptom relief for acute type I hypersensitivity reactions.
- Decongestants:Alpha-adrenergic agonists reduce nasal mucosa vascular congestion through vasoconstriction mechanisms.
Immunotherapy dominates installed base value. Nasal sprays represent where expansion concentrates fastest among self-directed patient segments.
Delivery Mode:
Patient adherence economics favor modalities reducing clinical touchpoints, reshaping prescriber preferences and extract manufacturer distribution investments.
- Sublingual:Allergen extracts dissolved under the tongue enable home-based immune tolerance induction without injection burden. Pharmacy benefit managers in the United States Northeast corridor restructure reimbursement to favor these protocols, capturing margin with manufacturers possessing direct-to-pharmacy infrastructure.
- Injectable:Subcutaneous immunotherapy deposits standardized extracts into subcutaneous tissue for gradual immune system modulation. Severe allergic rhinitis patients in hospital allergy departments retain preference for this modality where prescriber supervision ensures dosing precision.
- Oral:Systemic antihistamine and decongestant tablets dominate ambulatory care prescribing for acute symptom management.
- Topical:Localized nasal and ocular formulations deliver targeted histamine blockade with minimized systemic exposure.
Injectable protocols retain the deepest prescriber loyalty. Sublingual delivery is climbing the fastest as behavioral preferences compress clinical visit frequencies.
End User:
Site-of-care decisions determine reimbursement capture, with homecare and pharmacy channels diverging from traditional clinic-dependent revenue models.
- Pharmacies:Retail and specialty pharmacy networks administer sublingual immunotherapy protocols and dispense seasonal self-medication products. The United States Midwest corridor shows concentrated demand where pollen count peaks align with pharmacy benefit manager geographic targeting.
- Clinics:Allergy specialty and pediatric practices initiate long-term immunotherapy cycles with diagnostic confirmation. FDA label expansions for allergen extracts accelerate product approvals in these ambulatory settings.
- Hospitals:Acute care facilities manage severe anaphylaxis presentations and complex comorbid cases.
- Homecare:Patient self-administration of maintenance dosing extends treatment adherence beyond clinical supervision.
Clinics anchor immunotherapy initiation volume. Pharmacies represent the steepest expansion trajectory for maintenance protocol capture.
Treatment Duration:
Revenue cycle length varies from acute seasonal purchases to multi-year immune tolerance induction, segmenting patient lifetime value and manufacturer contract structures.
- Long-term:Three-to-five year immunotherapy protocols demand sustained patient compliance engineering and behavioral intervention infrastructure. Pediatric allergy clinics extending sublingual program enrollment windows capture extended revenue cycles.
- Seasonal:Pre-seasonal and co-seasonal medication use aligns with EPA ambient air monitoring pollen reporting in peak geographic corridors.
- Short-term:Acute symptom rescue therapy for intermittent allergen exposure episodes.
- Continuous:Year-round maintenance dosing for polysensitized patients with perennial symptom patterns.
Long-term protocols dominate cumulative revenue per patient. Seasonal treatment is gaining share fastest among newly diagnosed adult cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented extract manufacturers in Denmark and the Netherlands supply standardized allergen formulations to deficit markets in Southern Europe and Asia-Pacific. Import dependency for high-potency ragweed pollen concentrates shapes procurement strategies across clinics and pharmacy networks. Cross-border regulatory alignment between FDA and EMA quality frameworks simplifies bulk extract movements.
United States
Pediatric allergy clinics in the Midwest corridor drive sublingual immunotherapy enrollment where Ambrosia pollen counts peak seasonally. FDA label expansions for standardized extracts accelerate product approvals in ambulatory care settings. The Northeast corridor from Boston to Philadelphia anchors pharmacy benefit manager restructuring of reimbursement toward home-based protocols.
Germany
Reimbursement misalignment for pharmacy-administered sublingual drops lags injection penetration, creating modality conversion white space. EMA immunotherapy quality guidelines mandate dual-metric labeling of major allergen content alongside bioequivalent allergy units. The Rhine-Ruhr metropolitan cluster concentrates diagnostic-reagent bundling strategies by instrument manufacturers.
Denmark
Allergy specialty practices pilot recombinant allergen formulations for precision dosing of Ambrosia proteins. The country's national pharmaceutical regulator maintains alignment with EMA guidance on enhanced extract characterization. Copenhagen anchors captive manufacturing infrastructure for standardized extracts serving Northern European supply chains.
Netherlands
Diagnostic instrument placements secure downstream reagent pull-through in allergy testing workflows concentrated in Utrecht and Rotterdam medical corridors. Recombinant technology pilots decompose reliance on geographic pollen harvesting networks. Dutch regulators enforce EMA quality guidelines through national inspection protocols.
Canada
Health Canada regulates allergen extract imports through biologic drug pathways that parallel FDA frameworks. Pollen monitoring stations in Ontario and Quebec inform treatment timing for seasonal self-medication channels. The Greater Toronto Area concentrates pharmacy networks administering sublingual protocols to cross-border patient cohorts.
Ragweed Pollen Allergy Treatment Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and regulatory compliance depth. The supplier base compresses toward established extract houses with captive quality infrastructure as compliance costs escalate. Three archetypes dominate: vertically integrated pollen collectors, diagnostic-reagent bundlers, and recombinant technology pioneers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers secure multi-biome sourcing networks.
Within the extract manufacturing tier, ALK-Abello A/S and Stallergenes Greer plc exemplify vertically integrated specialists with captive pollen collection infrastructure. Thermo Fisher Scientific Inc. occupies a position among diagnostic-reagent bundlers leveraging instrument placements. Novartis AG and Sanofi S.A. represent pharmaceutical conglomerates with diversified allergy portfolios spanning symptomatic relief and immunotherapy segments.
| Leading Market Players |
|---|
| ALK-Abello A/S |
| Novartis AG |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Astellas Pharma Inc. |
| Stallergenes Greer plc |
| Thermo Fisher Scientific Inc. |
| ASIT Biotech SA |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between extract manufacturers and pediatric allergy clinic networks lock in multi-year supply access while stabilizing price visibility against seasonal pollen variability. These arrangements concentrate procurement power with vertically integrated suppliers possessing captive Midwest and Northeast collection infrastructure.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the immunotherapy segment. Price differentiation rests on FDA certification tier and major allergen content precision measured through mass spectrometry capabilities. Pricing pressure stems from biologic substitution pressure as monoclonal antibody therapies encroach on severe patient segments. Pharmacy benefit managers exhibit highest price sensitivity due to reimbursement restructuring toward home-based protocols, while hospital allergy departments retain lowest sensitivity given prescriber supervision requirements.
Supply Chain Analysis
Inventory lead times compress toward seasonal harvesting windows as ragweed pollen collection concentrates in August through October cycles. Geographic supply concentrates in the United States Midwest corridor, with secondary sourcing from Ontario and Quebec pollen monitoring stations. Raw material dependencies center on Ambrosia artemisiifolia pollen potency, standardized extract formulations, and diagnostic reagent bundles. Single-source vulnerability risks emerge from climate-dependent harvesting concentration. Distribution runs through specialty pharmacy networks and direct-to-clinic channels diverging by delivery modality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ragweed allergy treatment sits at a high-growth inflection as recombinant allergen technology decomposes traditional extract manufacturing and FDA label expansions accelerate product approvals.
For Market Incumbents: Compound diagnostic-reagent bundling advantages to secure downstream extract pull-through as Thermo Fisher Scientific has demonstrated. Deepen backward integration into multi-biome pollen collection networks to neutralize climate supply risks. Prioritize EMA dual-metric compliance investments to compress competitor entry. For New Entrants and Emerging Players: Lead with pharmacy-administered sublingual protocols in Germany where reimbursement misalignment creates modality conversion white space. Target pediatric allergy clinic expansion in the United States Northeast corridor where maintenance protocol capture is shifting fastest. Deploy direct-to-pharmacy distribution infrastructure to bypass clinic-dependent sales models. For Investors and Strategic Acquirers: Capital is best deployed toward recombinant technology pioneers with precision dosing capabilities and mass spectrometry infrastructure. The five-to-ten year viability window favors acquisition targets possessing FDA label expansion momentum and captive quality infrastructure. Monitor FDA formal approval pathway advances for non-injection biologics as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Allergen Technology Deployment | Eliminates batch-to-batch variability and seasonal production constraints for Ambrosia protein formulations. |
| Multi-Biome Pollen Collection Network Expansion | Secures supply continuity against climate-dependent harvesting concentration in Midwest corridors. |
| Diagnostic-Reagent Bundling Strategy | Leverages Thermo Fisher Scientific's instrument placement model to lock in downstream extract demand. |
| Pharmacy Benefit Manager Reimbursement Alignment | Captures margin shift toward home-based sublingual protocols in United States Northeast networks. |
| EMA Dual-Metric Compliance Investment | Creates regulatory moat through enhanced major allergen content characterization capabilities. |
Study Parameters
Initial hypotheses were tested against primary input from allergy specialty clinicians, pharmaceutical regulatory affairs leads, pharmacy benefit managers, and extract manufacturing procurement directors and refined through secondary validation. Sources included FDA allergen extract guidance filings, EMA immunotherapy quality guidelines, EPA ambient air monitoring databases, and hospital procurement system records. Bottom-up patient volume estimates and top-down revenue triangulation were cross-referenced for convergence.
Variance decomposition across treatment modality, delivery mode, end-user channel, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic healthcare expenditure trends. Forecast inputs incorporated pollen count monitoring data, pediatric clinic expansion trajectories, and reimbursement policy evolution patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA label expansion momentum or EMA quality guideline enforcement would require recalibration. Forecasts reflect documented assumptions regarding patient adherence engineering effectiveness and biologic substitution velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market