
 Sympathoimemetic Agents Market | 2026-2036
Sympathoimemetic Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Sympathoimemetic Agents Market Analytics
Synthetic norepinephrine bitartrate is realigning cost structures as manufacturers shift from animal-derived extraction to recombinant and fully synthetic routes. Pfizer leverages its sterile injectable infrastructure to sustain hospital contract positions across North America and Europe. Teva competes aggressively on price in the generic epinephrine vial segment, while Hikma Pharmaceuticals anchors Middle Eastern and African distribution through regional manufacturing partnerships.
Sympathomimetic agents are pharmacologic compounds that mimic sympathetic nervous system activation through direct or indirect action on alpha and beta adrenergic receptors, typically formulated as sterile solutions with specified osmolality and pH ranges for intravenous or intramuscular administration. These agents serve critical therapeutic roles in restoring perfusion pressure during septic or cardiogenic shock, reversing bronchospasm in acute asthma, and terminating anaphylactic cascade through targeted receptor agonism. The epinephrine product category dominates revenue due to its dual alpha-beta mechanism and mandated presence in emergency kits, while the injectable delivery mode captures the largest margin pool given hospital preference for rapid hemodynamic control and regulatory barriers to generic equivalence in concentration-critical vials. Allergic reactions as an application segment shows the steepest volume trajectory, propelled by rising anaphylaxis incidence and school-based epinephrine access legislation.
FDA cGMP enforcement for sterile compounding, EMA's GMP Annex 1 revisions for aseptic manufacturing, and WHO prequalification requirements for emergency medicines collectively elevate barrier costs for new entrants while consolidating procurement around audit-ready suppliers. These frameworks directly shape demand by mandating specific endotoxin limits, stability data packages, and container closure integrity standards that favor vertically integrated manufacturers with in-house analytical capabilities. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs for norepinephrine and dopamine, as divergence in impurity profiling requirements threatens to fragment regulatory submissions and delay market access for reformulated products.
Market Dynamics
Hospital formulary consolidation around pre-filled autoinjector formats is compressing supplier rosters while elevating endotoxin testing and serialization requirements as non-negotiable gatekeepers for contract eligibility.
Growth Catalysts
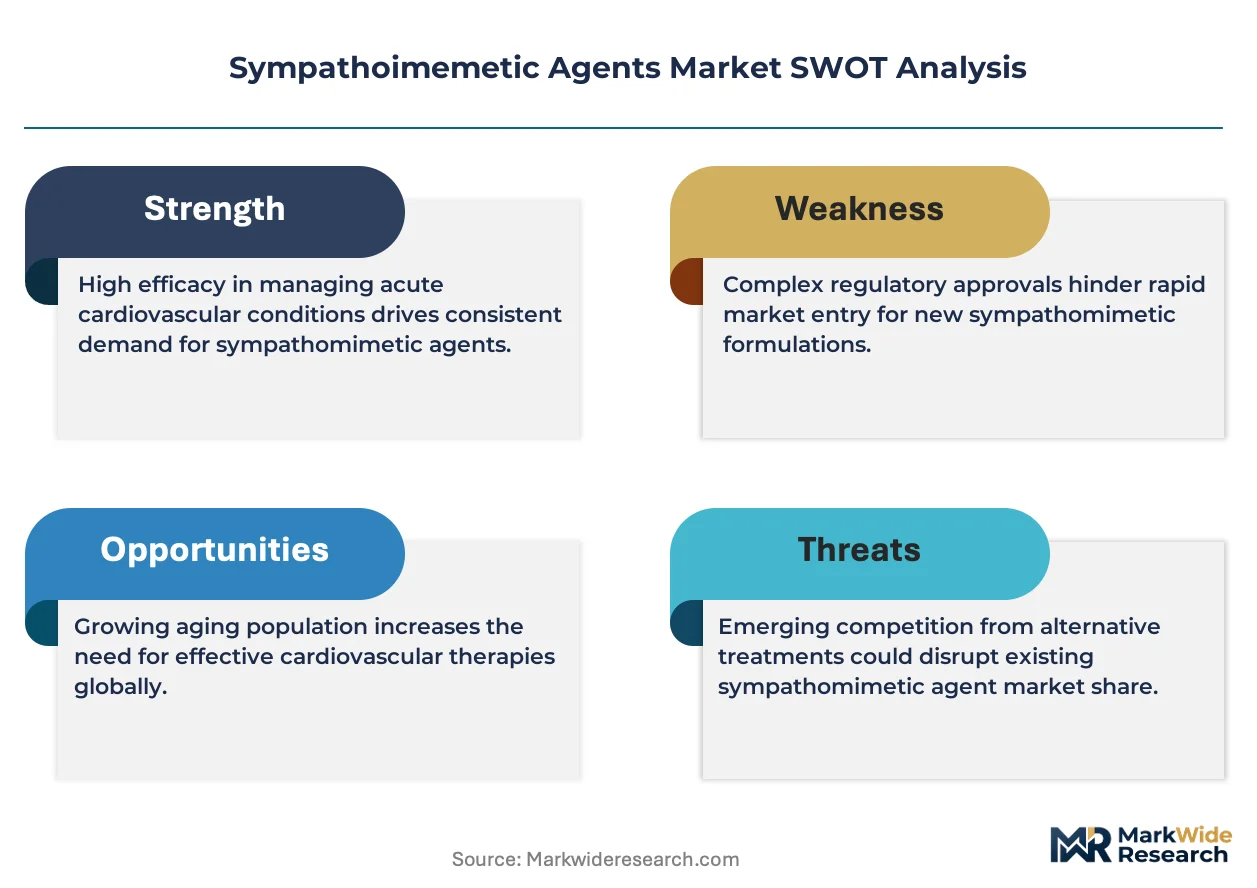
- EMA GMP Annex 1 revisions:The 2022 aseptic processing overhaul mandates continuous environmental monitoring and barrier technology upgrades, filtering out undercapitalized compounders and concentrating procurement among audit-validated sterile injectable manufacturers.
- School-based epinephrine access mandates:US state-level legislation requiring stock epinephrine in educational institutions is creating institutional procurement channels distinct from individual patient prescriptions, expanding addressable unit volume.
- Recombinant synthesis platforms:Microbial fermentation routes for catecholamine production are displacing animal-derived extraction, reducing lot-to-lot variability and enabling geographic sourcing diversification away from Chinese porcine adrenal tissue suppliers.
Market Restraints
- API supply concentration:Norepinephrine bitartrate active pharmaceutical ingredient production clusters among three Indian and Chinese contract manufacturers, exposing formulators to geopolitical friction and customs inspection delays.
- Container closure integrity failures:Glass delamination and elastomer extractables in high-concentration catecholamine vials trigger costly recalls and FDA warning letters, elevating total cost of quality ownership.
- Biologics substitution in shock management:Angiotensin II and synthetic vasopressin analogs are capturing refractory septic shock cases previously dominated by norepinephrine first-line protocols, compressing addressable patient days.
Strategic Opportunities
- Brazil ANVISA prequalification pathway:Emergency medicine registration fast-tracks for autoinjector epinephrine open access to Latin America's largest hospital procurement system, currently dependent on imported European supply.
- Drone-enabled emergency distribution:Last-mile aerial delivery networks for anaphylaxis rescue kits bypass pharmacy deserts in rural Australia and sub-Saharan Africa, creating direct-to-institution channels outside wholesale distribution.
- Japan PMDA Sakigake designation:Expedited review for novel delivery mechanisms including needle-free epinephrine powder injectors rewards innovation with six-month market exclusivity premiums.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic technique certification programs cannot replenish operator pools fast enough to match capacity expansion timelines for injectable catecholamine lines.
- Legacy ERP integration with track-and-trace:Serialization mandate compliance requires wholesale replacement of manufacturing execution systems at mid-tier facilities, freezing capital deployment for 18-24 month implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sympathoimemetic Agents Market |
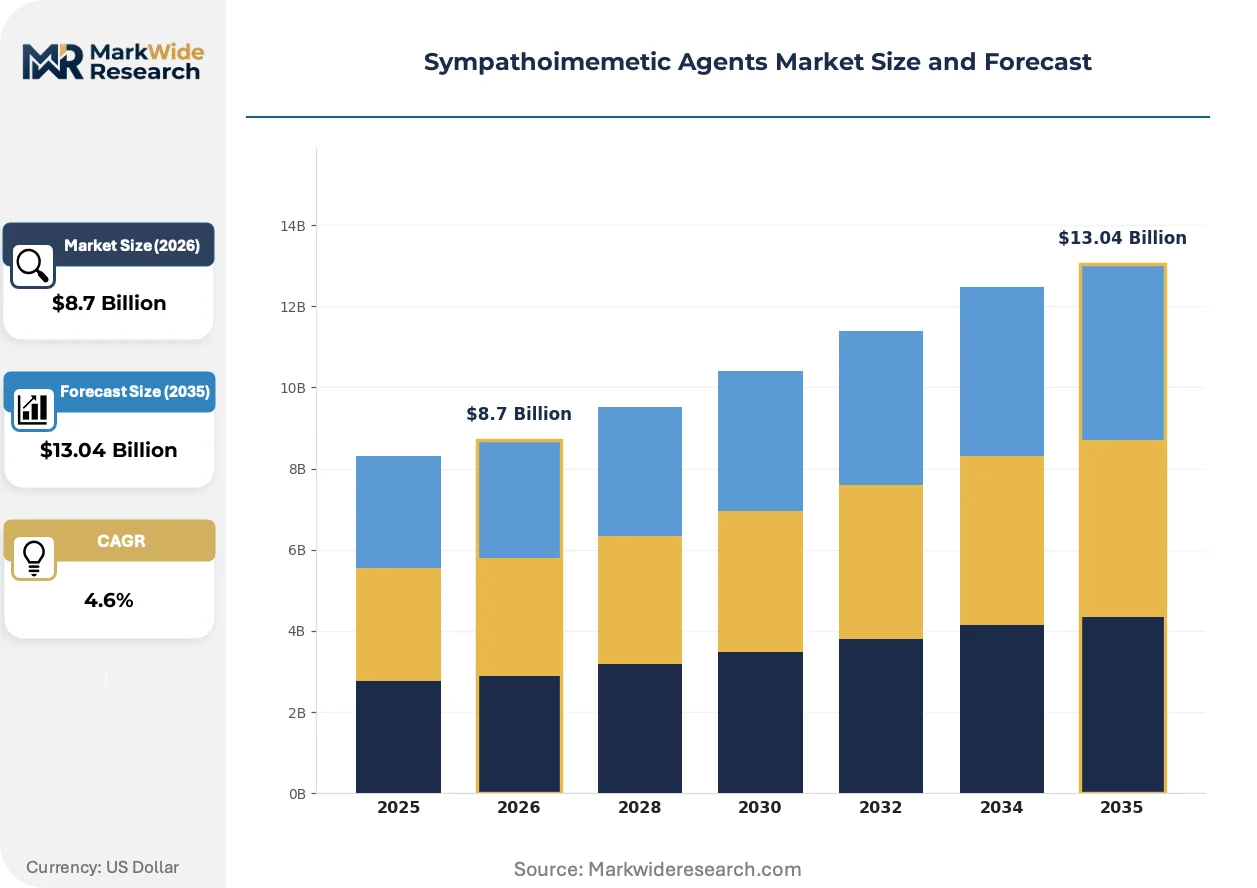
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epinephrine, Norepinephrine, Isoproterenol, Dopamine Application: Cardiac Arrest, Hypotension, Asthma, Allergic Reactions Delivery Mode: Injectable, Oral, Inhalation, Transdermal End User: Hospitals, Clinics, Home Care, Emergency Services |
| Companies Covered | Pfizer, Sanofi, Novartis, Teva, Sterimax, Amneal Biosciences, Bedford Pharmaceuticals, Hikma Pharmaceuticals, Baxter Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sympathoimemetic Agents Market Evolving Landscape
Manufacturing science and emergency care protocols are converging to redefine how sympathomimetic agents reach patients, with implications spanning formulation chemistry, regulatory submission strategy, and distribution infrastructure.
Synthetic norepinephrine bitartrate produced via enzymatic catalysis of glucose-derived precursors is electrifying cost structures for hospital-grade vials, enabling European and North American formulators to bypass porcine tissue supply chains entirely. Academic medical centers in Germany and the Netherlands are qualifying these recombinant batches for cardiogenic shock protocols previously restricted to traditional extraction-derived API. The technology is electrifying competitive positioning by decoupling production geography from agricultural commodity markets.
FDA's 2023 draft guidance on post-approval manufacturing changes for sterile injectables tightens comparability protocol requirements for catecholamine concentration and impurity profiles, extending supplemental approval timelines by 8-14 months for reformulated products. The industrial consequence is freezing of legacy vial specifications and accelerated investment in continuous manufacturing platforms that reduce batch-to-batch variation below detectable thresholds. Hospital purchasing committees are responding by locking multi-year contracts with suppliers demonstrating validated continuous processing.
Emergency department buyers are consolidating autoinjector procurement through group purchasing organizations, displacing fragmented hospital-by-hospital tendering with centralized formulary decisions covering 200-400 facility networks. The channel being disrupted is independent distributor relationships; what replaces it is direct manufacturer-GPO contracting with penalty clauses for stockout events. This concentration is most visible in the United States, where three national GPOs now control 85 percent of acute care epinephrine unit volume.
Sympathoimemetic Agents Market Segmentation
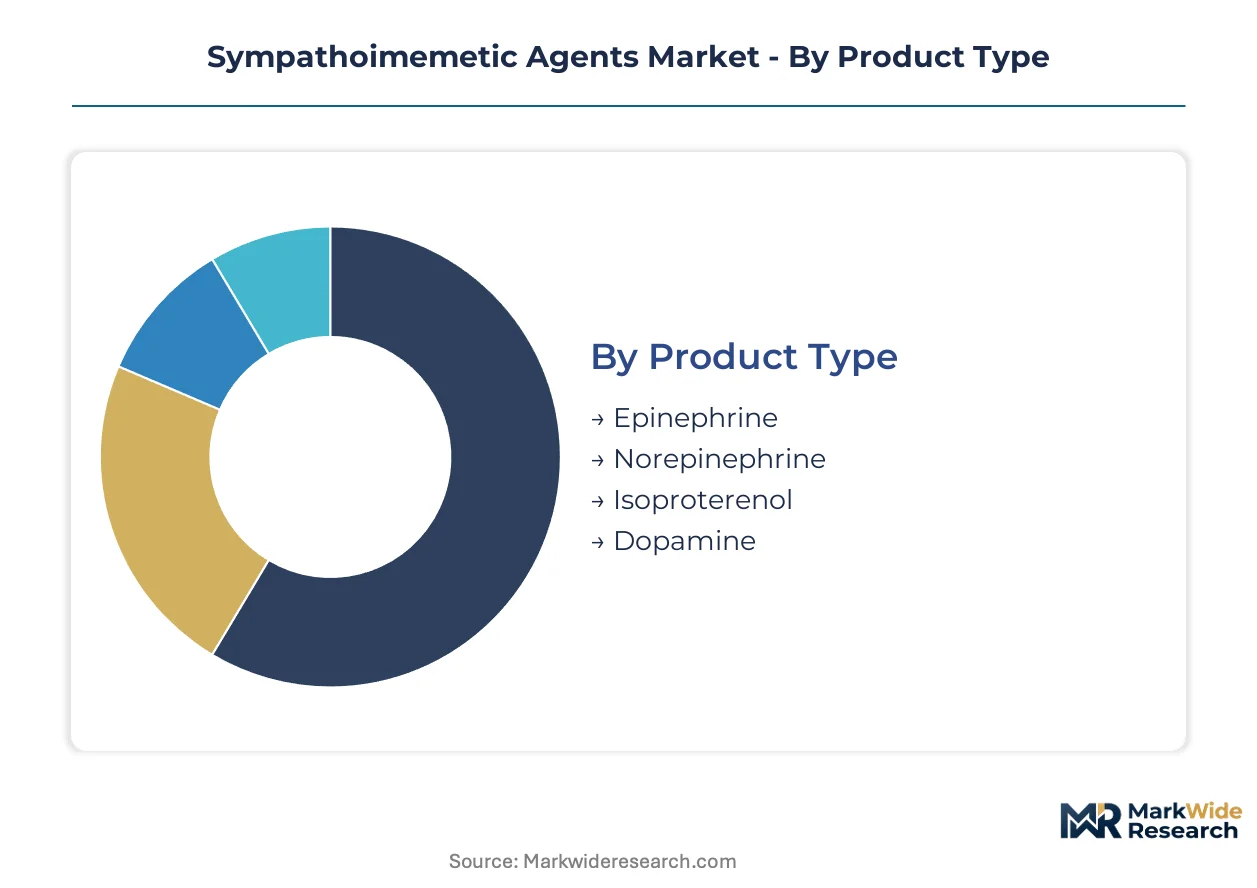
Sympathomimetic agents fragment across four structural axes that determine pricing power, regulatory burden, and distribution economics. Product chemistry dictates manufacturing complexity and API sourcing strategy. Delivery mode shapes sterility requirements and channel access. Application severity determines reimbursement tier and procurement urgency.
Product Type:
Synthetic route and receptor selectivity define cost position and clinical positioning across the catecholamine portfolio.
- Epinephrine:Dual alpha-beta adrenergic agonist formulated as bitartrate salt for parenteral delivery. Demand concentrates in emergency departments and school-based stock programs across the United States, driven by legislative mandates for anaphylaxis rescue access and zero-tolerance stockout protocols.
- Norepinephrine:Predominant alpha-adrenergic vasopressor for septic and cardiogenic shock management, requiring cold-chain distribution and light-protective packaging. German and Dutch academic medical centers are qualifying recombinant synthetic batches, displacing traditional porcine-derived extraction.
- Isoproterenol:Non-selective beta-agonist for bradyarrhythmia and bronchospasm rescue, limited by arrhythmogenic liability to monitored care settings.
- Dopamine:Dose-dependent receptor profile spanning renal, cardiac, and vascular effects, deployed in ICU hemodynamic protocols with declining preference versus norepinephrine first-line therapy.
Mature deployment sits with norepinephrine in hospital shock protocols. Newer deployment is concentrated in epinephrine autoinjector formats for community emergency access.
Application:
Clinical urgency and reimbursement intensity vary sharply across indication severity, fragmenting procurement behavior and margin capture.
- Allergic Reactions:Anaphylaxis termination commands premium pricing for rapid-onset delivery, with institutional procurement through group purchasing organizations displacing fragmented hospital tendering. US state legislation requiring stock epinephrine in educational institutions is expanding addressable unit volume outside traditional prescription channels.
- Hypotension:Chronic vasopressor support in ICU settings generates recurring volume through multi-day infusion protocols, with procurement locked to formulary-preferred concentrations and container specifications.
- Cardiac Arrest:ACLS-mandated epinephrine dosing in resuscitation protocols creates non-discretionary demand tied to emergency kit replenishment cycles.
- Asthma:Acute bronchospasm reversal competes with inhaled beta-agonist alternatives, limiting parenteral sympathomimetic use to refractory emergency presentations.
Revenue concentration sits with hypotension management in acute care. Steepest expansion trajectory is emerging in allergic reaction applications propelled by community emergency access mandates.
Delivery Mode:
Regulatory burden and sterility assurance requirements scale with invasiveness and concentration-critical dosing.
- Injectable:Sterile solutions for intravenous or intramuscular administration dominate hospital procurement, capturing the largest margin pool given FDA cGMP and EMA GMP Annex 1 compliance costs and preference for rapid hemodynamic control.
- Inhalation:Metered-dose and nebulized formulations for bronchospasm management compete with inhaled corticosteroid combinations, with procurement concentrated in ambulatory respiratory clinics.
- Oral:Limited bioavailability and extensive first-pass metabolism restrict oral sympathomimetics to decongestant applications outside acute care.
- Transdermal:Patch delivery for chronic hypotension remains experimental, with no approved products in major markets.
Established revenue sits with injectable formats in acute care. Emerging development is concentrated in needle-free powder injection systems seeking Japan PMDA Sakigake designation.
End User:
Purchasing authority and technical capability determine product format preference and contract structure.
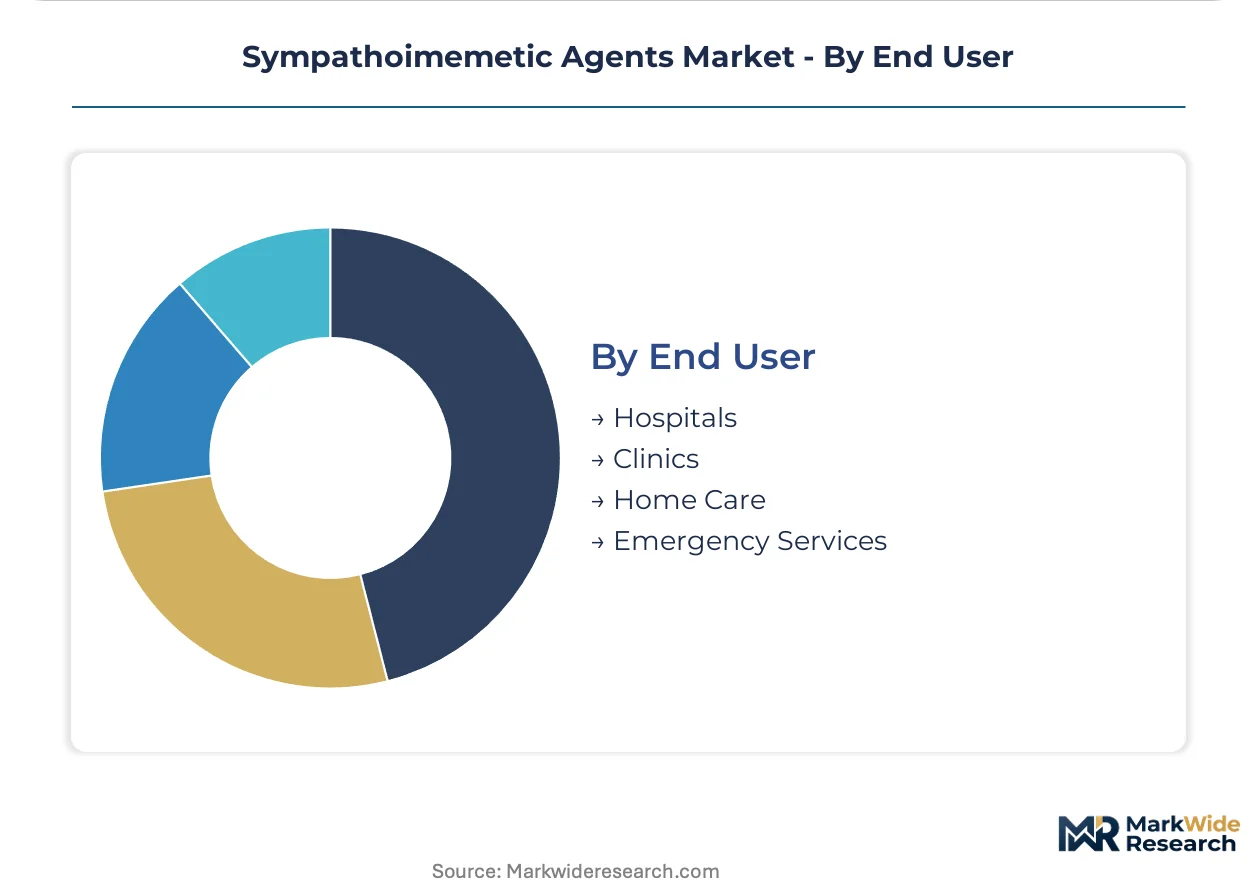
- Hospitals:Centralized pharmacy and therapeutics committees control formulary access, with group purchasing organization consolidation reducing supplier rosters to audit-validated sterile injectable manufacturers.
- Emergency Services:Pre-hospital protocols mandate autoinjector carriage, with procurement through municipal and regional emergency medical services authorities.
- Clinics:Ambulatory settings favor multi-dose vials for cost efficiency, with limited autoinjector stocking due to lower anaphylaxis incidence.
- Home Care:Patient-carried epinephrine autoinjectors generate retail pharmacy volume, with insurance prior authorization requirements creating access friction.
Procurement volume concentrates in hospital systems. Fastest-growing deployment is emerging in emergency services channels driven by pre-hospital protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement of autoinjector epinephrine concentrates in the United States, Germany, and Japan, where aging populations with cardiovascular comorbidities sustain chronic hypotension therapy requirements. Regulatory inspection regimes in these markets are tightening purity standards for norepinephrine and dopamine formulations.
United States
FDA cGMP enforcement for sterile compounding and school-based epinephrine access mandates drive institutional procurement channels. State-level legislation requiring stock epinephrine in educational institutions expands addressable unit volume outside traditional prescription channels. Greater Boston's academic medical centers qualify recombinant synthetic batches for cardiogenic shock protocols.
Germany
EMA GMP Annex 1 revisions mandate continuous environmental monitoring and barrier technology upgrades for aseptic processing. German academic medical centers lead qualification of enzymatic catalysis-derived norepinephrine bitartrate for hospital-grade vials. The Rhine-Ruhr industrial corridor anchors sterile injectable manufacturing infrastructure serving European distribution networks.
Japan
PMDA Sakigake designation expedites review for novel delivery mechanisms including needle-free epinephrine powder injectors. Aging demographics sustain chronic hypotension therapy requirements in ICU settings. The Kanto region around Tokyo concentrates pharmaceutical manufacturing execution systems compliance for serialization mandates.
India
Norepinephrine bitartrate active pharmaceutical ingredient production clusters among contract manufacturers serving formulators globally. CDSCO regulatory harmonization with USP and EP monographs shapes impurity profiling requirements for export-oriented suppliers. Hyderabad and Ahmedabad host sterile compounding facilities targeting Middle Eastern and African distribution partnerships.
Brazil
ANVISA prequalification pathways for emergency medicine registration fast-tracks autoinjector epinephrine access to Latin America's largest hospital procurement system. Municipal emergency medical services authorities drive pre-hospital protocol expansion for autoinjector carriage. São Paulo's pharmaceutical distribution infrastructure manages last-mile delivery to pharmacy-desert regions.
Sympathoimemetic Agents Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers upgrade barrier technology and continuous processing platforms to meet EMA GMP Annex 1 revisions. The vendor base concentrates around audit-validated sterile injectable specialists with in-house analytical capabilities, filtering out undercapitalized compounders. Three archetypes define competitive positioning: vertically integrated pharmaceutical conglomerates, regional generic specialists, and contract manufacturing organizations. M&A activity and strategic partnerships concentrate procurement power among group purchasing organizations while technology licensing agreements proliferate for recombinant synthesis platforms.
Among pharmaceutical conglomerates, Pfizer leverages sterile injectable infrastructure to sustain hospital contract positions, while Teva competes aggressively in generic epinephrine vial segments. Hikma Pharmaceuticals anchors Middle Eastern and African distribution through regional manufacturing partnerships. These three represent distinct archetypes: the scale-driven integrated manufacturer, the price-competitive generic specialist, and the geography-focused regional distributor.
| Leading Market Players |
|---|
| Pfizer |
| Sanofi |
| Novartis |
| Teva |
| Sterimax |
| Amneal Biosciences |
| Bedford Pharmaceuticals |
| Hikma Pharmaceuticals |
| Baxter Laboratories |
| Others |
Value Network & Pricing Analysis
EMA GMP Annex 1 revisions for sterile aseptic processing gate qualified supply access and premium-tier hospital contract eligibility, compressing procurement rosters to manufacturers with validated barrier technology and continuous environmental monitoring infrastructure. Formulators lacking audit-ready sterile injectable capabilities face exclusion from group purchasing organization tenders, while certified suppliers command contract premiums for endotoxin-compliant norepinephrine and epinephrine vials.
Pricing Analysis
Volume-margin splits concentrate procurement power among three archetypes: audit-validated sterile injectable specialists capturing premium hospital-GPO contracts, price-competitive generic vial suppliers serving ambulatory clinics, and regional distributors managing emergency services autoinjector tenders. Price differentiation hinges on FDA cGMP certification tier and cold-chain assurance capability, with US academic medical centers least sensitive and Latin American municipal buyers most responsive to unit cost. Cost compression in standard-grade vials intensifies as Teva and Amneal Biosciences compete on generic epinephrine pricing, while premium autoinjector formats sustain margin pools through legislated school-stock mandates.
Supply Chain Analysis
Dual-sourcing requirements from hospital purchasing committees mandate qualified backup suppliers for norepinephrine bitartrate API, reducing single-source vulnerability despite concentration in Indian and Chinese contract manufacturers. Active pharmaceutical ingredient production draws from porcine adrenal tissue extraction in China, recombinant enzymatic synthesis in Germany and the Netherlands, and synthetic chemical routes in India. Tariff exposure on Chinese-sourced starting materials threatens cost stability for traditional extraction-dependent formulators. Distribution runs through group purchasing organization central warehouses to hospital pharmacy systems, with emergency services procurement bypassing wholesale channels through direct municipal contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic manufacturing workforce scarcity props pricing for qualified sterile injectable supply, constraining capacity expansion timelines and sustaining contract premiums for audit-validated manufacturers.
For Market Incumbents: Extend barrier technology certification across European and North American manufacturing sites to lock multi-year GPO contracts before EMA GMP Annex 1 enforcement deadlines. Secure captive recombinant synthesis capacity through technology licensing or backward integration into enzymatic catalysis platforms, displacing porcine tissue supply exposure. Biologics substitution in septic shock management threatens norepinephrine volume; defend position through ICU protocol sponsorship and real-world evidence generation for refractory cases. For New Entrants and Emerging Players: Direct-to-institution digital procurement platforms offer white-space entry for drone-enabled emergency distribution in rural Australia and sub-Saharan Africa pharmacy deserts. Target Brazil ANVISA prequalification for autoinjector epinephrine fast-track registration, accessing Latin America's largest hospital procurement system currently dependent on European import supply. Municipal emergency medical services authorities represent the most penetrable buyer segment given fragmented pre-hospital procurement and limited incumbent contract lock-in. For Investors and Strategic Acquirers: FDA warning letters issued to sterile compounding facilities are the leading indicator that audit-validated manufacturing capacity will command acquisition premiums. The 5-10 year viability window favors contract manufacturing organizations with in-house analytical capabilities and existing hospital-GPO relationships. Target acquisition profile centers on mid-tier sterile injectable specialists lacking serialization compliance but possessing validated aseptic lines suitable for continuous manufacturing retrofit. Watch for EMA GMP Annex 1 compliance cost disclosures as the signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Platform Deployment | FDA draft guidance on post-approval changes rewards validated continuous processing with reduced batch variation and faster supplemental approvals. |
| Recombinant Synthesis Technology Licensing | Enzymatic catalysis routes decouple European formulators from Chinese porcine tissue supply chains and agricultural commodity volatility. |
| Group Purchasing Organization Direct Contracting | Three national GPOs control 85 percent of US acute care epinephrine volume, displacing independent distributor relationships. |
| Needle-Free Delivery Mechanism Development | Japan PMDA Sakigake designation offers six-month market exclusivity premiums for novel powder injector formats. |
| Serialization Mandate Compliance Investment | EMA Falsified Medicines Directive and US DSCSA requirements freeze capital deployment for 18-24 month ERP replacement windows. |
Research Methodology
Document review covered FDA cGMP inspection records, EMA GMP Annex 1 revision drafts, and WHO prequalification emergency medicine standards, complemented by interviews with hospital pharmacy directors, sterile manufacturing quality heads, GPO contracts managers, and regulatory affairs leads at formulators. Secondary validation drew from USP monograph updates, pharmacopeial harmonization working papers, and customs trade data on norepinephrine bitartrate API shipments. Bottom-up demand modeling for autoinjector and vial formats triangulated against top-down hospital procurement database aggregation.
Cross-referencing historical volume trends with panel input from formulary committees and emergency department buyers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry, delivery mode, application severity, and end-user purchasing authority, with regional regulatory cluster effects layered across United States, Germany, Japan, India, and Brazil markets. CAGRs derived from compound growth trajectory fitting to hospital admission patterns, anaphylaxis incidence surveillance, and school-based epinephrine mandate legislative tracking.
The model holds under sustained EMA GMP enforcement and FDA sterile compounding oversight; deviation in pharmacopeial monograph harmonization or major API supply disruption would shift volume and value outputs. Forecasts reflect assumptions on regulatory inspection intensity, workforce certification pipeline throughput, and recombinant synthesis scale-up timelines. A model refresh is warranted upon material change in FDA warning letter issuance patterns or ANVISA prequalification pathway expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Ceftriaxone Market