
 APOL1 Mediated Kidney Disease Market | 2026-2036
APOL1 Mediated Kidney Disease Market Size, Share, and Industry Trends Forecast 2026-2036
APOL1 Mediated Kidney Disease Market Outlook
Single-source reliance on academic biotech spinouts is recalibrating toward multi-source partnerships between large pharma and gene-editing platforms. Vertex Pharmaceuticals leverages its cystic fibrosis cash flows to anchor kidney disease expansion. Maze Therapeutics competes through differentiated small-molecule discovery against APOL1 protein variants. AstraZeneca sustains nephrology relevance via its Farxiga franchise infrastructure and emerging APOL1 alliances.
APOL1 mediated kidney disease encompasses progressive renal dysfunction driven by two gain-of-function coding variants (G1 and G2) in the apolipoprotein L1 gene, which trigger podocyte injury through ion channel dysregulation and autophagy disruption. Gene therapies command premium development investment due to curative potential, while small molecules retain near-term commercial viability through oral delivery scalability. Hospitals dominate end-user demand as biopsy-confirmed diagnosis and infusion administration concentrate in tertiary nephrology centers. Intravenous delivery currently anchors revenue but subcutaneous formulations are gaining fastest as patient convenience pressures intensify.
FDA orphan drug incentives and EMA PRIME eligibility reshape competitive timelines by accelerating review for APOL1-targeted candidates. The country's national pharmaceutical regulator in Japan and Health Canada align with ICH efficacy endpoints, reducing redundant trial design for sponsors pursuing multi-regional filings. Stakeholders must monitor biomarker-qualified surrogate endpoints and payer willingness to reimburse genotype-specific therapies ahead of long-term cardiovascular outcome data.
Market Dynamics
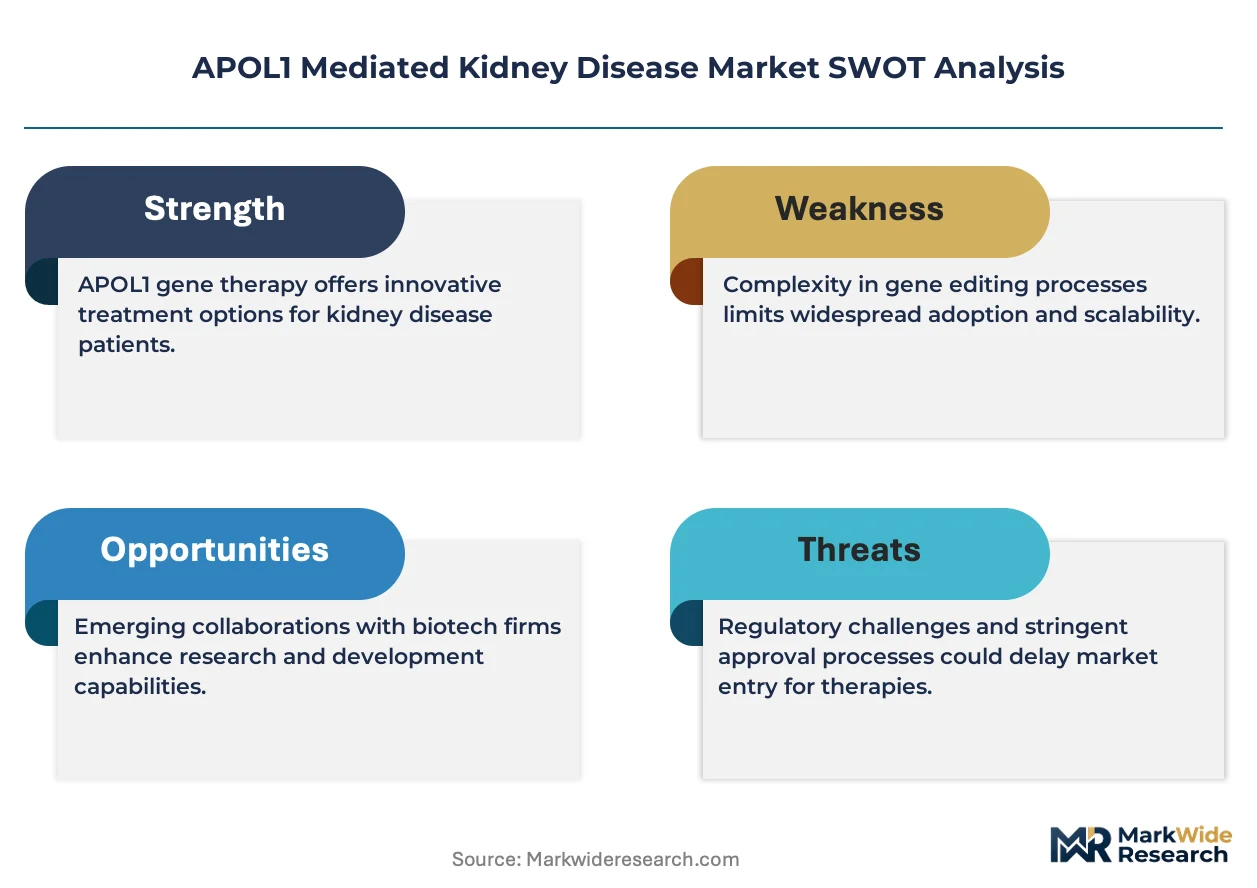
Precision nephrology pipelines are redirecting R&D capital toward genotype-specific therapeutics as orphan drug incentives compress development timelines for APOL1-targeted modalities. Biopharma sponsors now prioritize biomarker-qualified surrogate endpoints over traditional cardiovascular outcome studies to accelerate regulatory submissions.
Growth Catalysts
- FDA Orphan Drug Designation:The FDA's streamlined review pathways and tax credits for rare disease indications reduce clinical trial costs for APOL1-targeted programs, accelerating sponsor investment decisions.
- Podocyte biology advances:Cryo-electron microscopy and single-cell RNA sequencing now resolve APOL1 variant protein structures, enabling rational drug design against gain-of-function mechanisms.
- United States patient advocacy networks:African ancestry community organizations drive clinical trial enrollment and payer education campaigns, expanding addressable diagnosed populations.
Market Restraints
- Biopsy dependency:Definitive APOL1-mediated diagnosis requires renal tissue sampling, limiting screening scalability in primary care settings and concentrating diagnosis in tertiary centers.
- Gene therapy manufacturing:Viral vector production capacity constraints in North America and Europe create supply bottlenecks for curative APOL1 programs, extending development timelines.
- Reimbursement uncertainty:CMS and commercial payers lack established frameworks for genotype-specific chronic disease therapies, creating pricing volatility risk for sponsors.
Strategic Opportunities
- Sub-Saharan Africa screening infrastructure:High APOL1 risk variant prevalence in Nigeria, Ghana, and Kenya creates untapped demand for population genomics and early intervention programs.
- Subcutaneous formulation development:Transition from intravenous to subcutaneous delivery platforms reduces infusion center dependency and expands community nephrology access.
- EMA PRIME eligibility:Priority medicines status accelerates EMA scientific advice and accelerated assessment pathways for APOL1 candidates targeting unmet renal need.
Industry Challenges
- Nephrogenomics talent scarcity:The intersection of renal physiology, computational genomics, and regulatory science lacks trained specialists, constraining sponsor hiring pipelines.
- Longitudinal outcome data gaps:APOL1 variant carriers require decade-plus follow-up to demonstrate therapy impact on end-stage renal disease progression, complicating payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APOL1 Mediated Kidney Disease Market |
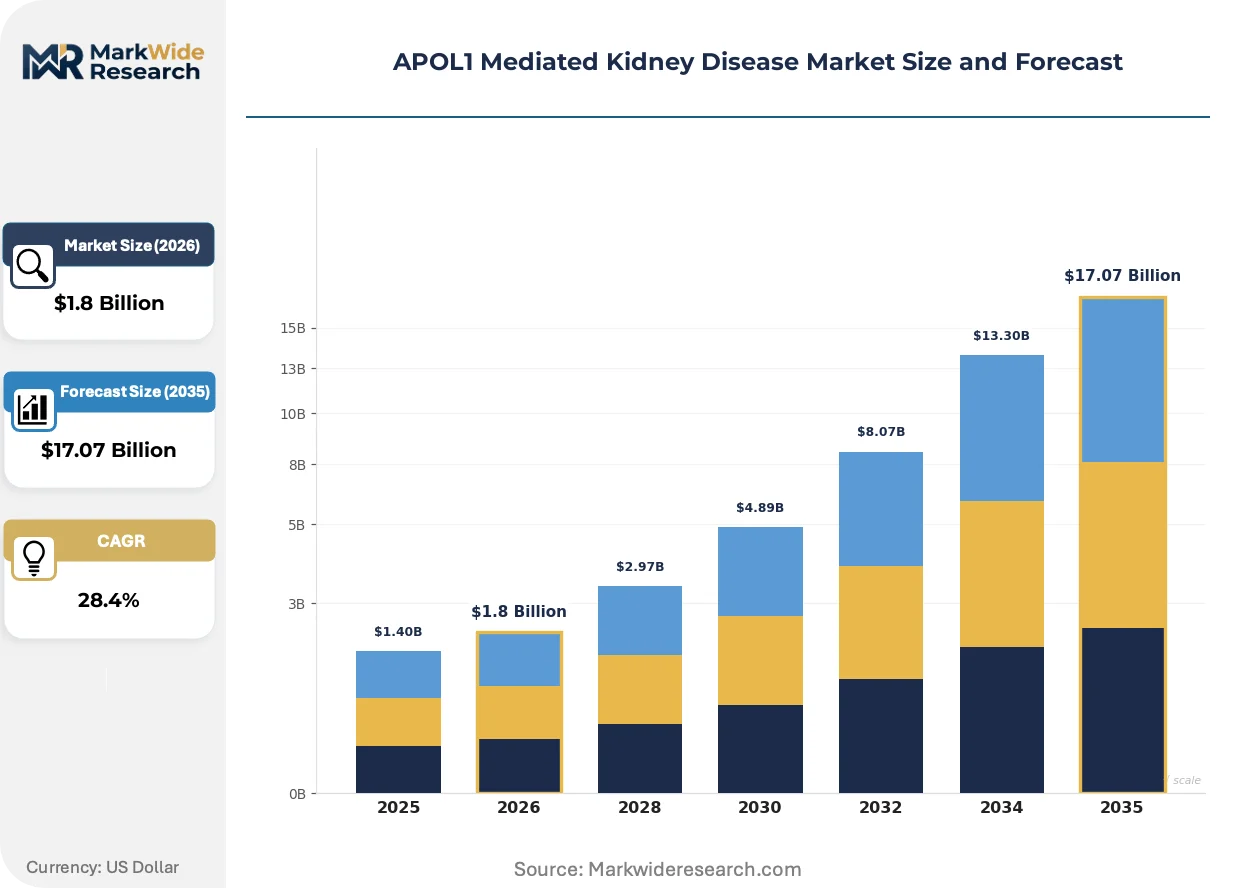
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Gene Therapies, Combination Therapies Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Clinics, Hospitals, Research Institutions, Home Care Therapy Area: Renal Disorders, Cardiovascular Conditions, Genetic Disorders, Autoimmune Diseases |
| Companies Covered | Vertex Pharmaceuticals, Maze Therapeutics, AstraZeneca, Novartis, Pfizer, Regeneron Pharmaceuticals, Ionis Pharmaceuticals, Biogen, Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APOL1 Mediated Kidney Disease Market Strategic Shifts
Gene-editing platforms and small-molecule discovery engines are converging on APOL1 protein modulation, reshaping competitive positioning between curative and chronic management approaches. Technology choices now determine partnership structures and capital allocation priorities.
Base-editing technologies are absorbing development investment as precision tools for reverting APOL1 risk variants to wild-type sequences without double-strand breaks. Academic medical centers in Boston and San Francisco are establishing first-in-human trial infrastructure for these programs. The technology is absorbing capital that previously flowed toward CRISPR-Cas9 knockdown approaches, compressing the addressable market for transient gene silencing.
The FDA's Breakthrough Therapy designation pathway is expanding eligibility criteria for APOL1-mediated kidney disease candidates that demonstrate early biomarker response. Sponsors now structure Phase 2 trials around albuminuria reduction rather than composite renal endpoints. Tertiary nephrology centers in the United States are responding by building dedicated genotype-directed trial units with embedded genetic counseling.
Hospital procurement committees are fragmenting purchasing authority for APOL1 therapies across pharmacy, nephrology, and precision medicine departments. Traditional centralized formulary decisions are yielding to disease-specific budget allocations tied to genetic testing infrastructure. This pattern is most visible in integrated delivery networks across California and Texas, where risk-bearing contracts create incentives for genotype-targeted therapeutic selection.
APOL1 Mediated Kidney Disease Market Segmentation
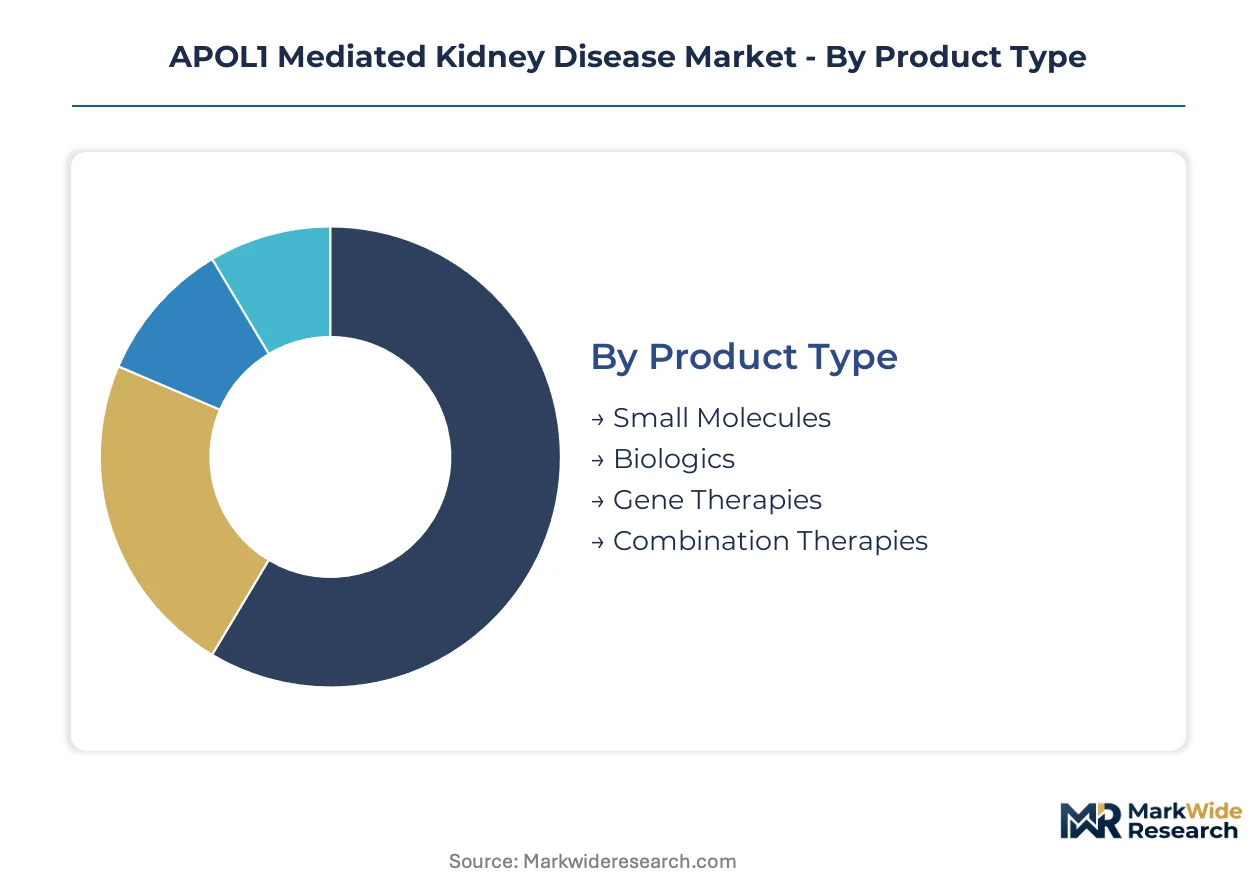
APOL1 therapeutic development demands precise segment targeting as modality choices determine manufacturing scale, regulatory pathways, and reimbursement negotiations. Product type and delivery mode selections directly constrain which patient populations sponsors can reach and which clinical settings will administer treatment.
Product Type:
Technology platforms differentiate on curative intent versus chronic management feasibility, with manufacturing complexity and dosing frequency driving capital allocation decisions across development portfolios.
- Small Molecules:Orally bioavailable compounds target APOL1 protein ion channel dysfunction through allosteric modulation. Demand concentrates in United States community nephrology practices where pill burden and infusion center access limit patient compliance with parenteral alternatives. Vertex Pharmaceuticals and Maze Therapeutics anchor competitive positioning through differentiated binding kinetics.
- Gene Therapies:Viral vector delivery of APOL1-targeting constructs offers potential functional cure through variant silencing or base editing. Manufacturing capacity constraints in North American contract development organizations restrict supply scalability despite premium pricing power. Academic medical centers in Boston and San Francisco establish first-in-human infrastructure for these programs.
- Biologics:Monoclonal antibodies and recombinant proteins modulate APOL1-mediated inflammatory cascades with established CMC frameworks.
- Combination Therapies:Small-molecule and biologic pairings address polygenic renal risk through complementary mechanisms.
Mature deployment sits with Small Molecules. Newer deployment is concentrated in Gene Therapies.
Delivery Mode:
Administration route determines site-of-care economics and patient adherence profiles, with convenience pressures reshaping formulation development priorities across sponsor pipelines.
- Intravenous:Infusion center administration dominates current revenue for APOL1-targeted biologics and gene therapies. Hospitals in California and Texas integrated delivery networks capture concentrated purchasing authority through dedicated nephrology pharmacy budgets. Tertiary centers require embedded genetic counseling infrastructure to support genotype-directed therapy selection.
- Subcutaneous:Self-administered injection platforms reduce infusion center dependency and expand access to community nephrology settings. Formulation development absorbs R&D investment as sponsors target patient convenience differentiation. Prefilled syringe and autoinjector device partnerships with contract manufacturers accelerate.
- Oral:Small-molecule candidates leverage established tableting and coating technologies for scalable production.
- Topical:Transdermal delivery remains exploratory for APOL1-related cutaneous manifestations.
Volume concentration favors Intravenous administration. Steepest expansion trajectory belongs to Subcutaneous platforms.
End User:
Care setting fragmentation reflects diagnostic complexity and therapy administration requirements, with procurement authority shifting toward disease-specific budget holders.
- Hospitals:Tertiary nephrology centers perform biopsy-confirmed APOL1 diagnosis and administer infusion-based therapies. Pharmacy and precision medicine departments fragment purchasing authority away from traditional centralized formularies. Risk-bearing contracts in United States integrated delivery networks incentivize genotype-targeted therapeutic selection.
- Clinics:Community nephrology practices drive oral small-molecule demand where infusion infrastructure is absent. African ancestry patient advocacy networks concentrate enrollment and payer education campaigns in urban clinic settings.
- Research Institutions:Academic medical centers host genotype-directed trial units with embedded genetic counseling.
- Home Care:Subcutaneous self-administration expands addressable settings beyond institutional boundaries.
Revenue concentration remains with Hospitals. Fastest patient volume growth is emerging in Clinics.
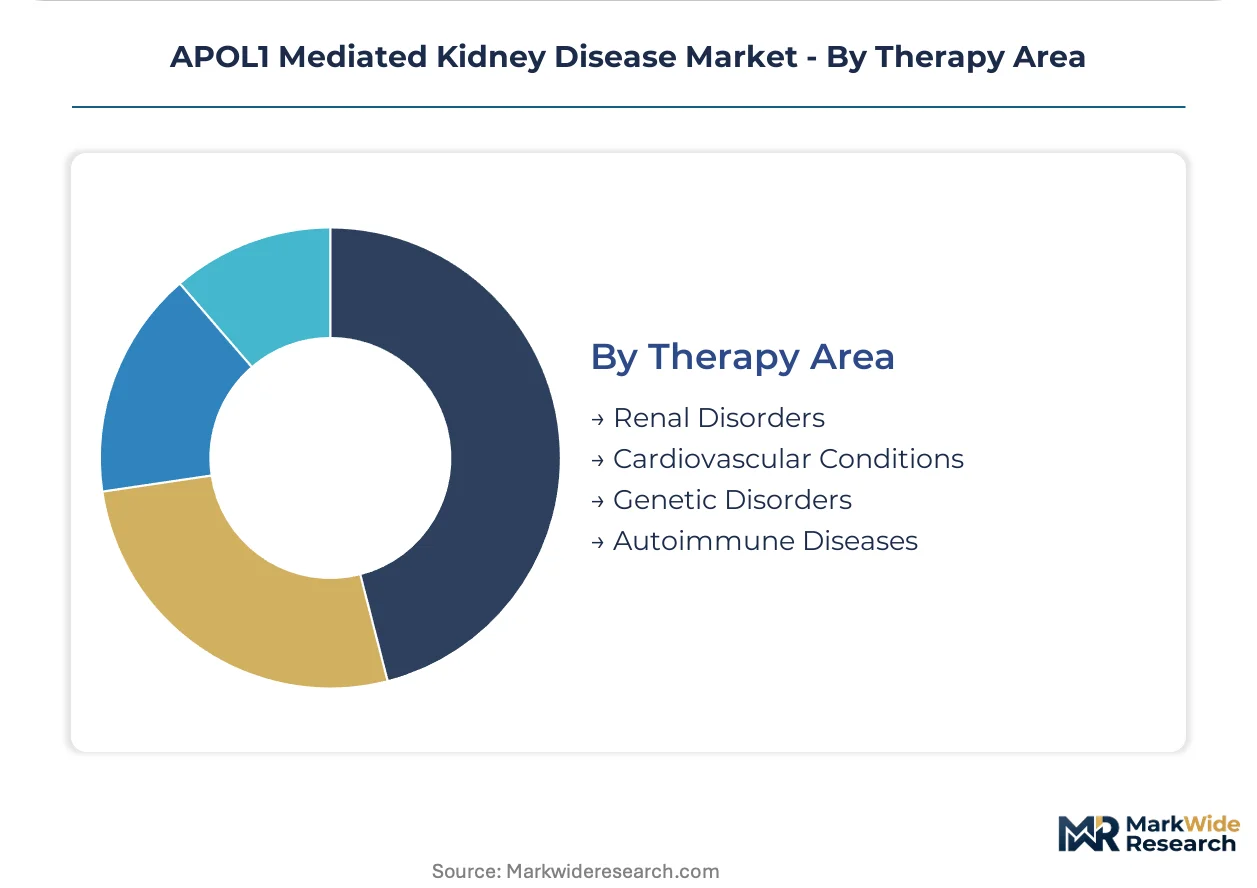
Therapy Area:
Indication breadth extends APOL1 variant relevance beyond primary renal pathology into cardiovascular and systemic autoimmune manifestations, broadening addressable populations.
- Renal Disorders:Focal segmental glomerulosclerosis and hypertension-attributed nephropathy constitute core APOL1-mediated indications. FDA orphan drug designation streamlines development timelines for genotype-specific candidates targeting progressive renal dysfunction. Albuminuria reduction serves as biomarker-qualified surrogate endpoint in Phase 2 trial designs.
- Cardiovascular Conditions:APOL1 variant carriers exhibit elevated cardiovascular mortality independent of renal function decline. Payer willingness to reimburse genotype-specific chronic disease therapies remains uncertain ahead of long-term outcome data.
- Genetic Disorders:Population genomics programs in Nigeria and Ghana expand screening infrastructure for risk variant identification.
- Autoimmune Diseases:APOL1-mediated inflammation intersects with lupus nephritis pathophysiology in overlapping patient populations.
Clinical development investment concentrates in Renal Disorders. Expanding most quickly into Cardiovascular Conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for APOL1-targeted therapeutics concentrates in the United States, where elevated risk variant prevalence among African ancestry populations drives clinical trial recruitment and payer prioritization. This geographic concentration shapes regulatory strategy and manufacturing investment across sponsor portfolios. The analysis examines five countries where precision nephrology infrastructure and variant epidemiology create distinct market conditions.
United States
FDA orphan drug designation and Breakthrough Therapy pathways accelerate APOL1 program timelines, while CMS reimbursement frameworks remain unsettled for genotype-specific chronic therapies. Boston and San Francisco academic medical centers establish first-in-human gene-editing trial infrastructure with embedded genetic counseling. Vertex Pharmaceuticals anchors development investment through cystic fibrosis-derived cash flows redirected toward renal expansion.
Germany
EMA PRIME eligibility and centralized health technology assessment processes attract multi-regional trial submissions from APOL1 sponsors seeking accelerated European access. The country's national pharmaceutical regulator aligns with ICH efficacy endpoints, reducing redundant study design for sponsors pursuing EMA filings. Heidelberg and Munich nephrology clusters concentrate precision medicine expertise and genotype-directed patient recruitment.
United Kingdom
NHS Genomic Medicine Service infrastructure supports population screening for APOL1 risk variants in African-Caribbean communities, expanding diagnosed prevalence ahead of therapeutic availability. MHRA post-Brexit regulatory autonomy enables streamlined approval pathways for innovative modalities. London teaching hospitals fragment procurement authority across pharmacy and precision medicine departments, mirroring United States integrated delivery network patterns.
Japan
PMDA Sakigake designation system offers priority review for APOL1 candidates addressing unmet renal need, though variant carrier prevalence remains low in the general population. The country's national pharmaceutical regulator harmonizes with ICH guidelines, facilitating bridge studies for Western-developed programs. Tokyo and Osaka nephrology centers concentrate Asia-Pacific trial site selection for sponsors seeking regulatory diversity.
Nigeria
High APOL1 risk variant prevalence in Lagos and Abuja urban corridors creates untapped demand for population genomics and early intervention infrastructure. The national pharmaceutical regulator develops capacity for clinical trial oversight as biopharma sponsors explore sub-Saharan expansion. Academic partnerships between University College Hospital Ibadan and Western institutions establish screening protocols and biomarker collection frameworks.
APOL1 Mediated Kidney Disease Market Competitive Environment
Strategic partnership formation dominates the current landscape as large pharma secures access to gene-editing platforms and small-molecule discovery engines. The competitive structure organizes around three tiers: cystic fibrosis cash-flow anchors diversifying into nephrology, dedicated rare disease biotechs with differentiated binding kinetics, and platform technology providers licensing editing capabilities. Two dominant competitive moves reshape positioning: multi-source R&D alliances replacing single academic spinout reliance, and subcutaneous formulation investments targeting patient convenience differentiation.
Within the large-pharma-diversification archetype, Vertex Pharmaceuticals and AstraZeneca occupy anchor positions—Vertex leveraging respiratory franchise cash flows for kidney disease expansion, AstraZeneca sustaining nephrology relevance through established diabetes and cardiovascular infrastructure. Maze Therapeutics exemplifies the dedicated biotech tier, competing through small-molecule discovery against APOL1 protein variants. These three entities represent distinct capital allocation philosophies: platform vertical integration, therapeutic area adjacency, and modality-specific specialization.
| Leading Market Players |
|---|
| Vertex Pharmaceuticals |
| Maze Therapeutics |
| AstraZeneca |
| Novartis |
| Pfizer |
| Regeneron Pharmaceuticals |
| Ionis Pharmaceuticals |
| Biogen |
| Gilead Sciences |
| Others |
Value Chain & Pricing Dynamics
Viral vector manufacturing costs cascade through APOL1 gene therapy pricing tiers, with North American contract development organization capacity constraints concentrating premium pricing power among sponsors who secured early manufacturing slots. Small-molecule oral formulations distribute pricing pressure across community nephrology settings where pill burden competes with infusion center economics.
Pricing Analysis
Volume concentration in intravenous biologics competes with margin expansion in subcutaneous and oral formats. Three-tier pricing structure across premium gene therapies, standard biologics, and economy oral small-molecules reflects manufacturing complexity and curative intent. Pricing pressure stems from CMS reimbursement uncertainty for genotype-specific chronic therapies. Community nephrology practices exhibit highest price sensitivity due to fixed reimbursement schedules, while academic medical centers absorb premium pricing for first-in-human programs.
Supply Chain Analysis
Single-source vulnerability sits with North American viral vector production capacity, where Boston and San Francisco academic medical centers anchor first-in-human trial infrastructure. Manufacturing draws from United States, Germany, and Switzerland for clinical-grade plasmid DNA, GMP-grade viral vectors, and fill-finish services. Regulatory restriction risk concentrates in FDA and EMA viral vector inspection backlogs. Distribution runs through hospital pharmacy and precision medicine departments with fragmented purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug designation creates a cost-of-compliance moat that rewards sponsors who navigate accelerated review pathways, while excluding capital-constrained entrants from viable timelines.
For Market Incumbents: Acquire base-editing platform capabilities to secure next-generation APOL1 variant correction positioning against CRISPR-Cas9 knockdown approaches. Secure manufacturing capacity in North American contract development organizations before viral vector supply bottlenecks intensify. Threat substitution from small-molecule convenience requires subcutaneous formulation investment as defensive priority. For New Entrants and Emerging Players: Begin with sub-Saharan Africa population genomics infrastructure in Nigeria and Ghana, where high APOL1 risk variant prevalence meets minimal competitive screening presence. Target urban clinic settings in Lagos and Abuja for early intervention program deployment. Go-to-market angle centers on academic partnerships with University College Hospital Ibadan for biomarker collection frameworks. For Investors and Strategic Acquirers: FDA Breakthrough Therapy designation award is the leading indicator that APOL1 candidate reimbursement negotiations will advance favorably. Long-term viability frames around decade-plus cardiovascular outcome data generation rather than near-term renal endpoint achievement. Acquisition target archetype includes dedicated rare disease biotechs with differentiated small-molecule binding kinetics against APOL1 protein variants. Signal to watch is EMA PRIME eligibility granting for European accelerated assessment pathway access.| Strategic Initiative | Industry Significance |
|---|---|
| Base-Editing Platform Acquisition | Precision variant correction without double-strand breaks differentiates curative positioning against transient silencing approaches. |
| Subcutaneous Formulation Development | Self-administered delivery reduces infusion center dependency and expands community nephrology market access. |
| FDA Breakthrough Therapy Pursuit | Early biomarker response qualification accelerates review timelines for albuminuria reduction endpoints. |
| Sub-Saharan Screening Infrastructure | Population genomics partnerships in Nigeria and Ghana establish first-mover presence in high-prevalence untapped populations. |
| Manufacturing Capacity Reservation | Early viral vector slot securing insulates against North American and European supply bottlenecks constraining gene therapy scale-up. |
Study Parameters
Multi-period observation of clinical trial enrollment velocity, regulatory designation awards, and manufacturing capacity utilization anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork combined with secondary validation against FDA orphan drug filings, EMA PRIME submissions, ClinicalTrials.gov protocols, and formulary database tracking. Bottom-up patient population modeling and top-down therapeutic category sizing provided triangulation across data sources.
Input-output matrix framing connected APOL1 variant prevalence estimates to treatment-eligible populations across renal disorder severity tiers, administration route adoption curves, and regional regulatory cluster pricing differentials. Segmentation dimensions spanned product type, delivery mode, end user setting, and therapy area indication breadth. CAGRs derived from logistic diffusion modeling of genotype-directed therapy penetration against standard-of-care displacement curves. Forecast inputs incorporated biomarker-qualified surrogate endpoint adoption timelines and payer willingness-to-pay evolution for precision nephrology.
Underlying measurement precision varies by segment; gene therapy revenue projections carry wider confidence intervals than small-molecule oral formulations due to manufacturing scale uncertainty. Forecasts reflect assumptions around regulatory pathway success rates and reimbursement framework maturation. Deviation in FDA or EMA viral vector inspection prioritization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Fascioliasis Treatment Market