
 Atrial Septal Defect Market | 2026-2036
Atrial Septal Defect Market Size, Share, and Industry Trends Forecast 2026-2036
Atrial Septal Defect Market Outlook
Hospital procurement for atrial septal defect devices is narrowing around dual-source contracting models that favor suppliers with captive manufacturing. Abbott Laboratories leverages its structural heart portfolio to anchor premium positioning across integrated delivery networks. Medtronic PLC competes through sustained R&D intensity in transcatheter occluder iterations. W. L. Gore & Associates specializes in expanded polytetrafluoroethylene patch materials that dominate surgical closure protocols.
An atrial septal defect is a congenital cardiac anomaly characterized by an abnormal opening in the interatrial septum, typically measuring 5 to 35 millimeters in diameter, permitting pathologic left-to-right shunting that elevates pulmonary blood flow and right heart volume overload. Closure aims to prevent pulmonary hypertension, arrhythmia, and right ventricular dysfunction through transcatheter device implantation or surgical patch repair. Transcatheter devices command the dominant revenue share due to shorter recovery trajectories and expanding eligibility in adult populations with secundum defects. Patch materials retain critical utility in large or fenestrated defects where device anchoring proves anatomically unfeasible. Echocardiography underpins real-time procedural guidance and postoperative surveillance across both intervention pathways.
FDA premarket notification pathways and EU MDR conformity assessment procedures shape product development timelines and clinical evidence requirements for atrial septal defect device manufacturers. The EPA regulates sterilization facility emissions affecting ethylene oxide-dependent supply chains for implantable cardiac devices. Japan's PMDA imposes supplemental local clinical trials that extend market entry intervals relative to Western regulators. Stakeholders must monitor evolving reimbursement thresholds for outpatient catheterization lab procedures versus surgical admissions.
Market Dynamics
Transcatheter closure devices are compressing surgical volumes as catheterization labs expand capacity for adult secundum defect repairs, forcing patch manufacturers to defend surgical niches through fenestrated and large-defect specialization.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited review timelines for novel occluder designs accelerate commercialization of next-generation nitinol wire frames with enhanced biocompatibility coatings.
- Germany's catheterization infrastructure:Tertiary hospitals in Munich and Heidelberg are doubling interventional cardiology suites, creating concentrated demand for device sterilization and procedure training ecosystems.
- Real-time 3D echocardiography:Procedural guidance technology reduces fluoroscopy exposure and enables closure in anatomically complex defects previously routed to surgery.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy sourcing clusters in a limited supplier base expose device manufacturers to raw material price volatility and geopolitical trade friction.
- EU MDR conformity costs:Expanded clinical evidence requirements for Class III implantable devices extend recertification timelines and elevate compliance expenditure for legacy product portfolios.
- Residual shunt limitations:Device migration and incomplete endothelialization in defects exceeding 38 millimeters preserve surgical patch as the standard of care for large fenestrations.
Strategic Opportunities
- Brazil's underpenetrated adult population:Late diagnosis of secundum defects in patients over 40 creates expansion potential for outpatient catheterization programs in São Paulo and Rio de Janeiro.
- Bioresorbable occluder convergence:Magnesium alloy frameworks combined with polymeric matrices promise complete device dissolution, eliminating long-term nickel allergy and MRI compatibility concerns.
- Japan's PMDA conditional approval:Early access pathways for pediatric applications enable commercial presence while completing post-market surveillance for expanded age indications.
Industry Challenges
- Interventional cardiologist training pipelines:Procedural volume requirements for transcatheter ASD certification strain academic medical centers already competing for structural heart fellowship candidates.
- Ethylene oxide sterilization reconfiguration:EPA emission regulations force supply chain restructuring for implantable cardiac devices, requiring capital deployment into alternative terminal sterilization modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrial Septal Defect Market |
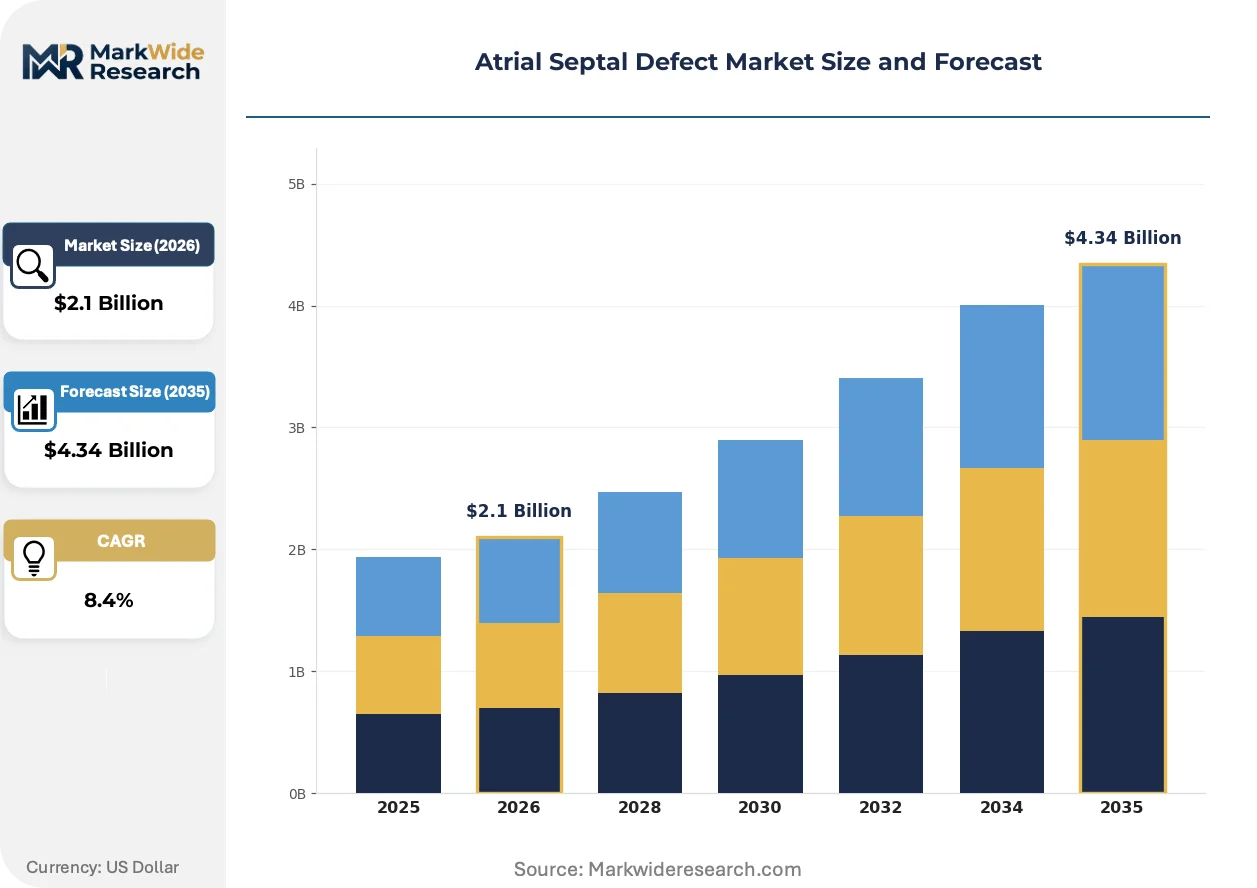
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcatheter Devices, Surgical Closure Devices, Patch Materials, Diagnostic Tools End User: Hospitals, Cardiac Centers, Outpatient Facilities, Research Institutions Technology: Minimal Invasive Techniques, Echocardiography, MRI Imaging, 3D Modeling Application: Pediatric Treatment, Adult Treatment, Preventive Care, Postoperative Monitoring |
| Companies Covered | Abbott Laboratories, Medtronic PLC, W. L. Gore & Associates, Lepu Medical Technology (Beijing) Co., Ltd, Lifetech Scientific, Occlutech GmbH, AtriCure, Carag AG, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrial Septal Defect Market Strategic Shifts
Device architecture is converging with advanced imaging and materials science, compressing procedure times while expanding treatable anatomies beyond conventional secundum boundaries.
Self-expanding nitinol disc technology is hybridizing with electrospun polymer membranes to accelerate endothelial coverage and reduce thrombogenicity. Pediatric cardiology departments in the United States are piloting these hybrid constructs for defects with deficient rims. The structural consequence is a compression of the surgical patch market to complex fenestrated anatomies and concomitant procedures.
EU MDR post-market clinical follow-up requirements are mandating extended surveillance registries for implantable cardiac occluders. Manufacturers must now fund multi-year safety tracking across diverse European populations. High-volume German and Italian centers are responding by consolidating procedural data into national congenital heart networks to satisfy notified body expectations.
Hospital purchasing committees are unbundling device procurement from procedure training and technical support. Integrated delivery networks now negotiate separate contracts for occluder supply, physician proctoring, and complication management protocols. This behavioral shift is most visible in United States IDNs where catheterization lab standardization drives volume commitments across multiple structural heart platforms.
Atrial Septal Defect Market Segmentation
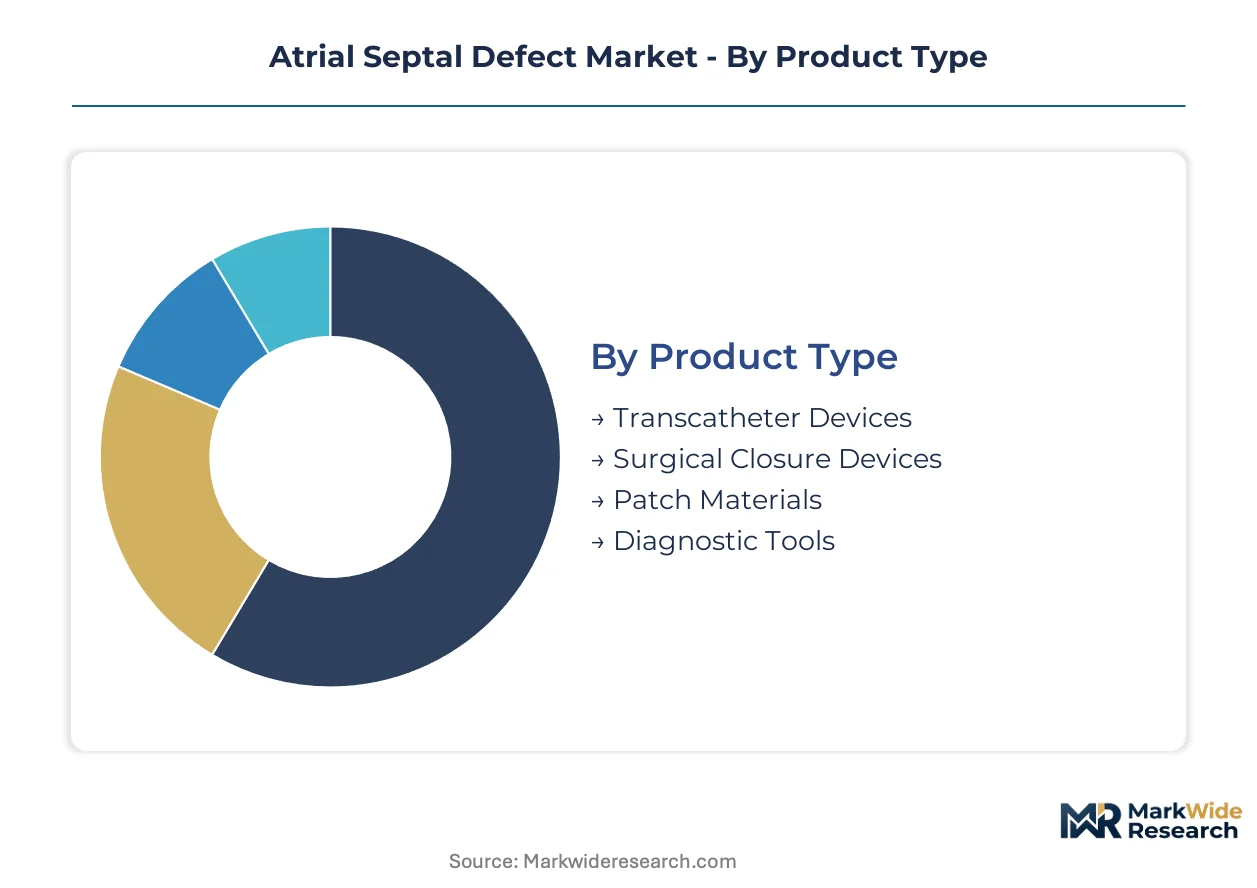
Segmentation in the atrial septal defect market reveals how intervention modality, care setting, and patient demographics reshape procurement patterns and technology investment. Device manufacturers align product portfolios with specific anatomical presentations and reimbursement pathways.
Product Type:
Use-case spectrum spans transcatheter implantation through surgical repair, with material science and delivery mechanism defining clinical positioning.
- Transcatheter Devices:Nitinol wire-frame occluders with polyester fabric membranes deploy through femoral venous access, eliminating sternotomy. United States catheterization labs in tertiary hospitals drive volume through outpatient reimbursement advantages and adult secundum defect eligibility expansion.
- Surgical Closure Devices:Mechanical suturing systems and stapling platforms enable direct atrial wall approximation when device anchoring fails. German cardiac surgery departments in Munich and Heidelberg retain utilization for fenestrated defects exceeding 38 millimeters where endothelialization risks persist.
- Patch Materials:Expanded polytetrafluoroethylene and autologous pericardial constructs address large defects with deficient rims.
- Diagnostic Tools:Intracardiac echocardiography catheters and Doppler flow sensors guide procedural decision-making.
Established volume favors transcatheter devices; emerging adoption favors surgical closure devices in complex anatomical subsets.
End User:
Care setting concentration follows catheterization lab infrastructure density and reimbursement differentiation between inpatient and outpatient episodes.
- Hospitals:Tertiary academic medical centers integrate congenital heart programs with structural heart services, capturing complex cases requiring hybrid operating suites. Japan's university hospitals in Tokyo and Osaka maintain surgical volume through PMDA pediatric indication requirements that delay transcatheter expansion.
- Cardiac Centers:Dedicated congenital heart institutes concentrate procedural volume and fellowship training pipelines.
- Outpatient Facilities:Ambulatory surgical centers in the United States exploit CMS reimbursement codes for elective secundum closures.
- Research Institutions:Pediatric cardiology consortia run extended surveillance registries for EU MDR post-market clinical follow-up mandates.
Procedure economics concentrate demand in cardiac centers; regulatory compliance requirements expand research institution engagement.
Technology:
Imaging and delivery innovation determines treatable anatomical boundaries and operator training requirements.
- Minimal Invasive Techniques:Percutaneous femoral access with transesophageal echocardiography guidance reduces recovery intervals from weeks to days. German interventional cardiology suites in Heidelberg deploy these techniques for adult secundum defects with adequate septal rims.
- Echocardiography:Real-time 3D transesophageal imaging enables defect sizing and device positioning without fluoroscopy dependency.
- MRI Imaging:Cardiac magnetic resonance quantifies right ventricular volume overload and pulmonary flow ratios for treatment timing decisions.
- 3D Modeling:Patient-specific printed septal replicas allow preprocedural device selection and complication anticipation.
Imaging infrastructure investment favors echocardiography; emerging precision favors 3D modeling for complex anatomical planning.
Application:
Patient age and intervention timing reshape device sizing specifications and long-term surveillance protocols.
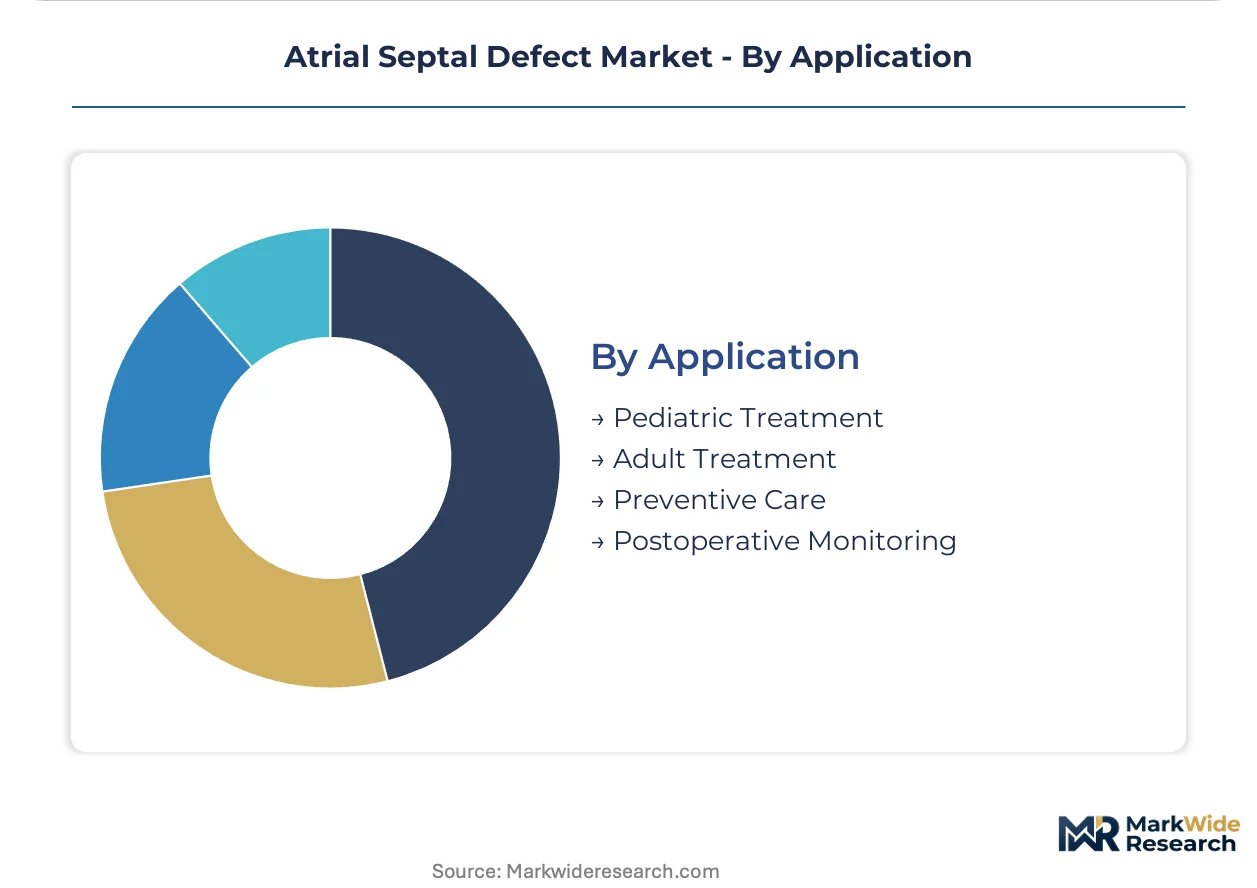
- Pediatric Treatment:Defect closure in patients under 18 requires smaller device footprints and growth-anticipating strategies. Japan's PMDA imposes supplemental local clinical trials that extend pediatric device approval timelines relative to adult indications.
- Adult Treatment:Late-diagnosed secundum defects in patients over 40 drive transcatheter volume through outpatient programs.
- Preventive Care:Screening protocols for pulmonary hypertension risk stratification identify asymptomatic defects before right heart dysfunction develops.
- Postoperative Monitoring:Residual shunt detection and arrhythmia surveillance extend device lifecycle management requirements.
Demographic transition favors adult treatment volume; long-term outcome accountability elevates postoperative monitoring technology demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The catheterization lab density in Heidelberg anchors Germany's interventional cardiology infrastructure, while Tokyo's university hospital network sustains surgical volume through pediatric indication requirements.
United States
Outpatient catheterization programs in tertiary academic medical centers drive transcatheter volume through CMS reimbursement codes for elective secundum closures. FDA breakthrough device designation pathways accelerate commercialization timelines for novel occluder designs. The catheterization lab infrastructure in Boston and Cleveland supports complex congenital interventions with real-time 3D echocardiography guidance.
Germany
Tertiary hospitals in Munich and Heidelberg are doubling interventional cardiology suites, creating concentrated demand for device sterilization ecosystems. EU MDR conformity assessment procedures extend recertification timelines for Class III implantable devices. The cardiac surgery departments in these cities retain surgical patch utilization for fenestrated defects exceeding 38 millimeters.
Japan
PMDA conditional approval pathways enable early commercial presence while post-market surveillance continues for expanded age indications. Supplemental local clinical trials extend pediatric device approval timelines relative to adult indications. University hospitals in Tokyo and Osaka maintain surgical volume through regulatory requirements that delay transcatheter expansion in younger patients.
China
Domestic manufacturers in Beijing and Shenzhen are scaling nitinol wire-frame production for regional supply security. NMPA regulatory pathways for innovative medical devices compress approval intervals for locally developed occluders. The catheterization lab buildout in Shanghai and Guangzhou supports adult secundum defect diagnosis in previously underpenetrated populations over 40.
Brazil
Late diagnosis of secundum defects in patients over 40 creates expansion potential for outpatient catheterization programs. ANVISA regulatory frameworks for imported cardiac devices require local representation and quality system audits. The interventional cardiology capacity in São Paulo and Rio de Janeiro is scaling through public-private hospital partnerships.
Atrial Septal Defect Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in materials and sterilization services. The vendor base concentrates around diversified structural heart portfolios and captive nitinol supply chains. Three archetypes dominate: diversified cardiovascular conglomerates with congenital portfolios, specialized occluder manufacturers with regional regulatory expertise, and materials science firms with surgical patch dominance. Competitive moves center on catheterization lab standardization contracts and alternative sterilization modality investments.
Within the diversified cardiovascular tier, Abbott Laboratories and Medtronic PLC exemplify platform breadth across interventional and surgical closure pathways. Boston Scientific Corporation occupies a position in structural heart device portfolios with catheterization lab integration capabilities. Among specialized regional manufacturers, Lepu Medical Technology (Beijing) Co., Ltd represents the domestic Chinese supply chain archetype with NMPA pathway expertise. W. L. Gore & Associates anchors the materials science tier with expanded polytetrafluoroethylene specialization for surgical protocols.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| W. L. Gore & Associates |
| Lepu Medical Technology (Beijing) Co., Ltd |
| Lifetech Scientific |
| Occlutech GmbH |
| AtriCure |
| Carag AG |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Nitinol wire-frame sourcing clusters in Chinese and German specialty metallurgy facilities, concentrating upstream margin capture with alloy processors while downstream pricing power accrues to device manufacturers with captive sterilization infrastructure and direct hospital contracting relationships.
Pricing Analysis
Volume-discount tiering structures separate premium nitinol occluders with enhanced biocompatibility coatings from standard polyester-membrane devices and economy-grade surgical patch materials. Price differentiation hinges on FDA breakthrough designation status and procedural training bundling. Cost compression in the economy tier intensifies as domestic Chinese manufacturers scale NMPA-approved production. Pediatric cardiology departments exhibit highest price sensitivity due to constrained procurement budgets, while integrated delivery networks in the United States demonstrate lowest sensitivity where outcome-based contracting predominates.
Supply Chain Analysis
Export-control regimes limiting advanced nitinol shape-memory alloy technology flows constrain supply security for European and North American device manufacturers. Raw material dependencies center on nickel-titanium alloy feedstock, electrospun polymer membranes, and ethylene oxide sterilization services. Supply chain risk manifests through single-source vulnerability in nitinol wire drawing. Distribution runs through specialized cardiac device distributors with catheterization lab technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procedural training and post-market surveillance services attach to hardware sales at expanding margins, with EU MDR-mandated clinical follow-up registries creating recurring revenue streams that outpace device unit growth.
For Market Incumbents: Entrench market position through backward integration into nitinol wire-frame production and captive sterilization facility investments that insulate against EPA emission regulation disruptions. Defend against specialized regional manufacturers by anchoring premium positioning across integrated delivery networks with bundled proctoring services. Prioritize R&D intensity in bioresorbable magnesium alloy frameworks to preempt nickel allergy-driven substitution threats. For New Entrants and Emerging Players: Brazil's underpenetrated adult secundum defect population over 40 represents the most penetrable entry point, with São Paulo catheterization lab partnerships offering procedural volume aggregation. Japan's PMDA conditional approval pathways enable early commercial presence while completing pediatric indication requirements. Target public-private hospital partnerships with technical training commitments as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European occluder specialists facing EU MDR recertification cost burdens. Long-term viability over a 5-10 year window favors manufacturers with diversified structural heart portfolios and alternative sterilization modality investments. Monitor bioresorbable occluder clinical trial readouts as the critical inflection signal for next-generation platform transitions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment accelerates market access for Class III implantable devices. |
| Hospital System Partnership | Integrated delivery network contracts standardize catheterization lab procurement across multi-hospital systems. |
| Software Companion Development | Real-time 3D echocardiography integration reduces fluoroscopy exposure and expands treatable anatomies. |
| Reimbursement Strategy | CMS outpatient procedure codes capture elective secundum closures in ambulatory settings. |
| Backward Integration | In-house nitinol wire-frame production mitigates shape-memory alloy supply concentration risks. |
Study Parameters
Initial hypotheses were tested against primary input from interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS reimbursement databases, and hospital procurement records. Bottom-up device shipment estimates were triangulated with top-down catheterization lab capacity assessments across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling procedure volume by intervention modality, patient age cohort, defect size classification, and regional regulatory cluster. CAGRs were derived from installed catheterization lab base expansion and adult secundum defect diagnosis rates. Forecast inputs incorporated nitinol alloy price trajectories and sterilization facility capacity constraints.
Stress conditions across nitinol supply disruptions, EPA emission regulation enforcement, and PMDA pediatric approval timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway predictability. Material shifts in bioresorbable occluder clinical efficacy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Essential Thrombocythemia Market