
 Advance Renal Cell Carcinoma Therapeutics Market | 2026-2036
Advance Renal Cell Carcinoma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Advance Renal Cell Carcinoma Therapeutics Market Outlook
Immunotherapy agents are restructuring treatment economics across the advance renal cell carcinoma therapeutics landscape, displacing conventional chemotherapy as the backbone of first-line intervention. Bristol Myers Squibb leverages its checkpoint inhibitor portfolio to anchor market presence in metastatic settings. Merck sustains competitive intensity through sustained investment in combination trials with tyrosine kinase inhibitors. Exelixis specializes in targeted therapy mechanisms that dominate the post-immunotherapy maintenance segment.
Advance renal cell carcinoma therapeutics comprise systemic drug interventions designed to inhibit tumor angiogenesis, modulate immune surveillance, or induce direct cytotoxicity in kidney malignancies that have progressed beyond localized resection, typically administered as oral small molecules or intravenous biologics with dosing calibrated to RECIST response criteria and patient performance status. The primary commercial purpose centers on extending progression-free survival in patient populations where surgical cure is no longer achievable. Immunotherapy now commands the largest revenue pool among product types, though combination therapy represents the fastest-expanding category as oncologists sequence multiple mechanisms. Oral delivery mode captures the dominant share of prescription volume due to patient convenience, yet intravenous administration retains higher per-treatment value in hospital infusion centers where combination protocols are concentrated.
The FDA's breakthrough therapy designation and EMA's PRIME scheme are compressing regulatory timelines, reshaping how manufacturers prioritize clinical trial endpoints and biomarker strategies for market access. REACH compliance and the EU MDR impose stringent manufacturing and post-market surveillance requirements on European supply chains, elevating quality costs for entrants. Stakeholders must monitor how CMS reimbursement decisions and NICE technology appraisals divergence across the Atlantic will influence site-of-care migration and portfolio allocation between oral and parenteral formats.
Market Dynamics
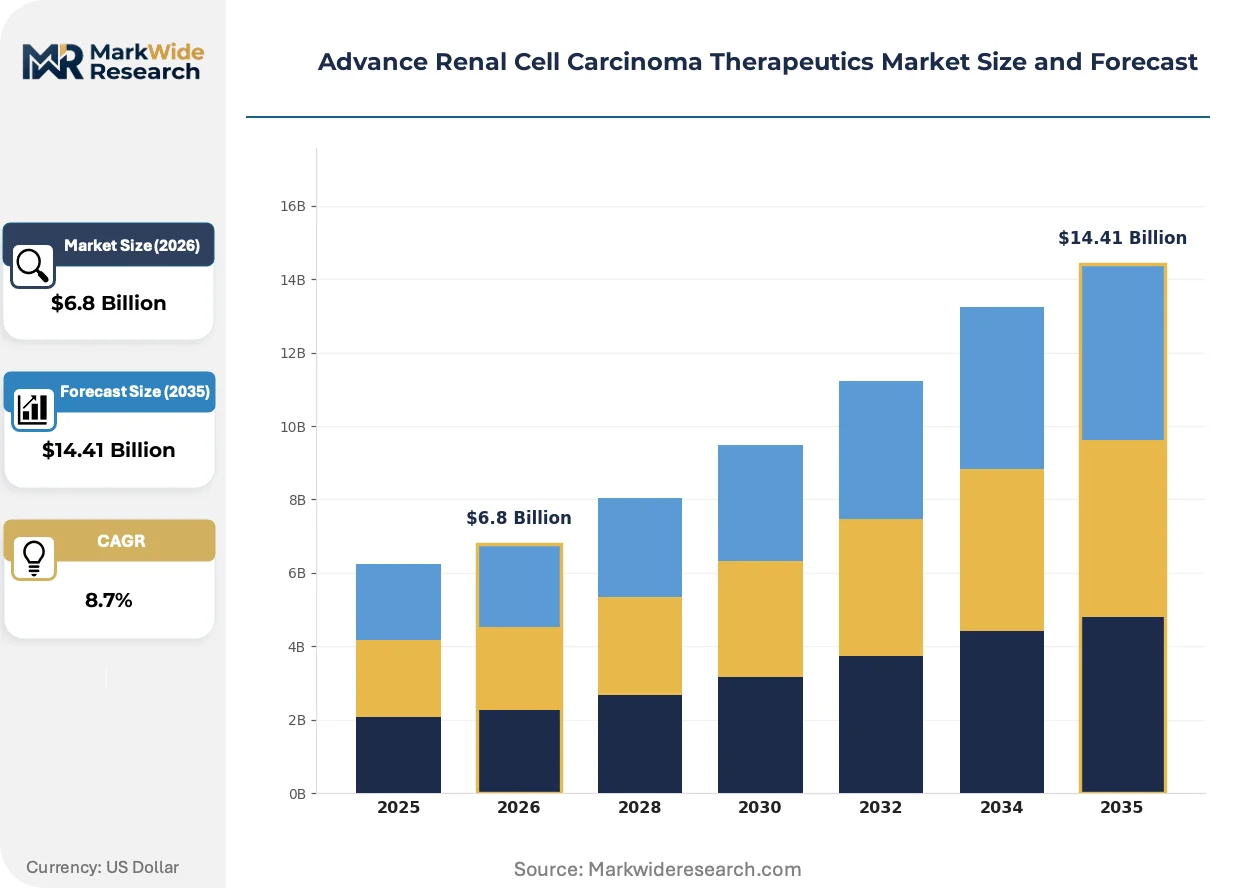
Checkpoint inhibitor combinations are restructuring first-line treatment protocols across oncology clinics, compressing the commercial window for single-agent tyrosine kinase inhibitors and forcing manufacturers to accelerate biomarker-driven trial designs.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated pathway compresses regulatory timelines from submission to commercial launch, enabling earlier revenue recognition for combination regimens targeting metastatic populations.
- Centralized Cancer Centers:Germany's network of comprehensive cancer centers drives protocol standardization across the federal system, creating concentrated demand pools for approved combination therapies.
- Biomarker Stratification:PD-L1 expression testing and genomic profiling are expanding addressable patient populations by identifying responders prior to therapy initiation, improving real-world effectiveness metrics.
Market Restraints
- Manufacturing Complexity:Biologic production for checkpoint inhibitors requires single-use bioreactor systems and cold-chain distribution, elevating cost structures above small-molecule alternatives.
- Reimbursement Divergence:CMS coverage determinations in the United States and NICE technology appraisals in the United Kingdom produce divergent access timelines, fragmenting commercial strategy.
- Primary Resistance Mechanisms:Approximately one-third of patients demonstrate innate resistance to PD-1/PD-L1 blockade, limiting addressable populations and requiring salvage therapy development.
Strategic Opportunities
- Maintenance Therapy Positioning:Post-immunotherapy TKI sequences represent an underserved clinical need where oral agents can capture prolonged treatment durations.
- EU MDR Alignment:Early compliance with the European Medical Device Regulation creates competitive moats against delayed entrants in companion diagnostic markets.
- Site-of-Care Migration:Oral combination components enable community oncology administration, reducing hospital infusion center dependency and expanding prescriber access.
Industry Challenges
- Immuno-oncology Talent Scarcity:Clinical development teams with checkpoint inhibitor trial experience command premium compensation, constraining mid-tier sponsor expansion.
- RECIST Criteria Evolution:Immune-related response criteria require specialized radiology training, creating site certification bottlenecks and enrollment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advance Renal Cell Carcinoma Therapeutics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Combination Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Research Institutions, Home Care Indication: Metastatic RCC, Locally Advanced RCC, Recurrent RCC, High-Risk RCC |
| Companies Covered | AstraZeneca, Eisai, Merck, Incyte Corporation, Corvus Pharmaceuticals, Exelixis, Pfizer, CRISPR Therapeutics, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advance Renal Cell Carcinoma Therapeutics Market Strategic Shifts
Combination therapy architectures are displacing sequential monotherapy as the dominant clinical paradigm, forcing manufacturers to restructure development portfolios around mechanism-of-action pairing rather than single-agent superiority trials.
Next-generation sequencing platforms are decentralizing biomarker testing from centralized academic laboratories to community pathology networks. Community oncology practices in the United States are adopting CLIA-certified in-house profiling at accelerating rates. This shift is compressing turnaround times for treatment decisions and enabling real-time protocol adjustments based on mutational status.
The EU MDR's post-market surveillance requirements are elevating pharmacovigilance burdens across European supply chains. Manufacturers must now maintain active safety databases with direct healthcare professional reporting channels. Intravenous biologics administered in hospital settings face heightened documentation requirements compared to oral agents.
Site-of-care economics are driving prescriber preference toward oral agents that avoid infusion center overhead. United States community oncology practices are prioritizing regimens with oral components to retain patient volume against hospital outpatient departments. This behavioral shift concentrates prescription volume in patient assistance program structures rather than buy-and-bill reimbursement models.
Advance Renal Cell Carcinoma Therapeutics Market Segmentation
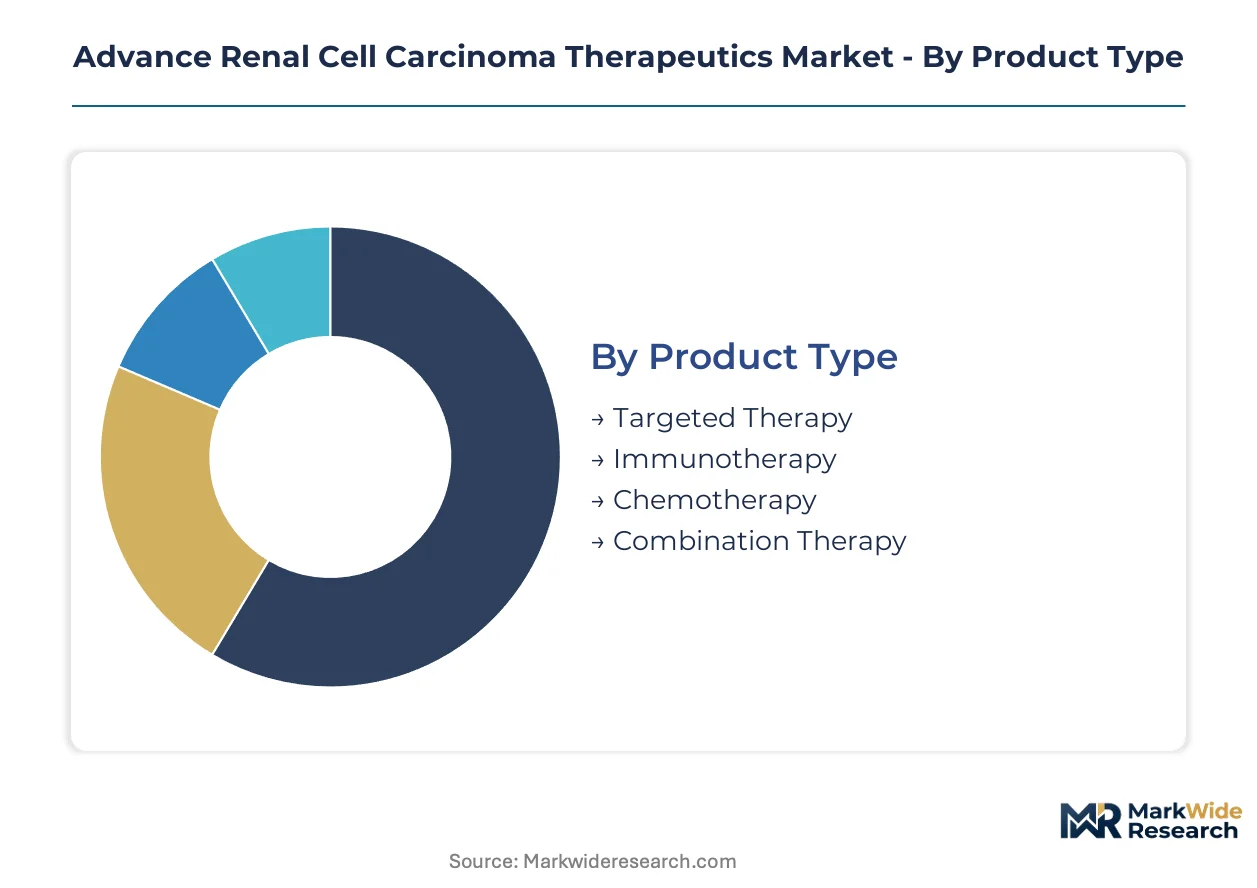
Segmentation in renal cell carcinoma therapeutics reveals how clinical practice splits across site-of-care economics and treatment sequencing protocols. Manufacturers must align formulation strategies with where patients actually receive care.
Product Type:
Supply concentration in checkpoint inhibitor manufacturing has tilted commercial investment toward biologic production capacity, leaving small-molecule capacity fragmented across contract manufacturers.
- Immunotherapy:PD-1 and PD-L1 inhibitors function through immune checkpoint blockade, requiring cold-chain distribution and infusion center administration. Demand concentrates in United States hospital outpatient departments where CMS reimbursement rates support biologic delivery. The FDA's breakthrough therapy designation pipeline favors this category for accelerated approval.
- Combination Therapy:Regimens pair checkpoint inhibitors with tyrosine kinase inhibitors or dual immunotherapy combinations, administered through sequential infusion and oral dosing protocols. Germany's comprehensive cancer centers drive protocol standardization for these complex schedules. EMA's PRIME scheme accelerates European market entry for qualifying combinations.
- Targeted Therapy:Oral tyrosine kinase inhibitors block VEGF signaling pathways to inhibit angiogenesis.
- Chemotherapy:Cytotoxic agents retain niche utility in salvage settings after immunotherapy failure.
Today's leader: Immunotherapy. Tomorrow's challenger: Combination Therapy.
Delivery Mode:
Cost tier differentiation separates hospital-administered biologics from community-dispensed oral agents, with reimbursement models driving prescriber preference toward lower-overhead formats.
- Oral:Small-molecule TKIs enable patient self-administration outside clinical settings, eliminating infusion center overhead. United States community oncology practices prioritize oral regimens to retain patient volume against hospital systems. Site-of-care migration toward oral formats accelerates as Medicare Advantage plans tighten network restrictions.
- Intravenous:Monoclonal antibodies and fusion proteins require sterile compounding and monitored administration in hospital infusion centers. Academic medical centers in the United States concentrate intravenous volume through buy-and-bill reimbursement structures. Cold-chain logistics and single-use bioreactor production elevate per-dose manufacturing costs above oral alternatives.
- Subcutaneous:Emerging formulations aim to bridge hospital and home administration for select immunotherapy agents.
- Intramuscular:Limited current application in RCC therapeutics, primarily experimental depot formulations.
Oral delivery captures prescription volume. Intravenous retains per-treatment value.
End User:
Customer type fragmentation splits demand across institutional purchasing coalitions, with hospital systems leveraging GPO leverage against specialty pharmacy networks serving community practices.
- Hospitals:Academic medical centers and integrated delivery networks administer intravenous immunotherapy through outpatient infusion centers, capturing buy-and-bill margin on biologic drugs. United States health systems with 340B eligibility access discounted pricing for outpatient oncology. EMA's EU MDR imposes heightened pharmacovigilance documentation requirements on hospital-administered biologics.
- Clinics:Community oncology practices concentrate oral prescription dispensing through in-house specialty pharmacies or contracted specialty distributors. Germany's ambulatory care reimbursement structure supports clinic-based TKI administration. Independent practices face margin compression from site-of-care migration policies favoring hospital systems.
- Research Institutions:Phase I-III trial sites drive early adoption of novel mechanisms before regulatory approval.
- Home Care:Oral TKI regimens enable treatment administration outside clinical settings for stable maintenance therapy.
Hospitals anchor biologic revenue. Clinics compete on oral access.
Indication:
Maturity gradients separate established metastatic protocols from emerging adjuvant applications, with regulatory pathways diverging between palliative and curative-intent trial designs.
- Metastatic RCC:First-line and subsequent therapy for distant metastases represents the commercial core of the therapeutic landscape, with FDA-approved combinations concentrated in this setting. United States oncology practices sequence immunotherapy followed by TKI salvage per NCCN guidelines. RECIST response criteria standardize trial endpoints across regulatory submissions.
- Locally Advanced RCC:Neoadjuvant and adjuvant applications seek to extend disease-free survival following nephrectomy, representing an expansion opportunity beyond palliative care. EMA's scientific advice procedures guide European development strategy for perioperative indications. Biomarker stratification through PD-L1 expression testing identifies trial-enriched populations.
- Recurrent RCC:Second and third-line therapy after prior systemic treatment requires mechanism switching.
- High-Risk RCC:Adjuvant therapy for resected high-risk disease remains an evolving evidence base.
Metastatic RCC commands current revenue. Locally advanced applications represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology hubs in the United States, Germany, and Japan concentrate clinical trial infrastructure and regulatory decision-making for renal cell carcinoma therapeutics. These markets set reimbursement benchmarks that cascade into secondary markets. Emerging centers in China and India are expanding manufacturing capacity and patient access programs.
United States
Academic medical centers in Boston and Houston drive protocol innovation for combination immunotherapy regimens. The FDA's breakthrough therapy designation accelerates commercial timelines for novel mechanisms. CMS reimbursement policies for hospital outpatient departments concentrate biologic administration in integrated health systems with 340B eligibility.
Germany
Comprehensive cancer centers in Munich and Heidelberg standardize treatment protocols across the federal reimbursement system. EMA's PRIME scheme supports accelerated assessment for combination therapies targeting metastatic populations. The country's statutory health insurance structure enables rapid adoption of NICE-aligned technology appraisals.
Japan
PMDA's Sakigake designation attracts sponsor investment in first-in-class mechanisms for Asian patient populations. Tokyo's National Cancer Center anchors biomarker research for PD-L1 expression stratification. Regional prefectures are expanding coverage for oral tyrosine kinase inhibitors under the universal health insurance system.
China
NMPA's priority review pathway compresses timelines for domestically manufactured checkpoint inhibitors. Shanghai's Zhangjiang Hi-Tech Park clusters biologic production capacity for regional supply. The National Reimbursement Drug List expansion is incorporating novel renal cell carcinoma therapies at negotiated volume-based pricing.
United Kingdom
NICE technology appraisals determine National Health Service access for immunotherapy combinations in England. The Manchester Cancer Research Centre coordinates real-world evidence generation for post-market surveillance. Scotland's SMC parallel assessment creates divergence in availability timelines across the devolved administrations.
Advance Renal Cell Carcinoma Therapeutics Market Competitive Environment
Global majors compete with regional champions across regulatory access and site-of-care positioning. The market structure concentrates around large-cap pharmaceutical companies with checkpoint inhibitor portfolios and mid-tier biotechs with targeted therapy specialization. Three archetypes dominate: integrated immunotherapy developers, precision oncology specialists, and emerging cell therapy platforms. Competitive intensity centers on combination trial enrollment speed and maintenance therapy sequencing rights.
Within the integrated pharmaceutical tier, Bristol Myers Squibb, Merck, and Pfizer occupy positions defined by checkpoint inhibitor infrastructure and combination regimen development. Bristol Myers Squibb anchors presence through PD-1 platform breadth. Merck exemplifies sustained investment in TKI pairing strategies. Pfizer represents scale-driven oncology portfolio diversification. Exelixis sits within the targeted therapy specialist archetype, focused on post-immunotherapy oral agent positioning. These five entities collectively shape clinical protocol standards and reimbursement negotiations across major markets.
| Leading Market Players |
|---|
| AstraZeneca |
| Eisai |
| Merck |
| Incyte Corporation |
| Corvus Pharmaceuticals |
| Exelixis |
| Pfizer |
| CRISPR Therapeutics |
| Bristol Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Specialized biologics manufacturing talent concentration in Switzerland and Massachusetts creates labor-cost differentials that widen pricing-tier spreads between originator checkpoint inhibitors and biosimilar alternatives entering European markets.
Pricing Analysis
Input-cost pass-through from single-use bioreactor consumables and cold-chain logistics elevates per-dose manufacturing costs for intravenous immunotherapies above oral tyrosine kinase inhibitors. Pricing stratifies across premium originator biologics, standard-of-care combinations, and economy-positioned salvage chemotherapy based on patent exclusivity status and CMS reimbursement tier. Pricing pressure stems from Medicare Advantage plan formulary restrictions tightening site-of-care migration policies. Community oncology practices demonstrate highest price sensitivity due to margin compression from 340B hospital competition.
Supply Chain Analysis
Workforce availability constraints in biologics manufacturing concentrate production capacity in Switzerland, Ireland, and Singapore where regulatory-compliant talent pools support FDA and EMA inspection standards. Active pharmaceutical ingredient sourcing draws from specialized fermentation facilities in Germany and contract manufacturing organizations in India for small-molecule components. Single-source vulnerability pervades monoclonal antibody fill-finish capacity controlled by limited sterile manufacturing sites. Distribution runs through hospital-centric specialty distributors for intravenous products and retail specialty pharmacy networks for oral agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in post-immunotherapy maintenance segments where oral TKI sequences command premium pricing against commodity salvage options, enabled by manufacturing cost-down through continuous processing adoption.
For Market Incumbents: Acquire late-stage TKI pipeline assets to secure sequencing rights in post-PD-1 maintenance therapy. Consolidate biologics manufacturing capacity in Switzerland and Ireland to defend against biosimilar entrants leveraging Indian CMO cost structures. Expand biomarker companion diagnostic control through CLIA-certified laboratory partnerships to lock prescriber decision points. For New Entrants and Emerging Players: Telehealth-integrated patient assistance programs offer direct channel access bypassing hospital GPO gatekeepers. Target United States community oncology practices in Medicare Advantage-dense states where site-of-care migration policies concentrate oral prescription volume. Pursue EMA PRIME designation to compress European regulatory timelines against entrenched checkpoint inhibitor portfolios. For Investors and Strategic Acquirers: Large-cap immunotherapy developers are the most active acquirers in this space, seeking TKI maintenance assets to complete combination regimens. Five-to-ten year viability hinges on perioperative adjuvant indication expansion beyond metastatic palliation. Watch FDA breakthrough therapy designation grants for dual immunotherapy combinations as inflection signals for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates biomarker-stratified enrollment for checkpoint inhibitor combinations per FDA breakthrough pathway. |
| Manufacturing Scale-Up | Expands single-use bioreactor capacity in Switzerland to meet EMA post-market surveillance requirements. |
| Licensing Agreement | Secures TKI pairing rights for post-immunotherapy sequences in United States community oncology. |
| Regulatory Approval Pathway | EMA PRIME scheme compresses European assessment timelines for metastatic combination therapies. |
| Pipeline Diversification | Adds perioperative adjuvant indications to extend addressable patient populations beyond salvage settings. |
Study Parameters
Multiple input streams — primary interviews, regulatory filing analysis, and prescription data reconciliation — were combined to construct market estimates. Conversations with drug development executives, formulary directors at United States health systems, payer access specialists, and hospital procurement managers informed clinical adoption assumptions. Secondary validation drew from FDA filings, EMA assessment reports, ClinicalTrials.gov protocol databases, and CMS Medicare Part B claims patterns. Bottom-up patient-flow modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Data-stream reconciliation across the projection horizon employed treatment-line segmentation, dosage-form differentiation, administration-route economics, and regional regulatory clustering. CAGRs were derived from modeled patient incidence flows, therapy-sequence penetration curves, and price-trajectory assumptions for originator and biosimilar alternatives. Forecast inputs incorporated biomarker testing adoption rates and site-of-care migration policy impacts on oral versus intravenous product mix.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous immunotherapy formulations would alter the outlook. Forecasts reflect assumptions regarding CMS reimbursement stability and EMA centralized procedure timelines. Material deviation in breakthrough therapy designation grant rates or NICE technology appraisal divergence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Pleurisy Market