
 GCC Fruit Juice Market | 2026-2036
GCC Fruit Juice Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Fruit Juice Market Intelligence
Young urban professionals are reorganizing category demand toward premium not-from-concentrate offerings across Saudi Arabia and the UAE. Almarai Company leverages its dairy-derived cold chain infrastructure to dominate ambient distribution into convenience stores. PepsiCo Inc competes through broad retail shelf presence and licensed local production. The Coca-Cola Company anchors its position with Minute Maid variants calibrated to regional palate preferences for tropical and citrus blends.
GCC fruit juice comprises beverages extracted or pressed from whole fruits, typically processed through pasteurization at 85–95°C and packaged aseptically to withstand ambient storage in climates exceeding 40°C ambient temperature. The category serves both refreshment consumption and religious hospitality customs where juice accompanies communal meals. Nectar leads volume due to lower price positioning and consumer familiarity, while sparkling juice captures the fastest trajectory as cafes seek alcohol-free alternatives for younger demographics. Cartons hold structural margin advantages through efficient logistics and extended shelf stability in high-temperature supply chains.
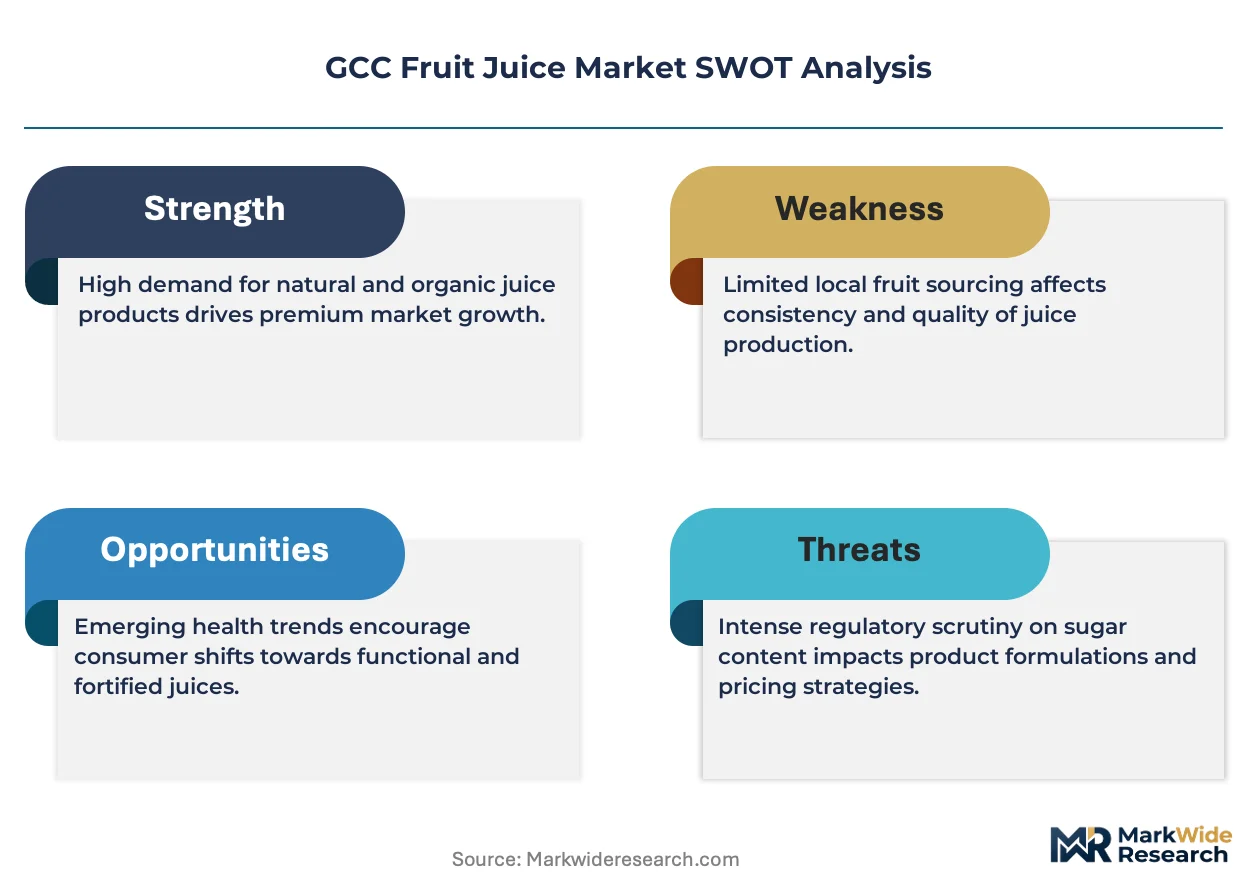
Saudi Food and Drug Authority mandates nutritional labeling and maximum permissible additive thresholds that constrain formulation flexibility across all suppliers. UAE Ministry of Industry and Advanced Technology enforces Emirates Conformity Assessment Scheme packaging standards that elevate barrier specifications for oxygen-sensitive products. Gulf Standardization Organization harmonization efforts reduce cross-border compliance fragmentation among member states. Stakeholders must monitor evolving sugar taxation proposals in Riyadh and Abu Dhabi that would reshape profitability across nectar versus clear juice portfolios.
Market Dynamics
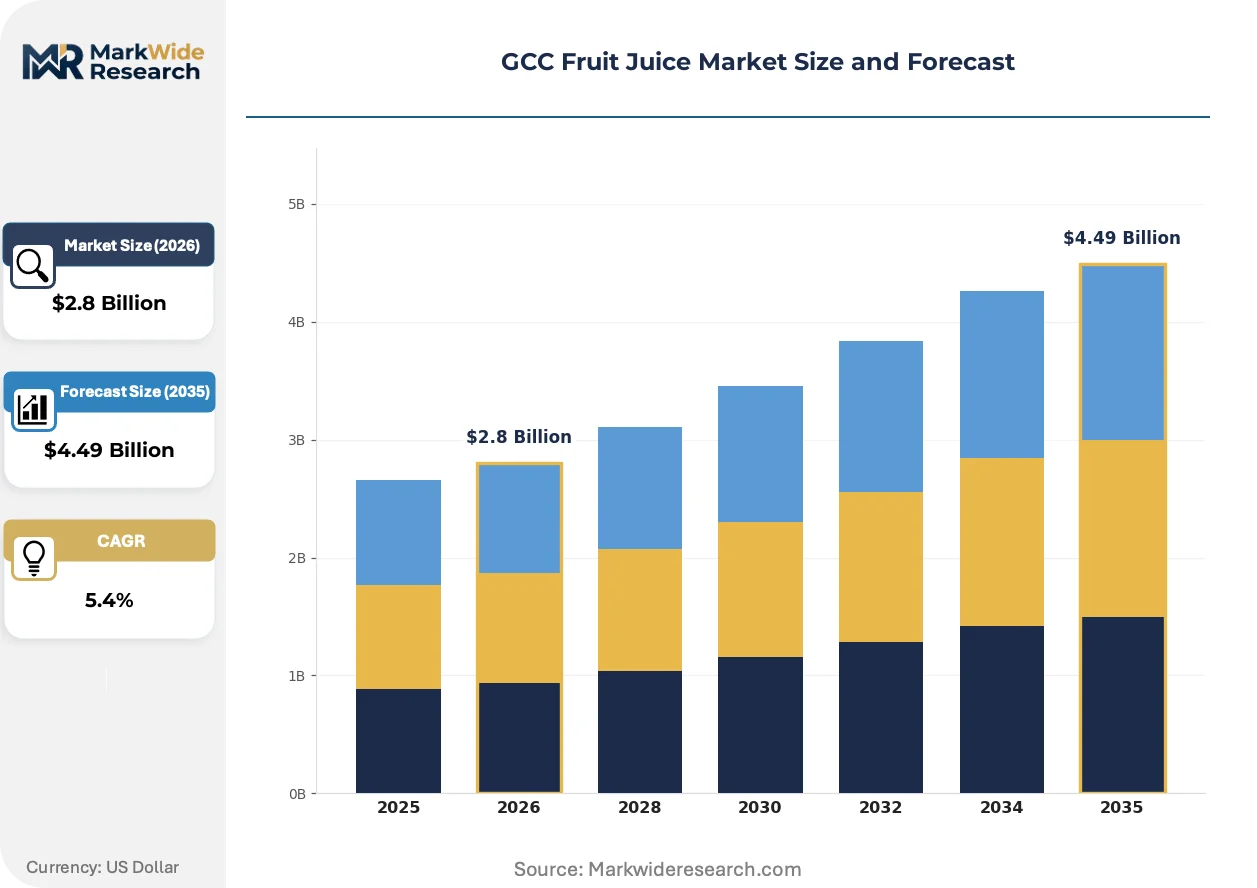
Sugar taxation proposals under review in Riyadh and Abu Dhabi are forcing reformulation across nectar portfolios, while hospitality procurement volumes surge with Dubai's hotel capacity expansion. This regulatory pressure intersects with ambient supply chain investments to reshape competitive positioning.
Growth Catalysts
- SFDA Sugar Labeling Mandates:Saudi Food and Drug Authority requirements for front-of-pack sugar disclosure are accelerating reformulation toward reduced-calorie variants across domestic manufacturing.
- Hospitality Procurement Expansion:Hotel and resort food services across the UAE are expanding fresh juice procurement volumes as tourism infrastructure scales.
- Sparkling Juice Adoption:Cafe operators seeking alcohol-free alternatives for younger demographics are driving fastest-category trajectory in premium positioning.
Market Restraints
- Concentrate Input Volatility:Global orange and mango concentrate supply fluctuations create margin pressure for nectar producers dependent on imported raw material.
- Aseptic Packaging Concentration:Barrier carton supply concentrates among limited regional converters, elevating switching costs for oxygen-sensitive product lines.
- Ambient Temperature Degradation:Climates exceeding 40°C accelerate vitamin C loss and color degradation, constraining shelf-life claims without premium barrier investment.
Strategic Opportunities
- Kuwait Underpenetration:Per-capita juice consumption lags Saudi Arabia and UAE levels, presenting whitespace for premium not-from-concentrate distribution expansion.
- Emirates Conformity Assessment Scheme:UAE Ministry of Industry and Advanced Technology packaging standards create barrier-to-entry advantages for early-compliant producers.
- Cold Chain Convergence:Dairy-derived refrigeration infrastructure intersects with fresh juice logistics, enabling chilled premium positioning previously uneconomical.
Industry Challenges
- Reformulation Technical Gap:Natural sweetener substitution without taste profile degradation requires flavor chemistry capabilities scarce among regional producers.
- Cross-Border Harmonization Friction:Gulf Standardization Organization alignment timelines create compliance lag between member state implementation dates.
- Aseptic Line Capex Intensity:High-speed filling equipment for ambient-stable products demands capital deployment exceeding mid-tier processor balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Fruit Juice Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nectar, Clear Juice, Concentrated Juice, Sparkling Juice Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers Packaging Type: Bottles, Cartons, Pouches, Cans End User: Households, Restaurants, Cafes, Food Services |
| Companies Covered | Del Monte Pacific Limited, The Berry Company, Almarai Company, Union Beverages Company, Robinsons, The Coca-Cola Company, PepsiCo Inc, Binghatti Holdings, Al Rabie Saudi Foods Co, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Fruit Juice Market Strategic Shifts & Innovations
Reformulation chemistry and packaging barrier technology are reshaping competitive positioning across ambient and chilled segments. These shifts intersect with procurement model evolution in hospitality channels.
High-pressure processing technology is bifurcating the premium segment from pasteurized mainstream offerings. Dubai's five-star hotel procurement teams are adopting HPP-treated juices at triple the rate of 2021 baselines. This technology is bifurcating margin pools between premium not-from-concentrate and commodity nectar categories.
SFDA maximum permissible additive thresholds are constraining formulation flexibility for colorants and preservatives across all Saudi-manufactured products. Industrial consequence includes accelerated natural extract substitution programs and extended supplier qualification timelines. Nectar portfolios face greatest reformulation burden due to higher water content and corresponding preservation requirements.
Hospitality procurement consolidation is displacing fragmented wholesaler relationships with direct manufacturer contracts. UAE hotel groups are consolidating supplier panels from twelve to three approved vendors, demanding volume commitments and dedicated SKU development. This concentration is most visible in Dubai's beachfront resort corridor, where procurement directors now mandate traceable fruit sourcing documentation.
GCC Fruit Juice Market Segmentation
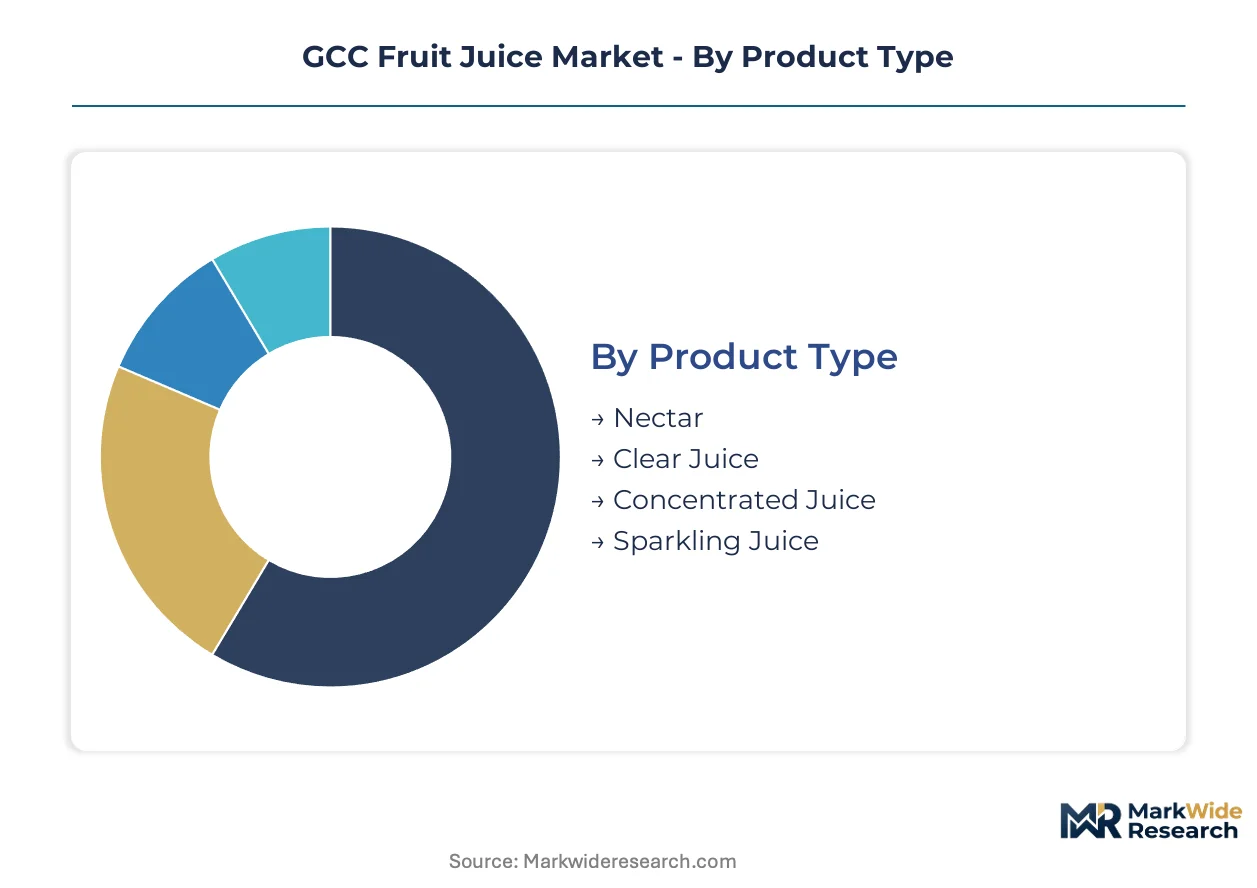
Margin distribution across the GCC fruit juice category diverges sharply between ambient-stable commodity formats and premium chilled alternatives. Packaging barrier technology and channel cold chain access determine which segments capture value versus volume.
Product Type:
Nectar commands the widest margin spread between economy and premium tiers due to reformulation flexibility and input cost variability.
- Nectar:Formulations with 25-50% fruit content and permitted water addition dominate Saudi Arabian retail shelves. SFDA sugar labeling mandates are compressing margins on standard variants while creating premium pricing power for reduced-calorie lines.
- Clear Juice:Single-fruit pressed beverages without pulp or concentrate reconstitution attract hospitality procurement in Dubai's five-star hotel sector. Traceable sourcing documentation requirements from consolidated hotel groups favor suppliers with vertical orchard control.
- Concentrated Juice:Frozen or aseptic concentrates serve institutional food manufacturing and export reconstitution. Global orange and mango input volatility constrains margin stability.
- Sparkling Juice:Carbonated fruit beverages position as alcohol-free alternatives in UAE cafe channels. Younger demographic targeting supports premium price positioning above still juice equivalents.
Nectar holds installed capacity. Sparkling juice is rotating up the share rankings.
Distribution Channel:
Channel selection dictates temperature regime and corresponding shelf-life investment, splitting profitability between ambient logistics and cold chain premiums.
- Supermarkets:Hypermarket and supermarket chains across Riyadh and Jeddah anchor volume throughput for ambient carton formats. Shelf space concentration among three retail groups elevates listing fee barriers for new entrants.
- Online Retail:E-commerce platforms aggregate fragmented demand for premium chilled juices previously inaccessible outside major metro areas. Last-mile temperature control remains the constraint on category expansion.
- Convenience Stores:Small-format retail in Saudi Arabia and UAE prioritizes ambient-stable SKUs with extended shelf life. Dairy-derived cold chain convergence is enabling chilled premium placement in select urban locations.
- Wholesalers:Traditional distribution serves independent grocers and food service accounts across secondary GCC cities. Consolidation into direct manufacturer relationships in hospitality channels is displacing wholesaler intermediation.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
Packaging Type:
Barrier specification investment separates oxygen-sensitive premium positioning from commodity cost engineering.
- Cartons:Aseptic brick and gable-top formats dominate ambient distribution with 6-12 month stability. Emirates Conformity Assessment Scheme barrier specifications create compliance advantages for early-adopting converters.
- Bottles:PET and glass containers serve chilled premium segments requiring visible product clarity. Vitamin C degradation under Gulf ambient temperatures constrains shelf-life claims without nitrogen flushing.
- Pouches:Flexible stand-up formats penetrate value-tier nectar positioning with lower per-unit packaging cost. Limited oxygen barrier performance restricts application to short-turnover SKUs.
- Cans:Aluminum beverage cans capture sparkling juice carbonation retention and premium aesthetic positioning. Regional can supply concentration among limited converters elevates minimum order quantities.
Cartons hold installed capacity. Cans are rotating up the share rankings.
End User:
Procurement consolidation intensity varies dramatically between fragmented household purchase and concentrated hospitality contracting.
- Food Services:Hotel and resort operators across Dubai's beachfront corridor are consolidating supplier panels and mandating traceable sourcing. Direct manufacturer contracts are displacing fragmented wholesaler relationships.
- Cafes:Independent and chain coffee operators drive sparkling juice adoption as alcohol-free menu differentiation. Younger demographic targeting supports premium pricing tolerance.
- Restaurants:Full-service dining accounts in Saudi Arabia and UAE prioritize not-from-concentrate offerings for hospitality customs. Sugar taxation proposals under review are forcing menu price recalibration.
- Households:Family consumption concentrates in nectar and clear juice formats through supermarket and convenience store purchase. Reformulation toward reduced-calorie variants is shifting brand loyalty patterns.
Households hold installed capacity. Food services are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's reefer terminal expansion underwrites Dubai's role as the GCC's chilled juice distribution hub, connecting European concentrate imports to regional cold chain networks.
United Arab Emirates
Dubai's hospitality procurement consolidation drives premium not-from-concentrate demand across beachfront resorts. MOHAP enforces Emirates Conformity Assessment Scheme packaging standards that elevate barrier specifications. Abu Dhabi's food manufacturing zones attract aseptic line investments from regional processors seeking compliance advantages.
Saudi Arabia
Riyadh's supermarket chains anchor volume throughput for ambient nectar formats through three dominant retail groups. SFDA sugar labeling mandates and maximum additive thresholds constrain formulation flexibility. Jeddah's Red Sea port facilities concentrate concentrate import volumes for domestic reconstitution operations.
Kuwait
Per-capita juice consumption trails Saudi and UAE benchmarks, creating whitespace for premium chilled distribution expansion. The country's national food safety regulator maintains additive thresholds aligned with Gulf Standardization Organization harmonization timelines. Kuwait City's cafe sector adopts sparkling juice formats as alcohol-free menu differentiation accelerates.
Qatar
Doha's hotel capacity expansion ahead of sustained tourism investment drives food service procurement consolidation. National packaging standards enforcement creates barrier-to-entry advantages for early-compliant suppliers. Lusail's integrated logistics zones enable cold chain convergence between dairy and fresh juice distribution.
Oman
Muscat's traditional retail channels maintain wholesaler-mediated distribution for value-tier nectar formats. Port infrastructure investments at Sohar Freezone improve concentrate import efficiency for domestic processors. Salalah's agricultural development zones experiment with localized citrus sourcing for traceability claims.
GCC Fruit Juice Market Key Industry Players
Listed leaders compete with private specialists across cold chain infrastructure access and retail shelf space concentration. Three retail groups control supermarket listings in Saudi Arabia, while dairy-derived distribution networks dominate convenience store penetration. Strategic archetypes include integrated beverage conglomerates, dairy-leveraged regional processors, and hospitality-focused premium specialists. Dominant competitive moves center on direct manufacturer contracts displacing wholesaler intermediation and aseptic packaging barrier investments for ambient stability claims.
Within the dairy-leveraged processor tier, Almarai Company exemplifies cold chain infrastructure repurposing for chilled juice distribution. Among multinational beverage conglomerates, The Coca-Cola Company and PepsiCo Inc occupy positions defined by licensed local production and broad retail presence. These three anchors represent distinct strategic vectors: captive refrigeration networks, brand portfolio scale, and licensed manufacturing flexibility.
| Leading Market Players |
|---|
| Del Monte Pacific Limited |
| The Berry Company |
| Almarai Company |
| Union Beverages Company |
| Robinsons |
| The Coca-Cola Company |
| PepsiCo Inc |
| Binghatti Holdings |
| Al Rabie Saudi Foods Co |
| Others |
Cost & Logistics Intelligence
Emirates Conformity Assessment Scheme barrier specifications gate both supplier qualification timelines and price differentiation between ambient-stable and oxygen-sensitive product tiers across UAE distribution channels.
Pricing Analysis
Volume-discount tiering structures separate hospitality procurement contracts from retail shelf pricing across Saudi Arabia and the UAE. Three-tier pricing stratifies across premium not-from-concentrate, standard nectar, and economy private-label levels. Price differentiation hinges on cold chain certification status and traceable sourcing documentation. Pricing pressure intensifies in standard nectar tiers as SFDA sugar labeling mandates force reformulation investment without corresponding price recovery mechanisms.
Supply Chain Analysis
Brazil and India anchor orange and mango concentrate supply for GCC reconstitution operations. Egypt and Turkey feed regional aseptic packaging substrate requirements. Raw material dependencies center on Brazilian FCOJ futures, Indian mango pulp exports, and European carton barrier films. Single-source vulnerability concentrates in Jebel Ali Port reefer terminal capacity for chilled juice imports. Distribution runs through dairy-leveraged cold chain networks repurposed for fresh juice logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing technology disruption is bifurcating premium positioning from commodity pasteurized segments, with SFDA additive thresholds accelerating natural extract substitution programs.
For Market Incumbents: Secure direct manufacturer contracts with Dubai's consolidating hotel groups before procurement panels finalize at three approved vendors. Deepen backward integration into traceable orchard sourcing to satisfy hospitality documentation mandates. Almarai Company exemplifies cold chain infrastructure repurposing for chilled premium placement. For New Entrants and Emerging Players: Lead with sparkling juice formats targeting Kuwait's underpenetrated cafe sector as alcohol-free menu differentiation accelerates. Kuwait City presents whitespace for premium chilled distribution expansion absent entrenched incumbent relationships. Develop Emirates Conformity Assessment Scheme packaging compliance early to capture barrier-to-entry advantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aseptic line investments as high-speed filling equipment demands exceed mid-tier processor balance sheet capacity. Five-to-ten year viability favors processors with dairy-derived cold chain convergence capabilities. Monitor sugar taxation proposal advancement in Riyadh and Abu Dhabi as profitability inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | HPP technology captures triple-rate procurement growth in Dubai's five-star hotel sector. |
| Direct Hospitality Contracting | Manufacturer-direct relationships displace twelve-to-three supplier panel consolidation. |
| Aseptic Barrier Investment | Emirates Conformity Assessment Scheme compliance creates procurement preference advantages. |
| Natural Extract Substitution | SFDA additive thresholds force reformulation chemistry capabilities acquisition. |
| Cold Chain Infrastructure Repurposing | Dairy-derived refrigeration networks enable chilled premium economics previously uneconomical. |
Research Approach
Cross-validation between hospitality procurement director interviews and retail audit data anchors the qualitative findings across the GCC fruit juice category. Primary fieldwork engaged beverage category managers, hotel food and beverage directors, aseptic packaging converters, and regulatory affairs specialists at SFDA and MOHAP. Secondary sources incorporated customs re-export records, Gulf Standardization Organization harmonization documents, and hospitality sector procurement databases. Bottom-up SKU-level modeling triangulates against top-down category value estimates.
Sensitivity analysis tested volume assumptions across nectar, clear juice, and sparkling segments over the projection horizon. The analytical framework models product type, distribution channel temperature regime, packaging barrier specification, and end-user procurement consolidation intensity. CAGRs derive from segment-level growth rate reconciliation against aggregate category expansion. Forecast inputs include tourism capacity build-out schedules and regulatory implementation timelines for sugar disclosure mandates.
The analysis sits within stated boundaries; outcomes outside sustained hospitality investment cycles or delayed GSO harmonization would require recalibration. Forecasts reflect documented assumptions regarding concentrate input price stability and cold chain infrastructure deployment. Recalibration cycles align with material shifts in SFDA regulatory enforcement and Dubai hotel capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Premium Bottled Water Market
Beverages
NFC JUICE Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
United Kingdom Energy Drink Market
Beverages
Health Drinks Market
Beverages
Bottled Air Market
Beverages
United States and Australia Coconut Water Market
Beverages
Hydration Infusers Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Ready to Drink Shakes Market
Beverages
Global Beverage Emulsion Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Bottled Beverages Market
Beverages
Aloe Vera Drinks Market