
 Garcinia Cambogia Extract Market | 2026-2036
Garcinia Cambogia Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Garcinia Cambogia Extract Market Foresight
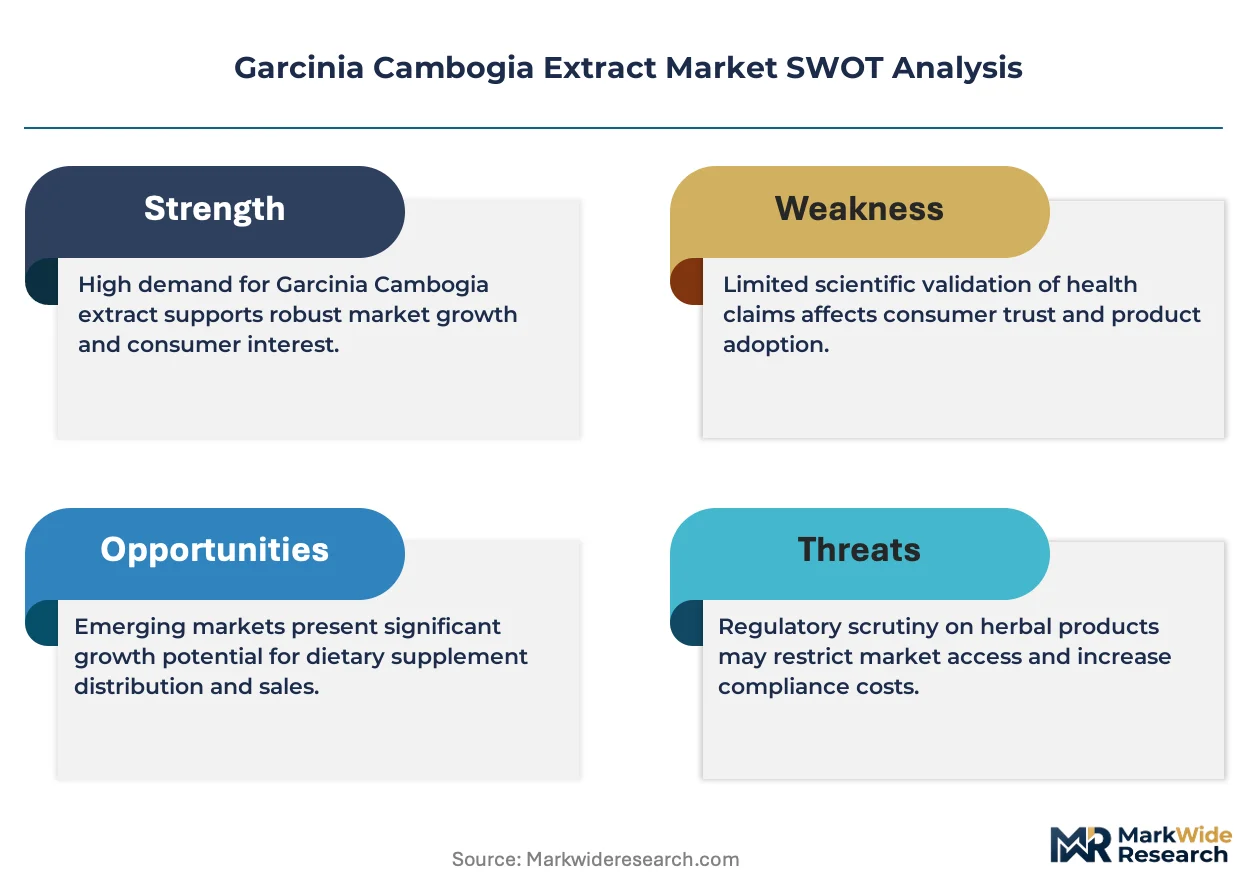
EU REACH compliance for botanical imports is expanding verification obligations for hydroxycitric acid suppliers. Xi'an Lyphar Biotech anchors its position through integrated cultivation-to-extract operations in Shaanxi Province. NOW Foods competes via certified manufacturing protocols and direct-to-consumer channel control. Givaudan SA leverages flavor-house infrastructure to serve functional food applications with standardized extract grades.
Garcinia cambogia extract derives from the dried fruit rind, typically standardized to 50-60% hydroxycitric acid content through solvent extraction and spray-drying processes; it functions primarily as a thermogenic and lipogenesis-inhibiting agent in commercial formulations. Powder extract dominates manufacturing throughput due to blending flexibility in capsule and tablet production, while gummies represent the fastest-growing delivery format as confectionery-format supplements capture younger demographics. The weight management application segment commands the largest revenue pool, though sports nutrition is accelerating as pre-workout formulations incorporate metabolic support claims.
The FDA Dietary Supplement Health and Education Act shapes label claim boundaries and adverse event reporting requirements for US-market products, while EFSA novel food assessments govern EU market entry for non-traditional botanical preparations. India's FSSAI and China's NMPA maintain divergent purity thresholds that fragment cross-border formulation standards. Stakeholders must monitor evolving pharmacovigilance mandates and adapt extract standardization protocols to preempt regulatory displacement in priority export corridors.
Market Dynamics
EU REACH compliance for botanical imports is expanding verification obligations for hydroxycitric acid suppliers, forcing extractors to reconfigure upstream quality assurance and documentation systems. This regulatory tightening is concentrating procurement among vertically integrated cultivators with in-house testing laboratories.
Growth Catalysts
- EU Novel Food Regulation pathway:Standardized extract grades that clear EFSA novel food assessments unlock pharmacy retail channels across Germany, France, and Italy.
- Sports nutrition formulation:Pre-workout metabolic support claims incorporating garcinia cambogia are accelerating purchase orders from contract manufacturers serving fitness-focused brands.
- Confectionery-format delivery:Gummy supplement production lines are absorbing powder extract volumes as younger demographics reject capsule formats.
Market Restraints
- Raw material geographic concentration:Cultivation clusters in Kerala and Karnataka, India, expose processors to monsoon-driven supply interruptions and quality inconsistency.
- Hydroxycitric acid stability limitations:Thermal degradation during spray-drying constrains shelf-life claims and complicates functional food applications.
- FDA label claim boundaries:The Dietary Supplement Health and Education Act restricts weight-loss messaging, compressing marketing differentiation and forcing reliance on ingredient branding.
Strategic Opportunities
- German pharmacy retail expansion:Apotheken channel penetration offers margin premiums unavailable in mass-market supplement distribution.
- Clean-label extraction technology:Supercritical CO2 processing is displacing solvent-based methods, enabling organic certification and premium positioning.
- China NMPA botanical registration:Approved traditional Chinese medicine crossover listings create access to domestic health product channels previously blocked to imported extracts.
Industry Challenges
- Analytical chemist talent scarcity:HPLC method development for hydroxycitric acid quantification requires specialized expertise that extractors struggle to recruit in secondary manufacturing hubs.
- Cross-border formulation standardization:Divergent purity thresholds between India's FSSAI and China's NMPA force parallel production runs and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garcinia Cambogia Extract Market |
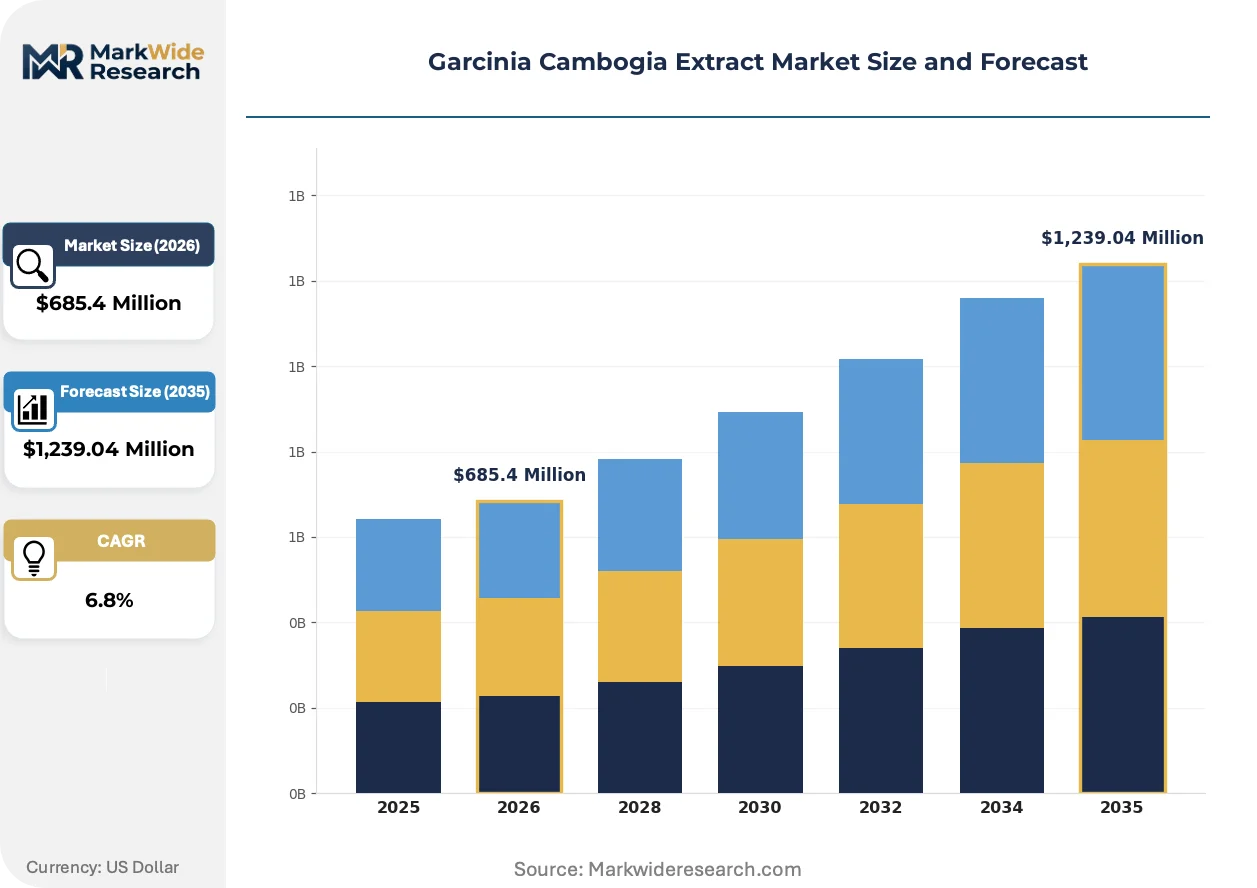
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Extract, Liquid Extract, Capsule, Tablet, Gummies Application: Weight Management, Appetite Suppressant, Sports Nutrition, Dietary Supplement, Metabolic Health End User: Health & Wellness Centers, Fitness Enthusiasts, Nutraceutical Manufacturers, Pharmacies, Online Retailers Packaging Type: Bottle, Sachet, Blister Pack, Jar, Tub |
| Companies Covered | Xi'an Lyphar Biotech, NOW Foods, Givaudan SA, Amino Up Chemical Co., Ltd., PLT Health Solutions Inc., Indena S.p.A., Layn Natural Ingredients Co., Ltd., NutraGreen Biotechnology Co., Ltd., Sabinsa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garcinia Cambogia Extract Market Shifts & Advancements
Supercritical CO2 extraction is displacing conventional solvent-based processing, enabling cleaner label positioning and organic certification capture. This technology shift is compressing the supplier base toward capital-intensive operators while opening premium price tiers.
Encapsulation technology is integrating liposomal and nano-emulsion delivery systems to address hydroxycitric acid's bioavailability constraints. Functional food manufacturers in Japan and South Korea are adopting these formats for beverage applications. The structural consequence is a bifurcation between commodity powder suppliers and formulation-technology licensors.
EFSA novel food assessment protocols are tightening evidentiary requirements for non-traditional botanical preparations. Extractors must now submit comprehensive toxicology dossiers and stability data to access EU pharmacy channels. German and Dutch importers are responding by consolidating procurement relationships with cultivators maintaining multi-year batch records.
Direct-to-consumer subscription models are capturing repeat purchase volumes previously routed through retail pharmacy. US-based supplement brands are building proprietary extract supply chains to support personalized nutrition platforms. This channel shift is most visible in California and Texas, where telehealth-integrated wellness programs bundle metabolic support products with diagnostic services.
Garcinia Cambogia Extract Market Segmentation
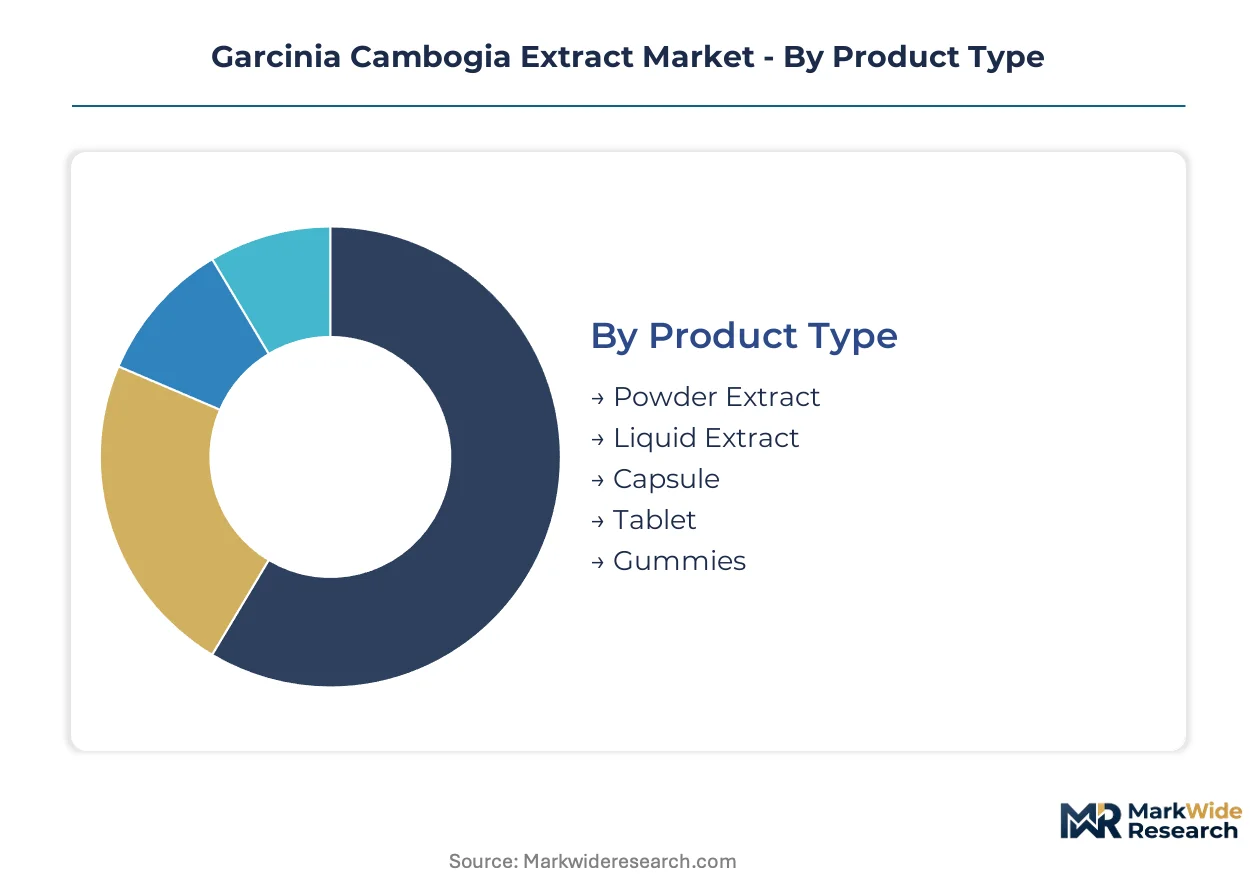
Extract standardization protocols and delivery format preferences fragment procurement patterns across nutraceutical channels. Manufacturers configure production lines around specific segment requirements, from high-volume powder throughput to precision-dosed gummy confectionery.
Product Type:
Powder extract capacity concentrates in Shaanxi Province facilities serving capsule and tablet contract manufacturers.
- Powder Extract:Spray-dried material standardized to 50-60% hydroxycitric acid dominates bulk procurement from nutraceutical manufacturers. Indian and Chinese processors in Kerala and Shaanxi supply multi-tonne orders to US and German encapsulation facilities.
- Gummies:Confectionery-format delivery systems capture younger demographics rejecting traditional capsules. South Korean and Japanese functional food manufacturers are absorbing powder extract volumes for pectin-based gummy production lines.
- Liquid Extract:Tincture formats serve boutique wellness brands and compounding pharmacies requiring dose flexibility.
- Capsule:Hard gelatin and vegetable cellulose shells remain the default delivery vehicle for US dietary supplement brands.
- Tablet:Direct-compression formulations suit high-volume weight management SKUs in mass retail channels.
Today's leader: Powder Extract. Tomorrow's challenger: Gummies.
Application:
Cost tier differentiation separates premium pharmacy-positioned metabolic health products from economy weight management SKUs.
- Weight Management:Thermogenic and lipogenesis-inhibition claims anchor the largest revenue pool despite FDA restrictions on specific messaging. US direct-to-consumer brands and German pharmacy networks sustain procurement volumes.
- Sports Nutrition:Pre-workout metabolic support formulations are climbing the fastest as fitness-focused brands incorporate garcinia cambogia into energy and endurance positioning. Contract manufacturers in California and Texas report accelerating purchase orders.
- Appetite Suppressant:Satiety-focused formulations target intermittent fasting protocols and meal-replacement programs.
- Dietary Supplement:General wellness positioning captures broad demographic reach through mass-market retail and online subscription models.
- Metabolic Health:Glucose metabolism and lipid profile claims serve premium positioning in functional medicine and integrative health channels.
Primary volume concentration: Weight Management. Steepest expansion trajectory: Sports Nutrition.
End User:
Customer type fragmentation reflects channel margin structures, from low-touch online retail to high-touch pharmacy consultation.
- Nutraceutical Manufacturers:Contract manufacturers and branded formulators in the United States and Germany drive standardized extract procurement. These entities require batch-to-batch consistency for GMP-certified production lines.
- Pharmacies:German Apotheken and Italian farmacia networks command premium pricing for EFSA-compliant novel food preparations. Pharmacy channel penetration offers margin structures unavailable in mass-market distribution.
- Health & Wellness Centers:Integrative medicine clinics and weight loss programs prescribe practitioner-grade formulations.
- Fitness Enthusiasts:Direct purchasing through specialty retailers and brand websites supports sports nutrition application growth.
- Online Retailers:Amazon, iHerb, and direct-to-consumer platforms capture repeat purchase volumes through subscription models.
Dominant procurement source: Nutraceutical Manufacturers. Emerging channel priority: Pharmacies.
Packaging Type:
Volume scale and shelf-life requirements determine primary packaging selection across distribution channels.
- Bottle:HDPE and PET containers with desiccant inserts protect hygroscopic powder from moisture degradation. Standard for 60-180 count capsule and tablet SKUs in US retail.
- Sachet:Single-serve stick packs serve travel formats and sampling programs in Asian markets. Japanese and South Korean functional beverage manufacturers favor this configuration.
- Blister Pack:Unit-dose aluminum-PVC formats suit pharmacy dispensing and clinical trial supply.
- Jar:Wide-mouth containers accommodate bulk powder and gummy formats in club retail channels.
- Tub:Protein powder-style packaging serves high-volume sports nutrition positioning.
Current standard: Bottle. Format gaining traction: Sachet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Garcinia cambogia extract production originated in the humid coastal forests of southwestern India, where traditional Ayurvedic practitioners first documented the fruit's metabolic properties. Commercial cultivation subsequently expanded to Indonesia and Thailand before Chinese processors in Shaanxi Province industrialized solvent extraction at scale. Today's procurement patterns reflect this dispersed heritage, with quality verification protocols now determining channel access across major import markets.
United States
FDA Dietary Supplement Health and Education Act enforcement shapes label claim boundaries for weight management products. The agency's adverse event reporting requirements compel brands to maintain batch traceability from Kerala cultivators through encapsulation facilities. California and Texas host the densest concentrations of sports nutrition contract manufacturers, where pre-workout formulation demand absorbs standardized powder volumes.
Germany
EFSA novel food assessments govern market entry for non-traditional botanical preparations seeking pharmacy retail placement. REACH compliance obligations for hydroxycitric acid imports have concentrated procurement among vertically integrated suppliers with in-house analytical laboratories. The Apotheken channel in Bavaria and North Rhine-Westphalia commands margin premiums unavailable in mass-market distribution.
China
NMPA botanical registration requirements create access barriers to domestic health product channels for unapproved foreign extracts. Shaanxi Province anchors global powder extract capacity, with Xi'an-based processors serving capsule and tablet manufacturers across North America and Europe. Dual carbon goals are accelerating supercritical CO2 adoption as solvent-based methods face environmental compliance pressure.
India
FSSAI purity thresholds diverge from Chinese and US standards, forcing parallel production runs for export-oriented processors. Monsoon-driven supply interruptions in Kerala and Karnataka cultivation clusters expose processors to raw material quality inconsistency. The country's national pharmaceutical regulator maintains distinct hydroxycitric acid quantification protocols that complicate cross-border formulation standardization.
Japan
METI guidance on functional food ingredient safety shapes encapsulation technology adoption for beverage applications. PMDA oversight of metabolic health claims restricts weight-loss messaging while permitting lipid metabolism positioning. Functional food manufacturers in Tokyo and Osaka prefectures are integrating liposomal delivery systems to address bioavailability constraints.
Garcinia Cambogia Extract Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the garcinia cambogia extract value chain. The supplier base fragments between integrated cultivator-processors maintaining captive raw material supply and specialized extractors relying on spot market procurement. Three archetypes dominate: vertically integrated operators controlling cultivation through spray-drying, formulation-technology licensors commanding premium tiers via delivery system patents, and commodity powder suppliers competing on throughput scale. Competitive intensity concentrates on clean-label extraction technology licensing and pharmacy channel certification attainment.
Within the integrated cultivation tier, Xi'an Lyphar Biotech occupies a position exemplifying Shaanxi Province's concentration of solvent extraction capacity. NOW Foods represents the certified manufacturing archetype competing through direct-to-consumer channel control. Givaudan SA anchors the flavor-house crossover segment, leveraging existing infrastructure to serve functional food applications with standardized extract grades.
| Leading Market Players |
|---|
| Xi'an Lyphar Biotech |
| NOW Foods |
| Givaudan SA |
| Amino Up Chemical Co., Ltd. |
| PLT Health Solutions Inc. |
| Indena S.p.A. |
| Layn Natural Ingredients Co., Ltd. |
| NutraGreen Biotechnology Co., Ltd. |
| Sabinsa Corporation |
| Others |
Supply & Pricing Matrix
Analytical chemist clusters in Shaanxi Province anchor labor-cost differentials that widen pricing spreads between commodity-grade powder and pharmacy-certified extract tiers. HPLC method development expertise commands premium wages that concentrate in coastal Chinese laboratories, compressing margins for processors lacking in-house quantification capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies procurement by certification grade and channel positioning. EFSA-compliant novel food preparations command pharmacy retail premiums, while uncertified bulk powder serves mass-market supplement brands. Pricing pressure stems from supercritical CO2 capital requirements that disadvantage solvent-dependent processors. Contract manufacturers exhibit highest price sensitivity; German Apotheken buyers absorb premium tiers for regulatory security.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke patterns for hydroxycitric acid shipments. Cultivation concentrates in Kerala and Karnataka, India, with Shaanxi Province anchoring extraction capacity. Raw material flows draw from monsoon-exposed fruit rind harvests, standardized solvents, and desiccant packaging materials. Single-source vulnerability in Indian cultivation clusters threatens batch consistency. Distribution runs through Rotterdam for EU pharmacy channels and Long Beach for US dietary supplement manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Novel Food Regulation compliance acts as a regulatory compounder, with EFSA assessment milestones driving pharmacy channel premiums that reshape procurement priorities.
For Market Incumbents: Hedge against supercritical CO2 displacement by securing backward integration into Shaanxi cultivation partnerships. Diversify beyond solvent-dependent extraction before environmental compliance costs erode standard-grade margins. Certification investment in EFSA novel food pathways defends pharmacy positioning against emerging clean-label competitors. For New Entrants and Emerging Players: EU REACH compliance in Germany opens a window for analytical-service differentiation targeting mid-tier processors lacking in-house HPLC capabilities. White-space exists in liposomal delivery system licensing for Japanese functional beverage manufacturers. Sports nutrition contract manufacturers in Texas represent the most penetrable buyer segment for bioavailability-enhanced formulations. For Investors and Strategic Acquirers: Flavor-house conglomerates are the most active acquirer in this space, leveraging existing botanical infrastructure for functional food crossover. Long-term viability hinges on pharmacy channel certification moats rather than commodity powder scale. Monitor EFSA novel food approval velocity as the inflection indicator for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Registration | Unlocks German Apotheken channel access with margin premiums unavailable in mass retail. |
| Supercritical CO2 Capacity Buildout | Enables organic certification capture and displaces solvent-dependent competitors in Shaanxi. |
| Sports Nutrition Partnership | Secures pre-workout formulation slots with California and Texas contract manufacturers. |
| Liposomal Delivery Licensing | Addresses hydroxycitric acid bioavailability constraints for Japanese beverage applications. |
| Direct-to-Consumer Subscription | Captures repeat purchase volumes through telehealth-integrated wellness platforms. |
Research Methodology
Multiple input streams — primary interviews with extraction facility managers, regulatory affairs specialists at EFSA and FDA, pharmacy procurement leads, and sports nutrition formulators — were reconciled against secondary validation from customs records, botanical trade databases, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume estimates from Shaanxi and Kerala processing capacities were triangulated with top-down demand modeling across US and German distribution channels.
Data-stream reconciliation anchored analytical framework construction across the projection horizon. Segmentation dimensions modeled include extract standardization grade, delivery format, application end-use, and regulatory compliance tier. CAGRs were derived from volume trajectory analysis incorporating hydroxycitric acid stability constraints and pharmacy channel penetration rates. Industry-specific inputs encompassed monsoon-driven supply interruption frequencies and EFSA assessment queue durations.
Revisions become necessary when EFSA novel food approval timelines extend, REACH compliance obligations expand, or supercritical CO2 adoption accelerates beyond current capital deployment patterns. Forecasts reflect assumptions about regulatory stability and cultivation yield consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market