
 North America Fruits and Vegetables Juice Market | 2026-2036
North America Fruits and Vegetables Juice Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fruits and Vegetables Juice Market Analytics
Health-focused millennials and Gen Z consumers are rotating toward premium, functional juice offerings with probiotic and adaptogenic claims. The Coca-Cola Company leverages its Minute Maid distribution network to sustain shelf dominance across mass retail channels. PepsiCo anchors its Tropicana portfolio with fortified variants targeting immune support positioning. Ocean Spray Cranberries differentiates through cooperative sourcing structures that control cranberry supply from Wisconsin and Massachusetts growers.
North America fruits and vegetables juice comprises extracted, pressed, or concentrated liquids from agricultural produce, typically processed through pasteurization or high-pressure processing to achieve shelf stability while retaining organoleptic properties and bioactive compounds such as vitamin C, polyphenols, and carotenoids. The category serves commercial refreshment, home consumption, and foodservice ingredient applications where natural positioning and clean-label credentials command price premiums. Citrus juice remains the volume anchor due to established breakfast rituals and year-round orange supply from Florida and Mexico, while beet juice and carrot juice represent the fastest-growing product types as fitness-oriented consumers adopt vegetable-centric formulations for nitrate content and antioxidant profiles. Tetra packs capture expanding share in health food stores and online retail channels where aseptic technology extends shelf life without refrigeration, though bottles still dominate supermarkets where visual branding and refrigerated placement drive impulse selection.
The FDA governs juice safety through Hazard Analysis Critical Control Point mandates and the Juice HACCP regulation requiring pathogen reduction treatments for all non-retail juice processing. USDA organic certification and California's Proposition 65 warning requirements for heavy metals create layered compliance thresholds that filter smaller processors from premium channel access. The Canadian Food Inspection Agency enforces Safe Food for Canadians Regulations that align with U.S. standards while maintaining distinct bilingual labeling protocols. Stakeholders must monitor evolving state-level extended producer responsibility legislation for packaging waste, as California and New York advance rules that will shift cost structures toward circular packaging investments and away from single-use plastics.
Market Dynamics
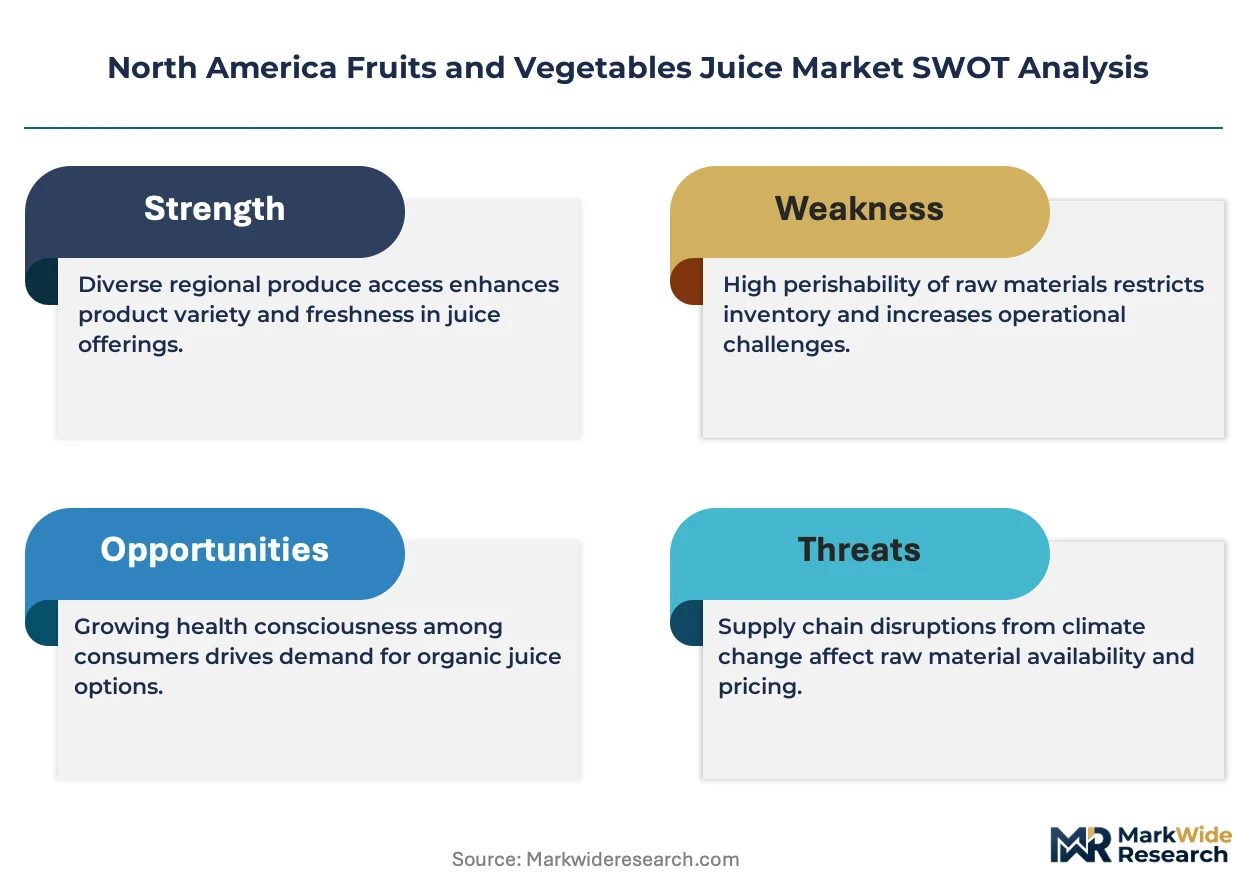
Cold-pressed processing technology and high-pressure processing systems are compressing shelf-life differentials between premium and mass-market juice tiers, forcing processors to recalibrate capital deployment toward equipment that preserves heat-sensitive bioactives without refrigeration dependency.
Growth Catalysts
- California Proposition 65 compliance investments:Processors upgrading heavy-metal testing protocols are capturing shelf space in natural grocery channels where warning-label avoidance commands price premiums.
- High-pressure processing equipment:Adoption among mid-scale processors is eliminating thermal degradation of vitamin C and polyphenols, enabling clean-label claims that resonate with fitness-oriented consumers.
- Florida citrus belt infrastructure:Dense clustering of extraction facilities and concentrate plants minimizes inbound logistics costs for orange and grapefruit processors serving breakfast ritual demand.
Market Restraints
- Concentrate price volatility:Brazilian orange concentrate supply fluctuations transmit directly into North American processor margins, squeezing formulation flexibility for value-tier products.
- Single-serve packaging waste regulations:Extended producer responsibility legislation advancing in California and New York threatens to impose circular economy compliance costs that smaller bottlers cannot absorb.
- Refrigerated distribution infrastructure gaps:Cold-chain limitations in rural and secondary markets constrain chilled juice penetration, preserving shelf-stable concentrate dominance in those geographies.
Strategic Opportunities
- Midwestern vegetable juice underpenetration:Wisconsin and Michigan processing capacity expansion could capture local beet and carrot supply currently flowing to ingredient markets rather than branded retail.
- Functional ingredient convergence:Probiotic strain stability in high-acid juice matrices, combined with adaptogenic botanical extraction, opens positioning against kombucha and functional beverage categories.
- Direct-to-subscription channel development:Cold-pressed subscription models bypass traditional retail slotting fees and capture consumer lifetime value through recurring revenue structures.
Industry Challenges
- Juice HACCP technical specialist scarcity:FDA-mandated pathogen reduction expertise commands salary premiums that strain mid-tier processor operating budgets.
- Organic certification timeline compression:USDA organic transition periods and documentation requirements delay new product launches, constraining responsiveness to emerging ingredient trends.
- Legacy pasteurization asset stranding:Thermal processing equipment depreciation schedules conflict with cold-pressed positioning demands, complicating capital reallocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fruits and Vegetables Juice Market |
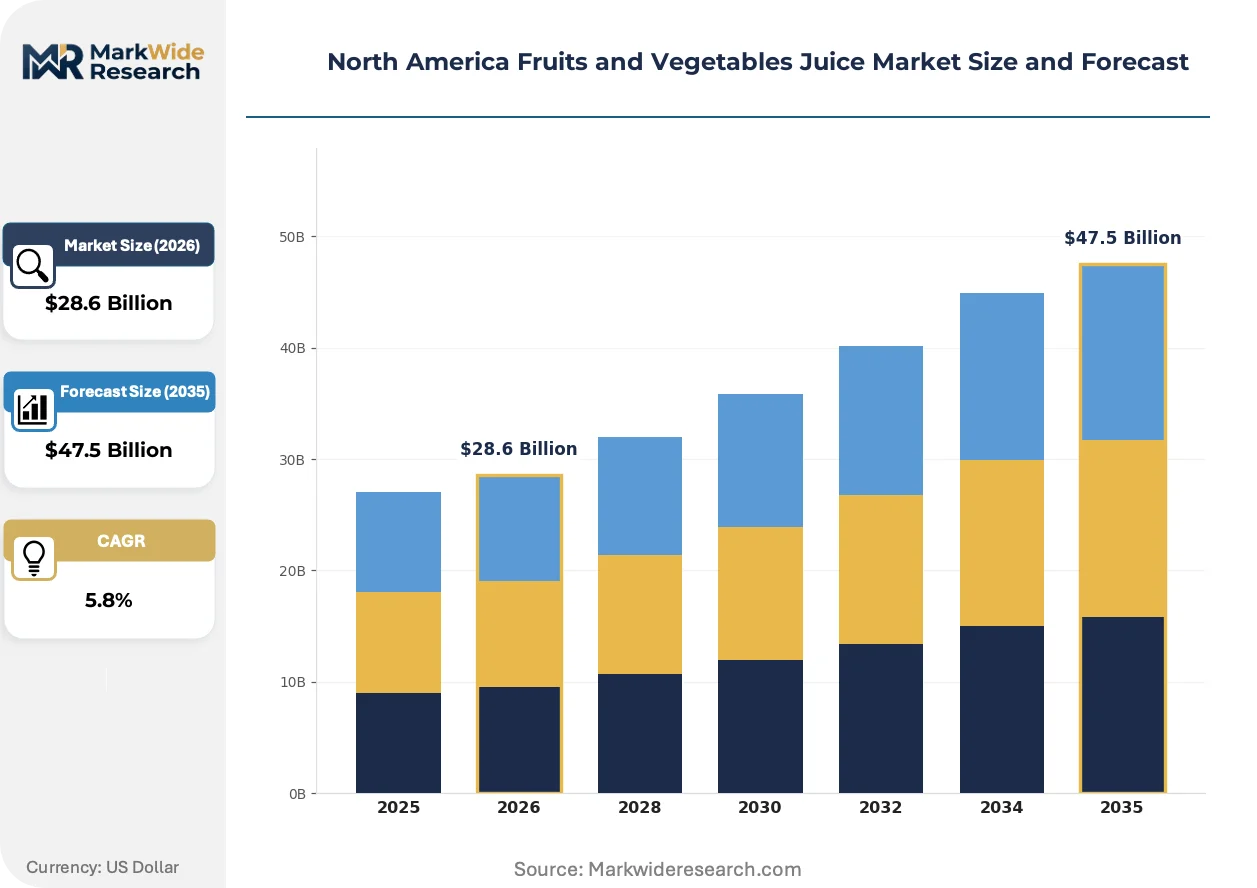
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Juice, Tomato Juice, Carrot Juice, Beet Juice Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores End User: Households, Restaurants, Cafes, Juice Bars |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc., The Kraft Heinz Company, Keurig Dr Pepper, Campbell Soup Company, Del Monte Foods Inc., Ocean Spray Cranberries Inc., Welch Foods Inc., Citrus World Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fruits and Vegetables Juice Market Evolving Landscape
Processing technology evolution and regulatory labeling mandates are compressing formulation cycles while consumer preference rotation toward vegetable-centric and functional blends is redefining category boundaries beyond traditional fruit dominance.
High-pressure processing is fragmenting the technical barrier between refrigerated premium juices and ambient shelf-stable alternatives. Mid-scale processors in California and Texas are deploying HPP tunnels to achieve 45-60 day ambient shelf life without thermal degradation. This capability compression is enabling regional brands to challenge national distribution networks that previously relied on refrigerated logistics as a competitive moat.
The FDA's updated Nutrition Facts labeling requirements are forcing added-sugar disclosure granularity that reshapes formulation priorities. Processors must now distinguish between naturally occurring and added sugars on front-facing panels, pressuring blends that rely on concentrate reconstitution. Tropicana and Minute Maid portfolio managers are responding with not-from-concentrate line extensions and reduced-sugar variants that preempt state-level sugar tax exposure in Illinois and California legislative discussions.
Fitness-oriented consumers are rotating consumption occasions from breakfast-centric orange juice toward pre-workout vegetable formulations. Beet juice nitrate content and carrot juice antioxidant positioning are capturing share among CrossFit and endurance athlete communities. This demand rotation is most visible in Colorado, California, and Pacific Northwest metropolitan markets where specialty fitness retail and juice bar density supports premium pricing for functional vegetable blends.
North America Fruits and Vegetables Juice Market Segmentation
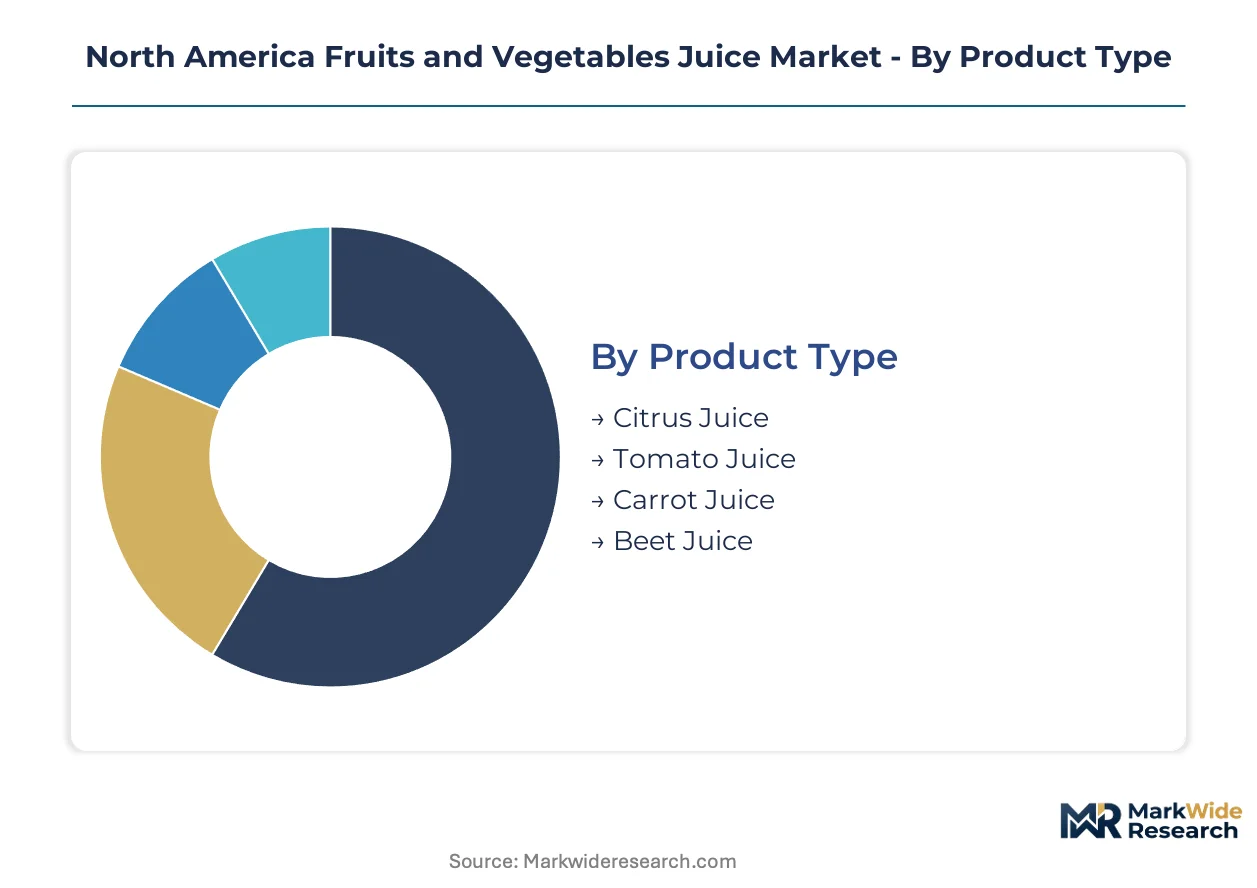
Segmentation in the North America fruits and vegetables juice market reveals how processing technology, packaging format, and channel access determine margin capture. Each dimension carries distinct capital requirements and regulatory exposure that shape competitive positioning across the value chain.
Product Type:
Margin pools concentrate in vegetable-centric formulations where functional claims command shelf price premiums.
- Citrus Juice:Orange and grapefruit extracts dominate volume through established breakfast consumption rituals. Florida's citrus belt processing infrastructure anchors supply reliability for processors serving mass retail channels.
- Beet Juice:High nitrate content targets pre-workout fitness segments in Colorado and California metropolitan markets. Cold-pressed processing preserves bioactive compounds that support premium positioning against sports nutrition alternatives.
- Carrot Juice:Beta-carotene antioxidant claims resonate with wellness-oriented households seeking vegetable-forward alternatives.
- Tomato Juice:Savory flavor profile captures Bloody Mary cocktail ingredient demand and sodium-conscious savory refreshment occasions.
The dominant share belongs to Citrus Juice, while Beet Juice is expanding most quickly through fitness channel penetration.
Packaging Type:
Channel access constraints and shelf-life requirements create tiered margin structures across material formats.
- Tetra Packs:Aseptic technology enables ambient distribution without refrigeration dependency. Health food stores and online retail channels favor this format for extended shelf life and reduced logistics complexity.
- Bottles:Visual branding real estate and refrigerated placement drive impulse selection in supermarkets. PET and glass variants carry distinct sustainability positioning that influences California and New York consumer preference.
- Cans:Aluminum recycling infrastructure supports circular economy claims in jurisdictions advancing extended producer responsibility legislation.
- Pouches:Flexible format reduces shipping cube and appeals to on-the-go consumption occasions in convenience retail.
Bottles retain the largest installed base, though Tetra Packs are gaining share fastest through e-commerce channel expansion.
Distribution Channel:
Slotting fee structures and cold-chain requirements fragment margin capture across retail formats.
- Supermarkets:Refrigerated case placement commands the highest foot traffic but incurs substantial trade spending. Minute Maid and Tropicana portfolio managers defend position through exclusive placement agreements.
- Health Food Stores:Clean-label curation and local brand inclusion support premium pricing for cold-pressed and organic variants. California's Proposition 65 compliance investments filter competitor access.
- Online Retail:Direct-to-consumer subscription models bypass traditional slotting fees and capture recurring revenue structures.
- Convenience Stores:Shelf-stable concentrate dominance persists where refrigerated distribution infrastructure gaps constrain chilled juice penetration.
Supermarkets control the volume anchor, yet Health Food Stores are climbing the fastest through premium assortment expansion.
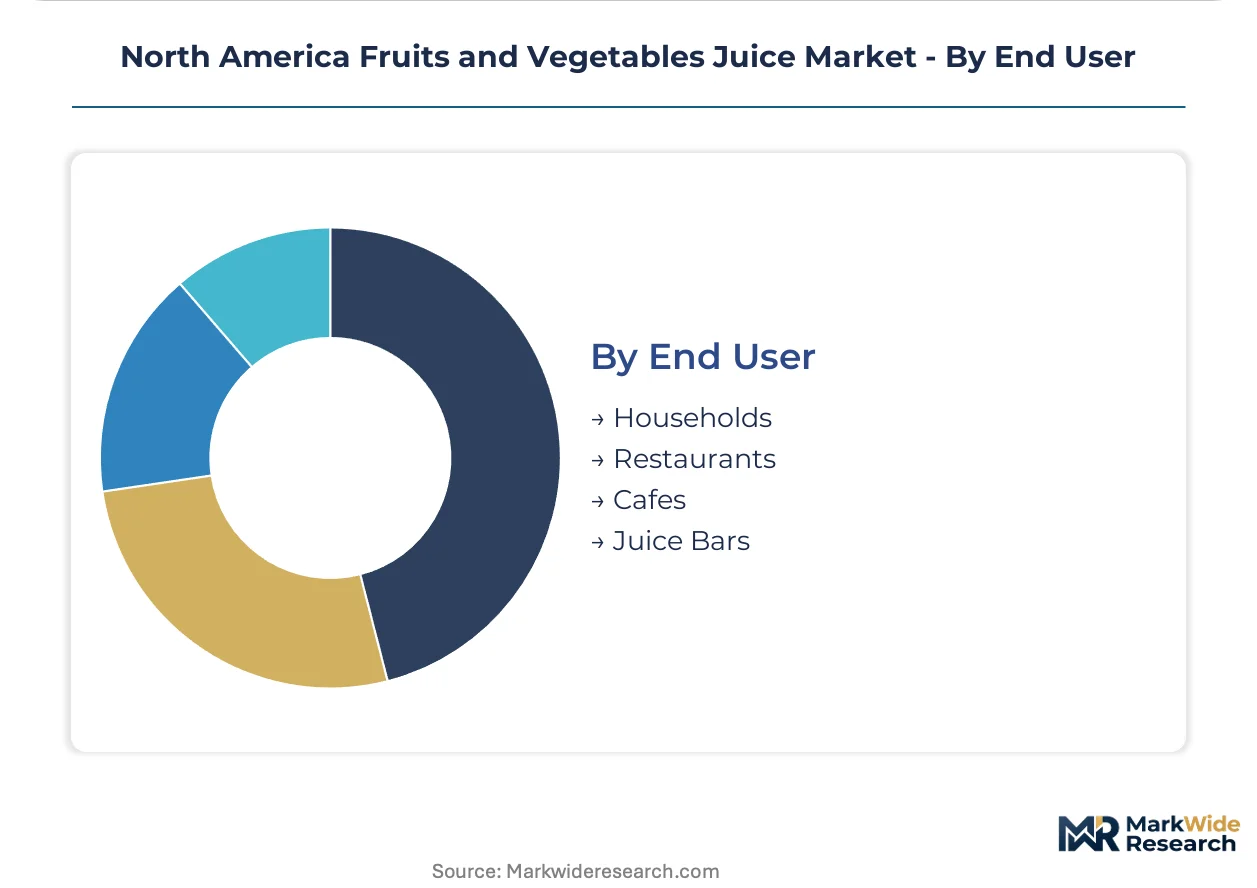
End User:
Consumption occasion differentiation separates institutional procurement from household purchasing patterns.
- Juice Bars:Cold-pressed and functional blend rotation captures health-conscious consumer spending through experiential service formats. Equipment depreciation for high-pressure processing systems concentrates investment risk.
- Households:Breakfast ritual anchoring sustains citrus volume, while vegetable-centric formulations expand through fitness-oriented purchase behavior.
- Restaurants:Cocktail ingredient demand and brunch service occasions support bulk concentrate procurement.
- Cafes:Specialty coffee adjacencies create cross-merchandising opportunities for premium juice offerings.
Households generate the dominant revenue base, while Juice Bars are capturing share fastest through functional positioning and subscription retention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican citrus exports flow northward into California and Florida processing facilities, anchoring cross-border supply chains that feed retail distribution networks across the United States and Canada.
United States
California's Central Valley and Florida's citrus belt concentrate extraction infrastructure and concentrate production capacity. FDA Juice HACCP regulations mandate pathogen reduction treatments that filter smaller processors from interstate commerce. Chicago and New York metropolitan markets drive cold-pressed subscription growth through dense fitness-oriented consumer bases.
Canada
Health-conscious households in Toronto and Vancouver propel demand for organic and functional juice variants. The Canadian Food Inspection Agency enforces Safe Food for Canadians Regulations with bilingual labeling protocols that add compliance complexity for U.S. exporters. Quebec's agricultural processing corridor near Montreal hosts concentrate reconstitution facilities serving eastern provinces.
Mexico
Veracruz and Tamaulipas citrus groves supply orange concentrate to North American processors under seasonal harvest cycles. Mexican agricultural regulators coordinate phytosanitary certifications with USDA import requirements. Guadalajara's emerging cold-pressed juice sector targets domestic health food retail expansion.
North America Fruits and Vegetables Juice Market Competitive Landscape
Listed leaders compete with private specialists across distribution network scale, creating a tiered structure where multinational beverage conglomerates defend mass retail shelf space against regional cold-pressed entrants. Three strategic archetypes dominate: diversified beverage conglomerates with legacy concentrate infrastructure, cooperative sourcing organizations controlling specific agricultural supply, and subscription-based cold-pressed specialists bypassing traditional retail. Competitive moves concentrate on exclusive placement agreements with supermarket chains and high-pressure processing equipment investments that compress shelf-life differentials.
Within the diversified beverage tier, The Coca-Cola Company and PepsiCo Inc. exemplify scale-driven distribution dominance through established concentrate and not-from-concentrate portfolios. Ocean Spray Cranberries Inc. represents cooperative sourcing archetypes that vertically integrate agricultural supply from member growers. These three entities anchor competitive positioning across mass retail, natural grocery, and foodservice channels respectively.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc. |
| The Kraft Heinz Company |
| Keurig Dr Pepper |
| Campbell Soup Company |
| Del Monte Foods Inc. |
| Ocean Spray Cranberries Inc. |
| Welch Foods Inc. |
| Citrus World Inc. |
| Others |
Value Network & Pricing Analysis
Florida citrus belt capacity utilization above 85 percent compresses per-unit extraction costs for orange processors while simultaneously anchoring price floors for premium cold-pressed entrants who lack comparable scale economies. This concentration dynamic forces mid-tier processors to absorb Brazilian concentrate volatility or invest in high-pressure processing equipment that preserves margin through extended shelf-life claims.
Pricing Analysis
Cold-pressed technology-generation pricing gaps separate ambient shelf-stable concentrates from refrigerated premium tiers and emerging functional blends. Three-tier pricing structure across premium organic, standard not-from-concentrate, and economy reconstituted levels reflects HPP certification investment and organic USDA compliance costs. Pricing pressure intensifies in standard tiers as state-level sugar tax discussions in California and Illinois force added-sugar disclosure granularity that erodes brand equity. Households remain most price-sensitive through breakfast ritual volume purchasing, while fitness-oriented consumers in Colorado and California metropolitan markets exhibit lowest sensitivity for pre-workout vegetable formulations.
Supply Chain Analysis
Strategic stockpile preferences dominate citrus concentrate procurement as processors buffer against Brazilian orange harvest volatility and Veracruz seasonal supply fluctuations. Raw material dependencies center on Florida and Mexican citrus groves, Wisconsin and Massachusetts cranberry bogs, and emerging California Central Valley vegetable sourcing for beet and carrot formulations. Single-source vulnerability concentrates in Brazilian concentrate supply that transmits directly into North American processor margins. Distribution runs through refrigerated logistics networks serving supermarket chains, with ambient Tetra Pack channels expanding through health food retail and direct-to-subscription models that bypass traditional slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription retention models and cold-pressed direct-to-consumer channels expand recurring-revenue capture faster than branded retail hardware, transforming juice market economics toward service-attach frameworks that prioritize lifetime value over single-transaction margin extraction.
For Market Incumbents: Secure exclusive placement agreements with supermarket chains defending refrigerated case positioning against regional cold-pressed entrants deploying high-pressure processing equipment. Invest in backward integration into Florida citrus belt extraction capacity to buffer Brazilian concentrate volatility and anchor supply reliability for breakfast ritual volume. Certification investment in California Proposition 65 compliance filters competitor access to natural grocery channels where warning-label avoidance commands price premiums. For New Entrants and Emerging Players: Anchor in Midwestern vegetable juice underpenetration where Wisconsin and Michigan processing capacity expansion could capture local beet and carrot supply currently flowing to ingredient markets rather than branded retail. Target fitness-oriented consumers in Colorado and Pacific Northwest metropolitan markets through cold-pressed subscription models that bypass traditional retail slotting fees and capture recurring revenue structures. Emphasize nitrate content and antioxidant positioning in direct-to-consumer marketing to differentiate against mass-market concentrate alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based cold-pressed specialists with HPP equipment depreciation schedules already absorbed and established consumer lifetime value metrics. Long-term viability over a five-to-ten-year window favors processors with captive supply agreements in Florida citrus belt or cooperative sourcing structures controlling specific agricultural inputs. Acquisition target archetypes include mid-scale HPP-equipped processors with natural grocery channel access and direct-to-subscription infrastructure. The signal to watch is state-level extended producer responsibility legislation advancing in California and New York that would impose circular economy compliance costs filtering smaller competitors from premium channel access.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Equipment Deployment | HPP tunnel investment preserves vitamin C and polyphenols while enabling 45-60 day ambient shelf life without thermal degradation. |
| Direct-to-Subscription Channel Development | Recurring revenue models bypass supermarket slotting fees and capture consumer lifetime value through retention-based economics. |
| Organic Certification Investment | USDA organic compliance filters competitor access to health food store channels where clean-label curation supports premium pricing. |
| Midwestern Processing Capacity Expansion | Wisconsin and Michigan facilities capture local beet and carrot supply currently diverted to ingredient markets. |
| Functional Ingredient Convergence | Probiotic strain stability in high-acid matrices opens positioning against kombucha and functional beverage categories. |
Research Methodology
Desk research of FDA Juice HACCP regulatory filings, USDA organic certification databases, and Nielsen retail audit data preceded structured interviews with juice processing plant managers, health food store category buyers, cold-pressed subscription service operators, and Florida citrus belt agricultural cooperatives. Primary fieldwork combined with secondary validation from trade association reports and customs import records enabled bottom-up volume triangulation against top-down category spend estimates.
Variance decomposition across product type, packaging format, distribution channel, and end-user segments isolated growth contribution by tier. CAGRs derive from segment-level volume trajectories and price index movements across the modeling period, with specific inputs including Brazilian concentrate supply forecasts, California Proposition 65 enforcement patterns, and HPP equipment adoption curves among mid-scale processors.
Material uncertainties — Brazilian harvest volatility, state-level sugar tax enactment, extended producer responsibility compliance cost imposition — sit outside the modeled envelope. Forecasts reflect assumptions regarding cold-chain infrastructure expansion and fitness-oriented consumption rotation. Revision becomes warranted when HPP equipment cost curves cross thresholds enabling mass-market ambient distribution parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
CBD-Infused Beverages Market
Beverages
Relaxation Beverages Market
Beverages
Premium Water Market
Beverages
Caffeinated Beverage Market
Beverages
North America Yerba Mate Market
Beverages
Fruit Juices and Nectars Market
Beverages
South East Asia Bottled Water Market
Beverages
Apple Cider Vinegar Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Foaming Creamer Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
South America Mate Market
Beverages
Powdered Beverages Market
Beverages
Nitro-Infused Beverages Market
Beverages
Pineapple Juice Market
Beverages
Wellness Water Market