
 Europe Food Colorants Market | 2026-2036
Europe Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Colorants Market Foresight
EFSA's additive authorization cycle is bifurcating the competitive landscape into clean-label specialists and legacy synthetic producers. Sensient Technologies leverages its botanical extraction infrastructure to dominate natural colorant supply for premium beverage clients. BASF SE anchors its position through petrochemical-derived pigment scale, though it navigates tightening azo-dye restrictions across EU member states. Chr. Hansen A/S differentiates through fermentation-based carotenoid platforms that bypass agricultural supply volatility.
Food colorants comprise chromophore-bearing compounds—anthocyanins, carotenoids, curcuminoids, or azo/pyrazole synthetics—dispersed at 0.01-0.5% inclusion rates to impart visual identity, mask process variation, or signal flavor intensity. Their primary commercial function is reducing consumer rejection of formulated foods where thermal or oxidative degradation has dulled native pigmentation. Natural colorants command premium positioning in beverages and dairy products, where E-number aversion drives substitution away from synthetic colorants in mid-tier retail channels. Powder and liquid forms split along application equipment compatibility, with high-throughput bakeries favoring dust-free granules while artisan producers prefer liquid dosing precision.
EFSA, the EU Green Deal framework, and REACH collectively govern colorant safety assessments, sustainability disclosure, and chemical hazard classification—creating compliance cost barriers that favor larger producers with dedicated regulatory affairs teams. The F-Gas Regulation indirectly pressures synthetic pigment manufacturing through solvent recovery mandates. Stakeholders must monitor EFSA's pending opinions on titanium dioxide and certain azo dyes, as negative determinations would force rapid portfolio restructuring across confectionery and bakery supply chains.
Market Dynamics
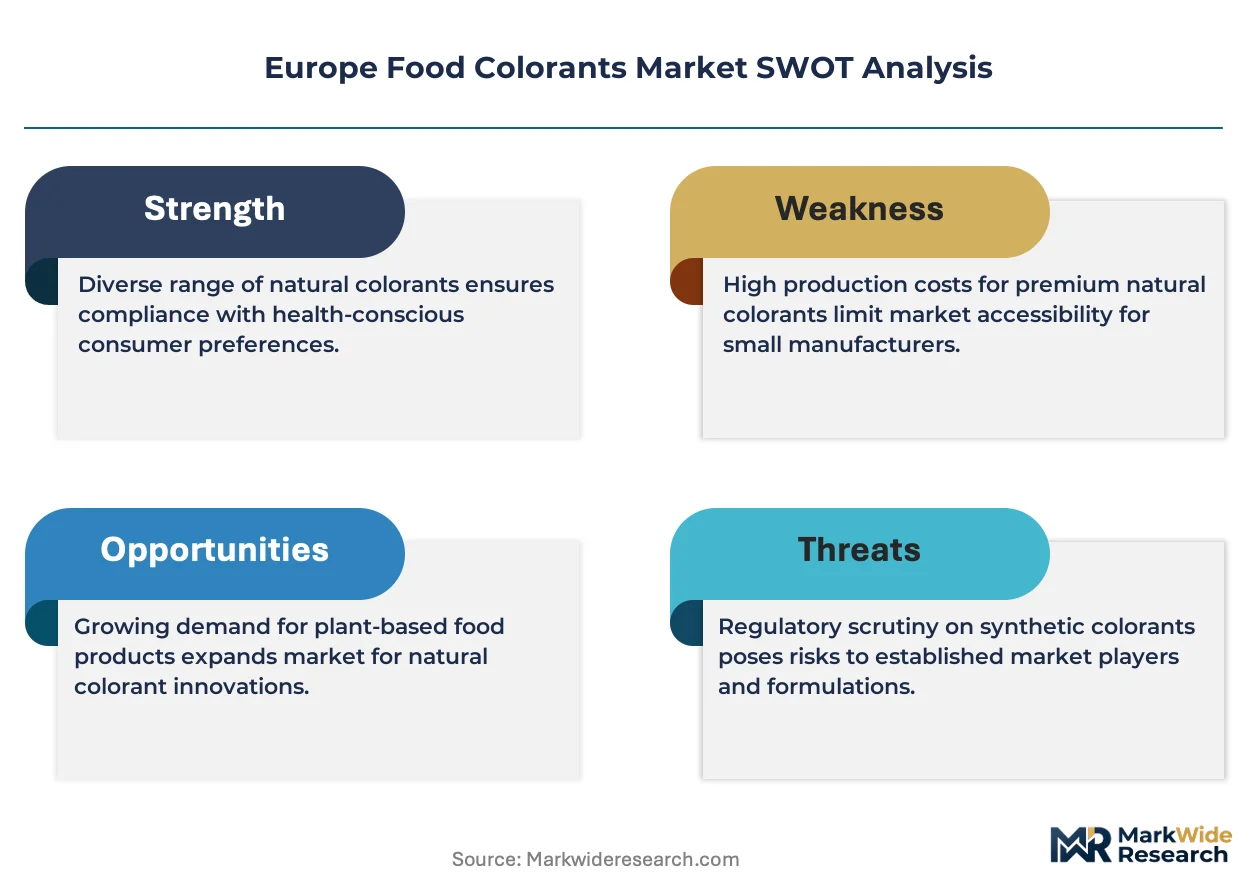
EFSA's additive re-evaluation cycle is compressing reformulation timelines across European food manufacturing, forcing simultaneous portfolio restructuring toward botanical-derived pigments while synthetic legacy stocks depreciate.
Growth Catalysts
- EU Green Deal sustainability mandates:Carbon disclosure requirements under CSRD are redirecting procurement budgets toward fermentation-based and agricultural-extraction colorant platforms with verified lifecycle credentials.
- Clean-label bakery demand:German, French, and Italian processed food manufacturers are expanding anthocyanin and beetroot pigment volumes to replace azo dyes in retail-facing packaged goods.
- F-Gas Regulation solvent recovery standards:Synthetic pigment producers are retrofitting manufacturing assets to comply with tightened volatile organic compound handling rules, creating equipment upgrade cycles that favor natural extraction infrastructure.
Market Restraints
- Agricultural input volatility:Beetroot and grape-skin anthocyanin supplies fluctuate with seasonal harvest yields across Southern European growing regions, compressing margin predictability for natural colorant specialists.
- EFSA authorization timelines:Novel food additive safety assessments now average 18-24 months, freezing pipeline commercialization for fermentation-derived carotenoid innovations.
- Synthetic legacy asset lock-in:Petrochemical-derived pigment production facilities in Northwest Europe carry stranded cost risk as member-state azo dye restrictions tighten ahead of harmonized EU-wide prohibitions.
Strategic Opportunities
- Eastern European processing expansion:Polish and Romanian contract manufacturing hubs are attracting natural colorant toll production investments to serve proximity advantages into Central European beverage markets.
- Fermentation platform scale-up:Precision fermentation of carotenoid molecules offers batch-to-batch consistency that agricultural extraction cannot match, opening premium positioning in infant nutrition and clinical food applications.
- REACH-registered bio-based alternatives:Early registrants of novel plant-derived chromophores are securing preferred supplier status with multinational food manufacturers ahead of 2027-2030 synthetic dye phase-out deadlines.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified toxicologists and food law specialists capable of navigating EFSA's evolving guidance on nano-scale colorant particles command premium compensation, constraining mid-tier producer compliance capacity.
- Cross-contamination control capex:Dual-use manufacturing facilities require segregated production lines and dedicated cleaning validation protocols to maintain natural certification integrity alongside legacy synthetic operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Colorants Market |
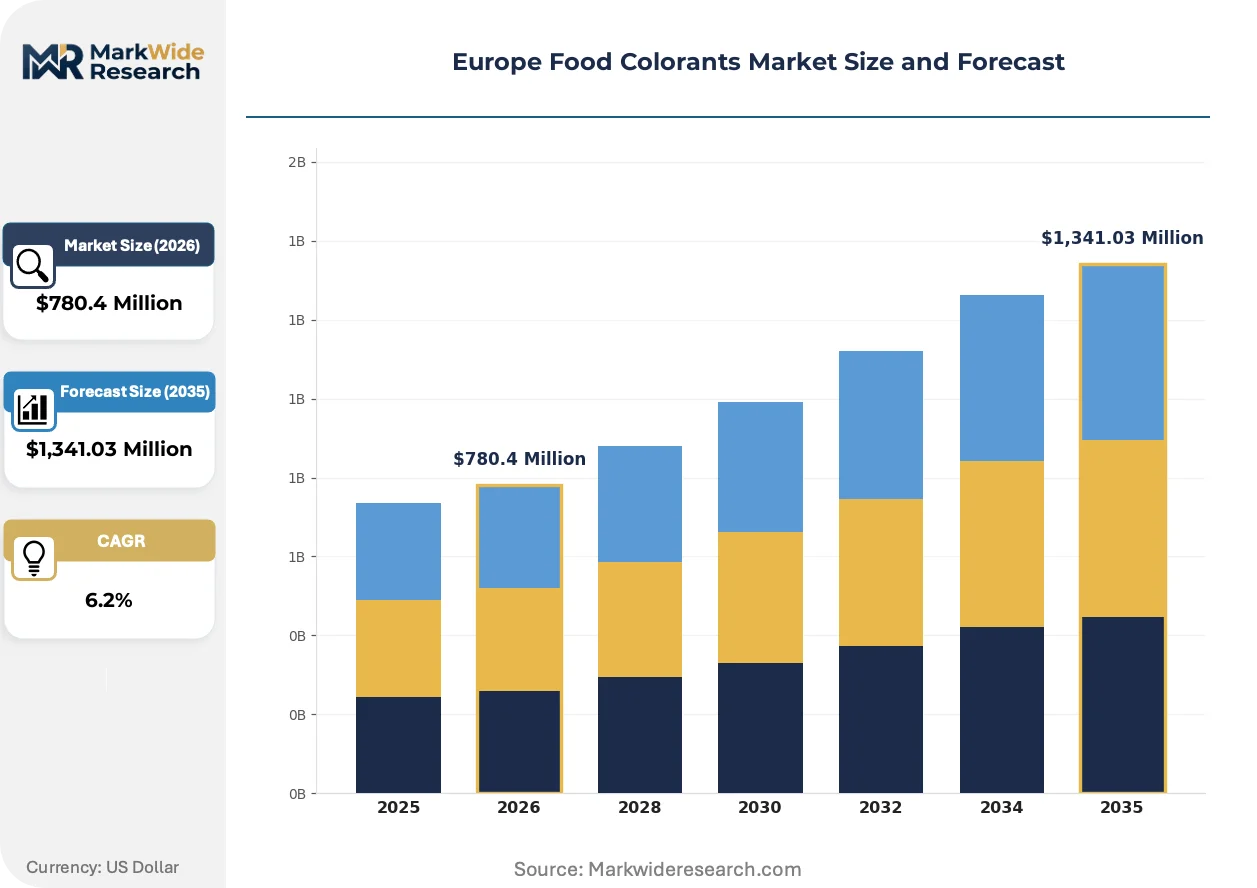
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,341.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Caramel Color, Anthocyanins Application: Beverages, Bakery Products, Dairy Products, Confectionery Form: Liquid, Powder, Gel, Granules End User: Food Manufacturers, Beverage Producers, Restaurants, Catering Services |
| Companies Covered | Sensient Technologies, D.D. Williamson & Co, Koninklijke DSM N.V., Givaudan, Riken Vitamin, BASF SE, Dohler Group, Oterra A/S, Chr. Hansen A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Colorants Market Shifts & Advancements
Microbiome-conscious formulation is redirecting colorant selection criteria beyond visual performance toward digestive tolerance and clean-label credentialing that satisfies retail audit standards.
Encapsulation technology using modified starch and gum arabic matrices is decomposing the stability-performance tradeoff that previously constrained natural colorant adoption in heat-processed applications. German dairy processors are deploying these systems for UHT beverage lines previously reserved for synthetic alternatives. The technology is decomposing price premiums between natural and synthetic colorant positioning in mid-tier retail channels.
REACH authorization amendments for microplastic-free labeling are compelling confectionery manufacturers to eliminate titanium dioxide and certain lake pigments from coating applications. ECHA's restriction proposals are forcing rapid alternative screening across gummy candy and pressed tablet segments. French and Italian sugar confectionery producers are accelerating beetroot and spirulina-derived whitening agent trials to maintain shelf-appeal without regulatory exposure.
Direct-supplier relationships are displacing traditional distribution intermediaries as large food manufacturers seek traceability documentation for ESG reporting under CSRD. Beverage and dairy sector procurement teams are consolidating supplier panels to reduce audit burden and secure volume commitments. This consolidation is most pronounced in German and Dutch headquarters operations where sustainability scorecards determine vendor eligibility.
Europe Food Colorants Market Segmentation
EFSA's additive re-evaluation cycle is fragmenting procurement patterns across European food manufacturing, with clean-label credentials now determining supplier eligibility in premium retail channels. Segmentation strategy must account for divergent compliance timelines between legacy synthetic portfolios and novel botanical platforms.
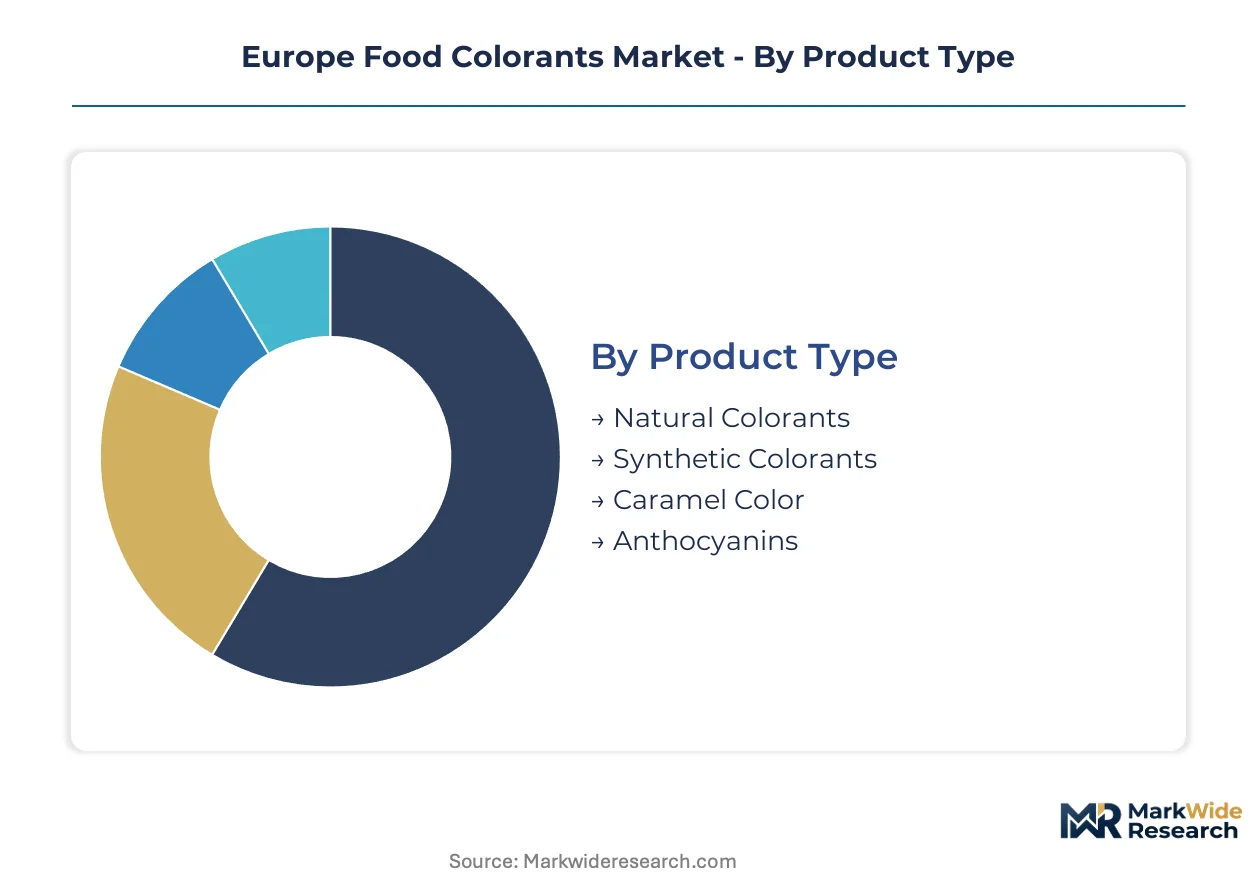
Product Type:
EFSA authorization status separates segments into unrestricted botanical extracts versus restricted or under-review synthetic molecules, reshaping R&D allocation across German, French, and Italian formulation labs.
- Natural Colorants:Anthocyanin, carotenoid, and curcuminoid extracts derived from grape skin, beetroot, and turmeric sources. German beverage manufacturers are expanding procurement volumes to meet retailer clean-label mandates ahead of azo dye phase-out deadlines.
- Synthetic Colorants:Petrochemical-derived azo and pyrazole chromophores including tartrazine and sunset yellow. Northwest European production facilities face stranded asset risk as member-state restrictions tighten ahead of harmonized EU-wide prohibitions.
- Caramel Color:Heat-treated sugar derivatives classified as natural by EFSA guidance.
- Anthocyanins:pH-sensitive polyphenol pigments from berry and vegetable sources with proven stability in acidic beverage matrices.
Established volume favors Synthetic Colorants; emerging adoption favors Natural Colorants.
Application:
Heat-processing requirements and pH conditions dictate colorant selection, with UHT dairy and baked goods demanding encapsulated natural alternatives previously reserved for synthetic stability.
- Beverages:Acidic liquid matrices favor anthocyanin stability while carbonated soft drinks drive carotenoid dispersion technology. French and Italian premium juice brands are mandating E-number-free formulations for retail placement.
- Bakery Products:Thermal degradation during oven exposure requires modified starch encapsulation of beetroot and turmeric extracts. German industrial bakeries are retrofitting dosing equipment for heat-stable natural granules.
- Dairy Products:Neutral pH matrices suit annatto and carotenoid emulsions in fermented and fresh applications.
- Confectionery:Sugar confectionery and chocolate coating segments face REACH microplastic-free labeling pressure on titanium dioxide replacements.
Volume concentration sits with Beverages; margin expansion favors Bakery Products.
Form:
Equipment compatibility and dosing precision determine procurement decisions, with high-throughput operations favoring dust-free handling and artisan producers prioritizing measurement accuracy.
- Liquid:Aqueous or oil-dispersed concentrates enabling precise volumetric dosing in small-batch artisan production. Italian traditional food manufacturers prefer liquid anthocyanin systems for visual intensity control in regional specialty applications.
- Powder:Spray-dried or agglomerated particles for dry-mix integration and extended shelf stability. Dutch ingredient distributors stock powder formats for Central European contract manufacturers serving multiple application types.
- Gel:Viscous suspensions for controlled-release decoration and surface application.
- Granules:Dust-free agglomerates engineered for pneumatic conveying systems in high-speed bakery lines.
Processing efficiency favors Granules; formulation flexibility favors Liquid.
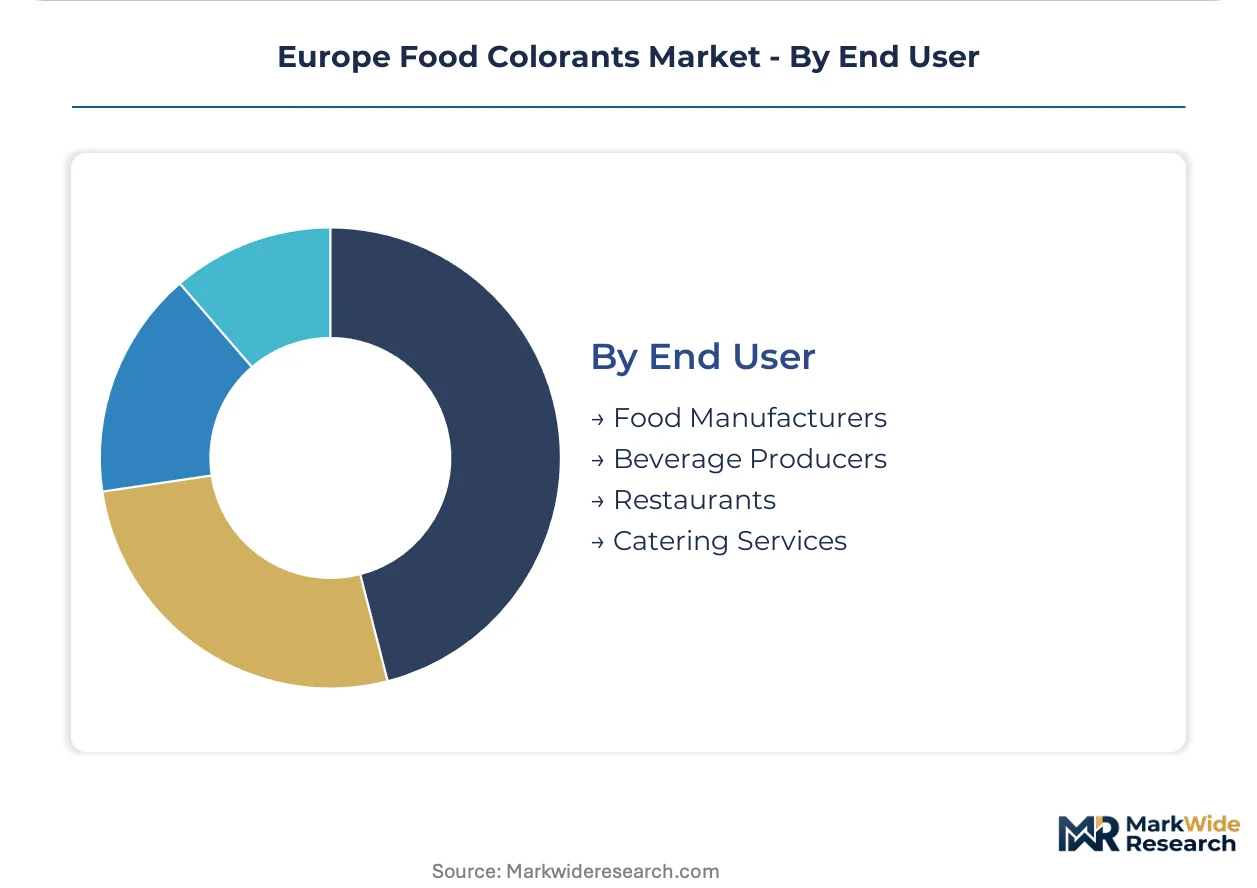
End User:
Traceability documentation requirements under CSRD carbon disclosure rules are consolidating supplier relationships toward direct manufacturer partnerships and away from distribution intermediaries.
- Food Manufacturers:Industrial processors of packaged retail goods requiring batch-to-batch consistency and EFSA compliance documentation. German headquarters operations are implementing sustainability scorecards that disqualify vendors lacking verified lifecycle credentials.
- Beverage Producers:Bottled water, juice, and soft drink specialists demanding acid-stable colorant performance. French mineral water and fruit juice multinationals are auditing botanical extraction supply chains for pesticide residue and carbon footprint verification.
- Restaurants:Foodservice operators seeking visual presentation enhancement for plated dishes and menu photography.
- Catering Services:Volume food preparation for institutional and event clients with cost-sensitive procurement parameters.
Procurement consolidation favors Food Manufacturers; price sensitivity dominates Catering Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CSRD carbon disclosure mandates are redirecting procurement budgets toward verified-lifecycle colorant platforms across European food manufacturing hubs. EFSA's additive re-evaluation cycle compresses reformulation timelines unevenly across member states.
Germany
Industrial bakery and beverage manufacturers drive anthocyanin and beetroot pigment procurement to meet retailer clean-label mandates. The F-Gas Regulation tightens volatile organic compound handling rules for synthetic pigment facilities in North Rhine-Westphalia. Cologne-Düsseldorf ingredient distribution clusters are consolidating supplier panels to reduce CSRD audit burden.
France
Premium juice brands and mineral water multinationals mandate E-number-free formulations for retail placement. ANSM coordinates with EFSA on nano-scale colorant particle guidance, affecting formulation lab R&D allocation. Paris Basin food manufacturers are retrofitting dosing equipment for heat-stable natural granules in UHT dairy lines.
Italy
Traditional food producers prefer liquid anthocyanin systems for visual intensity control in regional specialty applications. REACH microplastic-free labeling amendments pressure sugar confectionery producers to eliminate titanium dioxide from coating applications. Emilia-Romagna processing hubs attract natural colorant toll production investments for Central European beverage market proximity.
Netherlands
Ingredient distributors stock powder formats for Central European contract manufacturers serving multiple application types. ECHA restriction proposals on certain lake pigments force rapid alternative screening across gummy candy segments. Rotterdam-Antwerp logistics corridors enable carbon-efficient botanical extraction supply chain verification.
Poland
Contract manufacturing hubs attract fermentation-based carotenoid platform investments to serve proximity advantages into German beverage markets. EU Green Deal sustainability disclosure requirements redirect procurement toward agricultural-extraction colorant platforms. Warsaw-Łódź industrial zones are emerging as natural colorant toll production centers for mid-tier retail channels.
Europe Food Colorants Market Competitive Landscape
Player mix skews toward botanical extraction specialists and legacy synthetic producers navigating divergent regulatory timelines. Tiered competitive structure separates clean-label specialists with verified supply chains from petrochemical-derived pigment scale operators. Strategic archetypes include fermentation-based carotenoid platforms, agricultural-extraction natural colorant suppliers, and azo-dye legacy producers managing stranded asset risk. Dominant competitive moves encompass M&A for botanical extraction infrastructure and capacity expansion in Eastern European toll production facilities.
Within the fermentation-platform tier, Chr. Hansen A/S exemplifies batch-to-batch consistency capabilities that agricultural extraction cannot match. Among diversified ingredient conglomerates, BASF SE and Koninklijke DSM N.V. occupy positions spanning synthetic legacy portfolios and natural alternative development. Sensient Technologies anchors the botanical extraction specialist archetype with supply relationships for premium beverage clients. These three entities represent the competitive spectrum from petrochemical scale to fermentation precision to agricultural sourcing.
| Leading Market Players |
|---|
| Sensient Technologies |
| D.D. Williamson & Co |
| Koninklijke DSM N.V. |
| Givaudan |
| Riken Vitamin |
| BASF SE |
| Dohler Group |
| Oterra A/S |
| Chr. Hansen A/S |
| Others |
Supply & Pricing Matrix
Anthocyanin substitution for sunset yellow and tartrazine is redrawing procurement geography toward Southern European grape-skin and beetroot extraction zones while compressing margin structures for petrochemical-derived pigment producers facing F-Gas Regulation compliance costs.
Pricing Analysis
Certification level (EFSA-approved versus novel food additive status) creates the primary spread between natural colorant tiers. Three-tier pricing structure separates premium fermentation-derived carotenoids from standard agricultural-extraction anthocyanins and economy-grade caramel colorants. Cost compression in synthetic azo dyes is intensifying because stranded asset risk at Northwest European petrochemical facilities forces discounting to maintain offtake. Food manufacturers with CSRD-mandated sustainability scorecards demonstrate lowest price sensitivity; catering services and private-label confectionery producers exhibit highest elasticity.
Supply Chain Analysis
Rotterdam-Antwerp logistics corridors serve as the critical chokepoint for botanical extraction feedstock flows from Southern European growing regions into Central European processing hubs. Agricultural supply concentrates in Italy, Spain, and France for grape-skin and beetroot raw materials; fermentation capacity clusters in Denmark and the Netherlands for precision-derived carotenoids. Supply chain risk hinges on seasonal harvest volatility across Mediterranean growing belts that feeds from climate-exposed agricultural cycles. Distribution runs through ingredient distributor consolidation toward direct-manufacturer relationships as traceability documentation requirements harden under CSRD carbon disclosure mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's additive re-evaluation cycle is transforming colorant procurement into a platform-economics inflection where fermentation-based consistency protocols interoperate with agricultural-extraction supply chains through encapsulation technology standards.
For Market Incumbents: Compound defensive positioning by acquiring botanical extraction infrastructure in Emilia-Romagna and Warsaw-Łódź industrial zones to preempt toll production consolidation. Accelerate REACH-registered bio-based alternative pipelines ahead of synthetic dye phase-out deadlines. Vertical integration into fermentation-based carotenoid platforms neutralizes agricultural yield volatility that threatens margin predictability. For New Entrants and Emerging Players: EFSA novel food additive fast-track authorization creates entry pathways for precision fermentation specialists targeting infant nutrition and clinical food applications with batch-to-batch consistency guarantees. Polish and Romanian contract manufacturing white space offers lowest competitive density for natural colorant toll production serving German beverage markets. Direct-supplier relationship cultivation with sustainability scorecard-driven procurement teams bypasses traditional distribution intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed botanical extraction specialists holding Southern European agricultural supply contracts and EFSA-approved status. Five-to-ten-year viability favors fermentation-platform scale operators with intellectual property moats around carotenoid molecule production. The signal to watch is EFSA's pending titanium dioxide opinion, which would force rapid portfolio restructuring across confectionery supply chains and revalue whitening-agent alternative developers.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Scale-Up | Precision carotenoid production bypasses agricultural supply volatility that compresses natural colorant margins. |
| Botanical Extraction Infrastructure Acquisition | Southern European grape-skin and beetroot supply contracts secure preferred supplier status with EFSA-compliant documentation. |
| Encapsulation Technology Partnership | Modified starch matrix systems decompose stability-performance tradeoffs in UHT dairy and bakery heat processing. |
| Direct-Manufacturer Relationship Consolidation | CSRD traceability requirements displace distribution intermediaries and reduce audit burden for procurement teams. |
| REACH-Registered Bio-Based Alternative Development | Early novel plant-derived chromophore registrants secure multinational food manufacturer partnerships ahead of synthetic phase-outs. |
Research Methodology
Desk research of EFSA additive authorization databases, REACH registration filings, and EU Green Deal policy documentation preceded structured interviews with food manufacturer procurement directors, botanical extraction plant managers, fermentation platform R&D leads, and ingredient distribution channel heads. Primary fieldwork combined with secondary validation from customs trade data, Cefic chemical industry reports, and SEC filings of diversified ingredient conglomerates. Bottom-up volume modeling across application segments triangulated against top-down market sizing from production capacity assessments.
Variance decomposition across the projection horizon isolates pricing dynamics by certification tier, raw material input type, and geographic production hub. Segmentation dimensions modeled include product type (natural versus synthetic versus caramel), application (beverage, bakery, dairy, confectionery), form factor (liquid, powder, granule), and end-user procurement consolidation level. CAGRs derive from segment-level volume trajectories weighted by EFSA authorization timelines and member-state regulatory phase-out schedules. Forecast inputs incorporate F-Gas Regulation compliance cost assumptions and CSRD carbon disclosure implementation pace.
Decision-makers should treat outputs as directional under base assumptions of continued EFSA re-evaluation stringency and EU Green Deal sustainability mandate enforcement; material deviation in regulatory timelines or agricultural yield patterns would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA pending opinions on titanium dioxide and azo dyes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Japan Anti-Caking Market