
 NFC JUICE Market | 2026-2036
NFC JUICE Market Size, Share, and Industry Trends Forecast 2026-2036
NFC JUICE Market Intelligence
Specialized citrus agronomists and cold-chain engineers is reorganizing where NFC juice production concentrates, shifting capacity toward orchards with integrated pasteurization and aseptic filling. Döhler Group leverages backward integration into fruit breeding and orchard management to secure consistent Brix profiles across harvest cycles. PepsiCo Inc competes through direct-to-retailer volume contracts that anchor shelf space in North American and European grocery channels. Florida's Natural Growers differentiates by controlling cooperative member groves, sustaining traceability claims that command premium positioning.
Not-from-concentrate juice retains natural volatile aromatic compounds through single-strength extraction followed by gentle pasteurization at temperatures below 95°C, preserving enzymatic activity and native vitamin C levels for beverage and ingredient applications. Pure NFC Juice dominates value pools due to clean-label positioning and minimal processing narratives that justify price premiums in health food channels. Blended NFC Juice occupies the fastest-expanding segment as manufacturers fuse apple, pear, and tropical bases to balance acidity, sugar content, and year-round supply reliability.
FDA juice HACCP regulations and EU Organic certification frameworks mandate pathogen control and synthetic input prohibitions that reshape orchard management and processing investments. BIS standards in India and FSSAI labeling requirements add compliance layers for exporters targeting emerging middle-class consumers. Stakeholders must monitor how climate volatility affects harvest timing, Brix consistency, and the geographic viability of long-established citrus belts.
Market Dynamics
Cold-chain logistics expertise is reorganizing where NFC juice production concentrates, shifting capacity toward orchards with integrated pasteurization and aseptic filling capabilities that preserve volatile aromatic compounds.
Growth Catalysts
- FDA Juice HACCP Regulations:Mandatory pathogen control protocols are elevating processing standards across US facilities, creating competitive moats for compliant operators.
- EU Organic Certification:Synthetic input prohibitions are tightening raw material sourcing protocols and commanding premium shelf positioning in European retail channels.
- Private-Label Expansion:German and Brazilian retailers are anchoring volume through direct-to-retailer contracts that secure dedicated production lines.
Market Restraints
- Input Cost Volatility:Florida citrus greening disease and Brazilian frost cycles are compressing orange supply reliability and amplifying Brix inconsistency.
- Supply Concentration Risk:Premium apple varietal production clusters in Washington State and Polish orchards, creating geographic vulnerability to climate volatility.
- Substitution Threat:High-pressure processing (HPP) juices and refrigerated concentrates are capturing price-sensitive consumers in mass-market channels.
Strategic Opportunities
- Underpenetrated Markets:India's FSSAI labeling requirements are creating first-mover advantages for EU-certified exporters targeting emerging middle-class consumers.
- Technology Convergence:Aseptic filling systems combined with blockchain traceability are enabling real-time harvest-to-retail verification for cooperative grove networks.
- Channel Innovation:Subscription direct-to-consumer models are bypassing traditional grocery slotting fees and capturing lifetime value in urban households.
Industry Challenges
- Certification Timeline Compression:EU Organic and BIS standard synchronization is extending approval cycles for multi-destination exporters.
- Capex Intensity:Integrated pasteurization and cold-chain infrastructure requires substantial upfront investment that strains mid-scale processors.
- Talent Scarcity:Specialized citrus agronomists and cold-chain engineers command premiums that outpace operational budget growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NFC JUICE Market |
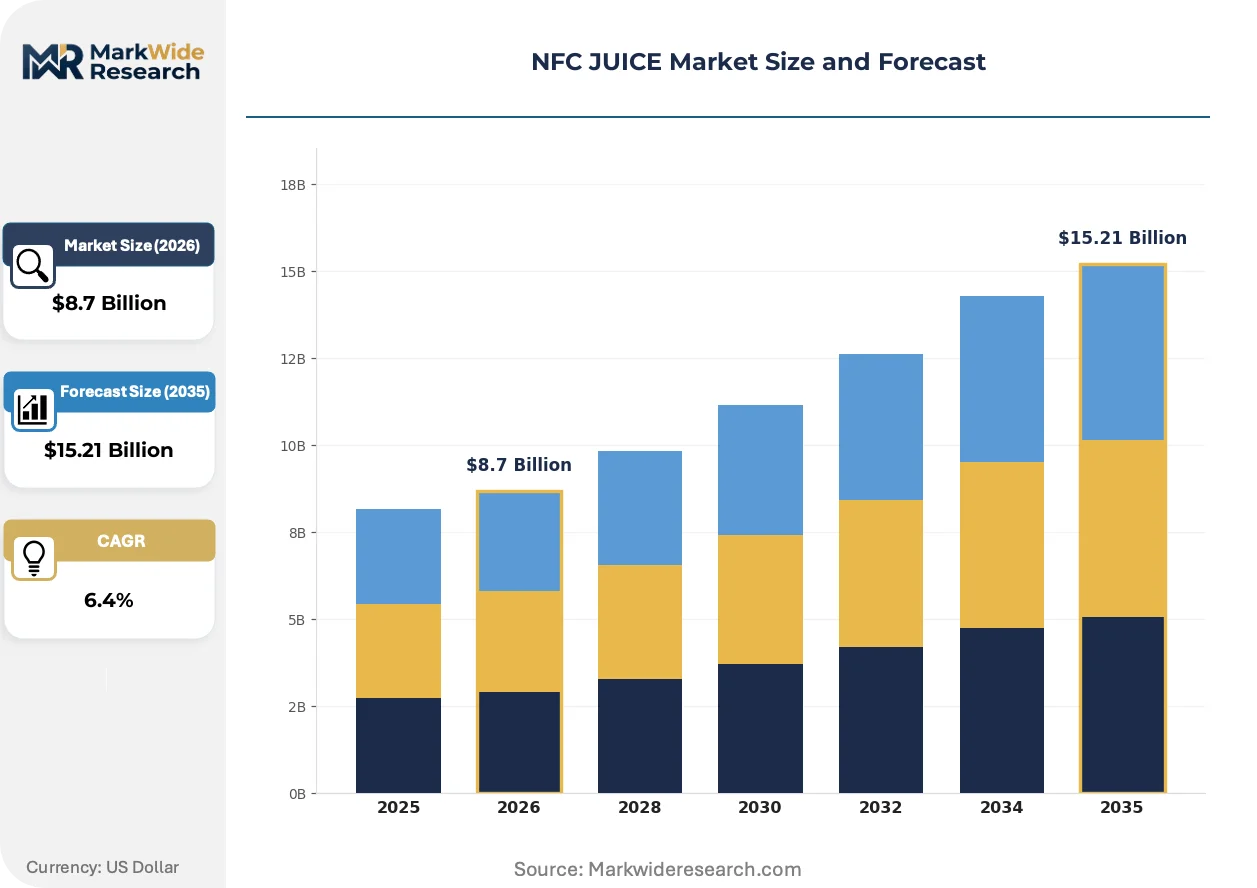
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure NFC Juice, Blended NFC Juice, Concentrated NFC Juice, Fused NFC Juice Flavor Profile: Citrus, Berry, Tropical, Stone Fruit Packaging Type: Glass Bottles, PET Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores |
| Companies Covered | Döhler Group, SVZ International B.V., The Coca-Cola Company, PepsiCo Inc, Eckes-Granini Group, Tropicana Products Inc., Florida’s Natural Growers, Austria Juice, Citrosuco S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NFC JUICE Market Strategic Shifts & Innovations
Processing technology and certification frameworks are actively compressing the gap between harvest volatility and retail consistency, reshaping how NFC juice manufacturers secure supply and justify price positioning.
High-pressure processing (HPP) technology is decomposing the traditional thermal pasteurization monopoly in premium juice segments. Cold-pressed juice bars and specialty retailers in California and New York are adopting HPP at accelerating rates. This shift is decomposing the historical advantage of large-scale aseptic facilities, enabling smaller regional processors to compete on sensory quality metrics previously reserved for industrial operators.
EU Green Deal agricultural targets are mandating synthetic pesticide reduction timelines that cascade into orchard management practices. Fruit breeding programs must now prioritize disease resistance alongside Brix profiles and yield stability. German and Dutch retailers are responding by tightening supplier qualification windows and demanding third-party carbon footprint verification.
Clean-label procurement is compressing ingredient disclosure expectations from finished product to raw material origin. Foodservice operators and institutional buyers in Nordic markets are replacing quarterly bidding with multi-year grove partnerships. This behavioral pivot is most visible in Sweden and Denmark, where municipal procurement guidelines now prioritize single-origin traceability over lowest-unit-cost sourcing.
NFC JUICE Market Segmentation
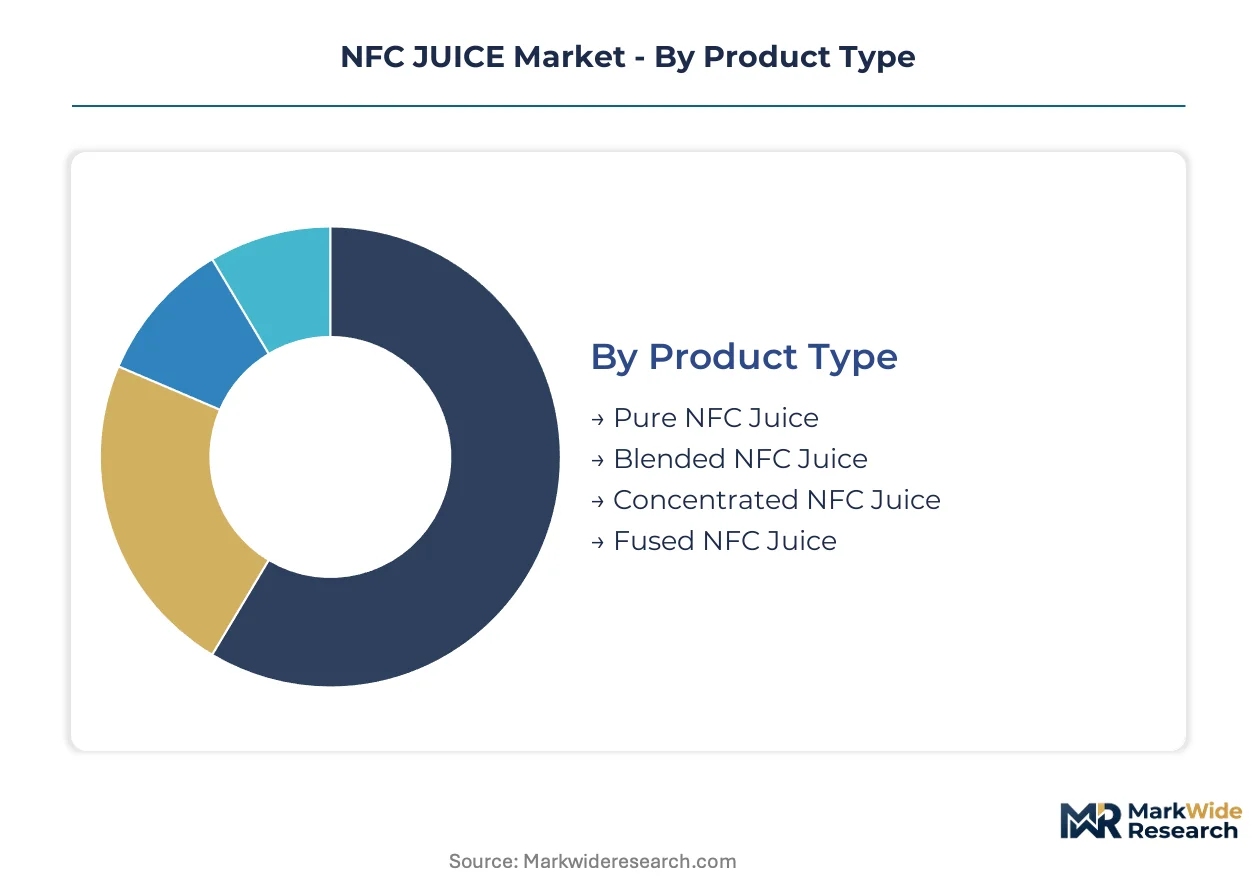
NFC juice manufacturers segment production to align pasteurization intensity with shelf-life requirements and to match packaging formats with channel-specific cold-chain capabilities. Category boundaries shift as retailers consolidate private-label sourcing and aseptic filling technology penetrates mid-scale processors.
Product Type:
Pure NFC Juice anchors domestic consumption in Germany and Florida where clean-label positioning commands premium shelf placement, while Blended NFC Juice concentrates export demand from Brazilian processors seeking year-round supply stability through multi-fruit formulations.
- Pure NFC Juice:Single-strength extraction from single-fruit cultivars preserves native enzymatic activity and volatile aromatic compounds below 95°C pasteurization. German health food retailers and Florida cooperative networks concentrate procurement here, leveraging minimal processing narratives to justify price premiums in HACCP-compliant channels.
- Blended NFC Juice:Fusion of apple, pear, and tropical bases balances acidity, sugar content, and harvest timing to ensure continuous production. Brazilian exporters and Polish apple processors dominate this segment, responding to EU retailer demand for consistent Brix profiles across seasonal gaps.
- Concentrated NFC Juice:Reduced water content through vacuum evaporation prior to reconstitution, favored by foodservice operators in India targeting BIS-compliant institutional buyers.
- Fused NFC Juice:Combination of NFC bases with functional additives such as probiotics or botanical extracts, emerging in California specialty channels and Nordic subscription services.
Pure NFC Juice holds the largest share; momentum sits with Blended NFC Juice.
Flavor Profile:
Cost tier differentiation separates commodity citrus from premium stone fruit, with berry and tropical occupying mid-tier positioning in retailer private-label hierarchies.
- Citrus:Orange and grapefruit varietals dominate volume through Florida and São Paulo orchard networks, though greening disease and frost cycles compress supply reliability. FDA juice HACCP regulations elevate processing standards for pathogen control in US facilities.
- Berry:Cranberry, blueberry, and raspberry bases command premium positioning in Nordic markets and California cold-pressed channels, with EU Organic certification tightening synthetic input prohibitions.
- Tropical:Mango, pineapple, and passionfruit sourcing concentrates in Brazilian northeast and Indian Maharashtra, serving export demand from German retailers expanding private-label programs.
- Stone Fruit:Peach and apricot NFC retains limited commercial scale due to harvest compression and enzymatic browning challenges, with small-batch production in California Central Valley and Italian Emilia-Romagna.
Citrus dominates volume; berry climbs the fastest on premium positioning.
Packaging Type:
Application-driven selection separates ambient-stable formats for mass retail from refrigerated premium packaging in direct-to-consumer channels.
- Glass Bottles:Premium positioning in urban health food stores and Nordic municipal procurement, with carbon footprint verification increasingly mandated by Dutch and German retailers.
- PET Bottles:Lightweight, shatter-resistant format dominating US supermarket and convenience store channels, compatible with existing cold-chain infrastructure.
- Tetra Packs:Aseptic filling technology enables ambient distribution in Indian and Brazilian emerging middle-class markets, reducing refrigeration burden.
- Pouches:Flexible format gaining share in subscription direct-to-consumer models and children's lunchbox segments across California and New York metro areas.
Tetra Packs hold the largest share; pouches gain share fastest on channel innovation.
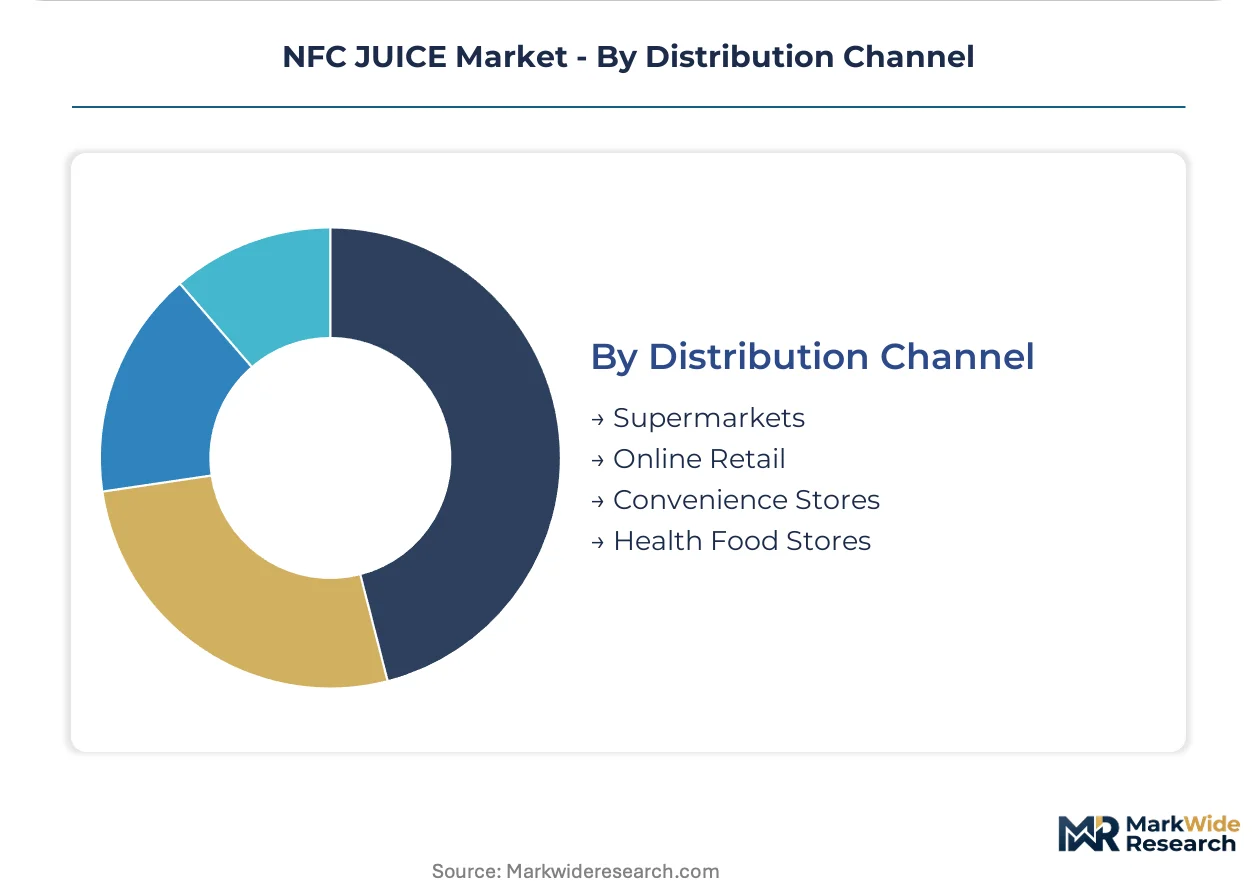
Distribution Channel:
Customer type fragmentation separates institutional volume from household premium procurement, with online retail bridging geographic access gaps.
- Supermarkets:Slotting fee negotiations anchor volume for PepsiCo and Döhler Group through direct-to-retailer contracts in North American and European grocery channels.
- Online Retail:Subscription models bypass traditional slotting fees, capturing lifetime value in urban households across California, New York, and London.
- Convenience Stores:Impulse purchase format in Japanese and South Korean urban corridors, requiring extended shelf-life through aseptic processing.
- Health Food Stores:Clean-label procurement concentrates here, with Swedish and Danish municipal guidelines prioritizing single-origin traceability over lowest-unit-cost sourcing.
Supermarkets retain the largest share; online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers prioritize clean-label procurement with single-origin traceability, while Brazilian processors emphasize year-round supply stability through multi-fruit blending. Indian institutional buyers favor BIS-compliant concentrated formats, and Florida cooperative networks anchor premium pure NFC positioning.
United States
FDA juice HACCP regulations elevate pathogen control standards across processing facilities. Florida citrus groves and California Central Valley orchards concentrate production capacity for domestic retail and foodservice channels. Cold-pressed juice bars in New York and Los Angeles accelerate HPP technology adoption.
Germany
EU Organic certification mandates synthetic input prohibitions that reshape supplier qualification windows. Retailers in Hamburg and Munich tighten carbon footprint verification requirements for private-label programs. Döhler Group leverages backward integration into fruit breeding to secure consistent Brix profiles.
Brazil
São Paulo orchard networks and northeast tropical sourcing regions balance harvest timing for export reliability. ANVISA alignment with international standards facilitates EU-bound shipments. Citrosuco S.A. anchors volume production for European retailer contracts.
India
FSSAI labeling requirements create compliance layers for EU-certified exporters targeting emerging middle-class consumers. Maharashtra mango and pineapple processors concentrate in Pune-Nashik corridor. BIS standards elevate institutional procurement protocols for foodservice operators.
Sweden
Municipal procurement guidelines prioritize single-origin traceability over lowest-unit-cost sourcing in Nordic markets. Stockholm and Copenhagen health food retailers concentrate clean-label demand. EU Green Deal agricultural targets cascade into orchard management practice mandates.
NFC JUICE Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the NFC juice market. Tier-one players control cooperative grove networks and captive breeding programs that secure raw material consistency. Mid-scale processors compete through regional cold-chain partnerships and private-label manufacturing agreements. Dominant competitive moves include backward integration into orchard management and direct-to-retailer volume contracts that anchor shelf space.
Within the integrated processing tier, Döhler Group and Citrosuco S.A. exemplify upstream control strategies through captive supply of fruit breeding and orchard operations. PepsiCo Inc occupies a position on the scale-driven end, representing volume-contract archetypes that secure dedicated production lines across North American and European grocery channels. Specialists in cooperative grove networks include Florida's Natural Growers, which anchors traceability-focused positioning through member-controlled citrus operations.
| Leading Market Players |
|---|
| Döhler Group |
| SVZ International B.V. |
| The Coca-Cola Company |
| PepsiCo Inc |
| Eckes-Granini Group |
| Tropicana Products Inc. |
| Florida's Natural Growers |
| Austria Juice |
| Citrosuco S.A. |
| Others |
Cost & Logistics Intelligence
HPP technology substitution for thermal pasteurization is simultaneously fragmenting supply geography toward regional cold-press processors and compressing pricing power at legacy aseptic facilities. This displacement forces traditional operators to absorb capex write-downs or pivot toward blended formulations where scale economies still defend margins.
Pricing Analysis
Long-term offtake contracts with German and Brazilian retailers anchor volume pricing for integrated processors, while spot procurement governs distressed citrus sales from Florida groves hit by greening disease. Three-tier pricing structure across premium organic, standard HACCP-compliant, and economy private-label levels separates EU-certified supply from conventional commodity juice. Pricing pressure stems from Brazilian frost cycles and Florida supply compression, which amplify Brix inconsistency and force discounting to maintain shelf presence. Foodservice operators in India show highest price sensitivity due to BIS compliance costs, while Nordic municipal buyers prioritize traceability premiums over unit economics.
Supply Chain Analysis
Inventory lead times stretch across harvest-to-retail cycles exceeding twelve months for single-origin pure NFC, forcing processors to carry working capital through seasonal gaps. Raw material supply concentrates in Brazil, Florida, and Washington State for oranges, and Poland for premium apple varietals, creating geographic vulnerability to climate volatility. The chain rests on aseptic filling equipment, cold-chain logistics partnerships, and EU Organic certification timelines as critical inputs. Single-source vulnerability runs through São Paulo orchard networks exposed to frost and disease. Distribution runs through direct-to-retailer contracts with supermarket chains and emerging subscription channels bypassing traditional slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription direct-to-consumer models represent a service-attach opportunity expanding faster than base product volume, capturing lifetime value through recurring replenishment and personalized flavor profiling.
For Market Incumbents: Shield cooperative grove networks from HPP displacement by deepening captive breeding programs that secure consistent Brix profiles across climate volatility. Anchor shelf space through multi-year direct-to-retailer contracts with German and Brazilian retailers that lock out regional cold-press entrants. Prioritize EU Organic certification investment as a defensive moat against synthetic-input-tightening Green Deal targets.
For New Entrants and Emerging Players: EU Organic certification fast-track through Dutch and German retailer qualification windows opens white-space in Nordic municipal procurement, where single-origin traceability commands premium positioning. Target India's emerging middle-class through FSSAI-compliant concentrated formats for institutional foodservice, leveraging lower cold-chain infrastructure requirements. Deploy blockchain traceability as a go-to-market differentiator for health food channel penetration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated processors with backward integration into orchard management and captive fruit breeding capabilities. Long-term viability hinges on climate-adaptive varietal development and cold-chain infrastructure ownership rather than commodity trading positions. Watch ANVISA-EU regulatory alignment as the inflection signal for Brazilian export volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Management | Döhler Group's captive breeding programs secure Brix consistency across harvest cycles. |
| Direct-to-Retailer Volume Contracts | PepsiCo anchors dedicated production lines through supermarket slotting fee negotiations. |
| EU Organic Certification Investment | Florida's Natural Growers commands premium positioning through traceability-compliant cooperative networks. |
| Aseptic Filling Technology Deployment | Citrosuco S.A. enables ambient distribution to Indian and Brazilian emerging middle-class markets. |
| Subscription Channel Launch | California and New York metro operators bypass grocery slotting fees through direct-to-consumer models. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA juice HACCP guidance documents, EU Organic certification frameworks, FSSAI labeling requirements, and customs trade data for citrus and apple concentrate flows. Primary interviews engaged citrus agronomists, cold-chain logistics directors, retailer category buyers, cooperative grove managers, and aseptic processing engineers. Secondary validation drew from ANVISA regulatory filings, BIS standard publications, SEC 10-K disclosures from integrated beverage processors, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Segmentation dimensions modeled include product type (pure, blended, concentrated, fused), flavor profile (citrus, berry, tropical, stone fruit), packaging format (glass, PET, Tetra Pack, pouch), and distribution channel (supermarket, online retail, convenience store, health food store). CAGRs were derived from historical trajectory analysis and forward projection of regulatory compliance timelines, climate volatility patterns, and channel shift velocities. Forecast inputs incorporated harvest timing compression, Brix consistency variance, and cold-chain infrastructure penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU Organic certification demand, stable ANVISA-EU regulatory alignment, and manageable Florida citrus greening progression; material deviation in climate patterns or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Baby Drinks Market
Beverages
Smoothies Market
Beverages
Spring Water Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Carbonated Soft Drinks Market
Beverages
Growlers Market
Beverages
Sparkling Water Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
India Soy Beverages Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Collagen-Infused Water Market
Beverages
Beverages Market
Beverages
United States Smoothie Market
Beverages
South America Mate Market
Beverages
Hydrogen Water Bottle Market