
 Health Drinks Market | 2026-2036
Health Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Health Drinks Market Analysis
Organic certification under USDA NOP and EU Regulation 2018/848 is bifurcating the competitive landscape into credentialed and conventional suppliers. Danone S.A. leverages its European dairy heritage to dominate probiotic drink categories. PepsiCo, Inc. anchors its portfolio through Gatorade's electrolyte science and extensive convenience store distribution. Red Bull GmbH differentiates via energy-drink pharmacology and extreme sports sponsorship lockups.
Health drinks comprise formulated beverages delivering targeted physiological benefits through bioactive compounds, probiotics, proteins, vitamins, or botanical extracts, typically manufactured via aseptic processing or cold-fill technologies to preserve functional integrity. Functional beverages command the widest margin pools as consumers pay premiums for adaptogenic and nootropic formulations. Protein shakes sustain volume leadership among athletes and fitness enthusiasts. Online retail channels are capturing the fastest growth trajectory as direct-to-consumer subscription models reshape replenishment behavior.
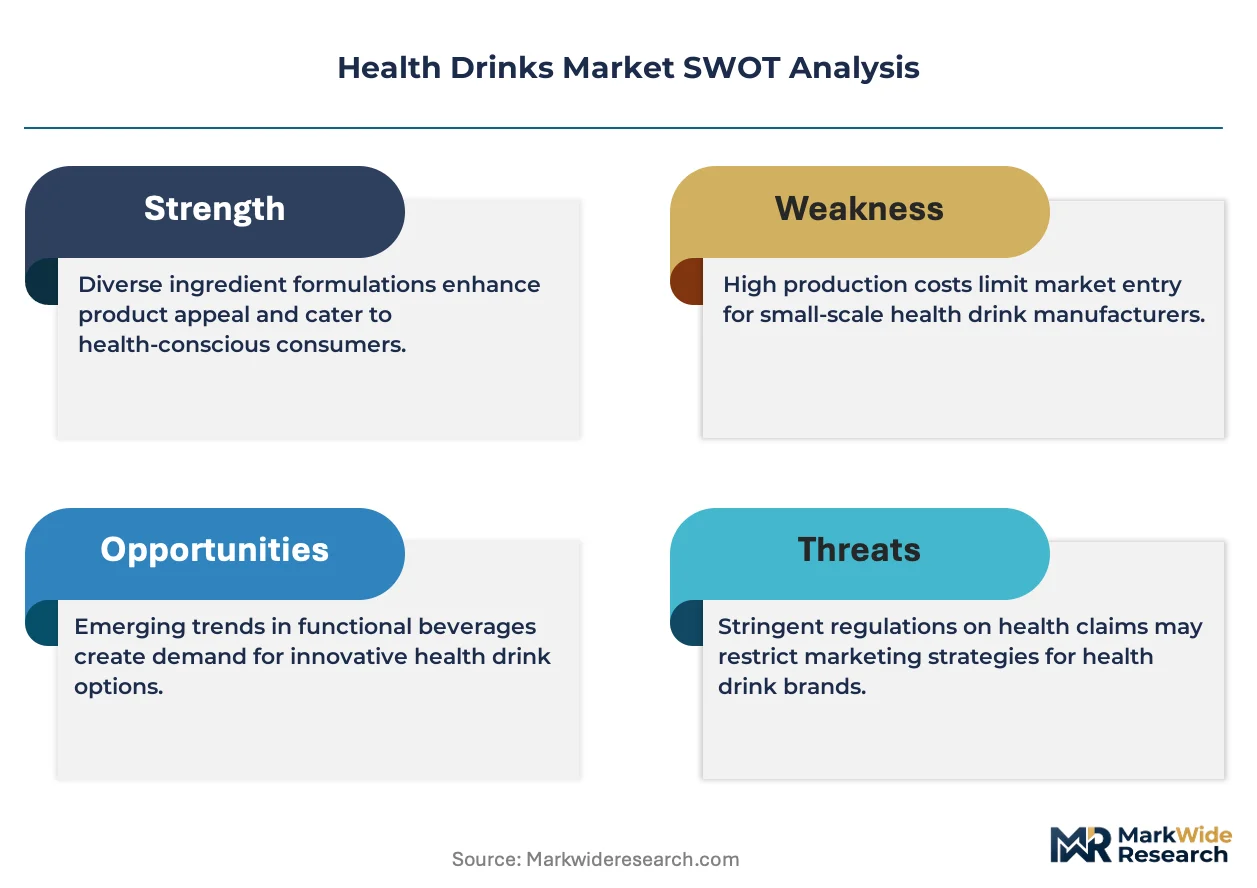
FDA nutrition labeling rules and the EU's Nutrition and Health Claims Regulation constrain permissible marketing language, forcing reformulation toward clinically substantiated ingredient doses. China's SAMR and NMPA jointly oversee functional food registration, creating a dual-approval bottleneck for entrants targeting the country's massive wellness consumer base. Stakeholders must monitor evolving probiotic strain approval lists and sugar-tax thresholds across multiple jurisdictions to anticipate portfolio repositioning requirements.
Market Dynamics
Protein fortification mandates and clean-label certification requirements are bifurcating supplier capabilities, forcing capital reallocation toward aseptic processing infrastructure and strain-specific probiotic documentation.
Growth Catalysts
- EU Farm to Fork Strategy:The additive disclosure tightening creates first-mover advantages for suppliers with pre-validated ingredient transparency systems.
- Fitness enthusiast demand concentration:Athletes and gym operators are pulling functional beverages into institutional procurement channels, expanding volume commitments.
- Cold-fill aseptic processing:This technology preserves bioactive integrity in probiotic formulations, unlocking premium shelf-stable distribution.
Market Restraints
- Dual-approval bottlenecks:China's SAMR and NMPA joint oversight extends functional food registration timelines, freezing capital in regulatory limbo.
- Sugar-tax threshold volatility:Multiple jurisdictions are adjusting levy bands unpredictably, forcing reactive reformulation cycles.
- Probiotic strain approval list fragmentation:Divergent national strain catalogs prevent standardized global formulations.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channels are capturing replenishment behavior, disintermediating traditional grocery slotting.
- Adaptogenic ingredient convergence:Ashwagandha and lion's mane combinations are opening nootropic positioning white space.
- USDA NOP organic certification tailwinds:Premium credentialed positioning commands sustained margin pools as conventional suppliers face exclusion.
Industry Challenges
- Clinical substantiation skill scarcity:Formulation teams lack expertise in designing trials that satisfy FDA and EFSA health claim standards simultaneously.
- Aseptic line capex intensity:Cold-fill equipment requires specialized infrastructure that mid-tier bottlers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Drinks Market |
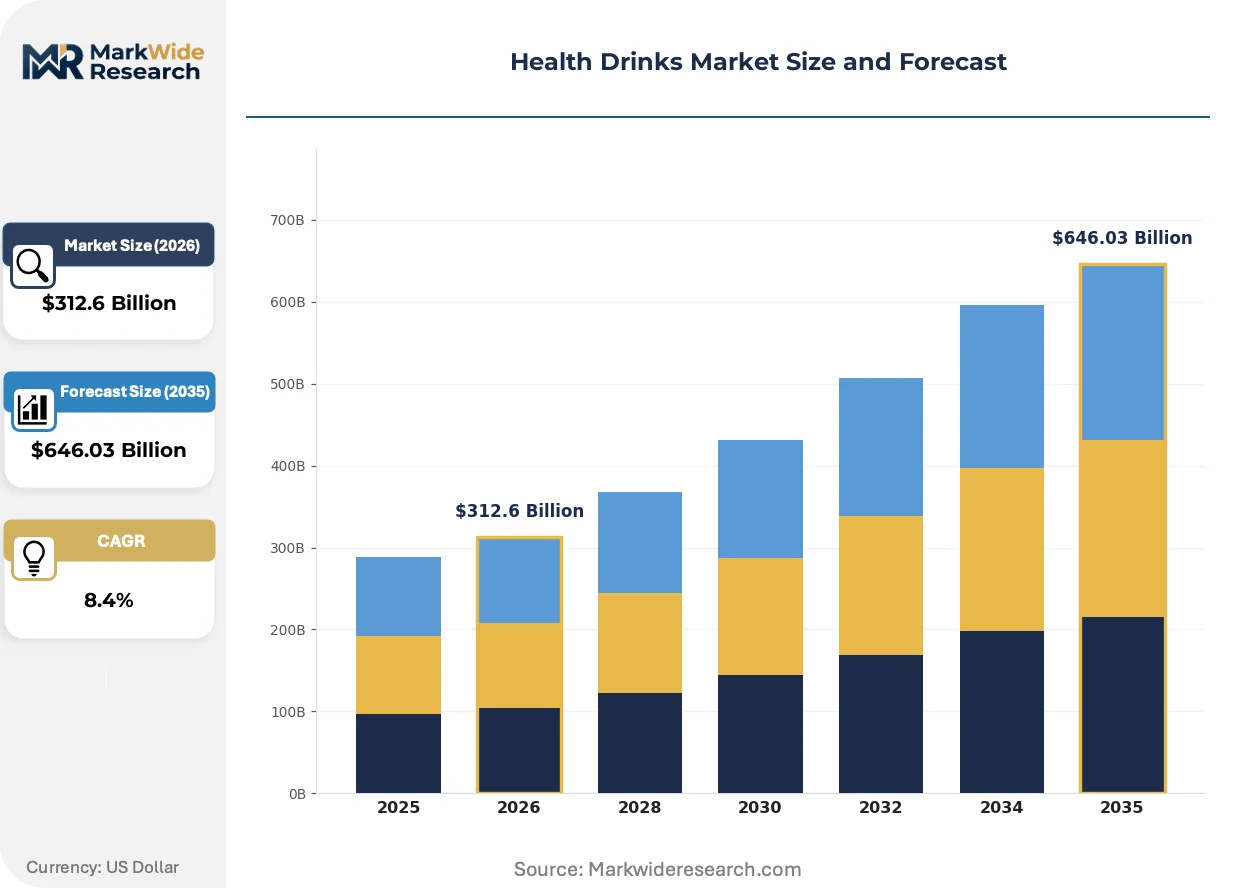
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Shakes, Meal Replacement Drinks, Functional Beverages, Herbal Infusions End User: Athletes, Fitness Enthusiasts, Busy Professionals, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Packaging Type: Bottles, Pouches, Tetra Packs, Cans |
| Companies Covered | Danone S.A., Monster Beverage Corp., PepsiCo, Inc., Glanbia Plc, Keurig Dr Pepper Inc., The Coca-Cola Company, Red Bull GmbH, Oatly Group, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Drinks Market Emerging Trajectories
Formulation science and distribution architecture are undergoing simultaneous transformation. Three distinct vectors are compressing legacy operating models and opening new competitive terrain.
Precision fermentation-derived proteins are displacing conventional whey and soy isolates in premium formulations. Sports nutrition buyers are adopting these ingredients at accelerating rates as taste-profile parity achieves commercial scale. This displacement is compressing commodity protein margins while expanding the addressable market for lactose-free and allergen-reduced positioning.
EFSA's evolving stance on botanical health claims is forcing reformulation toward clinically substantiated doses. The industrial consequence is consolidation of R&D budgets toward strain-specific probiotic trials and adaptogenic compound studies. Functional beverage categories targeting cognitive and stress-modulation benefits face the steepest compliance costs and are responding through partnership with academic research centers.
Replenishment behavior is migrating toward subscription-based direct fulfillment. Traditional convenience store and supermarket slotting arrangements are losing volume share to brand-owned digital channels. China and North America exhibit the most pronounced channel rotation, with fitness enthusiasts leading the behavioral shift through app-integrated auto-replenishment programs.
Health Drinks Market Segmentation
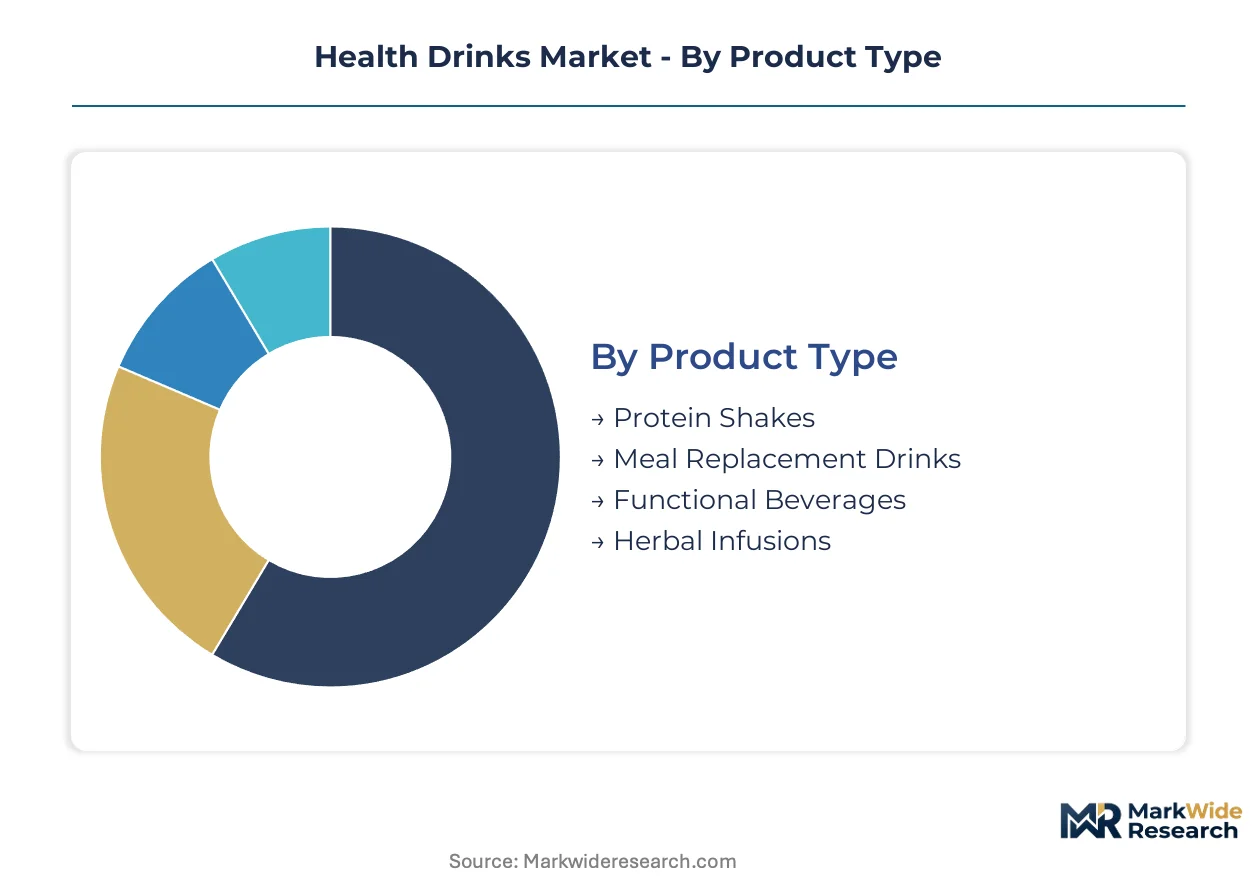
Health drinks segmentation reveals how functional benefits, consumption occasions, and channel economics split margin pools across distinct buyer clusters. Suppliers must align formulation investments with the specific physiological targets and replenishment habits of each segment to capture premium positioning.
Product Type:
Margin pools concentrate in formulations requiring bioactive preservation technology and clinical substantiation documentation.
- Protein Shakes:These formulations deliver concentrated whey, casein, or plant-based isolates for muscle protein synthesis support. Demand concentrates among athletes and gym operators in China as protein fortification shifts from discretionary to essential nutrition. Cold-fill aseptic processing preserves amino acid integrity, justifying premium shelf-stable pricing over refrigerated alternatives.
- Functional Beverages:Adaptogenic and nootropic formulations target stress modulation and cognitive performance through botanical extracts and probiotic strains. Fitness enthusiasts in North America are pulling these into pre-workout and recovery rituals, expanding consumption occasions beyond traditional sports nutrition windows. EFSA's evolving botanical health claim standards force reformulation toward clinically substantiated doses, raising R&D barriers for mid-tier entrants.
- Meal Replacement Drinks:Macro-nutritionally complete formulations substitute for solid food in time-constrained consumption contexts.
- Herbal Infusions:Botanical-based beverages leveraging traditional medicine positioning with functional extraction standardization.
The dominant share belongs to Protein Shakes, while Functional Beverages are gaining share fastest through adaptogenic ingredient convergence.
End User:
Volume distribution tracks closely with institutional procurement channels versus individual replenishment behavior.
- Athletes:Institutional buyers including collegiate programs, professional franchises, and Olympic training facilities specify performance-tested formulations with banned-substance certification. China's SAMR and NMPA dual-approval requirements extend registration timelines for entrants targeting this base through sports federation partnerships.
- Fitness Enthusiasts:Individual consumers with gym memberships and wearable-tracked activity metrics drive subscription-based replenishment through direct-to-consumer channels. App-integrated auto-replenishment programs in North America and China are disintermediating traditional grocery slotting for this cohort.
- Busy Professionals:Time-constrained buyers prioritizing convenience formats and meal-replacement functionality during commuting windows.
- Health-Conscious Consumers:Broad wellness-oriented buyers responding to USDA NOP and EU Regulation 2018/848 organic certification signals.
Athletes anchor volume commitments through institutional procurement, though Fitness Enthusiasts are expanding most quickly via digital channel migration.
Distribution Channel:
Channel economics diverge sharply between high-slotting-fee physical retail and lower-customer-acquisition-cost digital fulfillment.
- Online Retail:Brand-owned websites and marketplace storefronts capture replenishment behavior through subscription mechanics. Direct-to-consumer models bypass supermarket slotting fees and enable first-party data collection for personalization algorithms.
- Supermarkets:Mass-market volume depends on refrigerated case placement and promotional calendar coordination with category managers.
- Health Stores:Specialty retailers including GNC and Vitamin Shoppe assortments credential premium positioning through trained staff recommendation.
- Specialty Shops:Independent retailers and fitness-center pro-shops serving localized athlete communities with curated selection.
Supermarkets retain the dominant share through impulse and fill-in trips, while Online Retail climbs the fastest as subscription mechanics lock in recurring revenue.
Packaging Type:
Format selection trades off shelf stability, portability, and sustainability signaling against per-unit packaging economics.
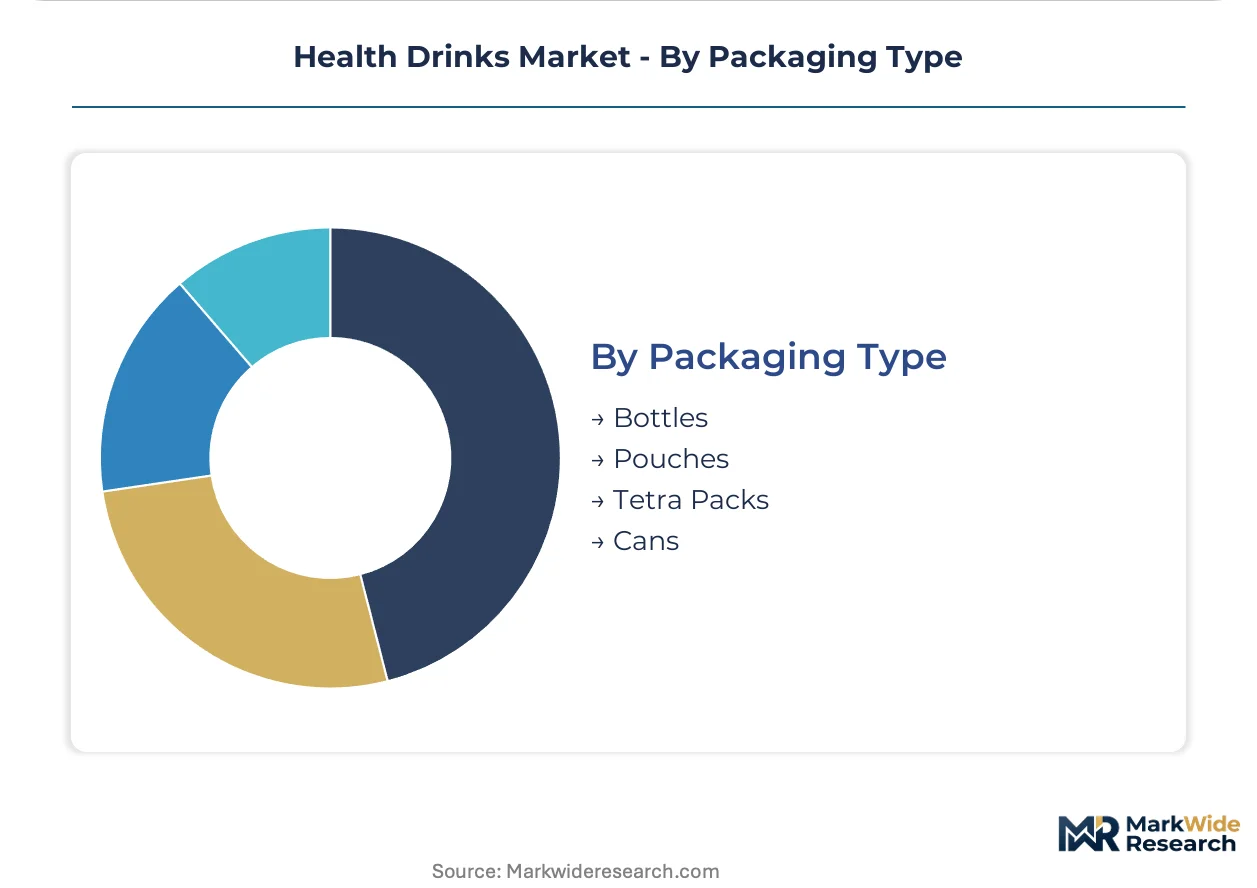
- Bottles:PET and HDPE formats dominate ready-to-drink protein and functional beverages with resealability for multi-occasion consumption. China's manufacturing clusters supply global converters with cost-competitive blow-molding capacity.
- Pouches:Flexible formats reduce shipping cube and material weight for e-commerce-optimized fulfillment. Fitness enthusiasts favor single-serve stick packs for gym bag portability.
- Tetra Packs:Aseptic carton technology enables ambient distribution of sensitive probiotic formulations without refrigeration infrastructure.
- Cans:Aluminum formats support carbonated functional beverages and energy-positioned products with premium tactile differentiation.
Bottles command the dominant share through resealability and format familiarity, while Pouches are expanding most quickly via e-commerce logistics optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts in China anchor volume concentration, while institutional procurement in the United States and Germany drives premium formulation demand. Regulatory divergence across FDA, EFSA, and SAMR jurisdictions creates compliance arbitrage opportunities for credentialed suppliers.
United States
Athletes and collegiate programs pull performance-tested formulations through institutional channels. FDA nutrition labeling rules constrain permissible marketing language, forcing reformulation toward clinically substantiated doses. California's functional beverage clusters concentrate precision fermentation R&D for allergen-reduced protein positioning.
Germany
Probiotic drink demand concentrates among health-conscious consumers seeking clean-label certification. EU Regulation 2018/848 organic standards and EFSA botanical health claim requirements raise entry barriers for conventional suppliers. Bavaria's dairy heritage anchors Danone S.A.'s European probiotic production infrastructure.
China
Fitness enthusiasts drive protein-fortified product adoption through app-integrated subscription channels. SAMR and NMPA dual-approval oversight extends functional food registration timelines, freezing capital for entrants. Yangtze River Delta manufacturing clusters supply global converters with cost-competitive aseptic processing equipment.
Japan
Busy professionals prioritize meal replacement functionality during commuting windows. METI and PMDA oversight of functional food claims maintains stringent substantiation requirements. Kanto region's Tokyo metro corridor concentrates direct-to-consumer brand headquarters and logistics optimization.
Brazil
Health-conscious consumers respond to USDA NOP-equivalent organic certification signals in premium positioning. ANVISA registration requirements for novel ingredients create documentation hurdles for adaptogenic entrants. São Paulo's beverage distribution networks anchor Latin American volume commitments for multinational portfolios.
Health Drinks Market Vendor Landscape
Player mix skews toward diversified beverage conglomerates with dairy heritage and energy-drink pharmacology specialists. Tiered structure separates credentialed organic suppliers from conventional commodity players. Strategic archetypes include European dairy-origin probiotic specialists, electrolyte-science sports nutrition anchors, and extreme sports sponsorship-driven energy brands. Dominant competitive moves encompass direct-to-consumer channel disintermediation and aseptic processing infrastructure expansion.
Among diversified beverage conglomerates, Danone S.A. and PepsiCo, Inc. exemplify scale-driven archetypes with complementary category dominance. Danone S.A. occupies a position within European dairy-origin probiotic positioning, leveraging continental heritage for clean-label credibility. PepsiCo, Inc. anchors the electrolyte-science vector through convenience store distribution density. Red Bull GmbH sits within the energy-drink pharmacology tier, representing sponsorship-lockup differentiation. Glanbia Plc exemplifies the sports nutrition specialist archetype with protein formulation concentration.
| Leading Market Players |
|---|
| Danone S.A. |
| Monster Beverage Corp. |
| PepsiCo, Inc. |
| Glanbia Plc |
| Keurig Dr Pepper Inc. |
| The Coca-Cola Company |
| Red Bull GmbH |
| Oatly Group |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Ninety-day probiotic strain documentation lead times concentrate pricing power with credentialed suppliers possessing pre-validated USDA NOP and EU Regulation 2018/848 certification systems. Cold-fill aseptic processing equipment backlogs extending sixteen months force buyers into cost-plus contracts indexed to dairy protein commodity curves.
Pricing Analysis
Cost-plus contracts with whey isolate indexation dominate procurement between multinational beverage conglomerates and Yangtze River Delta aseptic processors. Three-tier pricing structure across premium organic-certified, standard clean-label, and economy conventional tiers separates margin pools by certification grade and bioactive preservation technology. Pricing pressure stems from precision fermentation-derived proteins achieving taste-profile parity at lower input costs. Institutional buyers including collegiate athletic programs exhibit lowest price sensitivity, while convenience store distributors face acute margin compression from slotting fee escalation.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and Asia-Europe container availability constraints compress working capital cycles for European probiotic ingredient importers. Manufacturing gravity centers on China, Germany, and the United States for aseptic processing infrastructure and precision fermentation R&D. Raw material dependencies include whey and casein isolates, adaptogenic botanical extracts, and strain-specific probiotic cultures. Single-source vulnerability concentrates in Yangtze River Delta cold-fill equipment suppliers. Distribution runs through direct-to-consumer subscription channels disintermediating traditional supermarket slotting arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional beverage formulation represents a high-growth disruption as EFSA botanical health claim substantiation requirements and FDA nutrition labeling rules simultaneously elevate R&D barriers and consolidate margin pools toward clinically validated suppliers.
For Market Incumbents: Consolidate aseptic processing capacity through backward integration into Yangtze River Delta equipment supply chains. Acquire strain-specific probiotic documentation libraries to preempt EU Farm to Fork Strategy additive disclosure mandates. Lock in collegiate athletic program procurement contracts before precision fermentation proteins displace conventional dairy isolates in institutional specifications.
For New Entrants and Emerging Players: Anchor in app-integrated subscription replenishment channels serving North American fitness enthusiasts, the most penetrable buyer cohort exhibiting channel migration behavior. Target adaptogenic nootropic formulations combining ashwagandha and lion's mane where EFSA clinical substantiation requirements have frozen legacy competitor R&D cycles. Deploy direct-to-consumer launch sequences bypassing supermarket slotting fee structures entirely.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because USDA NOP and EU organic standards are bifurcating supplier tiers into sustainable premium-margin and commoditized conventional pools. Acquisition targets should exhibit pre-validated strain documentation libraries and existing aseptic processing infrastructure. Monitor EFSA botanical health claim approval velocity as the critical inflection signal for adaptogenic formulation category expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Infrastructure Expansion | Cold-fill capacity additions in China and Germany capture probiotic preservation premiums. |
| Direct-to-Consumer Channel Launch | Subscription mechanics bypass supermarket slotting fees and enable first-party data collection. |
| Precision Fermentation Partnership | Allergen-reduced protein positioning unlocks lactose-free premium pricing tiers. |
| Organic Certification Investment | USDA NOP and EU Regulation 2018/848 compliance creates sustainable margin separation. |
| Clinical Substantiation Consortium | Academic research center partnerships satisfy EFSA and FDA health claim standards simultaneously. |
Methodological Framework
Cross-validation between regulatory filing analysis and supply chain documentation anchors the qualitative findings in this study. Primary interviews with formulation scientists, aseptic processing equipment vendors, category buyers at specialty retailers, and regulatory affairs leads at functional food manufacturers combined with secondary validation from FDA GRAS notifications, EFSA health claim registers, SAMR functional food approval databases, and SEC 10-K filings. Bottom-up volume modeling and top-down value triangulation across product type, end user, distribution channel, and packaging format dimensions ensured segmentation integrity.
Sensitivity analysis across probiotic strain approval volatility scenarios and sugar-tax threshold adjustment bands tested forecast robustness. The analytical framework projects volume and value trajectories across the analysis window by modeling protein shake, functional beverage, meal replacement, and herbal infusion segments against athlete, fitness enthusiast, busy professional, and health-conscious consumer demand profiles. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and channel migration coefficients. Precision fermentation protein adoption curves and EFSA botanical claim approval velocities served as key industry-specific forecast inputs.
Material uncertainties — SAMR-NMPA dual-approval timeline extensions, EFSA botanical health claim reversals, and cold-fill equipment delivery delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding strain catalog harmonization and sugar-tax threshold stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Extra Virgin Olive Oil Market
Beverages
Water Bottle Market
Beverages
Dairy Based Beverages Market
Beverages
Semillon Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Hydration Infusers Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Japan Kombucha Market
Beverages
Chocolate Malt Drink Market
Beverages
Sports and Energy Drinks Market
Beverages
North America Kombucha Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
GCC Fruit Juice Market
Beverages
Caffeine Mint Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Europe Yerba Mate Market