
 Packaged Turmeric-Based Beverage Market | 2026-2036
Packaged Turmeric-Based Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Turmeric-Based Beverage Market Analytics
Multi-pack bundling of ready-to-drink turmeric shots with complementary wellness shots is broadening buyer choice beyond single-unit trial purchases. Unilever leverages its refrigerated distribution network to sustain shelf presence across mainstream retail channels. The Turmeric Co. specializes in cold-pressed turmeric shots with black pepper activation, dominating the premium convenience segment in the United Kingdom. ORGANIC INDIA Pvt. Ltd. anchors its positioning through certified organic sourcing from smallholder farms in India.
Packaged turmeric-based beverages comprise shelf-stable or refrigerated liquid and dry formulations containing Curcuma longa extract or powder, typically standardized for curcuminoid content between 2-5% in ready-to-drink formats, designed for anti-inflammatory and antioxidant delivery in consumer wellness applications. Ready-to-drink formats command the widest retail footprint but face margin compression from cold-chain logistics, while powdered mix products retain higher unit economics and longer pantry stability. Concentrate segments serve foodservice and wellness center channels where batch preparation flexibility matters, and herbal blends incorporating ashwagandha or ginger are capturing fastest-growing interest among athletes seeking recovery positioning.
FDA labeling requirements for dietary supplements and the EU's Novel Food Catalogue create divergent compliance pathways for turmeric beverages fortified with curcumin extracts versus traditional food-grade formulations. USDA Organic and EU Organic regulations shape raw material procurement, with India's APEDA export certification adding a third layer for suppliers sourcing from subcontinent processing clusters. Stakeholders must monitor how evolving caffeine-free functional beverage classifications in major jurisdictions affect shelf placement and health claim permissions.
Market Dynamics
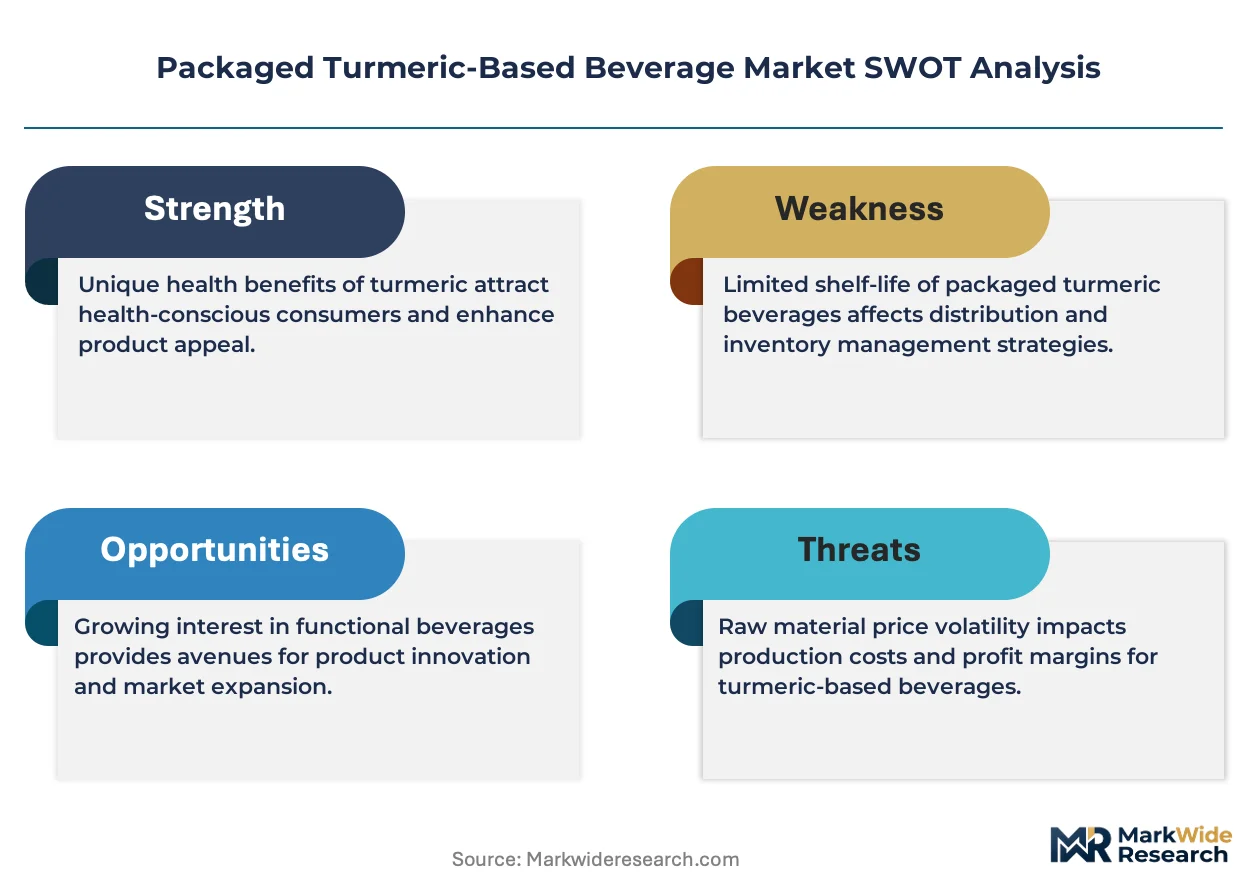
The packaged turmeric-based beverage market is experiencing structural pressure from cold-chain logistics costs, which compress margins for ready-to-drink formats while favoring shelf-stable and powdered alternatives with superior unit economics and distribution reach.
Growth Catalysts
- EU Organic Regulation (EU 2018/848):Mandatory certification standards for organic claims are accelerating farm-to-bottle traceability investments and premium positioning for certified products.
- Wellness center channel expansion:Recovery-focused beverage menus in North American and European fitness facilities are creating dedicated pull-through for turmeric shots positioned as post-workout anti-inflammatory solutions.
- Black pepper extract (piperine) bioavailability enhancement:Formulation science advances are standardizing curcumin absorption rates, enabling consistent efficacy claims across ready-to-drink portfolios.
Market Restraints
- Raw material concentration risk:India's dominance in turmeric cultivation creates supply vulnerability to monsoon variability and export policy shifts from APEDA.
- FDA dietary supplement versus food classification friction:Divergent compliance pathways for curcumin-fortified beverages create formulation uncertainty and label claim restrictions.
- Refrigerated distribution cost structure:Cold-chain requirements for premium shots impose 15-25% logistics premiums versus ambient-stable alternatives, limiting mainstream retail penetration.
Strategic Opportunities
- Foodservice concentrate segment:Batch-preparation flexibility for wellness centers and cafes enables higher-margin B2B positioning with lower per-unit logistics burden.
- Herbal blend convergence:Formulations combining turmeric with ashwagandha or ginger are capturing athlete recovery positioning in United States metropolitan markets.
- Caffeine-free functional beverage shelf placement:Evolving retail classification systems in major jurisdictions are opening dedicated aisle space previously occupied by energy drinks.
Industry Challenges
- Clean-label certification timeline compression:USDA Organic and EU Organic audit cycles are extending supplier onboarding timelines, constraining new product velocity.
- Curcuminoid standardization complexity:Achieving consistent 2-5% curcuminoid content across harvest batches requires advanced extraction infrastructure and quality control investment.
- Multi-jurisdiction label harmonization:Divergent health claim permissions between FDA, EFSA, and FSSAI frameworks complicate global portfolio architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Turmeric-Based Beverage Market |
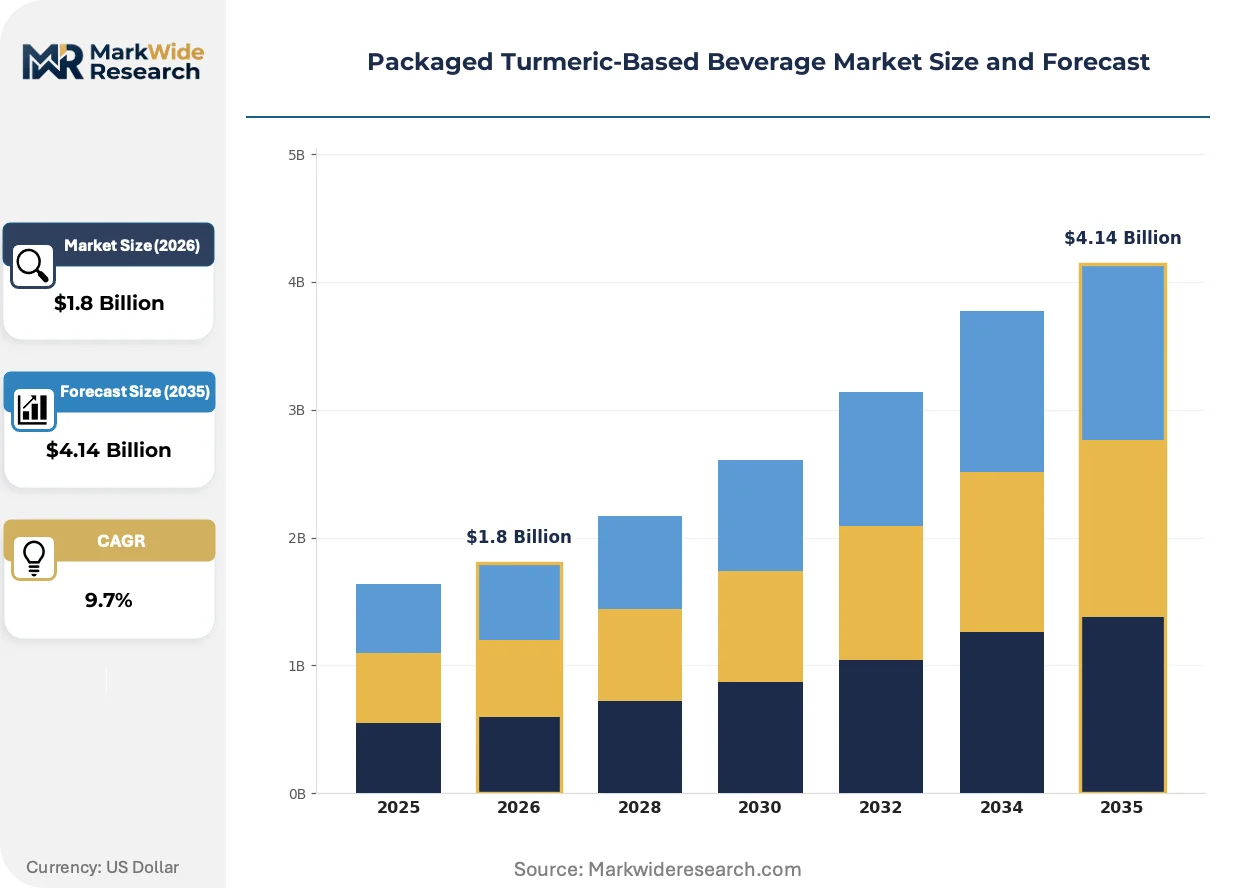
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Powdered Mix, Concentrate, Instant Beverage Ingredient Type: Organic Turmeric, Curcumin Extract, Herbal Blends, Flavor Additives Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops End User: Health Conscious Consumers, Athletes, Wellness Centers, Restaurants |
| Companies Covered | House Foods Group, The Turmeric Co., Unilever, Vahdam Teas Pvt. Ltd., Traditional Medicinals, Numi, Dunn's River Brands, ORGANIC INDIA Pvt. Ltd., Gaia Herbs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Turmeric-Based Beverage Market Evolving Landscape
Formulation science and regulatory classification systems are actively reshaping competitive positioning in turmeric beverages, with bioavailability enhancement and supply chain transparency emerging as the primary axes of differentiation.
Cold-pressed extraction technology is integrating black pepper activation directly into single-serve shot formats, preserving volatile compounds that degrade in heat-processed alternatives. Premium wellness consumers in London and New York metropolitan markets are adopting these products at accelerated velocities. This technology is integrating farm-fresh positioning with extended retail shelf presence, compressing the traditional trade-off between processing method and distribution reach.
EFSA's evolving Novel Food Catalogue guidance for curcumin extracts is forcing manufacturers to segregate traditional food-grade formulations from fortified supplement-positioned products. The industrial consequence is dual supply chain architecture with distinct procurement, labeling, and channel strategies. Ready-to-drink formats with elevated curcuminoid content face the most acute compliance pressure, driving reformulation toward whole-root turmeric bases in European markets.
Athlete recovery positioning is displacing general wellness messaging as the dominant demand driver in United States premium channels. Sports nutrition retailers and CrossFit-affiliated facilities are replacing conventional juice bars as the primary trial environment for turmeric shots. This behavioral shift concentrates highest growth velocity in metropolitan fitness ecosystems rather than conventional grocery channels.
Packaged Turmeric-Based Beverage Market Segmentation
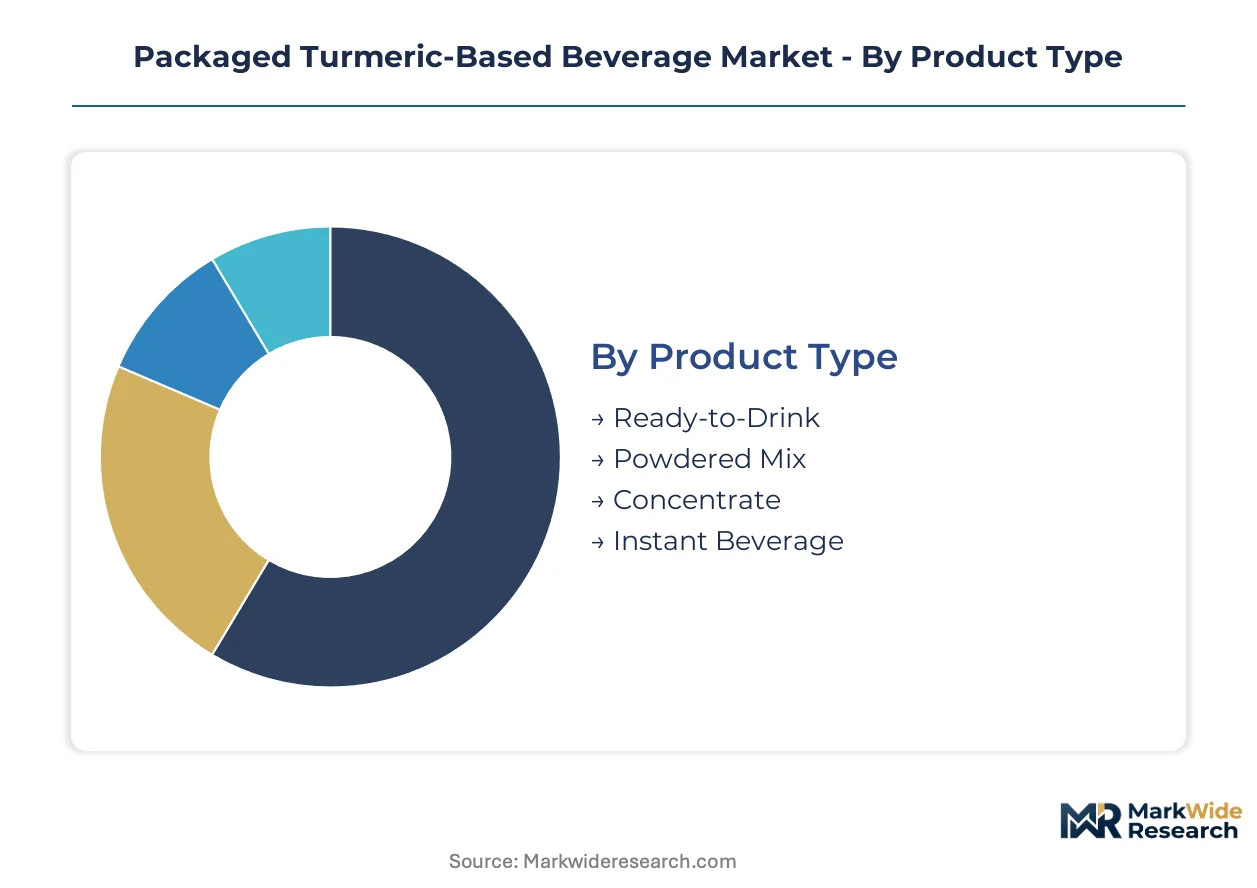
Segmentation in turmeric beverages reflects divergent logistics economics and certification requirements across consumption occasions. Product format selection determines cold-chain investment, while ingredient sourcing governs regulatory pathway and shelf positioning.
Product Type:
Standardization dominates at the mass-market end, with customization expanding at premium price tiers through processing method and bioavailability enhancement.
- Ready-to-Drink:Single-serve liquid formulations in refrigerated or ambient-stable packaging, typically standardized at 2-5% curcuminoid content. Demand concentrates in United States metropolitan markets where health-conscious consumers trial shots at fitness facilities. Cold-chain logistics impose 15-25% distribution cost premiums versus shelf-stable alternatives.
- Powdered Mix:Dry turmeric powder or extract requiring consumer reconstitution, offering superior pantry stability and unit economics. Expansion accelerates in European markets where EU Organic certification drives premium positioning for certified organic variants with farm-to-bottle traceability.
- Concentrate:Dilutable liquid bases serving foodservice batch preparation with flexible serving sizes. Wellness centers in North America adopt concentrates for post-workout recovery menu integration.
- Instant Beverage:Pre-sweetened or flavored soluble powders targeting convenience-oriented consumers. Shelf placement competes with traditional tea and coffee categories in mainstream retail.
Most installed capacity flows through Ready-to-Drink formats. Expansion is steepest in Concentrate solutions for foodservice channels.
Ingredient Type:
Certification tier and extraction method create four distinct procurement cost bands with divergent compliance obligations.
- Organic Turmeric:Whole-root sourcing from certified farms meeting USDA Organic or EU Organic standards, with India's APEDA export certification adding verification layers. Clean-label requirements from European Union and United States regulators accelerate farm-to-bottle traceability investments.
- Curcumin Extract:Standardized isolates enabling precise dosage claims, facing EFSA Novel Food Catalogue scrutiny in European markets. FDA dietary supplement versus food classification creates divergent compliance pathways for fortified beverages.
- Herbal Blends:Turmeric combined with ashwagandha, ginger, or black pepper extract for athlete recovery positioning. CrossFit-affiliated facilities in United States metropolitan markets drive trial velocity for these formulations.
- Flavor Additives:Natural or nature-identical flavoring agents masking turmeric's inherent bitterness. Mass-market penetration depends on palatability engineering for mainstream consumer acceptance.
Procurement volume concentrates in Organic Turmeric supply chains. Steepest expansion trajectory belongs to Herbal Blends capturing sports nutrition channel growth.
Distribution Channel:
Channel selection determines margin structure, with direct-to-consumer models capturing value otherwise lost to retail markup and slotting fees.
- Online Retail:Subscription and direct-to-consumer platforms enabling premium positioning with educational content. United States health-conscious consumers in metropolitan markets drive subscription velocity for cold-pressed shot formats.
- Supermarkets:Mainstream grocery placement requiring refrigerated distribution infrastructure or ambient-stable formulation. Unilever leverages existing refrigerated networks to sustain shelf presence across conventional retail.
- Health Stores:Specialty retailers prioritizing certified organic and clean-label assortments. EU Organic Regulation compliance accelerates category placement in European natural products channels.
- Specialty Shops:Independent wellness boutiques and juice bars offering curated turmeric shot menus. The Turmeric Co. dominates this channel in United Kingdom metropolitan markets through cold-pressed premium positioning.
Volume concentrates in Supermarkets. Online Retail demonstrates the steepest expansion trajectory as subscription models reduce customer acquisition costs.
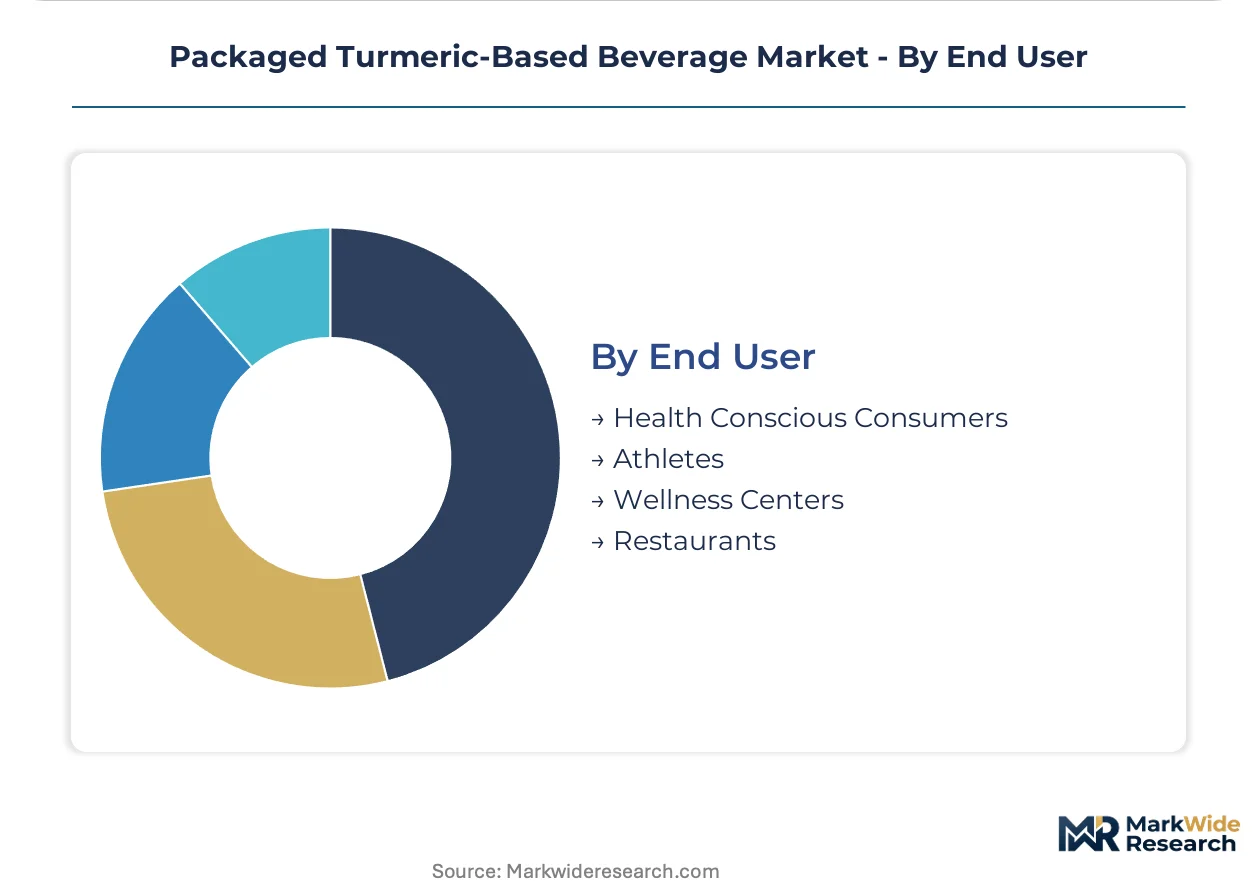
End User:
User sophistication spans from trial-oriented wellness seekers to institutional buyers with formulation specifications and batch consistency requirements.
- Health Conscious Consumers:Individual purchasers prioritizing anti-inflammatory and antioxidant benefits in daily wellness routines. Metropolitan markets in United States and United Kingdom show highest per-capita consumption rates for premium ready-to-drink formats.
- Athletes:Recovery-focused users seeking post-workout inflammation management. Sports nutrition retailers displace conventional juice bars as primary trial environment for turmeric shots in United States fitness ecosystems.
- Wellness Centers:Institutional buyers requiring batch preparation flexibility and consistent curcuminoid standardization. North American and European fitness facilities expand functional beverage menus to include turmeric lattes and shots.
- Restaurants:Foodservice operators integrating turmeric beverages into specialty coffee and wellness drink programs. Concentrate formats enable cost-effective menu integration with lower per-unit logistics burden.
Health Conscious Consumers represent the largest installed demand base. Athletes demonstrate the steepest expansion trajectory as recovery positioning displaces general wellness messaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turmeric cultivation and beverage formulation trace their commercial lineage to India's Ayurvedic traditions, with contemporary market development scaling through North American and European wellness infrastructure over the past decade.
United States
Metropolitan fitness ecosystems in New York, Los Angeles, and Austin drive trial velocity for cold-pressed turmeric shots positioned as post-workout recovery solutions. FDA dietary supplement versus food classification creates divergent compliance pathways for curcumin-fortified beverages, forcing dual formulation strategies. Sports nutrition retailers in Denver and Miami displace conventional juice bars as primary discovery channels for athlete-focused herbal blends.
United Kingdom
London's premium convenience segment anchors European demand for cold-pressed activation formats with black pepper bioavailability enhancement. EU Organic Regulation (EU 2018/848) mandates farm-to-bottle traceability investments that advantage certified supply chains. The Turmeric Co. dominates specialty shop channels across Greater London and Manchester through refrigerated premium positioning.
Germany
EFSA's Novel Food Catalogue scrutiny shapes procurement strategies for curcumin extracts versus traditional food-grade formulations. Berlin and Hamburg wellness centers expand functional beverage menus to include turmeric lattes as caffeine-free alternatives. German health stores prioritize EU Organic certification, accelerating category placement in natural products channels.
India
Smallholder farm clusters in Maharashtra and Karnataka supply certified organic turmeric meeting USDA Organic and EU Organic standards through APEDA export verification. ORGANIC INDIA Pvt. Ltd. anchors domestic processing infrastructure with backward integration into cultivation networks. Mumbai and Bangalore processing hubs concentrate extraction capacity for standardized curcuminoid content.
Australia
TGA classification frameworks for complementary medicines influence label claim permissions for turmeric beverages with elevated curcuminoid content. Sydney and Melbourne metropolitan consumers trial powdered mix formats with superior pantry stability for home preparation. Wellness centers in Brisbane integrate concentrate solutions for flexible batch preparation in post-workout recovery programs.
Packaged Turmeric-Based Beverage Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and processing method, with cold-pressed organic formats commanding 40-60% price premiums over heat-processed alternatives. The vendor base stratifies into three archetypes: multinational CPG conglomerates leveraging refrigerated distribution infrastructure, specialist cold-pressed shot producers dominating premium convenience channels, and certified organic sourcing specialists with farm-level integration. Dominant competitive moves include M&A activity targeting regional organic brands and strategic partnerships with wellness center chains for exclusive supply arrangements.
Within the multinational tier, Unilever exemplifies scale-driven refrigerated network leverage across mainstream retail placement. Among certified organic specialists, ORGANIC INDIA Pvt. Ltd. and Gaia Herbs occupy positions anchored by farm-level sourcing control and third-party certification authority. The Turmeric Co. represents the premium convenience archetype with concentrated channel presence in United Kingdom metropolitan markets.
| Leading Market Players |
|---|
| House Foods Group |
| The Turmeric Co. |
| Unilever |
| Vahdam Teas Pvt. Ltd. |
| Traditional Medicinals |
| Numi |
| Dunn's River Brands |
| ORGANIC INDIA Pvt. Ltd. |
| Gaia Herbs |
| Others |
Value Network & Pricing Analysis
Wellness center procurement concentration in United States metropolitan markets anchors contract-based pricing for concentrate formats, while retail buyers face spot-market volatility for cold-pressed shots. Cold-chain logistics premiums compress margins for refrigerated SKUs, forcing suppliers toward shelf-stable alternatives or direct-to-consumer subscription models that capture value otherwise lost to distributor markups.
Pricing Analysis
Three-tier pricing structure across premium cold-pressed, standard heat-processed, and economy powdered formats governs the market. Certification grade—USDA Organic versus conventional—and processing method drive price differentiation, with organic cold-pressed shots commanding substantial premiums. Cost compression in refrigerated tiers intensifies because logistics operators pass through fuel and equipment scarcity charges. Foodservice buyers exhibit highest price sensitivity due to batch-volume negotiation leverage, while direct-to-consumer subscribers show lowest sensitivity given education-driven perceived efficacy.
Supply Chain Analysis
Domestic-content mandates in India's APEDA export certification framework reshape sourcing toward verified smallholder clusters in Maharashtra and Karnataka. Raw material procurement draws from Indian turmeric cultivation, Indonesian black pepper extract for piperine activation, and European Union-sourced organic flavoring agents. Single-source vulnerability concentrates in Indian monsoon-dependent harvest cycles that disrupt curcuminoid standardization. Distribution runs through refrigerated networks for ready-to-drink formats and ambient logistics for powdered alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where athlete recovery positioning displaces general wellness messaging, elevating demand for certified organic formulations with bioavailability enhancement.
For Market Incumbents: Lock in exclusive supply arrangements with wellness center chains in United States metropolitan fitness ecosystems to defend against specialist cold-pressed entrants. Backward integration into APEDA-certified Indian farm clusters secures organic raw material access as EU Organic audit timelines extend supplier onboarding. Channel control through refrigerated distribution infrastructure sustains retail shelf presence against ambient-stable alternatives. For New Entrants and Emerging Players: Enter via foodservice concentrate segments serving North American wellness centers, where batch-preparation flexibility enables higher-margin B2B positioning with lower per-unit logistics burden. The most penetrable white space sits in caffeine-free functional beverage shelf placement previously occupied by energy drinks. A direct-to-consumer subscription model with educational content on curcumin absorption reduces customer acquisition costs relative to conventional retail slotting. For Investors and Strategic Acquirers: Beverage conglomerates with refrigerated infrastructure are the most active acquirer in this space, seeking certified organic brands with farm-level integration. The long-term viability framing centers on consolidation of fragmented specialist producers into scale-efficient portfolios. The signal to watch is EFSA Novel Food Catalogue enforcement intensity, which could force costly reformulation of curcumin-fortified products toward whole-root bases.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | EU Organic Regulation compliance accelerates farm-to-bottle traceability investments for premium positioning. |
| Cold-Pressed Technology Deployment | Black pepper activation integration preserves volatile compounds that degrade in heat-processed alternatives. |
| Foodservice Concentrate Expansion | Wellness center channel growth enables higher-margin B2B positioning with flexible batch preparation. |
| Direct-to-Consumer Subscription Launch | Educational content on bioavailability reduces acquisition costs versus conventional retail slotting fees. |
| Herbal Blend Formulation Development | Ashwagandha and ginger combinations capture athlete recovery positioning in United States fitness ecosystems. |
Research Methodology
Bottom-up wellness center and retail channel modeling reconciled against top-down turmeric cultivation and processing capacity tracking forms the analytical core. Primary interviews with brand managers at beverage conglomerates, category buyers at sports nutrition retailers, supply planners at cold-pressed specialists, and procurement leads at wellness center chains combined with secondary validation from FDA labeling guidance documents, EFSA Novel Food Catalogue entries, APEDA export certification records, and USDA Organic audit databases. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map curcuminoid demand by product format, ingredient certification tier, distribution channel, and end-user sophistication across the projection horizon. Segmentation dimensions include ready-to-drink versus powdered versus concentrate formats, organic versus conventional sourcing, and health-conscious consumer versus athlete versus institutional buyer categories. CAGRs derive from trend extrapolation of wellness center menu expansion rates and organic certification penetration curves, with cold-chain logistics cost inflation and EFSA regulatory enforcement intensity as key forecast inputs.
Inputs from FDA and EFSA regulatory filings were available through the study window; gaps in real-time APEDA smallholder farm yield data introduce uncertainty bands around raw material cost assumptions. Forecasts reflect documented assumptions about wellness center channel growth velocity and organic certification audit timeline compression. Supply disruption from Indian monsoon variability and evolving caffeine-free beverage retail classification represent specific risk factors that could revise projections. A small set of named triggers—EFSA enforcement actions, APEDA export policy shifts, and major wellness center chain bankruptcy events—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
India Cafes & Bars Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Fiber Fortified Beverages Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Crystal Boba Market
Beverages
Coconut Milk Beverages Market
Beverages
Baby Drinks Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Italy Probiotic Drinks Market
Beverages
North America Juices Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Electrolyte Mixes Market
Beverages
Fruit Water Market