
 Premium Bottled Water Market | 2026-2036
Premium Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Bottled Water Market Intelligence
The split between premium and commodity bottled water is realigning around source certification, packaging material, and channel positioning rather than price alone. Danone S.A. leverages its Evian and Volvic source protection agreements to anchor volume in European retail. Nestlé S.A. competes through Perrier and S.Pellegrino distribution depth in foodservice channels across North America and Asia. PepsiCo Inc. differentiates its LIFEWTR and premium offerings through artist-designed packaging and pH-balanced positioning in urban convenience formats.
Premium bottled water denotes water sourced from protected underground springs or mineral aquifers, meeting strict chemical composition standards for dissolved solids, silica content, and natural carbonation levels, then packaged without treatment that alters intrinsic mineral balance. Its primary commercial purpose is to serve as a differentiated beverage in hospitality, retail, and wellness contexts where provenance and purity justify price elevation above purified tap alternatives. Spring water and mineral water categories dominate value pools due to source scarcity and protected designation status, while sparkling water segments show the fastest structural expansion as restaurants replace soda fountains with premium carbonated options. Glass bottle formats command the highest margin pools in on-premise channels, though BPA-free plastic and eco-friendly packaging variants are gaining velocity in e-commerce subscription models.
The EU F-Gas Regulation and REACH frameworks govern carbonation equipment and packaging material compliance across European production sites, while the FDA enforces bottled water quality standards and source labeling requirements in the United States. These regulatory layers elevate compliance costs for new entrants but simultaneously protect incumbent positions by validating premium claims through enforceable standards. Stakeholders must monitor evolving extended producer responsibility laws and source extraction permits as the primary variables that will determine which producers can sustain volume growth without geographic expansion.
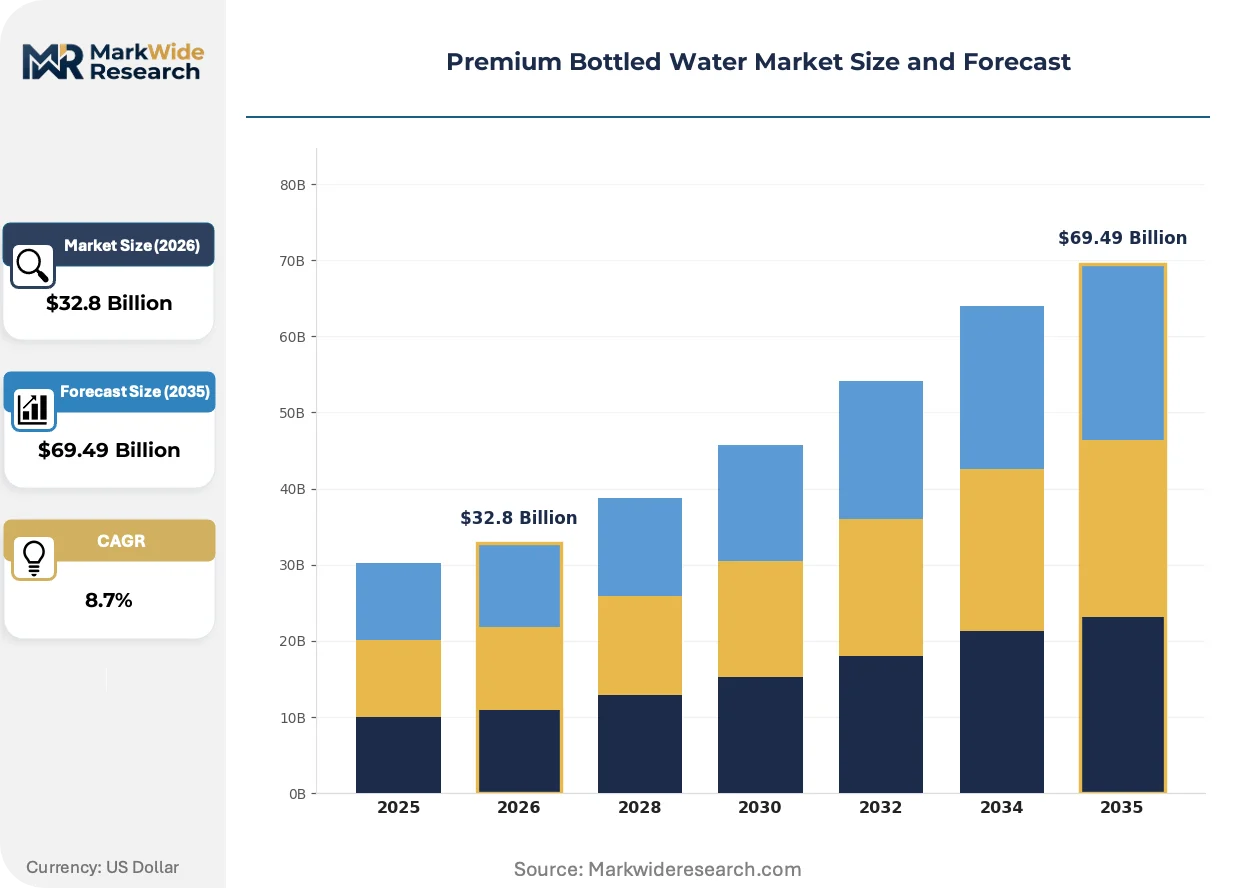
Market Dynamics
The EU F-Gas Regulation and single-use plastic directives are compressing commodity PET production while simultaneously elevating glass and refillable formats, forcing producers to reconfigure packaging portfolios around compliance rather than cost optimization alone.
Growth Catalysts
- Protected Source Certification:Germany's Black Forest and Italy's Lombardy region enforce strict aquifer protection agreements that validate mineral content claims and command sustained price premiums in European retail channels.
- EU Green Deal Implementation:Extended producer responsibility mandates across member states accelerate refillable bottle adoption and reward producers with closed-loop distribution infrastructure.
- Luxury Hospitality Specification:Properties in Dubai and the Maldives now mandate certified mineral water for guest room minibars, creating anchored volume commitments that stabilize revenue volatility.
Market Restraints
- Source Scarcity Concentration:Protected mineral aquifers in France, Italy, and Germany face extraction permit moratoriums that cap volume expansion for incumbent producers.
- Glass Packaging Cost Volatility:Energy-intensive furnace operations and natural gas price fluctuations in European manufacturing clusters compress margin pools for premium on-premise formats.
- Carbonated Water Equipment Compliance:REACH frameworks governing carbonation machinery impose retrofit costs that disadvantage smaller regional bottlers without captive technical teams.
Strategic Opportunities
- Wellness Channel Expansion:Urban fitness studios and medical spas in the United States are replacing complimentary tap water with pH-balanced premium offerings, creating new consumption occasions beyond traditional hospitality.
- E-commerce Subscription Models:Direct-to-consumer platforms enable producers to bypass retail slotting fees and capture recurring revenue through BPA-free plastic and aluminum format variety packs.
- Protected Designation Expansion:Emerging mineral water sources in the Swiss Alps and Austrian Tyrol seek PDO status under EFSA frameworks, opening new provenance narratives for market entry.
Industry Challenges
- Source Extraction Permit Timelines:Aquifer testing and geological validation requirements under national environmental agencies extend new source commercialization to multi-year horizons.
- Legacy PET Infrastructure Stranding:Producers with sunk investments in single-use plastic bottling lines face accelerated depreciation as EU member states advance deposit-return scheme mandates.
- Carbon Accounting Certification:CSRD-aligned scope 3 emissions disclosure requirements demand supply chain traceability that many mid-tier bottlers lack the data infrastructure to satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Bottled Water Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $69.49 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Sparkling Water, Flavored Water Packaging Type: Glass Bottles, BPA-Free Plastic, Tetra Pak, Eco-Friendly Packaging Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores End User: Households, Restaurants, Hotels, Gyms |
| Companies Covered | Danone S.A., Gerolsteiner Brunnen GmbH & Co. KG, Nestlé S.A., Ty Nant, Sanpellegrino S.p.A., PepsiCo Inc., FIJI Water Company LLC, Bling H2O LLC, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Bottled Water Market Strategic Shifts & Innovations
Packaging material substitution and carbonation technology advancement are restructuring competitive advantage around sustainability verification rather than traditional brand equity, with regulatory compliance emerging as the primary differentiator in premium positioning.
Aluminum bottle formats with internal epoxy liners are overtaking glass in urban convenience channels where weight reduction and recycling infrastructure compatibility matter more than tactile luxury. Boutique hotel chains in Copenhagen and Amsterdam have shifted procurement specifications to favor aluminum, compressing glass volume share in Scandinavian foodservice. The structural consequence is margin pool redistribution toward producers with captive aluminum forming partnerships rather than legacy glass furnace assets.
REACH frameworks governing carbonation equipment refrigerants are mandating HFO and natural refrigerant retrofits across European production sites by fixed compliance deadlines. This industrial consequence elevates capital requirements for carbonated water capacity expansion, favoring producers with existing technical service networks. Sparkling mineral water segments in France and Germany face the steepest compliance costs, driving consolidation among regional bottlers without captive engineering capabilities.
Subscription-based replenishment models are displacing impulse retail purchases in wellness-oriented households, with curated variety packs and personalized mineral content matching replacing single-SKU supermarket transactions. Direct-to-consumer platforms in California and New York metropolitan areas capture recurring revenue through algorithmic reorder timing, while traditional convenience store channels lose frequency among health-conscious demographics. This behavioral shift concentrates customer lifetime value with producers investing in proprietary e-commerce infrastructure rather than retail slotting fee negotiations.
Premium Bottled Water Market Segmentation
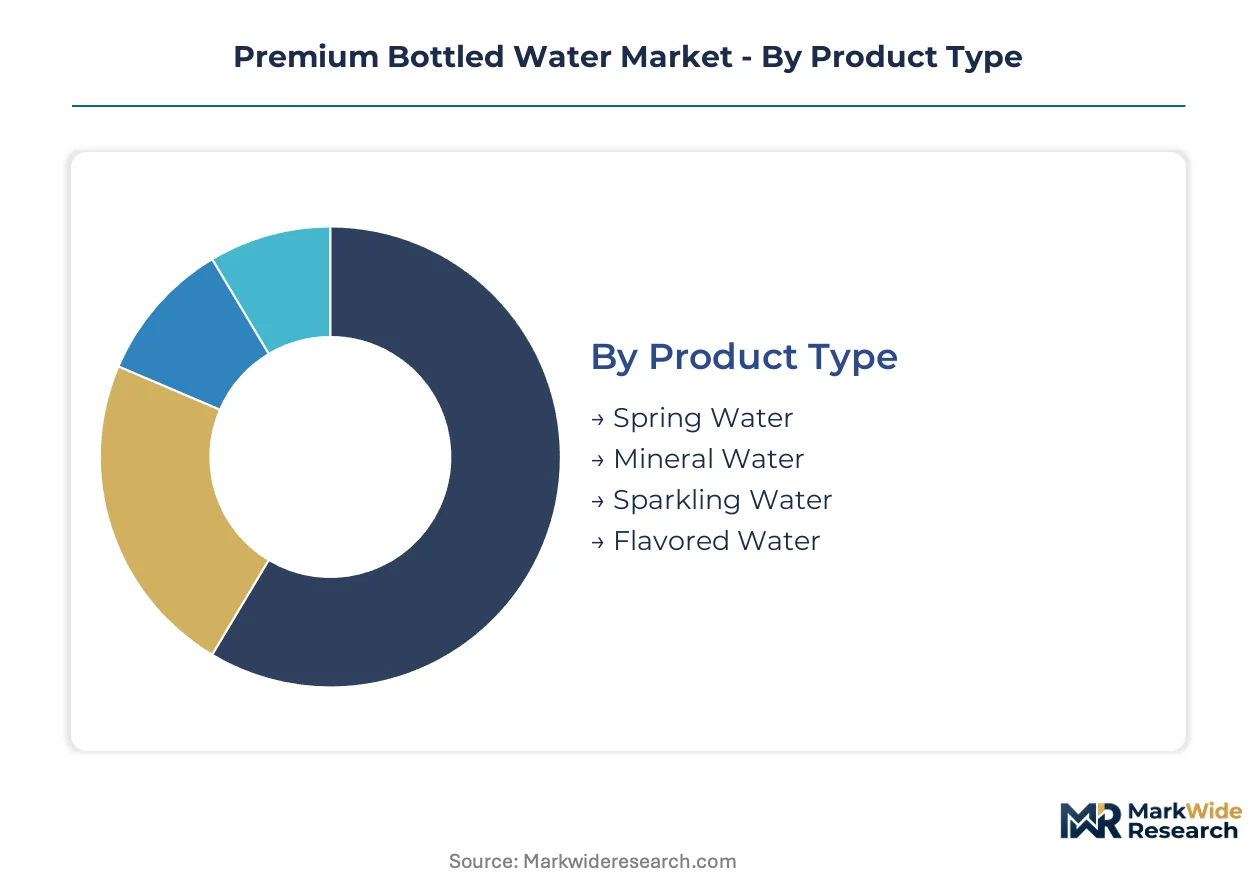
Premium bottled water segmentation reveals how capital deployment, regulatory compliance, and channel economics fragment value capture across the industry. Producers must align portfolio decisions with source certification costs, packaging furnace investments, and distribution infrastructure requirements.
Product Type:
Capital intensity varies sharply by product type, with protected aquifer extraction and mineral content validation demanding the heaviest upfront geological and legal investment.
- Spring Water:Sourced from protected underground formations with documented flow rates and mineral stability. Germany's Black Forest and Italy's Lombardy region concentrate demand where PDO status validates extraction permits and commands sustained price premiums in European retail.
- Mineral Water:Naturally carbonated or still water from geologically certified aquifers with fixed dissolved solid minimums. Dubai luxury hospitality properties and Maldives resort minibars now mandate certified mineral water, creating anchored volume commitments that reduce revenue volatility for incumbent producers.
- Sparkling Water:Artificially or naturally carbonated variants requiring pressurized bottling lines and REACH-compliant refrigeration equipment.
- Flavored Water:Value-added variants with natural extracts or essences, typically commanding lower margins due to simpler sourcing requirements.
Most installed capacity flows through Mineral Water. Expansion is steepest in Sparkling Water as restaurants replace soda fountains with premium carbonated alternatives.
Packaging Type:
Margin structure diverges by material based on energy input costs, recycling infrastructure compatibility, and EU regulatory compliance timelines.
- Glass Bottles:Energy-intensive furnace production with natural gas exposure. Copenhagen and Amsterdam boutique hotel chains have shifted procurement specifications toward lighter formats, compressing glass volume share in Scandinavian foodservice despite tactile luxury positioning.
- BPA-Free Plastic:PET alternatives with modified polymer chains eliminating bisphenol content. California and New York metropolitan subscription platforms capture recurring revenue through algorithmic reorder timing of plastic format variety packs.
- Tetra Pak:Laminated paperboard with aluminum barrier layers, gaining velocity in e-commerce for reduced shipping weight.
- Eco-Friendly Packaging:Aluminum bottles with internal epoxy liners overtaking glass in urban convenience channels where recycling infrastructure compatibility outweighs premium perception.
Glass retains the highest per-unit margins in on-premise channels. Aluminum formats are climbing the fastest as EU deposit-return schemes accelerate.
Distribution Channel:
Channel selection determines working capital intensity, with direct-to-consumer platforms requiring proprietary logistics investment versus retail slotting fee structures.
- Supermarkets:High-volume, low-frequency purchases with substantial slotting fee burdens and promotional depth requirements.
- Online Retail:Curated variety packs and personalized mineral content matching displace single-SKU transactions among wellness-oriented households.
- Convenience Stores:Impulse-driven urban formats losing frequency among health-conscious demographics to subscription replenishment models.
- Health Food Stores:Specialty retail with pH-balanced and electrolyte-enhanced positioning, concentrated in fitness-adjacent geographies.
Supermarkets still move the largest absolute volume. Online Retail is expanding most quickly as producers bypass retail slotting fees.
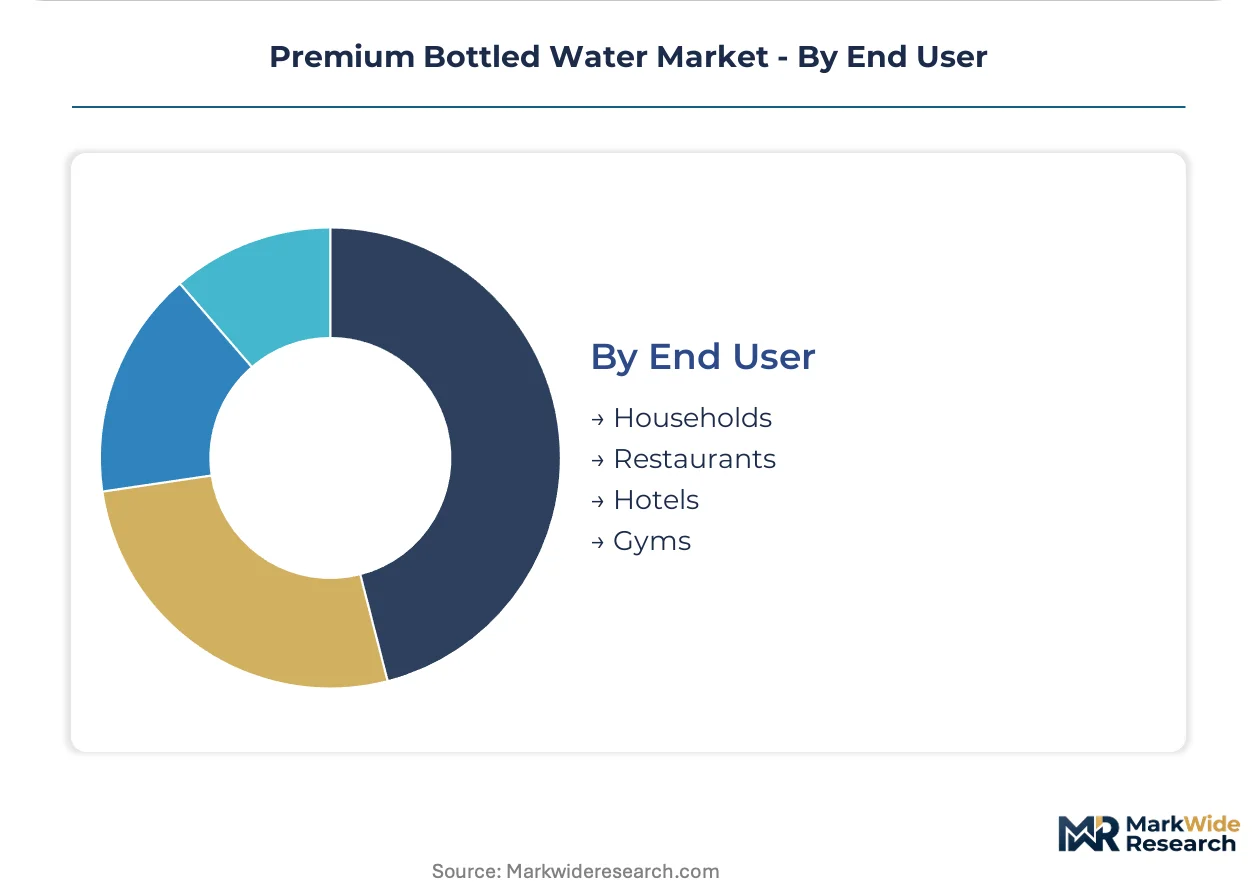
End User:
Customer type dictates packaging format mix and contractual stability, with institutional buyers offering volume predictability versus household fragmentation.
- Households:Fragmented demand across suburban stock-up and urban replenishment occasions, increasingly captured through direct-to-consumer platforms.
- Restaurants:Foodservice specifications favoring glass and aluminum formats, with carbonated options displacing traditional soda fountains.
- Hotels:Luxury hospitality in Dubai and the Maldives mandates certified mineral water for guest room minibars, creating multi-year procurement commitments.
- Gyms:Urban fitness studios and medical spas in the United States replacing complimentary tap water with pH-balanced premium offerings, generating new consumption occasions.
Restaurants absorb the highest packaging cost per liter. Gyms are gaining share fastest as wellness channel penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Source protection expertise concentrates in France, Italy, and Germany where hydrogeologists and mineralogists anchor the industry's technical workforce. Regulatory compliance teams in Brussels and national capitals translate EU directives into operational mandates. This talent distribution shapes where premium water production scales and where new entrants face barriers.
France
Evian-les-Bains and Vittel host the densest clusters of protected aquifer operations, with Danone S.A. and Nestlé S.A. maintaining extraction permits under strict ANSM oversight. The F-Gas Regulation drives carbonation equipment retrofits across Lorraine and Rhône-Alpes production sites. Paris and Lyon foodservice channels absorb the highest glass bottle volumes in European on-premise.
Italy
Lombardy's San Pellegrino Terme and Tuscan mineral districts command PDO status premiums in retail and hospitality procurement. EFSA frameworks govern source certification renewals that validate dissolved solid claims. Milan and Rome restaurant channels displace soda fountains with premium carbonated alternatives, compressing traditional soft drink share.
Germany
Gerolsteiner Brunnen GmbH & Co. KG anchors production in the Eifel volcanic region where mineral content stability supports brand equity. The EU Green Deal accelerates refillable bottle return schemes across Baden-Württemberg and Bavaria. Berlin and Hamburg direct-to-consumer platforms capture subscription revenue through algorithmic replenishment timing.
United States
FIJI Water Company LLC sources from Yaqara Valley aquifers while PepsiCo Inc. and The Coca-Cola Company distribute through urban convenience networks. FDA enforces source labeling requirements and quality standards that elevate compliance costs for imported volumes. California and New York metropolitan wellness channels replace complimentary tap with pH-balanced offerings in fitness studios and medical spas.
United Arab Emirates
Dubai luxury hospitality properties mandate certified mineral water specifications for guest room minibars, creating anchored procurement commitments. MOHAP oversees import standards and source documentation for premium water entering Gulf markets. Jumeirah and Palm Jumeirah resort clusters stabilize revenue volatility for producers with established distribution partnerships.
Premium Bottled Water Market Key Industry Players
Capital-heavy producers compete with asset-light designers across packaging and distribution rather than source access alone. The market structures around three tiers: multinational beverage conglomerates with diversified hydration portfolios, regional specialists with protected source monopolies, and niche luxury entrants with artist-collaboration positioning. Consolidation pressure concentrates among mid-tier bottlers lacking captive engineering teams for carbonation equipment compliance. Dominant competitive moves include portfolio diversification into aluminum formats and strategic partnerships with hospitality procurement consortia.
Within the multinational tier, Danone S.A., Nestlé S.A., and PepsiCo Inc. exemplify divergent strategic anchors. Danone S.A. represents source-protection contracting as a competitive moat. Nestlé S.A. occupies a position defined by foodservice channel depth. PepsiCo Inc. exemplifies artist-designed packaging and pH-balanced positioning for urban convenience penetration. These three patterns illustrate how scale players differentiate without competing directly on identical vectors.
| Leading Market Players |
|---|
| Danone S.A. |
| Gerolsteiner Brunnen GmbH & Co. KG |
| Nestlé S.A. |
| Ty Nant |
| Sanpellegrino S.p.A. |
| PepsiCo Inc. |
| FIJI Water Company LLC |
| Bling H2O LLC |
| The Coca-Cola Company |
| Others |
Cost & Logistics Intelligence
Aluminum bottle adoption across European urban convenience channels is compressing legacy glass furnace economics while simultaneously redistributing margin pools toward producers with captive forming partnerships rather than energy-intensive manufacturing assets. This packaging transition elevates sourcing flexibility for brands while stranding sunk investments in single-use PET infrastructure under advancing deposit-return mandates.
Pricing Analysis
Bundled hospitality procurement contracts versus unbundled direct-to-consumer subscriptions define the pricing architecture. Three-tier pricing structure across premium mineral, standard spring, and economy purified levels stratifies by source certification grade and channel format. Pricing pressure stems from natural gas volatility in European glass manufacturing clusters. Quick-service restaurants exhibit highest price sensitivity; luxury hotel minibars demonstrate lowest.
Supply Chain Analysis
Direct-to-hospitality channels handle anchored volume commitments from Dubai and Maldives resort properties, while direct-to-consumer platforms manage algorithmic replenishment for wellness-oriented households. Supply concentrates in France, Italy, and Germany where protected aquifer extraction permits face national environmental agency oversight. Raw material dependencies include aluminum sheet stock, BPA-free polymer resins, and natural gas for furnace operations. Single-source vulnerability runs through concentrated mineral water source regions. Distribution runs through hybrid retail-slotting and proprietary e-commerce logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium bottled water functions as a stable compounder anchored by irreplaceable protected source scarcity and regulatory validation of mineral content claims that sustain price premiums across economic cycles.
For Market Incumbents: Cement source protection agreements through multi-decade aquifer lease renewals in France and Italy ahead of extraction permit moratoriums. Deepen backward integration into aluminum forming partnerships to offset glass cost volatility. Prioritize REACH-compliant carbonation equipment retrofits before fixed compliance deadlines disadvantage regional bottlers lacking captive engineering capabilities. For New Entrants and Emerging Players: The price-point gap between premium PDO-certified mineral water and economy purified alternatives offers white-space entry through mid-tier spring water positioning. Target wellness channel expansion in California and New York metropolitan fitness studios where pH-balanced offerings displace complimentary tap. Pursue e-commerce subscription models with algorithmic reorder timing to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional bottlers stranded by legacy PET infrastructure depreciation yet possessing viable source extraction permits. Five-to-ten year viability hinges on successful format transition to aluminum and refillable closed-loop systems. Monitor EU member state deposit-return scheme implementation velocity as the inflection signal for infrastructure write-down timing.| Strategic Initiative | Industry Significance |
|---|---|
| Source Protection Agreement Renewal | Multi-decade aquifer leases in France and Italy lock in extraction rights ahead of regulatory moratoriums. |
| Aluminum Format Transition | Partnerships with European forming facilities reduce exposure to natural gas price volatility in glass manufacturing. |
| REACH-Compliant Equipment Retrofit | HFO and natural refrigerant upgrades satisfy F-Gas Regulation deadlines across carbonated water production lines. |
| Direct-to-Consumer Platform Launch | Proprietary e-commerce infrastructure captures recurring subscription revenue and bypasses retail slotting fees. |
| Wellness Channel Penetration | pH-balanced positioning in urban fitness studios creates new consumption occasions beyond traditional hospitality. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at luxury hospitality procurement consortia, supply planners at regional bottlers, and regulatory affairs leads at multinational beverage conglomerates with secondary validation from FDA source labeling filings, EU F-Gas Regulation implementation records, EFSA PDO certification databases, and customs trade data on aluminum and glass packaging imports. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Historical reference periods established baseline consumption patterns across source types, packaging formats, and channel structures before projection methodologies extended trends over the forecast horizon. Segmentation dimensions modeled include product type, packaging material, distribution channel, and end-user category alongside regional regulatory cluster variations. CAGRs derived from weighted average growth assumptions across these dimensions incorporate mineral content stability testing timelines, extraction permit renewal cycles, and hospitality procurement contract durations as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for aluminum bottle internal epoxy liner formulations or natural refrigerant carbonation systems would alter the outlook. Forecasts reflect assumptions about EU Green Deal implementation velocity, extended producer responsibility scheme adoption rates, and source extraction permit availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Oat Based Beverages Market
Beverages
Chill Block Market
Beverages
GCC Juice Market
Beverages
Blenders Market
Beverages
Beverage Premix Market
Beverages
Hot Cocoa Mix Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Sports Drink Market
Beverages
South America Bottled Water Market
Beverages
Baby Drinking Water Market
Beverages
Cactus Water Market
Beverages
Kombucha Market
Beverages
United States Recovery Drinks Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Fruit Vinegar Market
Beverages
North America Energy Drink Market