
 Bottled Air Market | 2026-2036
Bottled Air Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Air Market Analysis
The EU Green Deal is rebalancing product standards across industrial gas packaging, compelling manufacturers to redesign cylinder materials and recovery logistics. AIR WATER INC. leverages its integrated gas production network across East Asia to sustain cost advantages in medical-grade distribution. Boost Oxygen LLC. specializes in consumer-portable formats and dominates North American retail channels for recreational applications.
Bottled air refers to compressed or liquefied atmospheric gases—primarily oxygen, nitrogen, or blended formulations—stored in pressurized aluminum or composite cylinders at purity grades ranging from industrial to medical specifications, deployed for respiratory support, altitude compensation, or controlled industrial atmospheres. Medical Grade products anchor current revenue pools through hospital procurement contracts, while Recreational Grade formats are capturing faster growth as adventure sports participation expands. Specialty Blends command premium positioning in niche applications where precise gas ratios determine performance outcomes.
EPA regulations govern industrial gas emissions and cylinder disposal protocols in the United States, while REACH mandates material traceability and restricted substance controls across European supply chains. Japan's METI oversees high-pressure gas safety standards that directly shape product certification requirements for imported cylinders. Stakeholders must monitor evolving packaging recovery obligations and purity testing protocols as regulatory divergence between jurisdictions complicates cross-border product standardization.
Market Dynamics
Refillable cylinder logistics are reconfiguring competitive economics as EU Green Deal packaging recovery mandates force capital redeployment into reverse supply chains and composite material R&D.
Growth Catalysts
- Mountain tourism expansion:Aging demographics in Japan and high-altitude recreation growth across the Alps are pulling portable oxygen into consumer retail channels.
- REACH material traceability:European chemical safety mandates are accelerating substitution of aluminum cylinders with carbon-fiber composites that reduce transport emissions.
- High-pressure gas safety standards:METI certification requirements in Japan are consolidating import channels around qualified suppliers, raising barriers that protect incumbents with established compliance infrastructure.
Market Restraints
- Aluminum price volatility:Cylinder manufacturing costs fluctuate with London Metal Exchange pricing, compressing margins for standardized product lines.
- Industrial gas supply concentration:Bulk oxygen and nitrogen production clusters near petrochemical complexes on the US Gulf Coast, creating geographic dependency for cylinder fill operations.
- Stationary oxygen concentrator substitution:Home medical device improvements are displacing cylinder-based respiratory support for chronic conditions in reimbursed healthcare systems.
Strategic Opportunities
- Adventure sports retail penetration:Specialty outdoor retailers in Colorado and Utah are creating dedicated shelf space for recreational-grade portable oxygen, bypassing traditional industrial gas distributors.
- EU Green Deal innovation funding:Circular economy subsidies for refillable packaging systems are offsetting R&D costs for composite cylinder recovery programs.
- Telemedicine integration:Remote patient monitoring platforms are creating demand for home-delivered medical-grade cylinders with digital adherence tracking.
Industry Challenges
- Composite technician scarcity:Carbon-fiber cylinder repair and recertification requires specialized skills that outpace vocational training program output.
- Multi-jurisdiction certification lag:FDA 510(k) clearance, CE marking under MDR, and PMDA Shonin approval operate on asynchronous timelines, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Air Market |
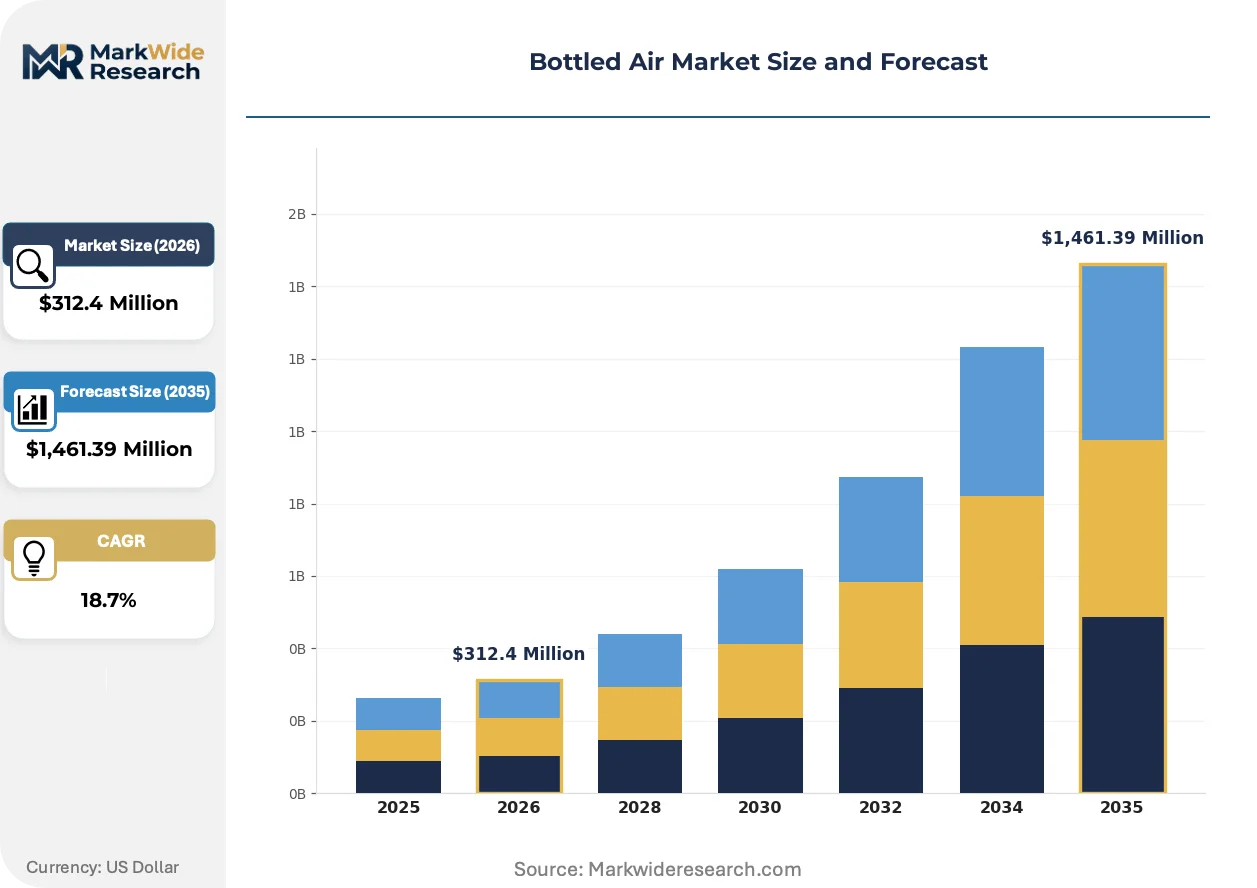
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Grade, Recreational Grade, Industrial Grade, Specialty Blends Application: Health & Wellness, Adventure Sports, Industrial Use, Emergency Situations Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Consumers, Hospitals, Outdoor Enthusiasts, Corporations |
| Companies Covered | AIR WATER INC., Boost Oxygen LLC., Air Liquide SA, Messer SE and Co. KGaA, Gulfcryo, Air Products and Chemicals Inc., Vitality Air, Mitsubishi Corp., Linde Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Air Market Emerging Trajectories
Digital cylinder tracking and automated fill-station networks are compressing asset utilization cycles while regulatory pressure on packaging waste is forcing material science investments.
Smart cylinder telemetry is automating inventory management for medical gas distributors. Hospital systems and home healthcare providers are deploying IoT-enabled pressure monitors that trigger automatic replenishment orders. This connectivity infrastructure is automating demand forecasting and reducing emergency delivery costs for high-dependency patients.
EU F-Gas Regulation amendments are tightening containment standards for fluorinated greenhouse gases used in specialty blend production. Industrial gas blenders must retrofit fill lines with improved leak detection and recovery systems. Medical-grade nitrogen-oxygen mixtures for neonatal care face the steepest compliance costs due to purity verification requirements.
Subscription-based cylinder exchange programs are displacing outright purchase models in North American recreational markets. Outdoor enthusiasts in California and Washington prefer monthly plans with doorstep delivery over retail pickup. This preference shift is visible most acutely in trail running and high-altitude cycling communities where convenience outweighs per-use cost sensitivity.
Bottled Air Market Segmentation
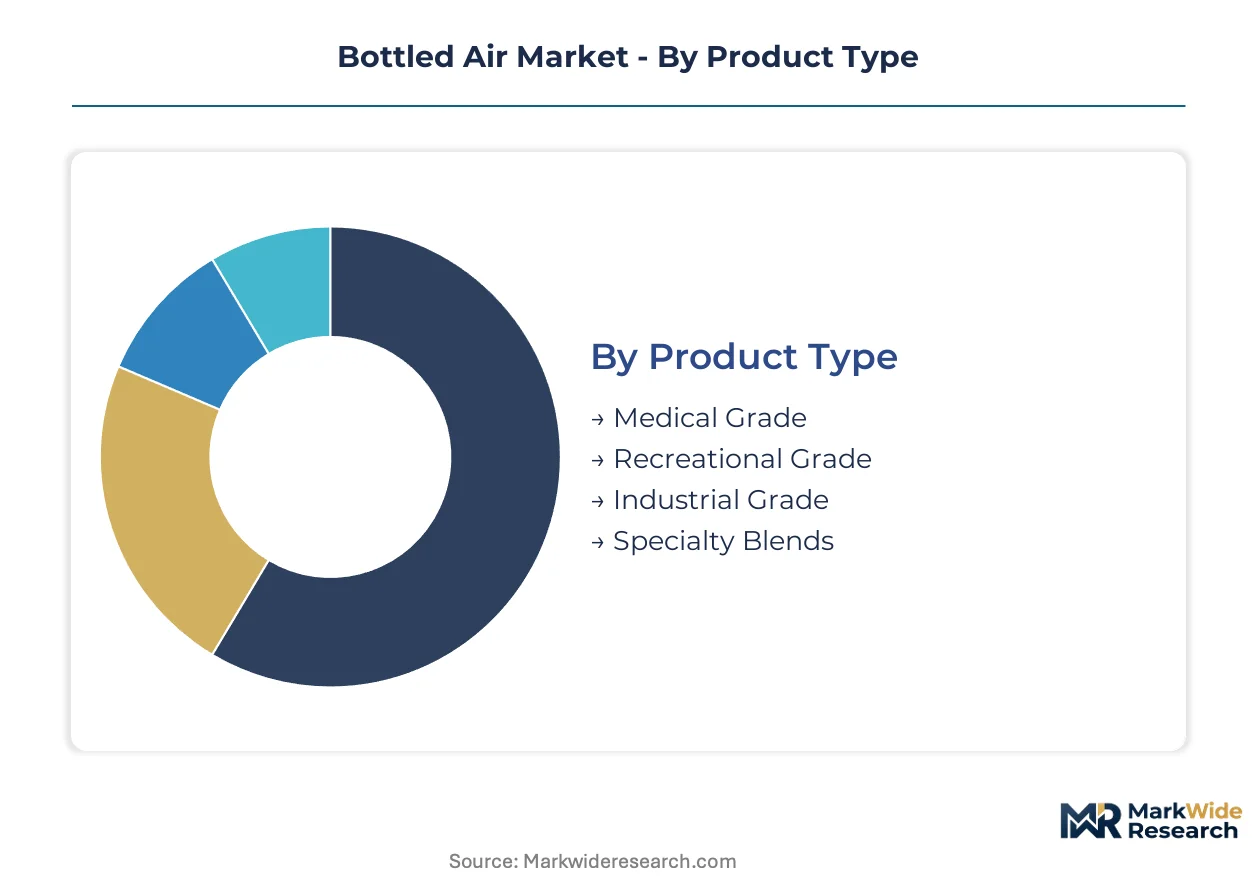
Segmentation in bottled air markets determines regulatory pathways, margin structures, and channel economics. Medical-grade certification creates the steepest barriers, while recreational formats unlock retail velocity through simplified compliance.
Product Type:
FDA 510(k) clearance applies to medical cylinders, CE marking under MDR governs European medical distribution, and METI certification shapes Japanese import eligibility for all pressurized formats.
- Medical Grade:Ultra-high purity oxygen and nitrogen mixtures meeting pharmacopeia standards for respiratory therapy and surgical support. Hospital procurement contracts in Japan and Germany anchor volume, though stationary concentrator substitution constrains chronic care segments.
- Recreational Grade:Lower-purity portable oxygen designed for altitude compensation and athletic recovery. Demand concentrates in Colorado trail running communities and Alpine trekking corridors where convenience retail penetration is accelerating fastest.
- Industrial Grade:Compressed atmospheric gases for manufacturing atmospheres and welding applications. EPA emissions protocols and cylinder disposal mandates shape US distribution economics.
- Specialty Blends:Precision-ratio mixtures for neonatal care, diving, and controlled industrial processes. Purity verification requirements under EU F-Gas Regulation amendments inflate compliance costs disproportionately.
Medical Grade sits at the top of the volume ranking, with Recreational Grade climbing the fastest.
Application:
Cost tier separation is pronounced: reimbursed healthcare systems sustain premium pricing for therapeutic use, while adventure sports operate on discretionary consumer budgets with higher price elasticity.
- Health & Wellness:Home respiratory support and wellness-oriented oxygen supplementation. Japanese aging demographics and telemedicine integration are expanding addressable populations beyond traditional hospital discharge.
- Adventure Sports:High-altitude recreation and endurance athletics requiring portable oxygen reserves. Utah and Washington specialty retailers are creating dedicated shelf space, bypassing industrial gas distributors entirely.
- Industrial Use:Controlled atmospheres for manufacturing, welding, and chemical processing. Gulf Coast petrochemical clustering creates geographic dependency for cylinder fill operations.
- Emergency Situations:Disaster relief stockpiles and first-responder reserves. Procurement runs through government contracts with extended qualification timelines.
Health & Wellness commands the revenue base, while Adventure Sports is gaining share fastest.
Distribution Channel:
Customer type determines channel selection: institutional buyers prefer direct relationships, while consumers migrate toward convenience-oriented formats.
- Online Retail:Subscription-based cylinder exchange programs with doorstep delivery. California trail running communities demonstrate acute preference for monthly plans over retail pickup.
- Specialty Stores:Outdoor retailers in mountain states providing hands-on product education. Staff expertise justifies premium positioning for first-time recreational buyers.
- Supermarkets:Limited penetration confined to pre-packished single-use canisters. Shelf space constraints restrict assortment breadth.
- Direct Sales:Hospital systems and industrial accounts procuring through contracted distributors. IoT-enabled telemetry is automating replenishment orders for high-dependency medical patients.
Direct Sales retains the largest volume footprint, with Online Retail expanding most quickly.
End User:
Margin structure varies sharply: hospitals negotiate multi-year contracts with price escalation caps, while outdoor enthusiasts pay spot premiums for convenience.
- Consumers:Individual purchasers seeking wellness supplementation or recreational altitude support. Subscription model adoption is highest in Pacific Coast metropolitan areas.
- Hospitals:Integrated health systems requiring uninterrupted medical-grade supply with digital adherence tracking. Smart cylinder telemetry is compressing emergency delivery costs.
- Outdoor Enthusiasts:Trail runners, cyclists, and mountaineers prioritizing portability. Colorado and Utah represent the densest concentration of recreational-grade demand.
- Corporations:Industrial manufacturers and emergency preparedness coordinators. Procurement decisions hinge on total cost of ownership including cylinder recovery logistics.
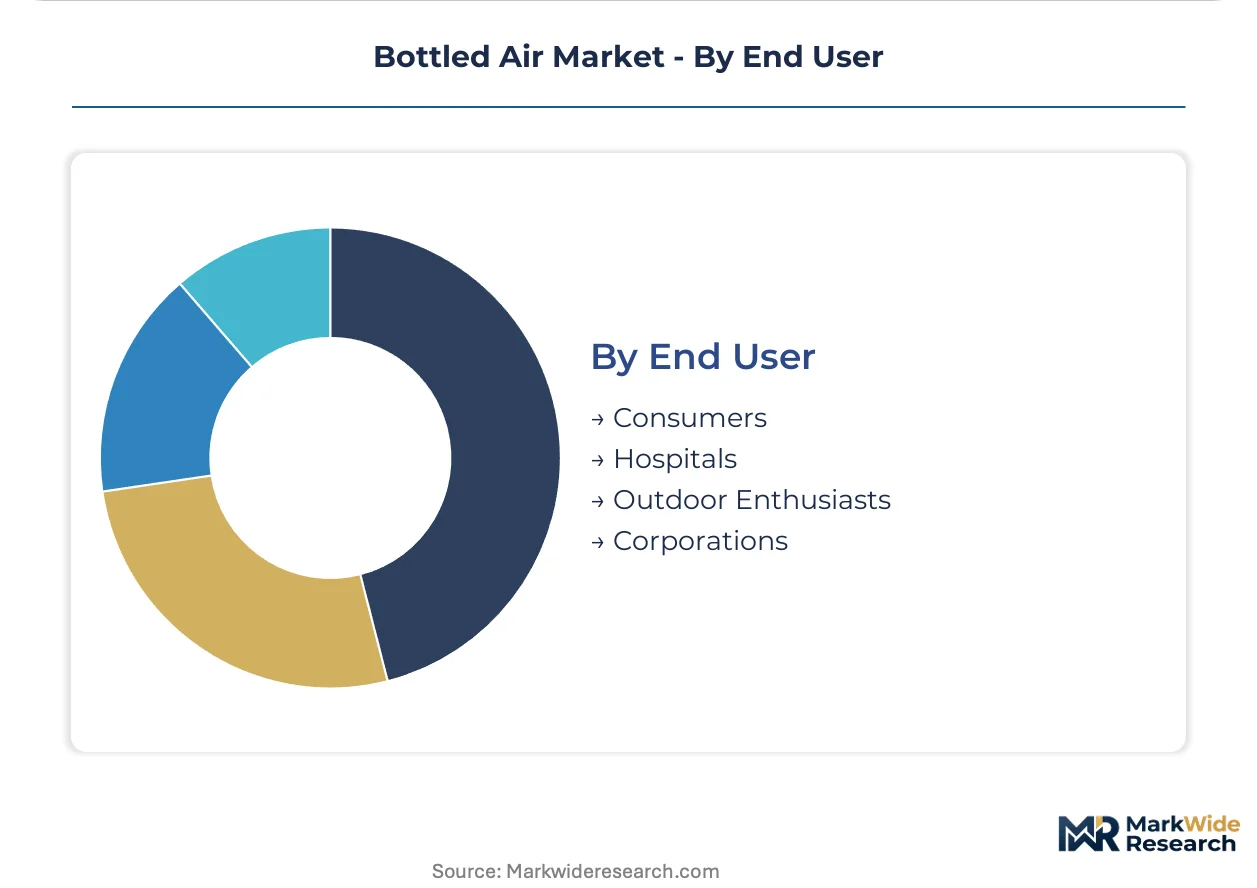
Hospitals dominate current volume, with Outdoor Enthusiasts showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bottled air production traces its modern industrial lineage to German chemical engineering advances in compressed gas handling during the late nineteenth century, with subsequent scaling in the United States through wartime medical oxygen demand and Japanese post-war industrial gas infrastructure development.
United States
Altitude recreation in Colorado and Utah drives recreational-grade consumption, while Gulf Coast petrochemical clusters anchor cylinder fill operations. EPA emissions protocols and cylinder disposal mandates shape distribution economics across industrial and medical segments. Houston and Louisiana industrial corridors concentrate bulk oxygen production near feedstock sources.
Germany
Alpine tourism corridors in Bavaria pull portable oxygen into retail channels, complementing established medical gas demand from university hospital systems. REACH material traceability mandates accelerate carbon-fiber composite substitution for aluminum cylinders. The Ruhr industrial basin maintains legacy welding and manufacturing atmosphere applications.
Japan
Aging demographics in Kanto and Kansai regions expand home respiratory support demand, while Mount Fuji and Japanese Alps tourism create dual consumer pull for recreational formats. METI high-pressure gas safety standards consolidate import channels around qualified suppliers. Nagoya industrial zones sustain precision manufacturing atmosphere requirements.
China
Domestic mountain tourism in Sichuan and Yunnan provinces drives emerging recreational demand, while coastal manufacturing clusters absorb industrial-grade volumes. NMPA medical device oversight and GB standards for pressurized containers shape product certification pathways. Yangtze River Delta electronics manufacturing sustains controlled atmosphere applications.
France
Chamonix and Alpine resort networks sustain recreational oxygen retail penetration, with Paris hospital systems anchoring medical-grade procurement. ANSM pharmaceutical oversight applies to therapeutic gas distribution, while ECHA chemical safety mandates affect cylinder material selection. Lyon and Grenoble industrial zones maintain specialty blend production for diving and medical applications.
Bottled Air Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the bottled air value chain, with integrated gas manufacturers owning fill infrastructure while retail specialists control consumer-facing distribution. The market structures around three tiers: multinational industrial gas conglomerates with captive production networks, regional medical gas distributors with hospital contracting expertise, and direct-to-consumer brands exploiting recreational segment growth. Consolidation pressure concentrates among industrial-grade suppliers, while recreational fragmentation persists. Geographic expansion and portfolio diversification represent dominant competitive vectors as players bridge medical and consumer segments.
Within the integrated industrial gas tier, Air Liquide SA and Linde Plc exemplify capital-intensive archetypes with captive production and distribution infrastructure spanning multiple continents. Boost Oxygen LLC occupies a position representing asset-light consumer specialists focused on recreational retail penetration. AIR WATER INC. anchors the Asia-Pacific regional specialist archetype with integrated East Asian gas production networks. These three patterns—global integrated conglomerate, consumer-focused brand builder, and regional integrated operator—capture the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| AIR WATER INC. |
| Boost Oxygen LLC. |
| Air Liquide SA |
| Messer SE and Co. KGaA |
| Gulfcryo |
| Air Products and Chemicals Inc. |
| Vitality Air |
| Mitsubishi Corp. |
| Linde Plc |
| Others |
Supply Flow & Price Mechanics
Aluminum London Metal Exchange pricing transmits directly through cylinder manufacturing costs, compressing margins for standardized medical-grade lines while REACH-mandated carbon-fiber composites command premium positioning in European distribution.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade pharmacopeia-certified cylinders from recreational portable formats and industrial bulk fills. Certification tier and volume scale drive price differentiation, with FDA 510(k) clearance adding substantial cost to therapeutic-grade procurement. Pricing pressure stems from aluminum commodity volatility and stationary oxygen concentrator substitution in reimbursed healthcare systems. Outdoor enthusiasts in Pacific Coast metropolitan areas show lowest price sensitivity, prioritizing subscription convenience over per-use economics.
Supply Chain Analysis
Regional distribution centers in Houston, Nagoya, and the Ruhr Basin anchor hub-and-spoke patterns for cylinder fill operations and composite material fabrication. Geographic supply concentrates in the United States, Japan, and Germany, with bulk oxygen production clustering near Gulf Coast petrochemical feedstocks. Raw material dependencies span aluminum billet, carbon-fiber pre-preg, and high-purity gas separation membranes. Single-source vulnerability around carbon-fiber composite repair technician training creates recertification bottlenecks. Distribution runs through direct hospital contracting for medical grades and specialty outdoor retail for recreational formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bottled air market functions as a regulatory compounder where EU Green Deal packaging recovery mandates and METI certification requirements continuously reshape competitive economics and demand profiles.
For Market Incumbents: Lock in hospital procurement contracts with multi-year price escalation caps before stationary concentrator substitution accelerates in reimbursed systems. Deepen backward integration into composite cylinder recertification infrastructure to capture margins threatened by technician scarcity. Prioritize METI compliance infrastructure investments to defend Japanese import channels against qualified supplier consolidation. For New Entrants and Emerging Players: Enter via subscription-based cylinder exchange programs in Colorado and Utah trail running communities where convenience retail penetration remains underdeveloped. Target adventure sports retail shelf space creation as the most penetrable vector, bypassing industrial gas distributor relationships entirely. Deploy doorstep delivery logistics as the primary go-to-market angle against entrenched direct sales networks. For Investors and Strategic Acquirers: Consolidation pressure builds where industrial-grade suppliers face capital redeployment requirements from EU packaging recovery mandates and carbon-fiber R&D obligations. Long-term viability favors regional medical gas distributors with hospital contracting expertise and established compliance infrastructure over asset-light recreational brands without fill network control. Watch METI certification timeline acceleration as the signal indicating Japanese import channel barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Cylinder Recovery Program | EU Green Deal subsidies offset R&D costs for refillable packaging circularity investments. |
| Telemedicine Platform Integration | IoT-enabled telemetry automates replenishment for high-dependency home respiratory patients. |
| Carbon-Fiber Material Substitution | REACH mandates accelerate aluminum replacement reducing transport emissions across European supply chains. |
| Adventure Sports Retail Expansion | Specialty outdoor retailers in mountain states create dedicated shelf space bypassing industrial distributors. |
| METI Certification Infrastructure | Japanese high-pressure gas safety standards consolidate import channels protecting qualified incumbent suppliers. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with hospital procurement managers, industrial gas plant engineers, specialty outdoor retail buyers, and composite cylinder recertification technicians with secondary validation from FDA 510(k) filings, METI certification registries, ECHA REACH substance databases, and SEC 10-K disclosures from listed industrial gas conglomerates.
Input-output matrix framing connects cylinder fill capacity utilization rates, aluminum LME price trajectories, and regulatory compliance cost structures to segment-level volume and value outputs across the projection horizon. Product type, application, distribution channel, and end user dimensions were modeled with CAGRs derived from historical procurement pattern analysis and forward-looking regulatory milestone timing. Forecast inputs incorporated EU F-Gas Regulation amendment implementation schedules and telemedicine platform adoption curves for home respiratory monitoring.
Inputs from FDA, ECHA, and METI regulatory databases were available through the study window; gaps in real-time composite cylinder repair technician training program output introduce uncertainty bands around recertification capacity forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Extra Virgin Olive Oil Market
Beverages
Vegetable Juice Market
Beverages
Packaged Coconut Water Market
Beverages
Bubble Food and Beverages Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Caffeine Mint Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Wine Cooler and Chest Freezer Market
Beverages
Indonesia Bottled Water Market
Beverages
Carbonated Beverages Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
North America Fruit Juice Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Fruit Juice Market