
 Asia-Pacific Bottled Water Market | 2026-2036
Asia-Pacific Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bottled Water Market Outlook
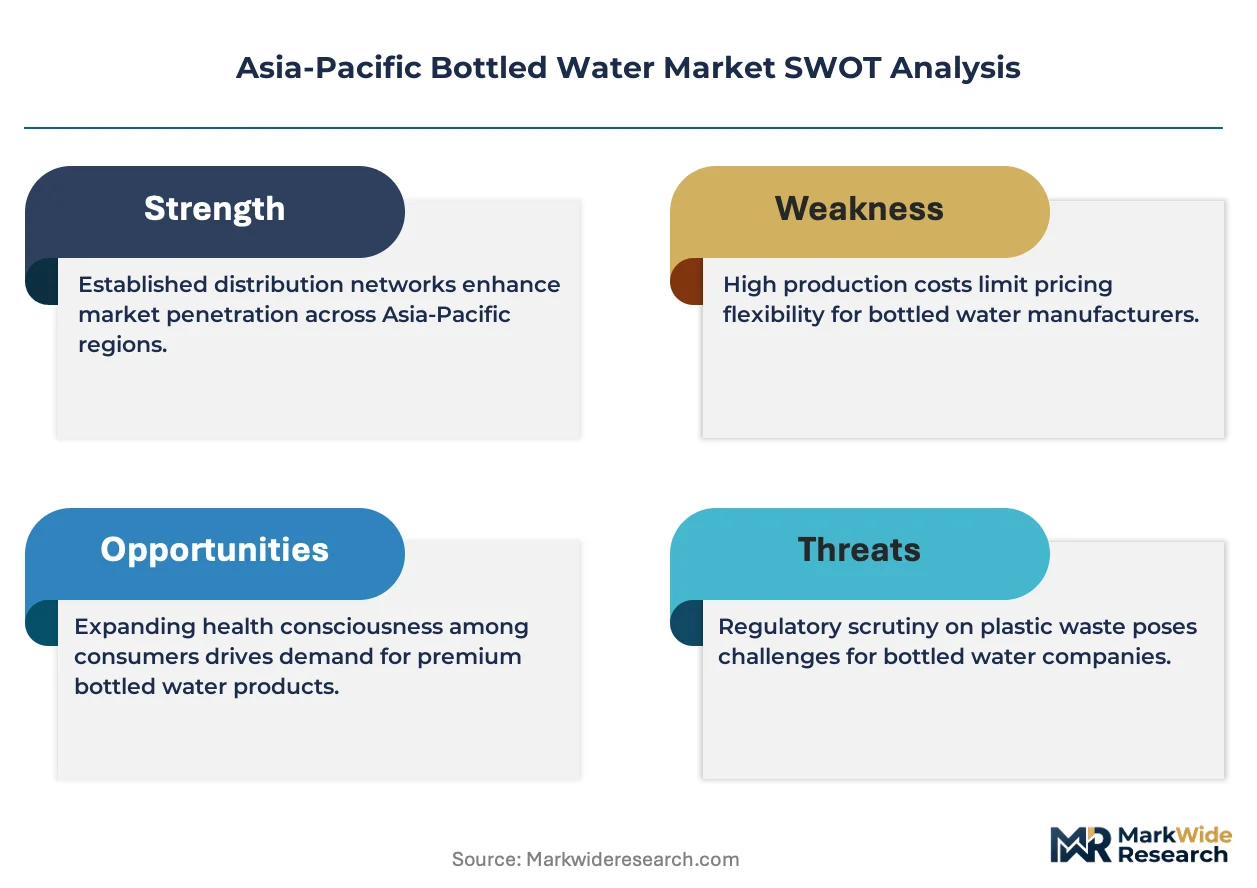
ISO 22000 food safety management certification is unwinding competitive access across the Asia-Pacific bottled water sector, forcing smaller regional bottlers toward costly facility upgrades or exit. Nongfu Spring Co. Ltd leverages its deep well-sourced mineral reserves to dominate premium still water distribution throughout China's tier-one cities. Tata Consumer Products Limited anchors its portfolio through Himalayan-branded natural mineral water, competing directly with Bisleri International, which specializes in mass-market PET packaging across India's fragmented retail landscape.
Bottled water comprises potable water sealed in food-grade containers, treated through reverse osmosis, ultraviolet sterilization, or ozonation to meet microbiological and chemical safety thresholds for direct human consumption. Still water occupies the largest volume share given its everyday affordability and household penetration, while sparkling water captures expanding margin pools among urban professionals seeking alternatives to sugary beverages. PET Bottles sustain overwhelming packaging dominance due to logistics efficiency, though regulatory pressure on single-use plastics is accelerating trials in biodegradable cartons and recycled-content pouches across Japan and South Korea.
China's SAMR enforces GB 19298 standards for packaged drinking water, while India's FSSAI mandates BIS certification for all commercial bottling operations, collectively raising compliance costs and consolidating production toward scaled manufacturers. Japan's Ministry of Health, Labour and Welfare maintains stringent mineral content labeling rules that shape product positioning and import eligibility. Stakeholders must monitor evolving extended producer responsibility frameworks and packaging material restrictions that will determine which production formats remain economically viable.
Market Dynamics
ISO 22000 certification mandates are compressing competitive access across the Asia-Pacific bottled water sector, forcing facility upgrades that favor scaled manufacturers with capital reserves over regional bottlers operating on thin margins.
Growth Catalysts
- Urban household expansion:Municipal water quality deficits in China's eastern coastal provinces and India's western Maharashtra-Gujarat corridor sustain category pull from consumers seeking reliable potable alternatives.
- GB 19298 enforcement:China's SAMR tightening of packaged drinking water standards consolidates production toward compliant facilities, eliminating subscale competitors and protecting volume for certified operators.
- Reverse osmosis diffusion:Treatment technology cost curves enable mid-tier bottlers to achieve microbiological safety thresholds previously reserved for premium mineral water extraction operations.
Market Restraints
- PET resin price volatility:Crude-linked feedstock costs transmit directly to packaging economics, squeezing margin structures for producers without long-term polymer supply contracts.
- Groundwater extraction licensing:China's MEE and India's state-level groundwater authorities are tightening permit issuance for new borewells, constraining capacity expansion for mineral-sourced products.
- Extended producer responsibility frameworks:Japan and South Korea's advancing packaging waste regulations impose collection and recycling cost burdens that disproportionately impact single-SKU regional bottlers.
Strategic Opportunities
- Southeast Asia underpenetration:Vietnam, Indonesia, and Philippines bottled water per-capita consumption trails China and India by substantial margins, offering volume expansion for entrants with distribution scale.
- Biodegradable packaging trials:Carton and recycled-content pouch formats in Japan and South Korea create first-mover positioning ahead of anticipated single-use plastic restrictions.
- Sparkling water premiumization:Urban professional segments seeking sugar-free alternatives present margin expansion potential distinct from commoditized still water categories.
Industry Challenges
- Food safety auditor scarcity:ISO 22000 and FSSAI-BIS dual certification requirements strain qualified inspector availability, extending facility approval timelines and delaying commercial launches.
- Cold chain last-mile fragmentation:India's ambient-temperature retail density and Indonesia's archipelago geography complicate temperature-controlled distribution for sensitive packaging formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bottled Water Market |
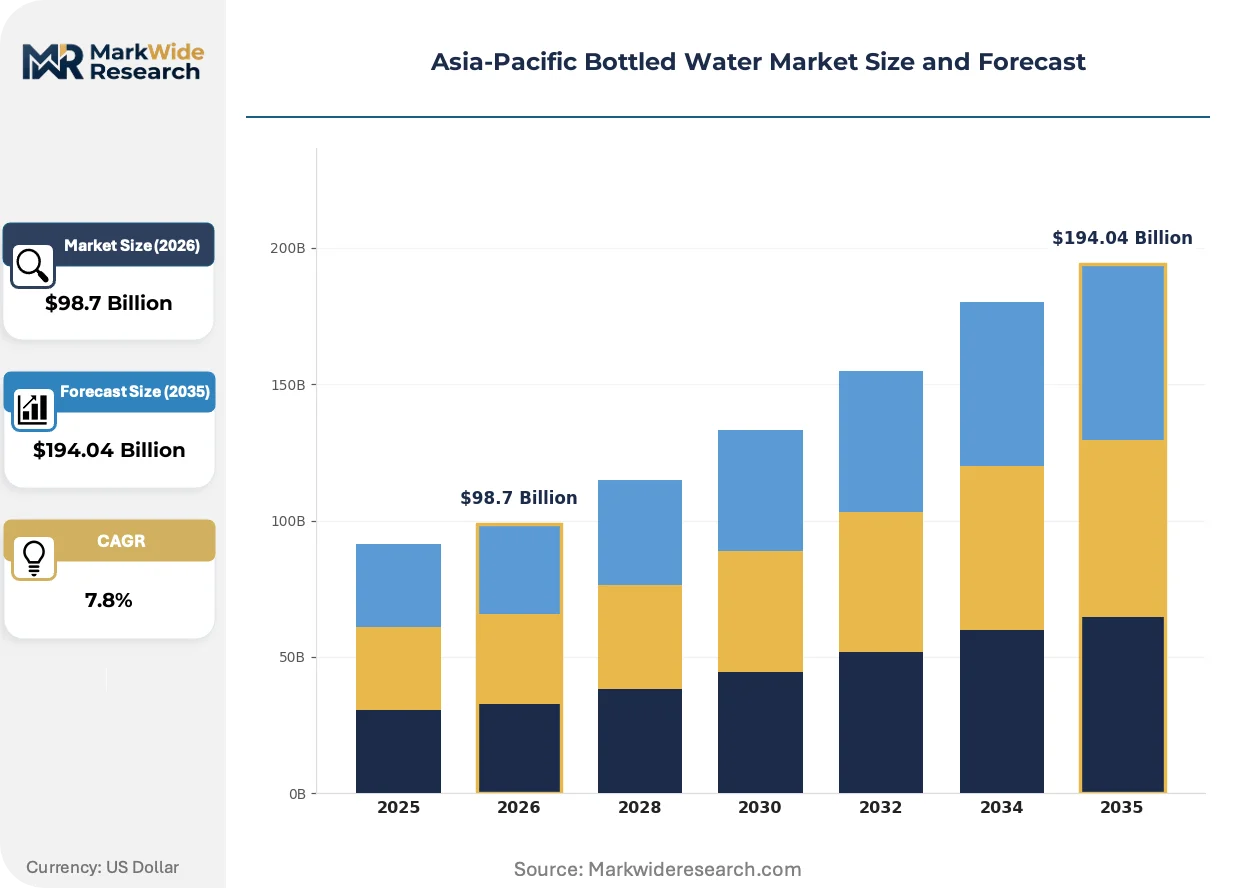
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $194.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water Packaging Type: PET Bottles, Glass Bottles, Cartons, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Households, Offices, Restaurants, Gyms |
| Companies Covered | The Coca-Cola Company, Tata Consumer Products Limited, Nestlé S.A., Bisleri International, Suntory Beverage & Food Ltd, Danone S.A., Nongfu Spring Co. Ltd, Asahi Group Holdings Ltd, PepsiCo Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bottled Water Market Strategic Shifts
Technology diffusion and regulatory tightening are actively restructuring production economics and competitive positioning across the Asia-Pacific bottled water sector, with implications for facility investment and channel access.
Aseptic bottling technology is bifurcating production capabilities across the sector. High-capacity rotary fillers with hydrogen peroxide sterilization enable ambient distribution of preservative-free products, compressing the shelf-life advantage traditionally held by regional players with refrigerated logistics. Japanese and South Korean manufacturers are deploying these systems fastest, while Indian and Indonesian bottlers face capex barriers to adoption.
China's GB standards for packaged drinking water are tightening contaminant thresholds for bromate and heavy metals, forcing treatment system upgrades among legacy operators. The industrial consequence is accelerated consolidation toward producers with captive laboratory testing and in-house ozonation capacity. Premium mineral water extraction permits in Yunnan and Jilin provinces face renewed scrutiny, advantaging incumbents with established geological assessments.
Subscription-based home and office delivery is displacing traditional retail replenishment cycles among India's urban households and China's tier-one apartment complexes. E-commerce platforms and dedicated delivery apps are capturing recurring revenue streams that supermarket and convenience store channels cannot match. This pattern is most visible in Bangalore, Mumbai, Shanghai, and Shenzhen, where logistics density supports same-day or scheduled delivery economics.
Asia-Pacific Bottled Water Market Segmentation
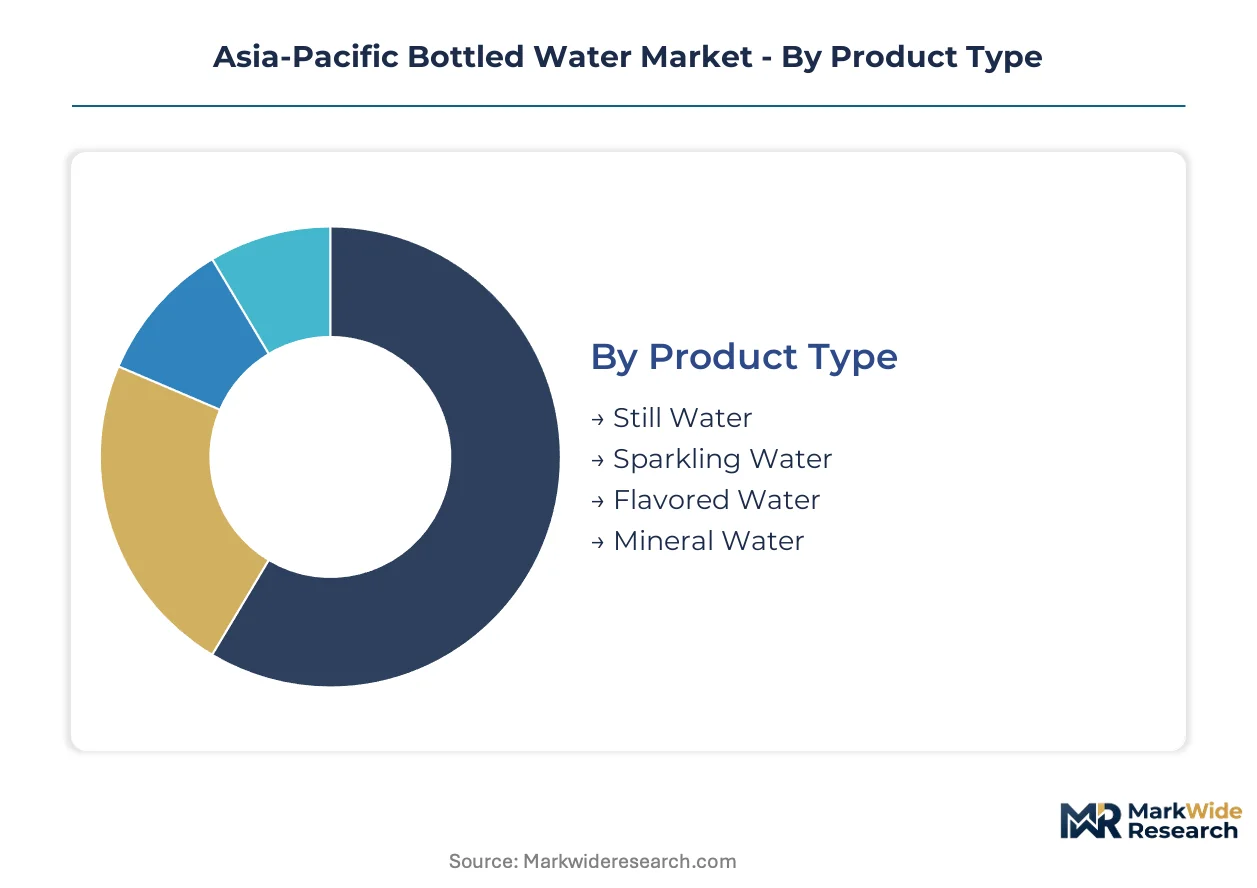
Segmentation in the Asia-Pacific bottled water market reveals distinct profit pools and regulatory exposure across product formats and channel structures. Manufacturers configure production assets and certification investments differently depending on which segments they target.
Product Type:
Still water dominates domestic consumption across China and India, while sparkling and mineral variants increasingly serve export-oriented premium positioning in Japan and South Korea.
- Still Water:Untreated or minimally treated potable water without carbonation, typically sourced from municipal supplies or shallow aquifers. Demand concentrates in China's eastern coastal provinces and India's Maharashtra-Gujarat corridor where municipal quality deficits drive household substitution. GB 19298 enforcement by SAMR is consolidating production toward certified operators with in-house laboratory capacity.
- Sparkling Water:Carbonated water with dissolved carbon dioxide, either naturally occurring or artificially injected. Urban professionals in Shanghai, Tokyo, and Seoul are displacing sugary beverages with this format, creating margin expansion distinct from commoditized still water. Japan's Ministry of Health, Labour and Welfare mineral content labeling rules shape import eligibility and product positioning.
- Flavored Water:Water with added natural or artificial flavoring agents and often sweeteners. Indonesia and Philippines bottlers are testing fruit-infused variants for younger demographics.
- Mineral Water:Water from protected underground sources with consistent mineral content, regulated as food products rather than beverages. Yunnan and Jilin province extraction permits face renewed MEE scrutiny.
Still water commands the established base. The steepest expansion runs through sparkling water.
Packaging Type:
Packaging economics divide sharply between high-volume PET logistics and emerging sustainable formats where regulatory pressure is rewriting cost structures.
- PET Bottles:Food-grade polyethylene terephthalate containers dominating mass-market distribution due to logistics efficiency and shatter resistance. Crude-linked resin price volatility transmits directly to margin structures for producers without long-term polymer supply contracts. China's eastern coastal bottlers maintain overwhelming volume share.
- Glass Bottles:Returnable and single-use glass containers for premium restaurant and hotel channels. HoReCa demand in Japan and South Korea sustains refillable systems with higher per-unit economics.
- Cartons:Paper-based laminated packaging with biodegradable coatings. Trials are accelerating ahead of anticipated single-use plastic restrictions.
- Pouches:Flexible laminated films with recycled content. Indonesia's archipelago geography complicates temperature-controlled distribution for this format.
PET bottles anchor current volume. Cartons are gaining share fastest as EPR frameworks advance.
Distribution Channel:
Channel access determines working capital intensity and customer acquisition economics, with digital platforms displacing traditional retail in dense urban clusters.
- Supermarkets:Large-format retail with shelf-space competition and promotional pricing. India's fragmented retail landscape concentrates modern trade in Mumbai and Bangalore.
- Convenience Stores:Small-footprint immediate-consumption outlets with premium pricing power. Japan's Lawson and 7-Eleven density supports impulse purchase patterns.
- Online Retail:E-commerce platforms and dedicated delivery apps capturing recurring revenue through subscription models. Tier-one Chinese apartment complexes and Indian urban households are shifting replenishment cycles away from physical retail.
- HoReCa:Hotels, restaurants, and catering channels with specification-driven procurement and long-term contracts. Mineral water positioning dominates this segment.
Supermarkets retain the volume base. Online retail shows the steepest expansion trajectory.
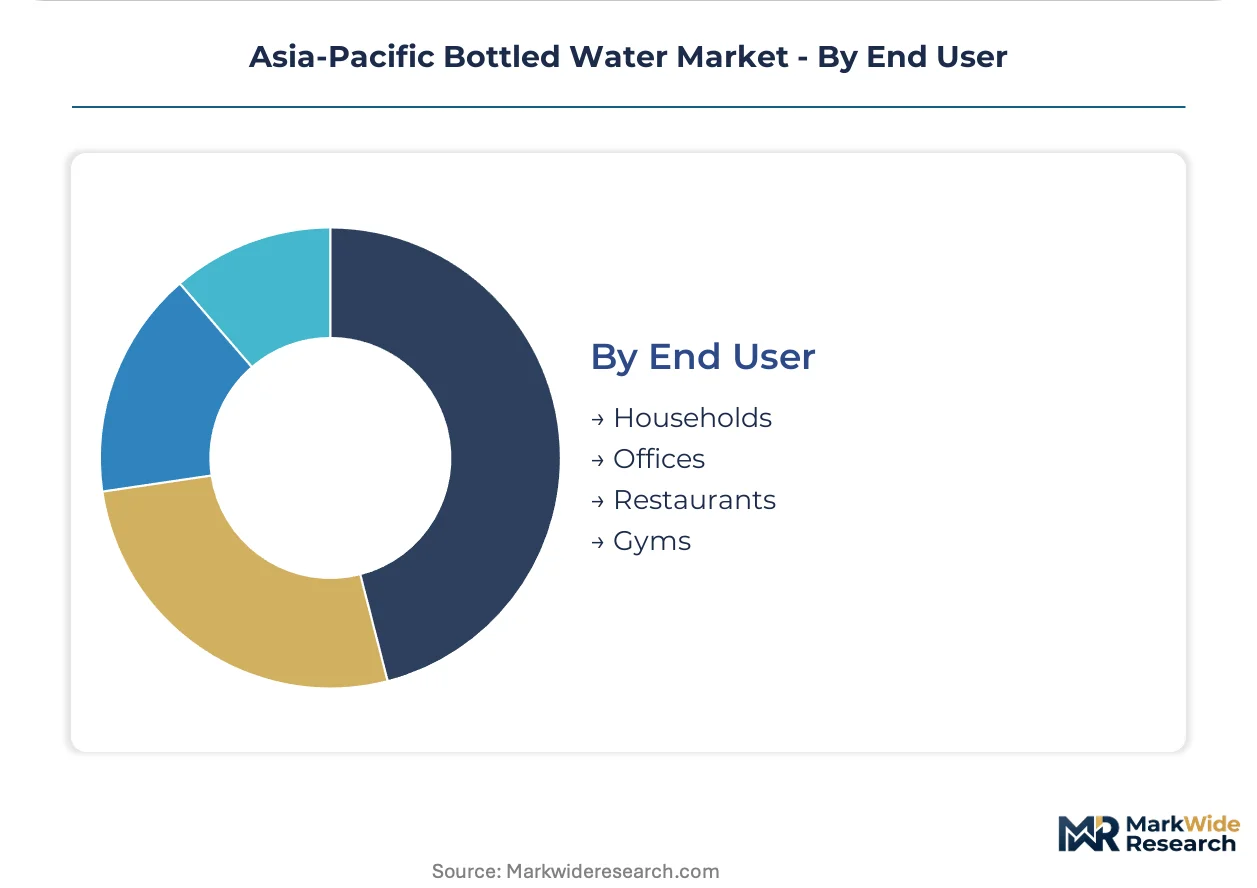
End User:
End-use segmentation maps directly to consumption occasion and pricing tolerance, with institutional buyers commanding different negotiation leverage than individual consumers.
- Households:Residential consumption for drinking, cooking, and hygiene purposes. Municipal water quality concerns in China's tier-one cities sustain category pull.
- Offices:Workplace hydration through bottled dispensers or individual containers. Subscription-based delivery is displacing traditional wholesale procurement in Bangalore and Shenzhen.
- Restaurants:Table service and kitchen use with brand visibility requirements. Glass bottle formats command positioning premiums.
- Gyms:Fitness center vending and membership-included hydration. Flavored water trials target post-workout recovery positioning.
Households represent the established demand base. Offices are expanding most quickly through platform-based subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's tightening GB 19298 standards and India's FSSAI-BIS certification mandates are redrawing production maps across the region. Urban households in water-stressed corridors sustain category pull as municipal quality deficits persist.
China
Tier-one city households substitute municipal supplies with packaged alternatives at accelerating rates. SAMR enforces stricter bromate and heavy metal thresholds under GB 19298, eliminating subscale operators. Production concentrates in eastern coastal provinces where laboratory-equipped facilities achieve compliance economies.
India
Maharashtra-Gujarat corridor households drive volume through fragmented retail networks. FSSAI mandates BIS certification for all commercial bottling, extending approval timelines and consolidating toward scaled manufacturers. Mumbai and Bangalore clusters see subscription delivery platforms displace traditional wholesale procurement.
Japan
Urban professionals in Tokyo and Osaka displace sugary beverages with carbonated alternatives. The Ministry of Health, Labour and Welfare enforces stringent mineral content labeling rules that shape import eligibility and product positioning. Kanto region manufacturers deploy aseptic rotary fillers fastest, compressing shelf-life advantages.
South Korea
Seoul Capital Area consumption shifts toward premium positioning amid HoReCa specification demands. Extended producer responsibility frameworks impose collection and recycling cost burdens on packaging economics. Busan-Ulsan manufacturers trial biodegradable cartons ahead of anticipated single-use plastic restrictions.
Indonesia
Jakarta and Surabaya households show underpenetration relative to China and India per-capita benchmarks. Archipelago geography complicates temperature-controlled distribution for sensitive packaging formats. Java-based bottlers test fruit-infused variants targeting younger demographics through modern trade channels.
Asia-Pacific Bottled Water Market Competitive Environment
Listed leaders compete with private specialists across certification access and mineral reserve control. The vendor base structures into three tiers: multinational beverage conglomerates with diversified portfolios, regional mineral water specialists with captive geological assets, and subscale local bottlers facing compliance-driven exit pressure. Dominant competitive moves include aseptic technology licensing partnerships and subscription platform acquisitions to secure recurring revenue streams.
Within the mineral reserve specialist tier, Nongfu Spring Co. Ltd and Tata Consumer Products Limited exemplify archetypes leveraging deep well-sourced geological positioning. Bisleri International occupies a position representing mass-market PET scale across fragmented Indian retail. These three anchors illustrate how certification compliance and distribution density separate sustainable operations from consolidation targets.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Tata Consumer Products Limited |
| Nestlé S.A. |
| Bisleri International |
| Suntory Beverage & Food Ltd |
| Danone S.A. |
| Nongfu Spring Co. Ltd |
| Asahi Group Holdings Ltd |
| PepsiCo Inc. |
| Others |
Value Chain & Pricing Dynamics
Biodegradable carton substitution for conventional PET is simultaneously redrawing sourcing geographies toward pulp-processing hubs and compressing margin structures for producers without long-term fiber supply contracts. This material transition intersects with extended producer responsibility frameworks to reshape where bottling economics remain viable.
Pricing Analysis
Certification level creates the primary spread between premium mineral water and mass-market still variants. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 compliance status, with FSSAI-BIS dual-certified Indian operators commanding shelf-space premiums over single-certified regional bottlers. Cost compression in the standard tier is intensifying because PET resin volatility transmits directly to packaging economics. Households in China's tier-one cities show lowest price sensitivity, while ambient-temperature retail purchasers in India's fragmented trade gravitate toward economy SKUs.
Supply Chain Analysis
Just-in-time resin procurement dominates among Japanese and South Korean manufacturers, while Chinese and Indian bottlers maintain strategic stockpiles against crude-linked feedstock volatility. Geographic supply concentration centers on China's eastern coastal provinces for PET resin processing, Indonesia for pulp-based carton trials, and Thailand for aseptic filling equipment manufacturing. Raw material dependencies draw from Saudi and Singaporean polymer feedstocks, Yunnan and Jilin mineral extraction permits, and Finnish pulp suppliers. Single-source vulnerability runs through groundwater licensing constraints imposed by China's MEE and India's state-level authorities. Distribution runs through platform-based subscription models in dense urban clusters and traditional wholesale networks in fragmented retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific bottled water sits in early-cycle expansion as municipal quality deficits in water-stressed urban corridors sustain category substitution at household level.
For Market Incumbents: Fortify compliance infrastructure against SAMR's tightening GB 19298 contaminant thresholds and FSSAI-BIS certification mandates. Incumbent producers should deepen captive laboratory capacity and in-house ozonation systems to eliminate subscale competitors. Channel control through subscription platform acquisitions protects recurring revenue streams as e-commerce displaces traditional retail replenishment cycles in Shanghai, Mumbai, and Bangalore clusters. For New Entrants and Emerging Players: Lead with biodegradable packaging trials in Japan and South Korea ahead of anticipated single-use plastic restrictions. Vietnam, Indonesia, and Philippines bottled water per-capita consumption trails China and India benchmarks, offering volume expansion for entrants with distribution scale. HoReCa mineral water specification in Seoul Capital Area presents premium positioning distinct from commoditized still water. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional bottlers facing ISO 22000 upgrade costs or exit pressure. Long-term viability over a five-to-ten year window favors scaled manufacturers with captive geological assessments and aseptic technology licensing partnerships. The signal to watch is groundwater extraction permit issuance rates by China's MEE and India's state-level authorities as inflection indicator for mineral-sourced capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Technology Licensing | Japanese rotary filler partnerships compress shelf-life advantages for Indian and Indonesian adopters. |
| Subscription Platform Acquisition | Recurring revenue capture in tier-one Chinese apartment complexes displaces wholesale procurement. |
| Biodegradable Packaging Trials | Carton and recycled-content pouch formats in Busan-Ulsan anticipate EPR framework acceleration. |
| Groundwater Permit Securement | Yunnan and Jilin extraction rights face renewed MEE scrutiny, advantaging established geological assessments. |
| Mineral Reserve Diversification | Himalayan-branded positioning competes with deep well-sourced reserves for premium HoReCa contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with bottling plant managers, FSSAI compliance officers, modern trade category buyers, and subscription platform operators; and secondary validation through SAMR GB standard filings, BIS certification registries, customs trade data, and Nielsen retail audit records. Bottom-up volume triangulation across product type, packaging format, and distribution channel intersected with top-down macroeconomic calibration.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, packaging material, distribution channel, and end-user occasion. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement intensity and technology diffusion curves. Forecast inputs incorporated groundwater licensing approval timelines, PET resin price volatility bands, and aseptic bottling adoption rates by manufacturing cluster.
Forecasts assume regulatory continuity in China's SAMR enforcement posture and India's FSSAI-BIS certification mandates; material policy shifts would require re-modeling. Revision becomes warranted when groundwater extraction permit issuance rates or extended producer responsibility cost burdens cross thresholds that alter facility economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Low Calorie RTD Beverages Market
Beverages
Global Fruit Juice Concentrate Market
Beverages
Hot Chocolate Market
Beverages
Sparkling Juice Drinks Market
Beverages
Ready to Drink Margarita Market
Beverages
South America Bottled Water Market
Beverages
South America Ready to Drink Beverages Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Spring Water Market
Beverages
Oat Based Beverages Market
Beverages
Sports Drink Market
Beverages
Caffeinated Beverage Market
Beverages
NFC JUICE Market
Beverages
Commercial Drink Mixers Market
Beverages
Fermented Foods and Beverages Market
Beverages
Global Soft Drinks Concentrate Market