
 Citrus Water Market | 2026-2036
Citrus Water Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Water Market Outlook
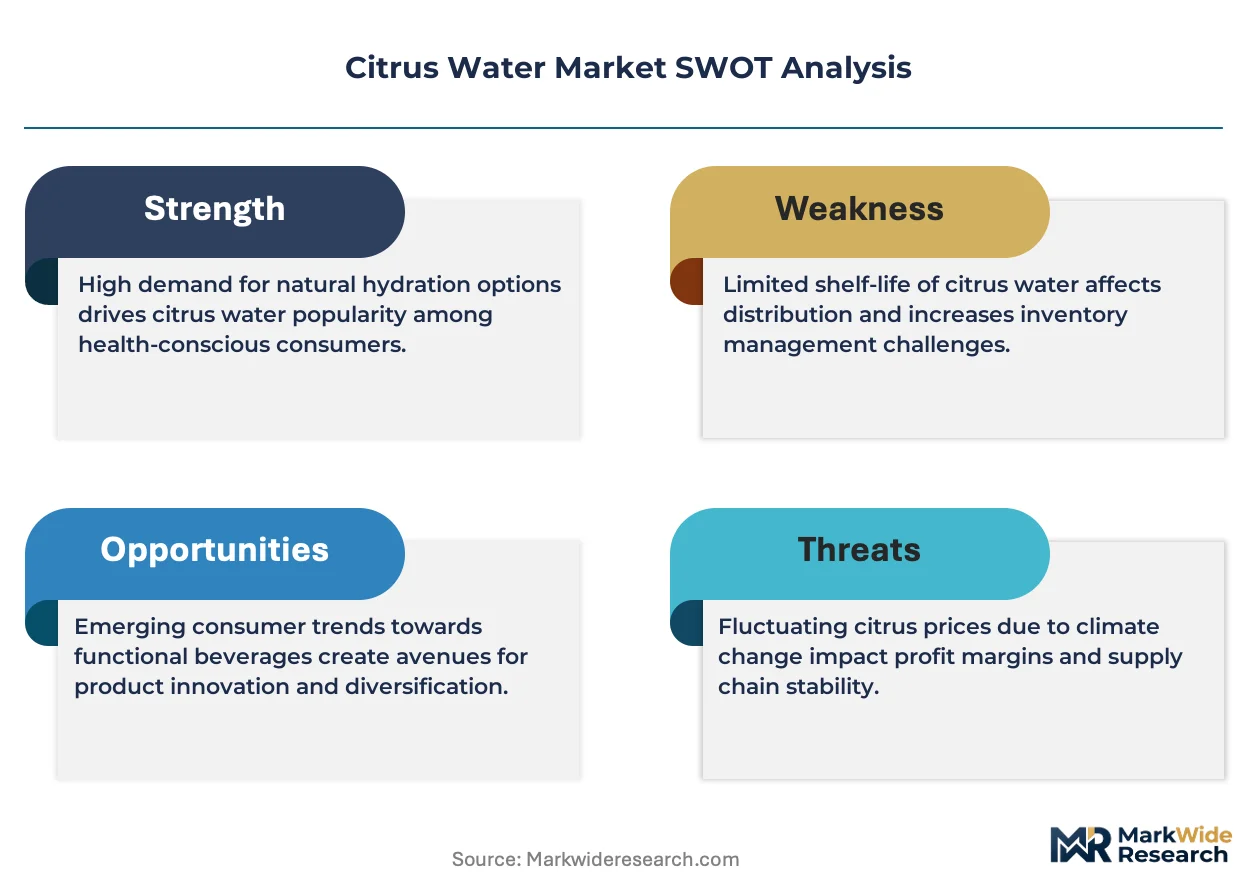
E-commerce platforms is rewriting how citrus water reaches health-conscious consumers, bypassing traditional grocery gatekeepers to build direct brand relationships. PepsiCo leverages its North American bottling network to sustain shelf dominance in convenience retail. Nestlé S.A. anchors European premium positioning through mineral water heritage brands extended into citrus variants. Danone S.A. competes in functional hydration by specializing in low-sugar formulations that target gym and café channels.
Citrus water denotes non-carbonated or lightly carbonated beverages infused with natural citrus extracts, typically containing zero to trace calories, pH-balanced between 3.0 and 4.5, and preserved through flash pasteurization or cold aseptic filling to maintain volatile aromatic compounds. The product serves commercial and institutional buyers seeking alternatives to sugar-sweetened beverages without sacrificing flavor complexity. Lemon variants occupy the largest volume share due to consumer familiarity and perceived detoxification associations, while grapefruit formulations command premium pricing in health stores where bioactive compound claims differentiate shelf positioning. Bottle packaging dominates value capture across supermarkets and convenience stores, though pouches are gaining traction in gym channel vending where portability dictates purchase behavior.
The FDA governs nutrition labeling and health claims for citrus water sold in the United States, while the EPA regulates source water quality standards that constrain supply security for bottlers dependent on municipal or spring inputs. EFSA in Europe enforces stricter additive thresholds that shape reformulation decisions for exporters seeking CE-marketed distribution. Stakeholders must monitor evolving sugar-tax legislation across multiple state and national jurisdictions, as these fiscal mechanisms are accelerating consumer migration from sweetened soft drinks to unsweetened citrus alternatives.
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing bottlers to strip artificial sweeteners and pivot toward natural citrus extracts, compressing reformulation timelines and reshaping supplier relationships across the value chain.
Growth Catalysts
- Zero-calorie gym channel demand:Health-conscious consumers in fitness centers are pulling unsweetened citrus variants into vending machines, displacing traditional sports drinks.
- EPA source water standards:Stricter municipal and spring water quality mandates are accelerating investment in filtration infrastructure that supports premium positioning.
- Cold aseptic filling:This preservation technology is unlocking extended shelf life without thermal degradation of volatile aromatic compounds.
Market Restraints
- Citrus extract supply volatility:Weather-dependent harvests in Florida and Brazil create input cost swings that squeeze margin structures.
- Spring water source concentration:Bottlers dependent on specific aquifer regions face supply security risks from drought and competing municipal withdrawals.
- Substitution by tap filtration:Home carbonation and countertop filtration systems are capturing price-sensitive households seeking flavored hydration.
Strategic Opportunities
- Underpenetrated German gym chains:Functional beverage culture in fitness centers lags US penetration, creating whitespace for low-sugar entrants.
- E-commerce subscription models:Direct-to-consumer platforms are bypassing grocery slotting fees and capturing recurring revenue from health-conscious households.
- EU Green Deal packaging mandates:Biodegradable bottle requirements are rewarding early movers with premium shelf placement and reduced compliance costs.
Industry Challenges
- Flash pasteurization technician scarcity:Specialized operators who maintain volatile compound integrity through thermal processing are concentrated among legacy beverage engineers.
- Multi-jurisdiction sugar-tax navigation:Bottlers face fragmented state and national fiscal regimes requiring SKU proliferation and label complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Water Market |
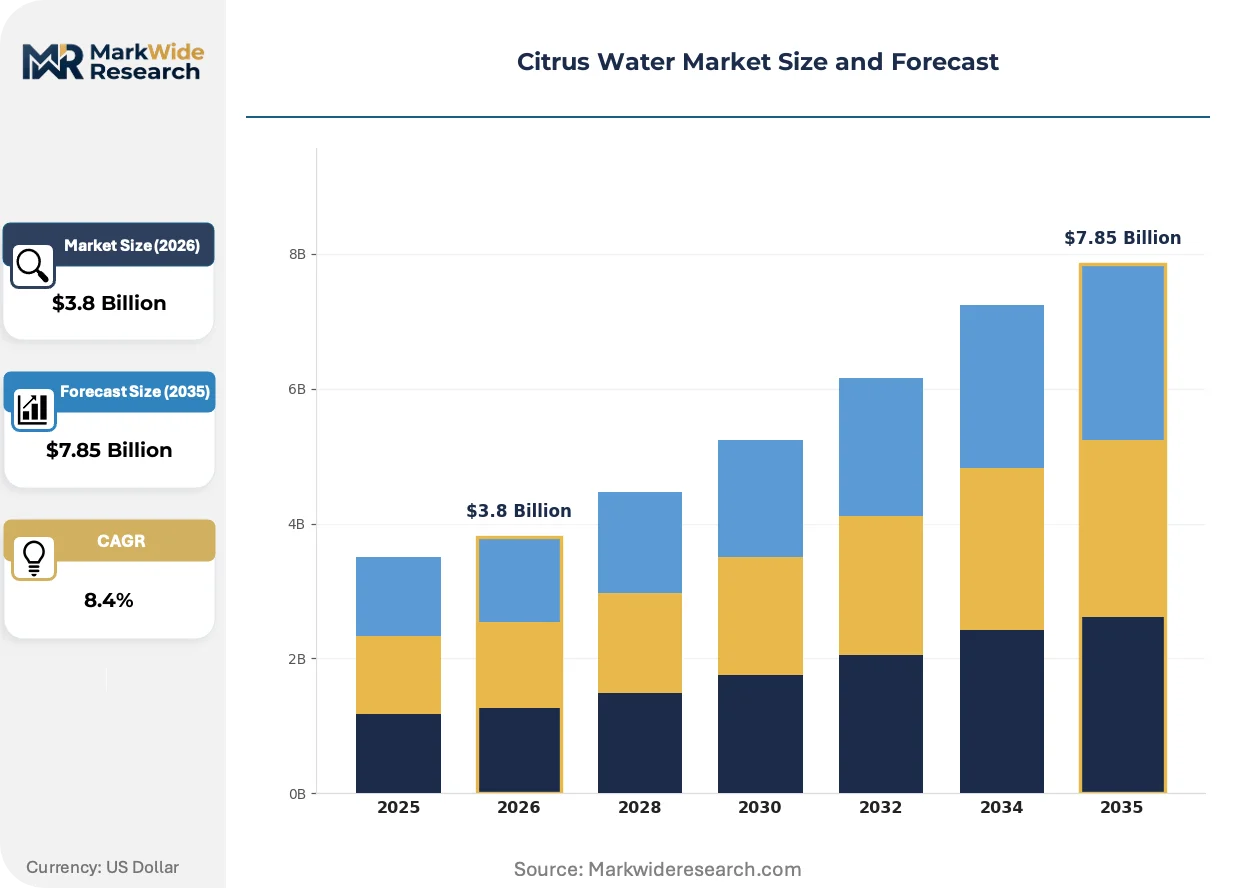
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lemon, Orange, Grapefruit, Lime Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Stores End User: Households, Restaurants, Cafés, Gyms Packaging Type: Bottle, Carton, Can, Pouch |
| Companies Covered | PepsiCo Inc, The Coca-Cola Company, Nestlé S.A., Danone S.A., Keurig Dr Pepper, Suntory Beverages & Food Ltd, Hint Inc., CORE Nutrition LLC, Mountain Valley Spring Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Water Market Strategic Shifts
Reformulation science and channel disintermediation are converging to compress traditional beverage value chains, with technology and regulation jointly dictating competitive survival.
Cold aseptic filling lines are collapsing the trade-off between shelf stability and flavor fidelity that previously forced thermal pasteurization compromises. Mid-sized regional bottlers are adopting this capital-intensive technology to compete against national brands on taste differentiation. The result is collapsing batch-size economics that enable localized citrus sourcing without scale penalties.
EFSA's stricter additive thresholds are reshaping European export formulations, forcing US bottlers to strip synthetic preservatives from cross-border SKUs. This regulatory friction is compressing product line complexity as manufacturers converge on clean-label recipes acceptable in multiple jurisdictions. German and French health stores are responding by prioritizing CE-marked citrus waters with explicit bioactive compound disclosures.
Gym vending procurement is consolidating around single-source beverage contracts that bundle hydration, protein, and recovery SKUs. This buyer concentration is squeezing standalone citrus water brands into co-packing arrangements or exclusive distribution pacts. The shift is most visible in US metropolitan fitness chains where procurement directors now mandate portfolio breadth over single-category excellence.
Citrus Water Market Segmentation
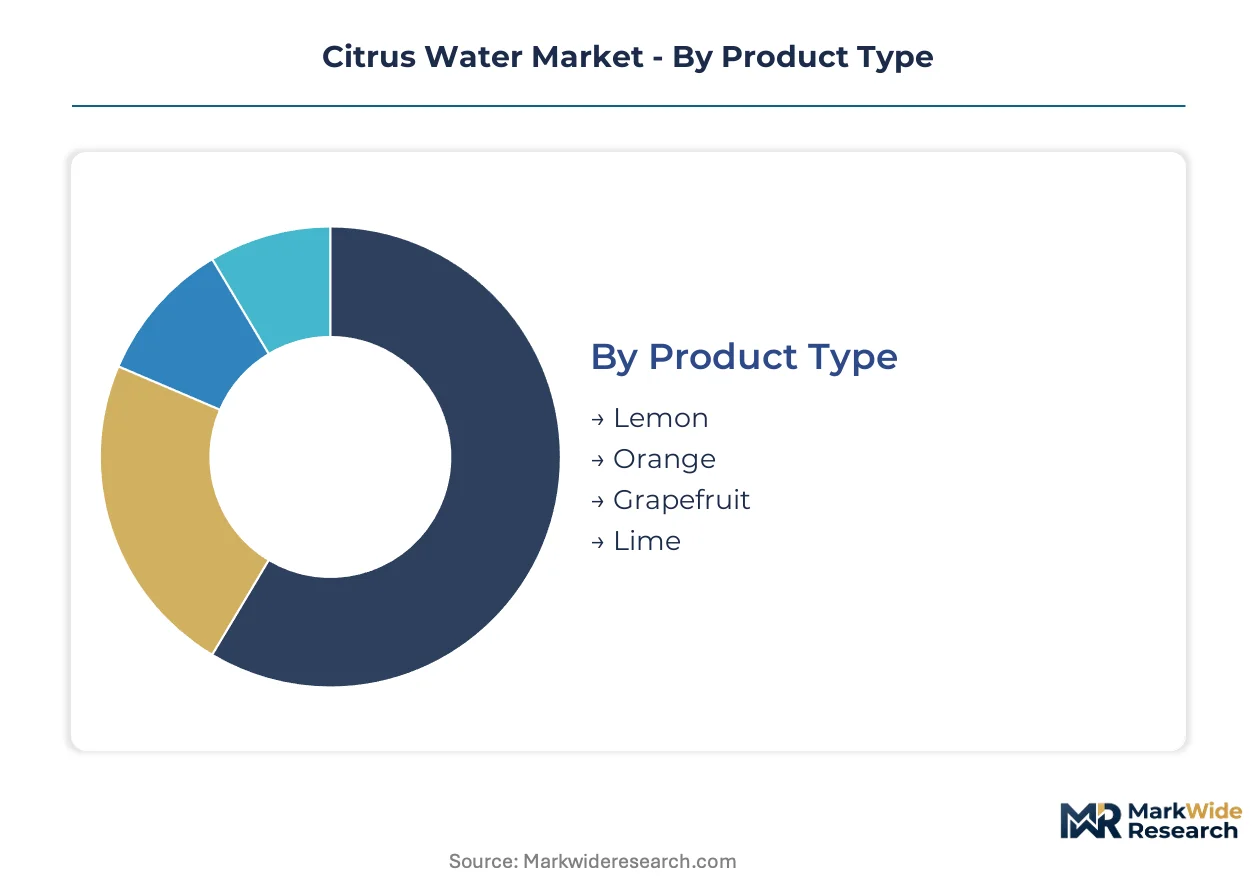
Citrus water segmentation reveals how formulation chemistry, channel economics, and consumption rituals intersect to create distinct profit pools. Understanding these divides exposes where formulation investments concentrate and where channel power reshapes margin capture.
Product Type:
The use-case spectrum spans detoxification rituals to functional bioactive consumption, with flavor familiarity and health claims driving divergent price positioning.
- Lemon:Zero-to-trace calorie formulations with pH 3.0-3.5 balance dominate volume through detoxification associations and palate familiarity. Demand concentrates in US supermarkets where health-conscious households stock daily hydration alternatives. FDA labeling clarity on added sugars accelerates reformulation toward natural extract bases.
- Grapefruit:Bioactive compound claims around naringin and limonoids command premium shelf positioning in health stores. German and French retailers prioritize CE-marked variants with explicit compound disclosures per EFSA additive thresholds. Cold aseptic filling preserves volatile aromatic integrity that thermal pasteurization degrades.
- Orange:Milder acidity profiles suit children's consumption and family household stocking patterns.
- Lime:Cocktail culture and mixology applications drive restaurant and café channel placement.
Established volume favors Lemon; emerging adoption favors Grapefruit.
Distribution Channel:
Cost tier stratification separates slotting-fee heavy retail from direct-margin digital platforms.
- Online Retail:Subscription models bypass grocery gatekeepers to capture recurring revenue through direct brand relationships. E-commerce platforms enable flavor customization and bulk purchasing that health-conscious households favor. Cold chain logistics investments protect volatile compound integrity through last-mile delivery.
- Supermarkets:Shelf dominance depends on bottler network scale and promotional fund depth. US volume concentrates here where lemon variants occupy end-cap positioning during resolution-season demand spikes.
- Convenience Stores:Impulse purchase velocity rewards single-serve bottle formats with grab-and-go accessibility.
- Health Stores:Bioactive disclosure requirements and premium pricing tolerance attract grapefruit and functional variant placement.
Margin concentration sits with Online Retail; volume scale sits with Supermarkets.
End User:
Application context reshapes formulation priorities from hydration efficiency to ritual enhancement.
- Gyms:Zero-calorie demand pulls unsweetened citrus variants into vending machines, displacing traditional sports drinks. Procurement consolidation around single-source beverage contracts bundles hydration with protein and recovery SKUs. Flash pasteurization technician scarcity constrains localized supply expansion.
- Households:Daily consumption rituals favor multi-pack bottle purchases with refrigerator-friendly formats. Home carbonation systems threaten price-sensitive segments through countertop filtration substitution.
- Restaurants:Table service integration demands glass-compatible presentation and mixology versatility.
- Cafés:Low-sugar formulations align with wellness-positioned beverage menus in urban metropolitan chains.
Procurement power concentrates in Gyms; purchase frequency concentrates in Households.
Packaging Type:
Customer mobility requirements and shelf-life engineering create divergent material specifications.
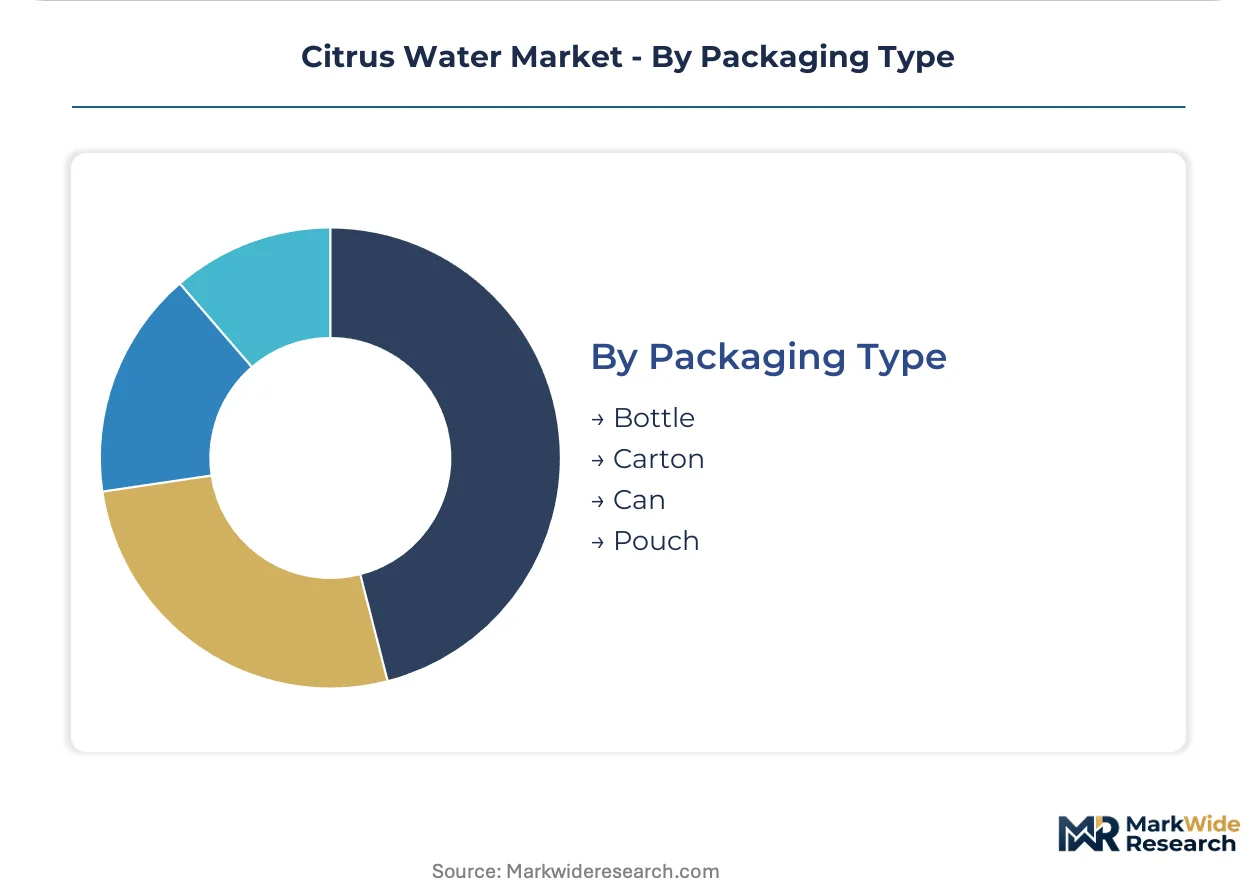
- Bottle:PET and rPET formats dominate value capture across supermarkets and convenience stores through established recycling infrastructure. EU Green Deal packaging mandates reward biodegradable bottle early movers with reduced compliance costs. Extended shelf life from cold aseptic filling justifies premium positioning.
- Pouch:Flexible formats gain traction in gym channel vending where portability dictates purchase behavior and bag-friendly profiles matter.
- Carton:Aseptic brick formats suit foodservice bulk dispensing and institutional cafeteria applications.
- Can:Aluminum formats target outdoor recreation and beach consumption contexts where breakage resistance matters.
Current infrastructure favors Bottle; format innovation favors Pouch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium shelf positioning in German health stores commands 40% price premiums over US supermarket equivalents, while Brazilian bottlers absorb volatile citrus extract costs that compress margin structures. This pricing-power asymmetry shapes where multinational players allocate reformulation investments and cold aseptic filling capacity.
United States
Fitness center vending procurement concentrates demand for zero-calorie lemon variants in metropolitan gym chains across California and Texas. The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing bottlers to strip artificial sweeteners and pivot toward natural citrus extracts. PepsiCo leverages its North American bottling network to sustain shelf dominance in convenience retail throughout the Southeast and Midwest corridors.
Germany
Health-conscious consumers in Berlin and Munich fitness centers are driving adoption of unsweetened citrus variants with explicit bioactive compound disclosures. EFSA enforces stricter additive thresholds that shape reformulation decisions for exporters seeking CE-marketed distribution. Danone S.A. competes in functional hydration by specializing in low-sugar formulations that target gym and café channels in the Rhine-Ruhr industrial cluster.
Brazil
Weather-dependent orange harvests in São Paulo state create input cost swings that squeeze margin structures for regional bottlers. The country's national food safety regulator monitors source water quality standards that constrain supply security for bottlers dependent on municipal inputs. Citrus extract supply volatility from Florida and Brazilian growing regions forces reformulation timelines that reshape supplier relationships across the value chain.
Japan
Metro Tokyo and Osaka consumers favor mildly carbonated grapefruit formulations with premium positioning in convenience retail channels. METI standards influence packaging material specifications that reward biodegradable bottle early movers with reduced compliance costs. Suntory Beverages & Food Ltd anchors market presence through mineral water heritage brands extended into citrus variants for the Kanto and Kansai regional markets.
United Kingdom
London health stores and metropolitan café channels prioritize CE-marked citrus waters with clean-label recipes acceptable across multiple European jurisdictions. The country's national environmental regulator enforces packaging waste directives that accelerate migration from single-use plastics. Nestlé S.A. extends European premium positioning through established mineral water distribution networks serving Greater London and the Southeast economic corridor.
Citrus Water Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The citrus water market structures around three tiers: multinational beverage conglomerates with North American bottling networks, European mineral water heritage houses, and mid-sized functional hydration specialists. Consolidation pressure concentrates procurement power in gym vending and supermarket slotting negotiations. Dominant competitive moves include portfolio diversification into zero-calorie variants and geographic expansion through co-packing arrangements in underpenetrated European fitness channels.
Among multinational platform players, PepsiCo Inc and The Coca-Cola Company exemplify scale-driven shelf dominance through established convenience retail networks. Nestlé S.A. and Danone S.A. occupy positions within the European heritage tier, leveraging mineral water brand equity for premium citrus variant extension. Hint Inc. and CORE Nutrition LLC represent the functional specialist archetype, targeting health-conscious households through direct-to-consumer channels and gym vending procurement consolidation.
| Leading Market Players |
|---|
| PepsiCo Inc |
| The Coca-Cola Company |
| Nestlé S.A. |
| Danone S.A. |
| Keurig Dr Pepper |
| Suntory Beverages & Food Ltd |
| Hint Inc. |
| CORE Nutrition LLC |
| Mountain Valley Spring Company |
| Others |
Value Chain & Pricing Dynamics
São Paulo state citrus belt capacity swings directly determine downstream pricing power for Brazilian extract suppliers serving North American bottlers. Weather-induced harvest volatility in Florida and Brazil creates input cost asymmetries that compress margin structures for regional processors while rewarding diversified sourcing networks.
Pricing Analysis
Configured-to-order grapefruit formulations with explicit bioactive compound disclosures command substantial premiums over standard lemon variants in German health stores. Three-tier pricing structure across premium, standard, and economy levels separates cold aseptic-filled products from flash-pasteurized alternatives from thermally processed entries. Cost compression in economy tiers is intensifying because home carbonation systems capture price-sensitive households. Gym vending procurement shows lowest price sensitivity; supermarket multi-pack buyers exhibit highest.
Supply Chain Analysis
Export-control regimes on cold aseptic filling technology limit equipment flows to mid-sized regional bottlers seeking taste differentiation capabilities. Geographic supply concentrates in Brazil, Florida, and Mediterranean growing regions for citrus extract inputs. Raw material dependencies span orange and lemon harvests, spring water aquifer access, and aseptic packaging films. Single-source vulnerability runs through Florida citrus belt concentration exposed to hurricane disruption. Distribution runs through PepsiCo and Coca-Cola bottling networks dominating convenience retail shelf access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against home carbonation and countertop filtration systems capturing daily hydration rituals. Incumbents must navigate this threat while consolidating procurement power in gym vending consolidation.
For Market Incumbents: Insulate market position through backward integration into Brazilian citrus extract processing to secure supply against Florida weather volatility. Anchor capacity in Rhine-Ruhr industrial cluster to serve underpenetrated German gym chains before competitors establish presence. Cold aseptic filling technician scarcity represents critical capability gap requiring training pipeline investment. For New Entrants and Emerging Players: Establish a beachhead in e-commerce subscription models bypassing grocery slotting fees that exclude capital-light competitors. Target gym vending procurement consolidation with bundled hydration-protein-recovery portfolios meeting single-source contract requirements. Direct-to-consumer flavor customization captures health-conscious households seeking personalized hydration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among functional hydration specialists with established subscription bases and gym vending exclusivity. Long-term viability across the analysis window favors mid-sized regional bottlers owning cold aseptic capacity and localized citrus sourcing relationships. Acquisition target archetype: European mineral water heritage houses with premium extension potential. Signal to watch: EFSA additive threshold tightening accelerating clean-label convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Aseptic Filling Adoption | Preserves volatile aromatic compounds that thermal pasteurization degrades, enabling taste differentiation. |
| Backward Integration into Extract Processing | Secures supply against Florida and Brazilian harvest volatility squeezing margin structures. |
| E-Commerce Subscription Launch | Bypasses grocery slotting fees while capturing recurring revenue from health-conscious households. |
| EU Green Deal Packaging Compliance | Rewards biodegradable bottle early movers with premium shelf placement and reduced compliance costs. |
| Gym Vending Portfolio Bundling | Meets procurement consolidation demands for single-source hydration-protein-recovery contracts. |
Study Parameters
Cross-validation between bottler procurement interviews and retail audit data anchors the qualitative findings in observable channel behavior. Primary interviews with beverage R&D directors, gym chain procurement managers, flavor house technical leads, and cold aseptic equipment suppliers combined with secondary validation from FDA filings, EFSA additive threshold documentation, Nielsen retail audit data, and customs import records. Bottom-up volume triangulation against top-down value estimates ensures segment-level consistency.
Calibration against historical growth patterns in functional beverage categories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include flavor chemistry, distribution channel economics, end-use application context, and packaging material specifications. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated gym vending procurement consolidation velocity and EFSA clean-label threshold evolution.
Stress conditions across citrus harvest volatility, spring water aquifer withdrawal limits, and sugar-tax legislative expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cold aseptic filling adoption rates and e-commerce penetration trajectories. Material shifts in FDA added-sugar labeling enforcement or EU Green Deal packaging mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Packaged Coconut Water Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
Bottled Beverages Market
Beverages
Sparkling Water Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
United States Soy Beverages Market
Beverages
Drinking Water Market
Beverages
Europe Coconut Water Market
Beverages
Apple Juice Concentrate Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Collagen Drinks Market
Beverages
Electrolyte Mixes Market
Beverages
South East Asia Bottled Water Market
Beverages
Fermented Drinks Market
Beverages
GCC Coconut Water Market