
 Fruit Juice Market | 2026-2036
Fruit Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Juice Market Intelligence
The European Union's mandatory front-of-pack nutritional labeling, under its Farm to Fork strategy, is realigning the cost-of-entry calculus for juice manufacturers. PepsiCo's Tropicana brand leverages its vast distribution network to introduce reformulated, lower-sugar options globally. Innocent differentiates through its brand identity centered on natural ingredients and ethical sourcing. In Japan, Kagome specializes in vegetable-fruit blends, capturing a niche of health-focused consumers.
Fruit juice is a non-fermented, potable liquid obtained from the edible part of sound, mature fruits. Products are often defined by their processing method, such as high-pressure processing for cold-pressed juices to retain nutrients, or flash pasteurization for extended shelf life. The cold-pressed product type represents a high-margin, premium category, while from-concentrate juices command the largest volume share. Supermarkets remain the dominant distribution channel, though online retailers are expanding rapidly, altering traditional supply chains.
The U.S. FDA enforces strict labeling rules regarding juice content percentages and health claims. In India, the FSSAI sets standards for fruit juice quality and safety, while the global Codex Alimentarius provides a benchmark for international trade. Producers must now decide whether to invest in reformulation for low-sugar variants or focus on premium, unprocessed categories to maintain margins.
Market Dynamics
The fruit juice market is defined by a structural tension between consumer demand for natural, unprocessed products and regulatory pressures for lower sugar content. This dynamic forces producers to innovate in both formulation, as seen with the EU's labeling rules, and processing technology.
Growth Catalysts
- Health and Wellness Policies:Government initiatives promoting healthier diets in schools and public institutions create a captive market for 100% fruit juices as alternatives to sugar-sweetened carbonated beverages.
- Processing Advancements:The adoption of High-Pressure Processing (HPP) allows for the creation of premium, cold-pressed juices with longer shelf lives and better nutrient retention, appealing to health-conscious consumers.
- Shifting Consumer Preferences:In emerging economies like India, a growing middle class is moving away from traditional sodas towards packaged juices, perceived as a healthier and more convenient beverage choice.
Market Restraints
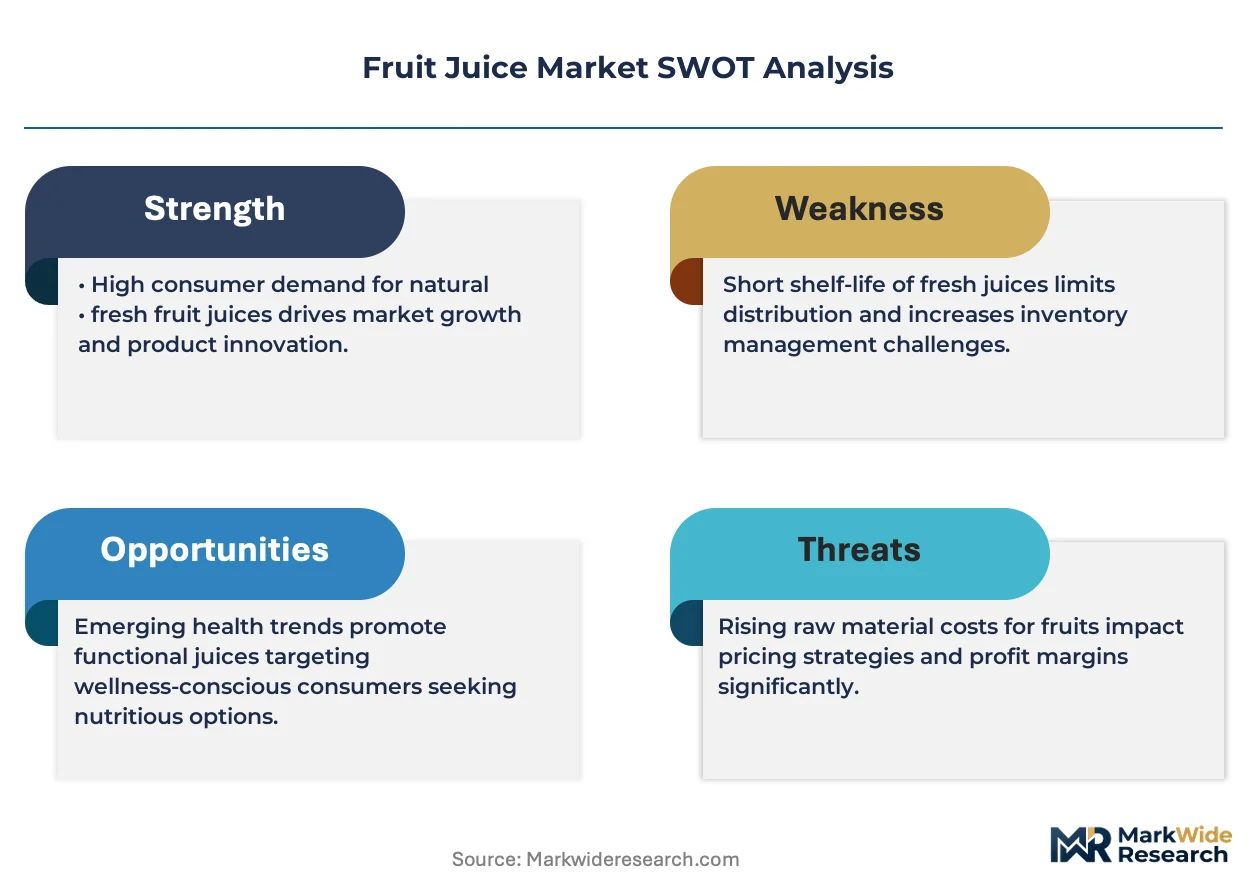
- Input Cost Volatility:Fruit prices are subject to significant fluctuations due to climate change, disease, and geopolitical factors, which directly impacts production costs and margin stability for juice manufacturers.
- Threat of Substitution:The market faces intense competition from a widening array of beverage categories, including functional waters, ready-to-drink teas, and plant-based milks, which often have a lower sugar profile.
- Regulatory Scrutiny on Sugar:Regulations such as the UK's sugar tax and mandatory front-of-pack labeling in the EU increase compliance costs and can negatively impact the perception of even 100% fruit juices.
Strategic Opportunities
- Functional Juice Blends:There is a significant opportunity in developing juices fortified with functional ingredients like probiotics, vitamins, and adaptogens, catering to consumer interest in personalized nutrition and wellness.
- Geographic Expansion:Underpenetrated markets in Southeast Asia and Africa present white-space opportunities for both premium and mass-market juice products as disposable incomes and urbanization rates increase.
- Direct-to-Consumer Channels:Subscription-based D2C models for fresh, cold-pressed juices allow brands to bypass traditional retail, build direct customer relationships, and capture higher margins.
Industry Challenges
- Cold Chain Complexity:Maintaining the integrity of the cold chain for unpasteurized, high-premium juices from production to consumer is capital-intensive and logistically complex, posing a barrier to entry.
- Fragmented International Standards:Manufacturers must navigate a complex web of differing food safety and labeling standards between regulatory bodies like the U.S. FDA, the EU's EFSA, and India's FSSAI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Juice Market |
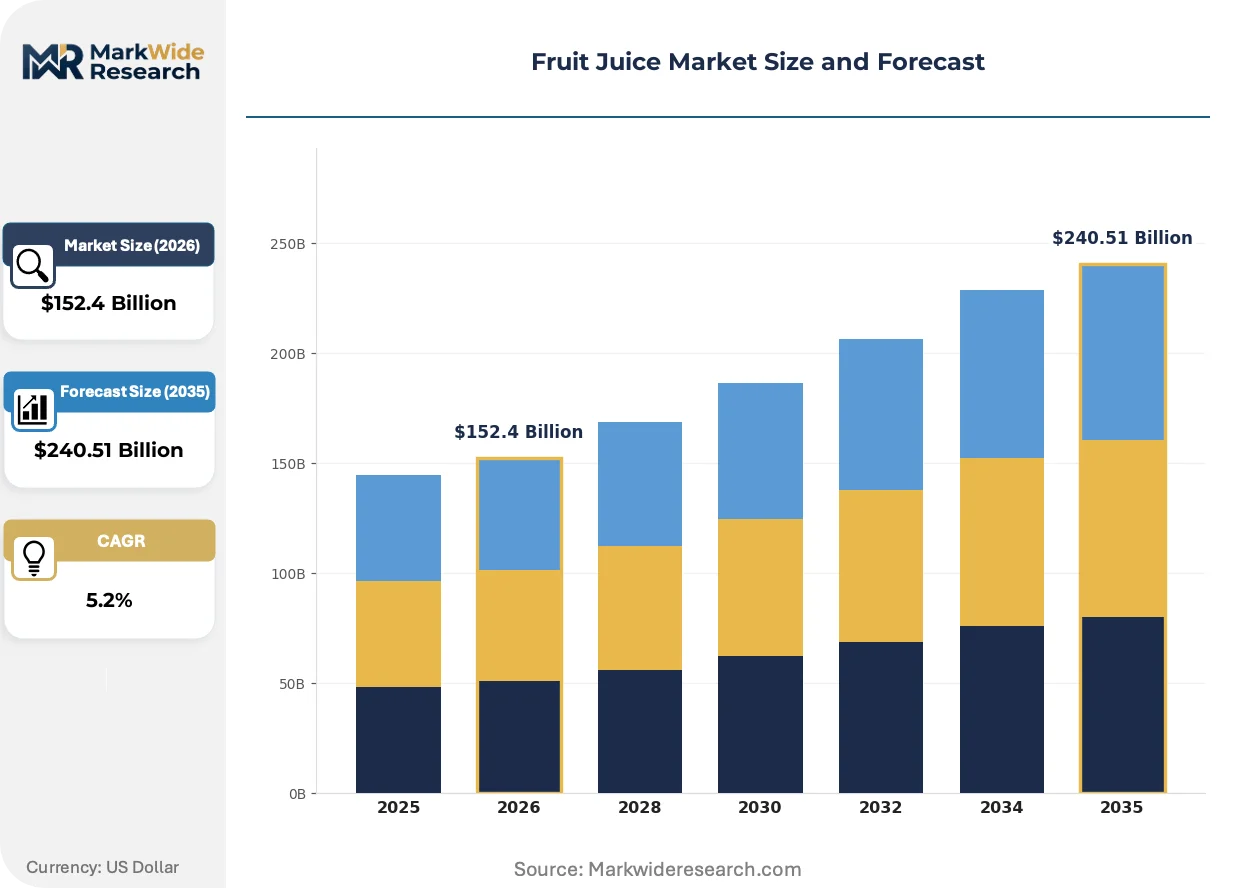
| Market Size in 2026 | $152.4 Billion |
| Market Size in 2035 | $240.51 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Concentrate, From Fresh, Organic, Fortified Packaging Type: Carton Pack, Glass Bottle, PET Bottle, Tetra Pak, Pouch Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale, Specialty Stores End User: Household Consumers, Foodservice Providers, Institutional Buyers, Fitness Centers |
| Companies Covered | Del Valle, Tropicana, Innocent, Coca-Cola, PepsiCo, Kagome, Robinsons, Keurig Dr Pepper, Minute Maid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Juice Market Strategic Shifts & Innovations
Product innovation is bifurcating the market into two distinct paths: low-sugar reformulations for the mass market and minimally processed, high-nutrient products for the premium segment. This divergence is driven by technology advancements and evolving health perceptions among consumers.
High-Pressure Processing (HPP) is a non-thermal pasteurization method that preserves the sensory and nutritional profile of fresh juice. Premium juice brands are rapidly adopting HPP for their cold-pressed lines to extend shelf life without heat. This technology is modularizing production, enabling manufacturers to run distinct high-margin, 'fresh' product tiers alongside traditional pasteurized offerings from the same facility.
The European Union's Farm to Fork strategy mandates front-of-pack nutritional labeling, directly influencing product design. This regulation compels manufacturers to lower sugar content to achieve more favorable consumer-facing scores. The 100% juice category is particularly affected, accelerating the shift toward vegetable-fruit blends and formulations using naturally lower-sugar fruits.
Consumer purchasing behavior is evolving from weekly bulk buys at supermarkets to on-demand and subscription-based models. This change is disrupting traditional retail channels, with direct-to-consumer (DTC) brands building loyal followings for premium and customized juice products. The shift is most pronounced in dense urban centers across North America and Western Europe, where convenience and freshness are primary purchase drivers.
Fruit Juice Market Segmentation
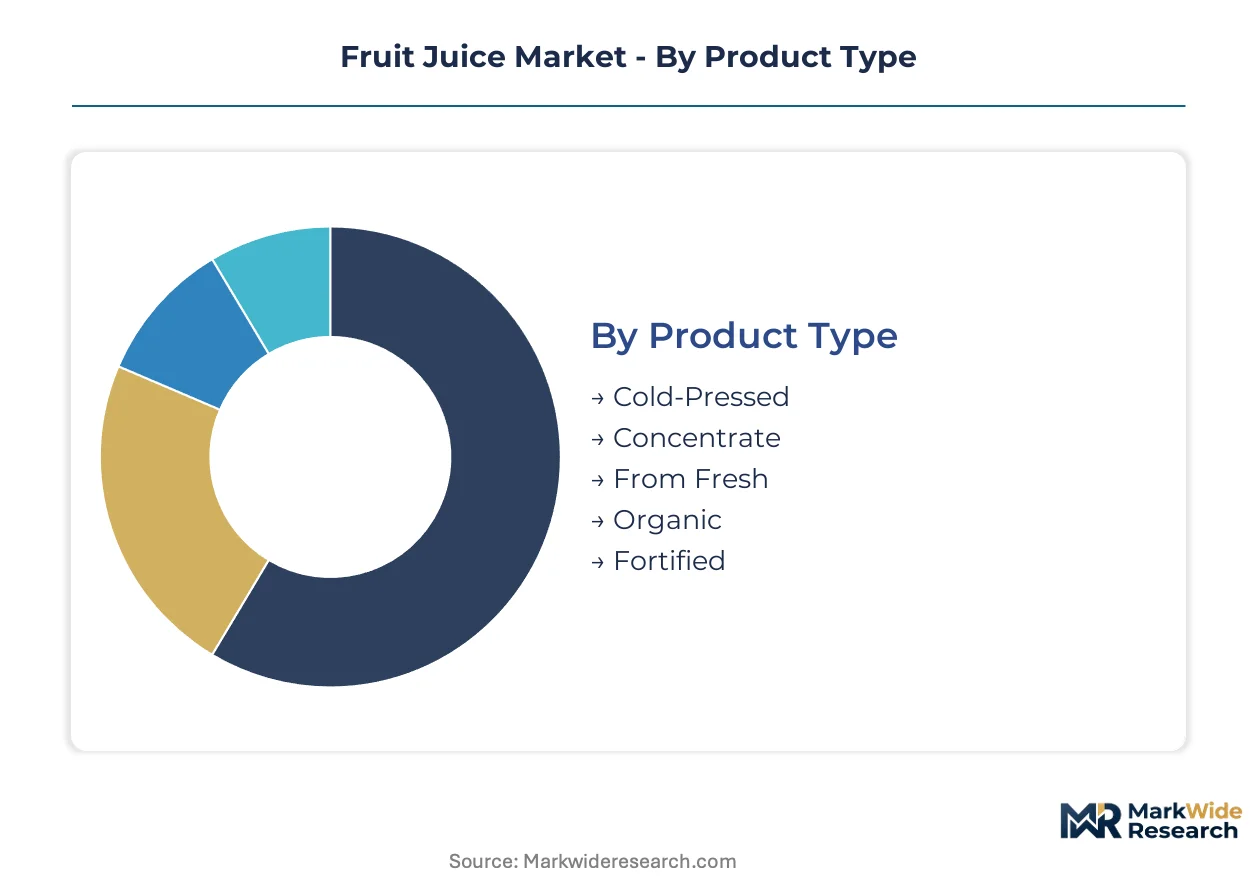
The fruit juice market exhibits diverse segmentation, reflecting varied consumer preferences, processing methods, and distribution strategies. Understanding these distinct categories provides clarity on market structure and growth opportunities for manufacturers. Each segment addresses specific consumer needs, from health-conscious choices to convenience-driven purchases.
Product Type:
Consumer purchasing decisions for fruit juice often hinge on perceived naturalness, nutritional value, and processing methods.
- Cold-Pressed:Cold-pressed juices are produced using high-pressure processing (HPP), a non-thermal method that preserves enzymes, vitamins, and the fresh taste of fruits and vegetables. Demand for these premium products is concentrating in urban centers across North America and Western Europe, driven by health-conscious consumers seeking minimal processing.
- Concentrate:From-concentrate juices are produced by removing water from fruit pulp, then rehydrating it before packaging, offering an economical and shelf-stable option. This segment commands the largest volume share globally, particularly in price-sensitive markets like India, where affordability and convenience drive widespread consumption.
- From Fresh:From fresh juices are directly extracted from fruits, typically flash-pasteurized, appealing to consumers prioritizing taste and minimal processing.
- Organic:Organic juices are made from fruits grown without synthetic pesticides or fertilizers, appealing to consumers prioritizing environmental impact and chemical-free products.
- Fortified:Fortified juices contain added vitamins, minerals, or other functional ingredients, targeting consumers seeking specific health benefits beyond basic nutrition.
Concentrate leads on scale; Cold-Pressed leads on momentum.
Packaging Type:
The choice of packaging type for fruit juice is often dictated by factors such as product shelf life, consumer convenience, and environmental considerations.
- Carton Pack:Carton packs, typically made from multi-layered paperboard, aluminum, and polyethylene, offer excellent protection against light and oxygen, enabling long shelf life for ambient storage. This packaging type dominates mass-market distribution in Europe and Asia, valued for its cost-effectiveness and recyclability.
- Glass Bottle:Glass bottles offer a premium perception and maintain product purity, primarily used for high-end or organic juices due to their inert nature.
- PET Bottle:PET (polyethylene terephthalate) bottles are lightweight, shatterproof, and resealable, providing convenience for on-the-go consumption and a clear view of the product. Demand for PET bottles is strong in North America and Southeast Asia, driven by consumer preference for portability and ease of use.
- Tetra Pak:Tetra Pak packaging provides aseptic processing capabilities, extending shelf life without refrigeration, making it popular for ambient juice products in emerging markets.
- Pouch:Pouches are flexible, lightweight, and often feature spouts, appealing to parents for children's juices and to consumers seeking portable, single-serve options.
The shift towards PET Bottle highlights evolving consumer priorities, while Carton Pack maintains its foundational role.
Distribution Channel:
The distribution channels for fruit juice are critical in determining market reach, consumer accessibility, and brand visibility across various demographics.
- Supermarkets:Supermarkets represent the dominant distribution channel, offering a wide assortment of brands and product types, benefiting from high foot traffic and bulk purchasing habits. This channel concentrates demand across mature markets like the U.S. and Germany, leveraging extensive shelf space and promotional activities.
- Convenience Stores:Convenience stores cater to immediate consumption needs, stocking single-serve juice options for on-the-go consumers in high-traffic urban areas.
- Online Retailers:Online retailers provide convenience and a broader product selection, enabling direct-to-consumer models for niche and premium juice brands. This channel is experiencing rapid expansion in dense urban centers across North America and Western Europe, driven by evolving consumer purchasing behavior and convenience.
- Wholesale:Wholesale channels supply large volumes of juice to institutions, foodservice providers, and smaller retailers, forming a crucial backbone for bulk distribution.
- Specialty Stores:Specialty stores, including health food and organic markets, focus on premium, organic, and cold-pressed juices, attracting health-conscious consumers.
While Supermarkets remain foundational, Online Retailers demonstrate the most dynamic expansion.
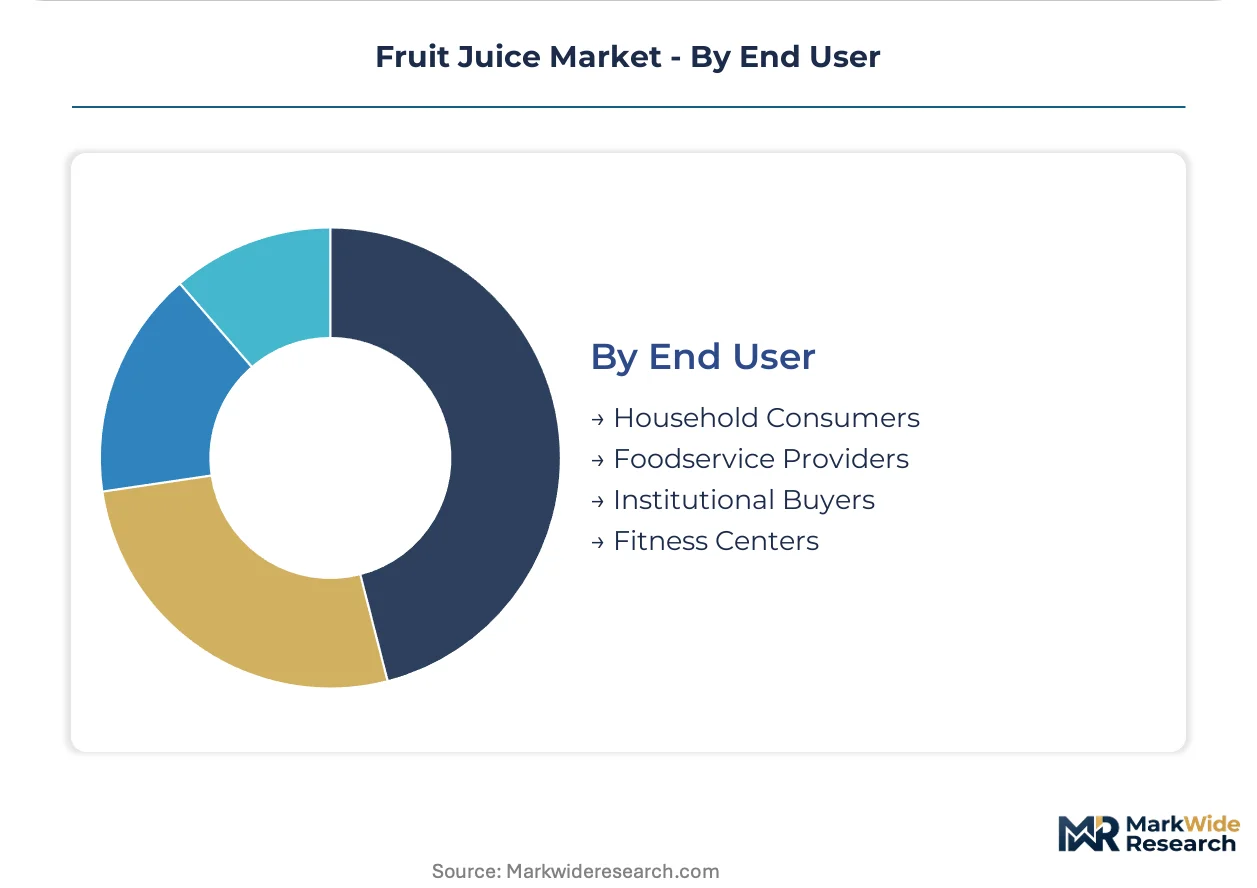
End User:
Understanding the distinct consumption patterns and purchasing motivations of different end-user segments is crucial for tailoring product offerings and marketing strategies.
- Household Consumers:Household consumers represent the largest end-user segment, purchasing juice for daily consumption, meal accompaniment, and as a healthier beverage alternative. Demand from this segment is broad-based, influencing product formulation towards lower sugar variants due to regulatory pressures in the EU.
- Foodservice Providers:Foodservice providers, including restaurants, cafes, and catering services, incorporate fruit juices into menus as standalone beverages or as ingredients in cocktails and smoothies. This segment shows notable expansion in North America, driven by the inclusion of premium and freshly squeezed juices.
- Institutional Buyers:Institutional buyers, such as schools, hospitals, and corporate cafeterias, procure juice in bulk, often prioritizing nutritional standards and cost-effectiveness.
- Fitness Centers:Fitness centers offer juices as part of post-workout recovery or health-focused options, favoring fortified or cold-pressed variants for their nutritional benefits.
The market's core demand originates from Household Consumers, with Foodservice Providers exhibiting specialized growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The expansive consumer base in the United States anchors a significant portion of global fruit juice demand. This demographic shift, particularly towards healthier options, influences product innovation worldwide. Regulatory frameworks across key markets further shape regional growth trajectories.
United States
The United States market demonstrates robust demand for premium, health-oriented fruit juices, particularly cold-pressed and organic variants. The U.S. FDA enforces strict labeling rules regarding juice content percentages and health claims, influencing product transparency. California's robust agricultural sector in the Central Valley supports a thriving cold-pressed juice industry, emphasizing local sourcing and freshness.
India
India's growing middle class increasingly shifts preferences away from traditional carbonated beverages towards packaged fruit juices. The FSSAI sets stringent standards for fruit juice quality and safety, ensuring consumer trust and product integrity. The Delhi-NCR region, a major urban cluster, concentrates demand for convenient and healthier beverage alternatives.
Germany
Consumer awareness of health and sustainability drives demand for organic and lower-sugar juice variants across Germany. EU front-of-pack nutrition labeling rules, under the Farm to Fork strategy, compel manufacturers to reformulate products. Bavaria's strong organic food industry fosters innovation in naturally sourced and environmentally conscious juice production.
Brazil
Brazil's abundant tropical fruit production underpins a large domestic fruit juice market, with strong consumption of natural and fresh options. ANVISA, the national health surveillance agency, regulates food safety and labeling for all beverage products. The São Paulo metropolitan area serves as a key hub for beverage manufacturing and distribution, catering to diverse consumer tastes.
Fruit Juice Market Key Industry Players
The competitive structure tilts toward a tiered landscape, balancing large-scale beverage conglomerates with agile, specialized juice brands. This market exhibits consolidation among traditional volume players, while fragmentation defines the premium and functional segments. Strategic archetypes include multinational food and beverage giants, regional processing specialists, and niche health-focused producers. Companies pursue portfolio diversification to capture varied consumer preferences and engage in geographic expansion to penetrate emerging markets.
Within the global conglomerate segment, PepsiCo and Coca-Cola represent established players leveraging vast distribution networks for mass-market reach. PepsiCo, through its Tropicana brand, exemplifies reformulation efforts to meet lower-sugar mandates across diverse geographies. Coca-Cola's Minute Maid brand also anchors significant volume, catering to broad consumer demand for accessible juice options. Innocent, conversely, occupies a distinct position as a premium specialist, emphasizing natural ingredients and ethical sourcing to differentiate its offerings. These companies collectively illustrate the dual market dynamics of scale-driven efficiency and specialized value proposition.
| Leading Market Players |
|---|
| Del Valle |
| Tropicana |
| Innocent |
| Coca-Cola |
| PepsiCo |
| Kagome |
| Robinsons |
| Keurig Dr Pepper |
| Minute Maid |
| Others |
Cost & Logistics Intelligence
A distinct premium-commodity divergence in the fruit juice market dictates pricing power and supply chain complexity. This bifurcation separates high-margin cold-pressed products from volume-driven concentrate offerings, influencing both consumer cost and logistical requirements.
Pricing Analysis
The bundled-versus-unbundled product experience critically shapes fruit juice pricing across tiers. Pricing stratifies across premium, standard, and economy levels, driven by processing methods like HPP for cold-pressed juices or traditional pasteurization for from-fresh variants. Organic certification and brand equity also command significant price differentiation. Cost compression in the mass-market segment intensifies due to regulatory pressures for lower sugar content, particularly in the EU. Household consumers purchasing concentrate products exhibit high price sensitivity, while health-conscious buyers of cold-pressed varieties demonstrate lower price elasticity.
Supply Chain Analysis
Fresh fruit input dependency heavily influences the fruit juice supply chain. Raw material sourcing centers on key agricultural regions like Brazil for tropical fruits, the U.S. for citrus, and India for a diverse range of produce. Commodity price volatility, driven by climate change and disease outbreaks, represents a structural supply chain risk, impacting production costs. Packaging materials like PET bottles and Tetra Pak cartons also constitute critical inputs. Downstream distribution runs through established supermarket networks, with online retailers rapidly expanding their reach in urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fruit juice market presents a geographic-arbitrage opportunity, particularly leveraging regions with abundant, low-cost fruit production against markets demanding premium, health-oriented products. This allows for strategic sourcing and processing to optimize margins across diverse regulatory landscapes.
For Market Incumbents:To counter the threat of substitution from functional waters and plant-based milks, incumbents must diversify their product portfolios. Investment in High-Pressure Processing technology allows for premium cold-pressed lines, appealing to health-conscious consumers. Leveraging existing vast distribution networks maintains market presence against agile niche brands. Reformulation efforts for lower-sugar variants also address evolving regulatory pressures and consumer preferences.
For New Entrants and Emerging Players:A significant price-point gap between ultra-premium cold-pressed and mass-market concentrate juices creates entry opportunities. New entrants can target underpenetrated urban centers in North America and Western Europe with subscription-based direct-to-consumer models. Focusing on functional juice blends fortified with adaptogens or probiotics offers a distinct value proposition. This strategy builds direct customer relationships and captures higher margins.
For Investors and Strategic Acquirers:Consolidation pressure builds where cold chain complexity and high capital expenditure constrain smaller players in the premium segment. The long-term viability favors entities capable of scaling specialized processing technologies like HPP or expanding into underpenetrated markets. Acquisition targets include regional cold-pressed juice specialists or successful direct-to-consumer brands with established customer bases. A sustained acceleration in online retail penetration serves as a key inflection indicator for investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Functional Blends | This broadens consumer appeal by offering health-specific benefits beyond basic nutrition, addressing evolving wellness trends. |
| High-Pressure Processing (HPP) Investment | HPP technology extends shelf life and preserves nutrient integrity for premium cold-pressed juices, differentiating product offerings. |
| Direct-to-Consumer (D2C) Channel Development | D2C models bypass traditional retail, fostering direct customer relationships and capturing higher margins for specialized products. |
| Geographic Expansion into Underpenetrated Markets | Expanding into emerging economies like Southeast Asia taps into rising disposable incomes and shifting consumer preferences. |
| Lower-Sugar Product Reformulation | This addresses regulatory mandates and consumer demand for healthier options, maintaining market access in regions like the EU. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform market analysis. Primary research involved discussions with juice manufacturers, retail category managers, agricultural suppliers, and food scientists. This was complemented by secondary validation using regulatory documents from the U.S. FDA and India's FSSAI, alongside trade association reports. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
The forecast window was anchored to historical reference periods to establish a robust analytical baseline. This framework modeled segmentation across product type, packaging type, distribution channel, end-user, and regional regulatory clusters. Compound annual growth rates were derived from an assessment of market drivers and restraints. Key forecast inputs included fruit commodity price fluctuations and evolving consumer health trend adoption rates.
Caveats apply where new regulatory mandates or significant climate impacts on fruit yields could materially shift the outlook. Forecasts reflect assumptions regarding processing technology advancements and consumer dietary shifts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Soy Drinks Market
Beverages
India Bottled Water Market
Beverages
US Bubble Tea Market
Beverages
Beverage Multipacks Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Ready to Drink Shakes Market
Beverages
Still Drinks Market
Beverages
Europe Juices Market
Beverages
Commercial Drink Mixers Market
Beverages
Solid Beverages Market
Beverages
India Soy Beverages Market
Beverages
Carbonated Beverages Market
Beverages
Chill Block Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Ginger Beer Market
Beverages
NFC JUICE Market