
 Hydration Infusers Market | 2026-2036
Hydration Infusers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydration Infusers Market Foresight
Smart bottle connectivity and embedded sensor technology is tilting product development toward data-driven hydration tracking. B. Braun SE leverages its medical-grade manufacturing heritage to anchor premium positioning in clinical-adjacent wellness segments. Baxter sustains R&D intensity around biocompatible materials that bridge consumer and professional use cases. Grifols, S.A. competes through specialized infusion expertise adapted for portable hydration formats.
Hydration infusers are vessels engineered to integrate flavor, electrolytes, or nutrients into water through removable chambers, typically constructed from borosilicate glass, food-grade silicone, or stainless steel with temperature tolerances spanning -20°C to 120°C. Their primary commercial purpose centers on converting plain water consumption into functional hydration routines across fitness, workplace, and clinical wellness settings. Plastic infusers still dominate unit volume but glass and silicone variants capture disproportionate margin pools as health conscious consumers prioritize material safety. Online retail channels extend fastest among distribution pathways, though specialty stores retain outsized influence in athlete and premium fitness enthusiast segments.
The FDA governs food-contact material safety under 21 CFR standards while the EU EFSA enforces migration limits through its plastics regulation, collectively elevating compliance costs for multi-market suppliers. REACH chemical restrictions and California's Proposition 65 labeling requirements further constrain material choices for brands serving transatlantic demand. Stakeholders must monitor evolving state-level packaging regulations and sensor-data privacy frameworks as connected hydration products proliferate.
Market Dynamics
Material safety mandates from the FDA and EU EFSA are compressing plastic infuser margins while accelerating glass and silicone substitution across premium consumer segments. This regulatory pressure is restructuring supplier portfolios and forcing rapid manufacturing transitions.
Growth Catalysts
- Workplace Wellness Expansion:Corporate hydration programs in the United States are institutionalizing infuser procurement at scale, creating institutional demand anchors beyond individual consumer purchases.
- 21 CFR Compliance:FDA food-contact material standards are elevating certified glass and silicone products above uncertified competitors, rewarding compliant manufacturers with shelf access.
- Embedded Sensor Convergence:Bluetooth-enabled hydration tracking is migrating from fitness wearables into bottle-integrated formats, opening data-monetization pathways for hardware vendors.
Market Restraints
- REACH Chemical Restrictions:ECHA migration limits on plastic additives are constraining European supplier material choices and elevating reformulation costs for multi-market brands.
- Borosilicate Glass Supply Concentration:Specialized glass manufacturing concentrates in Germany and China, creating input bottlenecks during demand surges.
- Stainless Steel Price Volatility:Nickel and chromium input costs swing with commodity cycles, compressing margin stability for metal-infuser producers.
Strategic Opportunities
- Clinical-Adjacent Wellness:Post-acute care facilities and outpatient rehabilitation centers represent underpenetrated institutional demand for medical-grade hydration formats.
- California Proposition 65 Labeling:Early compliance with state-level chemical disclosure requirements creates competitive differentiation for brands targeting health-conscious coastal consumers.
- Direct-to-Consumer Subscription:Replenishment models for flavor cartridges and filter inserts are capturing recurring revenue streams independent of hardware replacement cycles.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 testing protocols for skin-contact materials extend product development cycles by 8-14 months.
- Sensor-Data Privacy Frameworks:Emerging GDPR and state-level biometric data regulations create compliance uncertainty for connected hydration products collecting consumption patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydration Infusers Market |
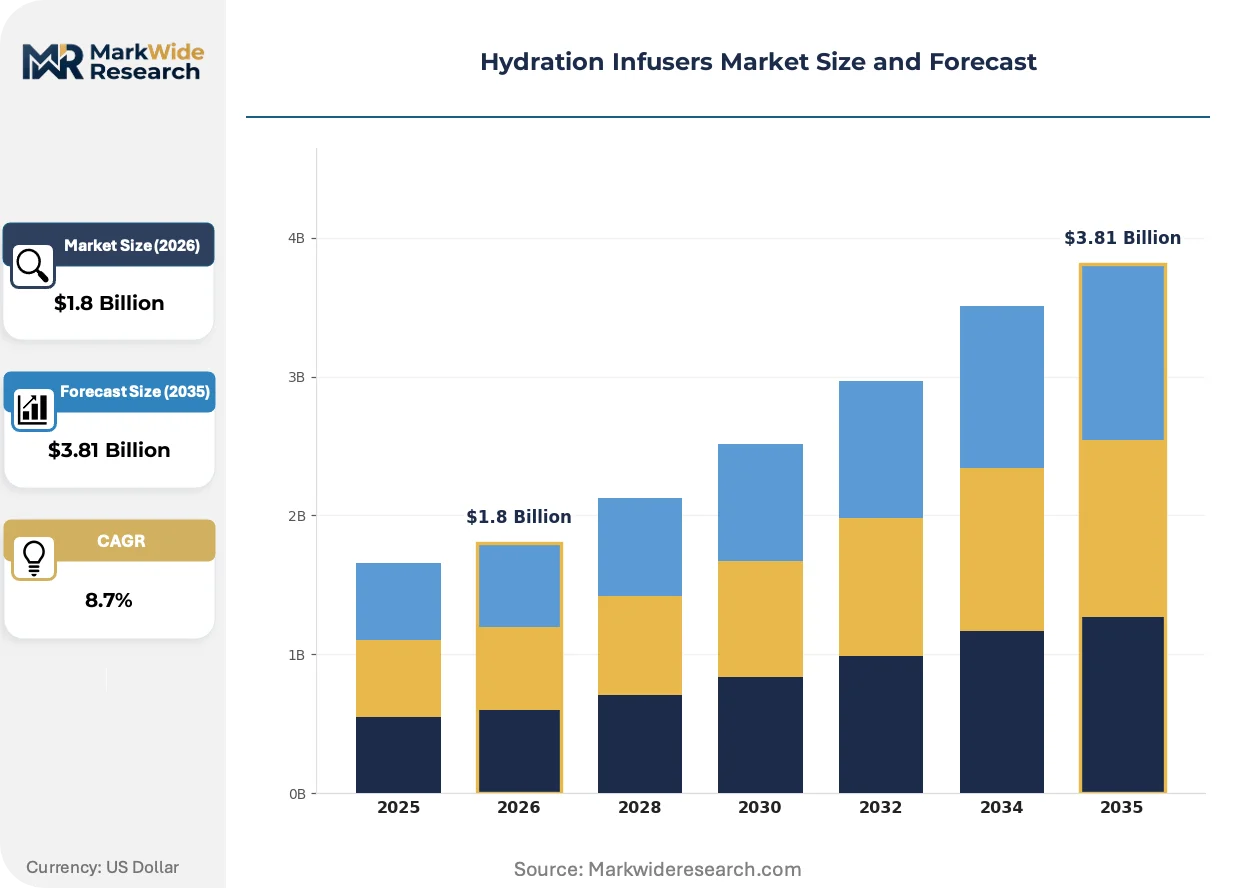
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Infusers, Plastic Infusers, Metal Infusers, Silicone Infusers End User: Fitness Enthusiasts, Athletes, Health Conscious Consumers, Offices Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Fitness Centers Design Feature: Portable Design, Eco-Friendly Materials, Leak-Proof Lids, Built-In Filters |
| Companies Covered | Baxter, B. Braun SE, Otsuka Pharmaceutical Co., Ltd., Grifols, S.A., Vifor Pharma Management Ltd., JW Life Science Corporation, Amanta Healthcare, NexGen Health, Core IV Therapy, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydration Infusers Market Shifts & Advancements
Smart connectivity and material transparency are converging to redefine product differentiation in hydration hardware. Manufacturers now compete on data utility and chemical safety credentials rather than purely aesthetic design.
Borosilicate glass construction is migrating from artisanal positioning to mass-market accessibility as automated forming technologies reduce unit costs. Fitness enthusiasts and clinical wellness adopters are driving this transition fastest. The technology is migrating from premium boutique channels into mainstream retail assortments, compressing price premiums for basic glass formats while opening margin pools for sensor-integrated variants.
EU EFSA plastics regulation and California Proposition 65 are tightening disclosure requirements for food-contact materials simultaneously. Manufacturers serving transatlantic demand face overlapping compliance burdens that favor larger suppliers with dedicated regulatory affairs functions. Small and mid-tier brands are responding by narrowing geographic focus or outsourcing certification to specialized testing laboratories.
Subscription-based consumable replenishment is displacing pure hardware transactions in direct-to-consumer channels. Athlete and corporate wellness segments are adopting cartridge auto-delivery for electrolyte and flavor inserts most aggressively. This pattern is most visible in United States coastal metropolitan markets where convenience premiums support recurring revenue models.
Hydration Infusers Market Segmentation
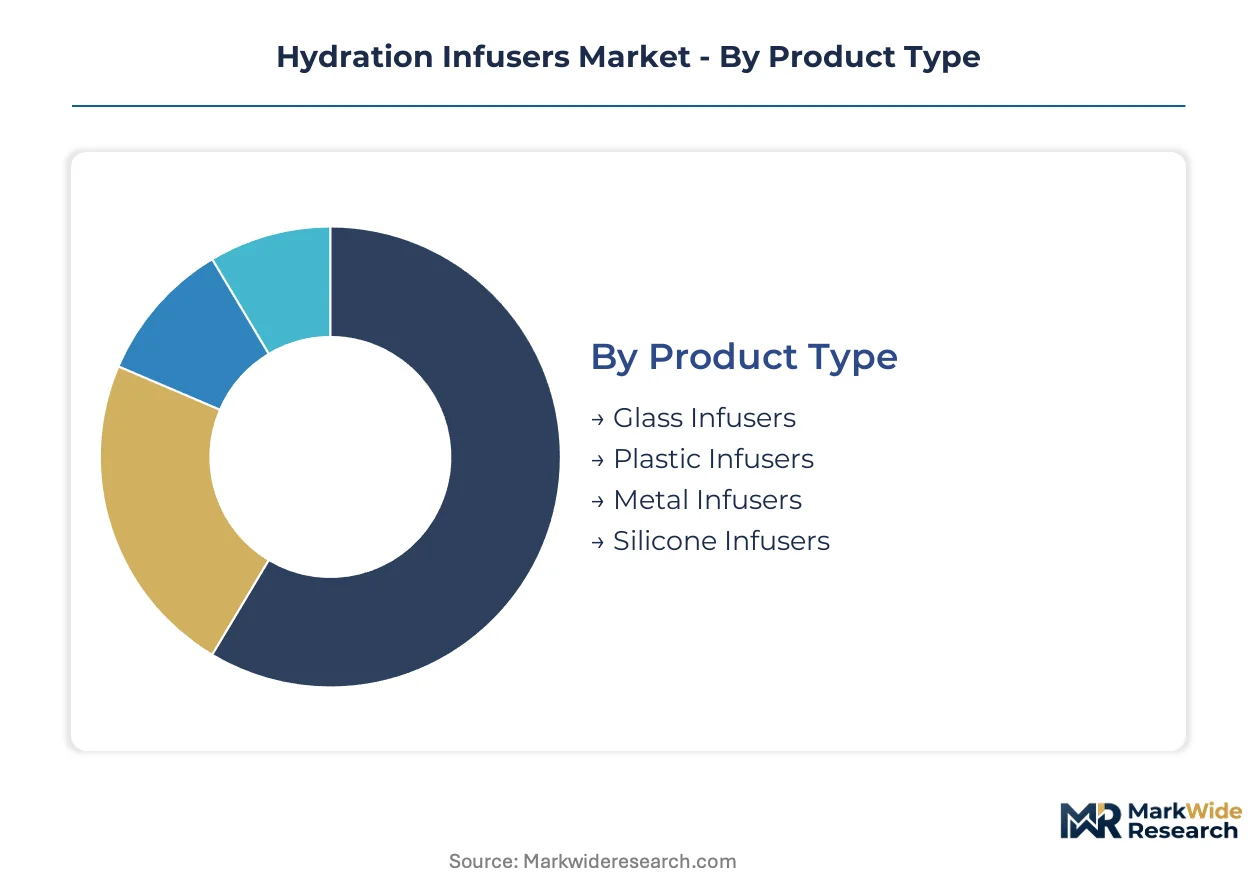
Segmentation in hydration infusers reveals how material choices, user contexts, and channel strategies fragment demand across distinct margin pools. Each dimension carries regulatory and behavioral implications that reshape supplier priorities.
Product Type:
Mature glass formats now compete with emerging smart-material alternatives across price tiers.
- Glass Infusers:Borosilicate construction tolerates thermal shock from -20°C to 120°C, satisfying FDA 21 CFR food-contact standards. Demand concentrates in United States coastal metropolitan wellness programs where BPA-free mandates drive institutional procurement.
- Plastic Infusers:Tritan copolyester and polypropylene variants dominate unit economics despite REACH chemical restrictions compressing European margins. Volume leadership persists in price-sensitive emerging markets where regulatory enforcement lags.
- Metal Infusers:18/8 stainless steel construction with electropolished interiors resists corrosion and metallic leaching. Nickel price volatility constrains margin stability for producers dependent on commodity supply chains.
- Silicone Infusers:Food-grade platinum-cured elastomers enable collapsible and lightweight formats for travel segments. ISO 10993 biocompatibility testing extends development timelines by 8-14 months for skin-contact variants.
Plastic infusers retain volume leadership; silicone formats hold the steepest expansion curve as workplace wellness programs scale.
End User:
Customer archetypes span individual consumption to institutional procurement with diverging technical requirements.
- Fitness Enthusiasts:Bluetooth-enabled tracking and electrolyte cartridge compatibility define product selection. United States gym chains and boutique studios drive recurring hardware refresh cycles.
- Athletes:Medical-grade material certification and precision nutrient dosing distinguish professional-tier products. Competitive cyclists and endurance runners in Germany and Australia prioritize ISO-certified glass construction.
- Health Conscious Consumers:Material transparency and chemical disclosure labeling influence purchase decisions above functional performance. California Proposition 65 compliance creates competitive differentiation for brands targeting coastal United States markets.
- Offices:Corporate hydration programs institutionalize bulk procurement with standardized branding and sensor-data integration for wellness analytics. Fortune 500 headquarters in New York and San Francisco anchor demand.
Health conscious consumers command the highest per-unit margins; corporate offices deliver the most predictable volume pipelines.
Distribution Channel:
Channel economics separate convenience-driven transactions from relationship-heavy consultative sales.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment for flavor cartridges and filter inserts. Amazon and specialized wellness marketplaces capture the fastest growth in United States and United Kingdom demand.
- Supermarkets:Mass-market placement emphasizes price accessibility and impulse purchase visibility. Walmart and Target assortments concentrate on plastic and entry-level metal formats.
- Specialty Stores:REI and running specialty retailers provide hands-on material education and fitting consultation. Athletes and premium fitness enthusiasts drive disproportionate margin capture here.
- Fitness Centers:Equinox and Lifetime Fitness embed infusers into membership packages and retail concessions. Co-branded hardware creates captive distribution for sensor-integrated products.
Online retail expands most quickly; specialty stores preserve margin concentration through expertise differentiation.
Design Feature:
Functional attributes now determine price positioning more than aesthetic differentiation alone.
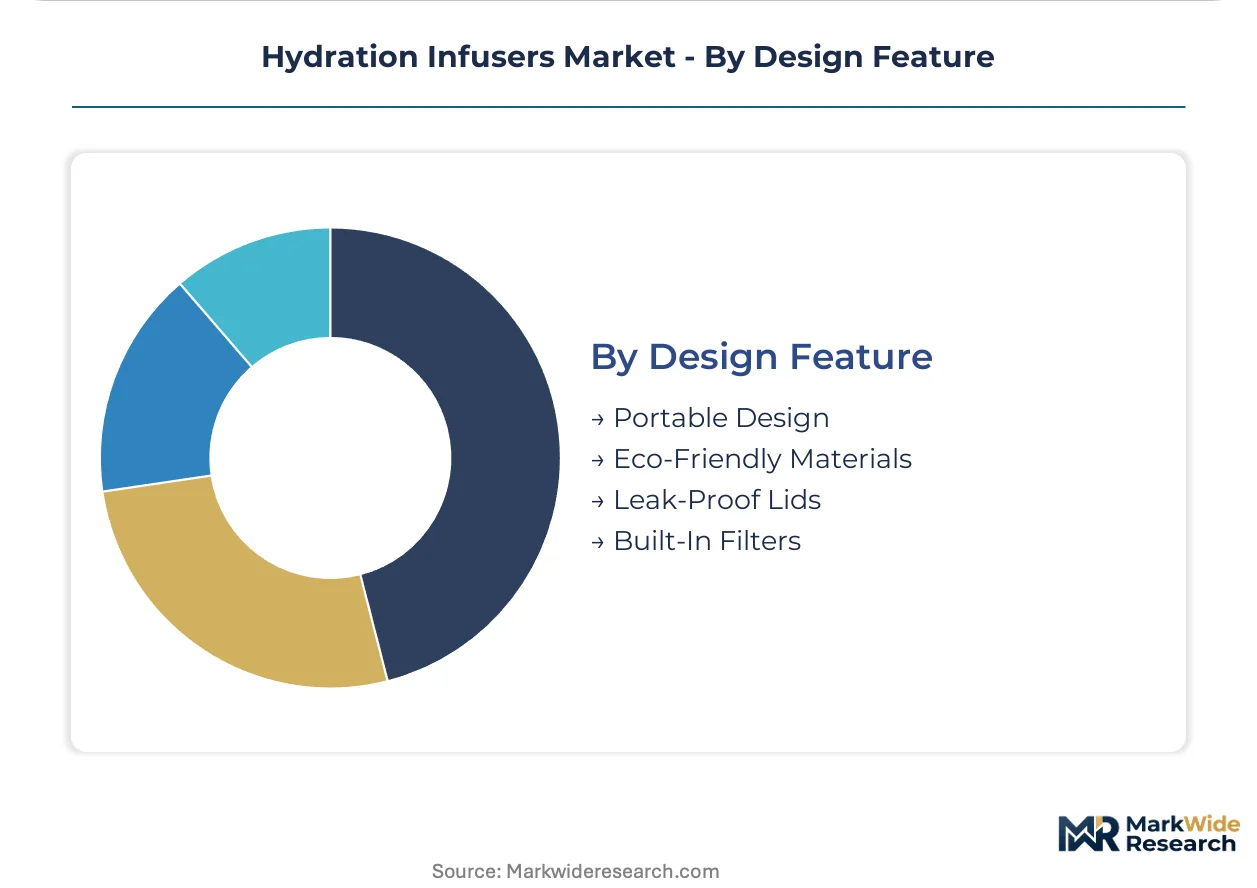
- Portable Design:Collapsible silicone and slim-profile glass formats optimize for commuter and travel contexts. Japanese rail commuters and United States remote workers drive format innovation.
- Eco-Friendly Materials:Recycled ocean plastic and carbon-neutral borosilicate supply chains respond to EU Green Deal procurement guidelines. German and Scandinavian public sector tenders increasingly mandate sustainability credentials.
- Leak-Proof Lids:Silicone gasket engineering and thread-lock mechanisms prevent spillage in bag and desk environments. Office workers and students rank this attribute highest in purchase surveys.
- Built-In Filters:Activated carbon and ion-exchange resin chambers remove chlorine and heavy metals at point-of-use. Concerns over municipal water quality in older United States infrastructure accelerate adoption.
Leak-proof lids remain the baseline expectation; eco-friendly materials gain share fastest as institutional procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in hydration infusers tilt toward net importing in premium glass and silicone segments, while plastic formats dominate outbound manufacturing from cost-optimized production bases. Demand concentrates in high-income wellness economies where workplace hydration programs and fitness culture institutionalize hardware procurement.
United States
Corporate wellness programs at Fortune 500 headquarters in New York and San Francisco drive institutional bulk procurement of sensor-integrated infusers. FDA 21 CFR food-contact material standards elevate certified glass and silicone products above uncertified competitors in retail channels. Austin and Denver anchor startup activity around connected hydration hardware and subscription cartridge replenishment models.
Germany
REACH chemical restrictions and EFSA migration limits compress margins for plastic infuser suppliers while accelerating borosilicate glass adoption. EU Green Deal procurement guidelines increasingly mandate recycled content and carbon-neutral supply chains for public sector tenders. Bavaria and Baden-Württemberg concentrate specialized glass manufacturing and medical-grade material processing capabilities.
China
Domestic fitness culture expansion and municipal water quality concerns propel demand for filtered infuser formats in tier-one cities. GB standards for food-contact materials enforce baseline safety requirements, though enforcement intensity varies by province. Yangtze River Delta and Pearl River Delta clusters dominate global manufacturing output for plastic and entry-level metal infuser exports.
Japan
Rail commuter culture and compact living spaces sustain demand for collapsible silicone and slim-profile portable formats. METI guidelines on chemical safety in consumer products align with JIS standards for food-contact materials. Tokyo and Osaka metropolitan areas concentrate premium retail distribution and corporate wellness program adoption.
Australia
Endurance sports participation and outdoor recreation culture drive medical-grade glass infuser uptake among competitive cyclists and triathletes. TGA oversight of therapeutic goods creates compliance pathways for clinical-adjacent wellness positioning. Sydney and Melbourne anchor specialty retail networks and boutique fitness studio distribution channels.
Hydration Infusers Market Competitive Landscape
On the supply side, the industry is bifurcated between medical-grade heritage manufacturers and consumer wellness entrants, with mid-tier specialists occupying narrowing margin territory. Consolidation pressures concentrate around material certification capabilities and regulatory affairs functions. Three archetypes dominate: diversified healthcare conglomerates leveraging clinical credibility, pure-play hydration hardware specialists, and contract manufacturers serving private-label retail programs. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with sensor technology licensing emerging as a secondary vector.
Within the medical-grade tier, Baxter and B. Braun SE exemplify heritage positioning anchored in biocompatible material expertise and ISO-certified manufacturing protocols. Grifols, S.A. occupies a specialized position derived from infusion therapy heritage adapted toward portable wellness formats. These three entities represent distinct geographic anchors—Baxter through North American operational scale, B. Braun SE through German engineering lineage, and Grifols through European clinical specialization—each leveraging regulatory compliance infrastructure to differentiate against consumer-native competitors.
| Leading Market Players |
|---|
| Baxter |
| B. Braun SE |
| Otsuka Pharmaceutical Co., Ltd. |
| Grifols, S.A. |
| Vifor Pharma Management Ltd. |
| JW Life Science Corporation |
| Amanta Healthcare |
| NexGen Health |
| Core IV Therapy, LLC |
| Others |
Supply & Pricing Matrix
Yangtze River Delta manufacturing clusters dictate downstream pricing power through concentrated borosilicate glass and food-grade silicone capacity. FDA 21 CFR compliance costs and REACH chemical restrictions amplify margin separation between certified and uncertified suppliers across transatlantic markets.
Pricing Analysis
Sensor-integrated next-generation infusers command premium positioning against basic glass prior-generation formats and collapsing silicone economy tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 biocompatibility certification and Bluetooth connectivity bundling. Pricing pressure stems from nickel commodity volatility compressing stainless steel margins. Corporate wellness buyers exhibit lowest price sensitivity while emerging market consumers drive volume through plastic economy segments.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta suppliers and supply-chain finance facilities anchor working capital structures for mid-tier brands. Manufacturing concentrates in China, Germany, and the United States across glass forming, silicone curing, and sensor assembly stages. Raw material flows draw from Australian nickel, German borosilicate, and Chinese rare-earth magnet inputs. Single-source vulnerability concentrates in specialized medical-grade glass furnace capacity. Distribution runs through Amazon direct-to-consumer platforms and Equinox fitness center concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workplace wellness program cyclicality positions this market for recovery as Fortune 500 headquarters reinstate employee benefit procurement. Post-pandemic return-to-office mandates accelerate corporate hydration hardware refresh cycles.
For Market Incumbents: Entrench regulatory compliance infrastructure as a moat against emerging sensor-technology entrants. Baxter and B. Braun SE should deepen ISO 10993 certification pipelines while accelerating backward integration into borosilicate glass supply. Defensive capacity addition in Baden-Württemberg medical-grade processing clusters counters Chinese cost-positioned competitors.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription replenishment models targeting coastal United States health-conscious consumers. California Proposition 65 early compliance creates differentiation white space against lagging mid-tier brands. Specialty store partnerships with REI and running retailers anchor consultative go-to-market positioning for athlete segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors medical-grade heritage manufacturers with regulatory affairs scale over consumer-native hardware startups. Long-term viability across the 5-10 year window hinges on clinical-adjacent wellness segment penetration and data-monetization pathway development. ISO 10993 certification backlog duration serves as inflection indicator for acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Licensing | Baxter's biocompatible material expertise enables Bluetooth hydration tracking integration for wellness data platforms. |
| Backward Integration into Glass | B. Braun SE captive borosilicate supply secures FDA 21 CFR certified input against Yangtze River Delta bottlenecks. |
| Direct-to-Consumer Subscription Launch | Flavor cartridge auto-delivery captures recurring revenue independent of hardware replacement cycles at Equinox retail. |
| Clinical-Adjacent Wellness Partnership | Grifols infusion therapy heritage opens post-acute care facility procurement channels for medical-grade formats. |
| Sustainability Repositioning | EU Green Deal recycled ocean plastic compliance secures German and Scandinavian public sector tender eligibility. |
Research Methodology
A standing panel of hydration hardware product managers, FDA regulatory affairs consultants, corporate wellness procurement directors, and specialty retail category buyers provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against FDA 21 CFR filings, EFSA migration limit databases, Amazon marketplace sales rankings, and Equinox retail concession data. Bottom-up unit shipment estimates and top-down wellness program spending analysis triangulated market sizing across the projection horizon.
Scenario-bracketing around workplace wellness adoption rates and sensor-technology cost curves framed analytical outputs. Segmentation modeling spanned material type, end-user archetype, distribution channel, and connectivity feature dimensions. CAGRs derived from regression analysis of historical corporate benefit spending and fitness hardware refresh cycles. Borosilicate glass supply concentration and REACH chemical restriction timelines served as industry-specific forecast inputs.
Stress conditions across nickel commodity volatility, FDA enforcement intensity, and corporate return-to-office velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding wellness program institutionalization and biocompatibility certification pipeline duration. Macroeconomic recession, regulatory harmonization failure, or sensor-data privacy framework disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fruit and Vegetable Juice Market
Beverages
Kombucha Market
Beverages
Growlers Market
Beverages
South America Bottled Water Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Packaged Milkshake Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Europe Smoothies Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Apple Juice Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
United States Recovery Drinks Market
Beverages
India Bottled Water Market
Beverages
Nitro-Infused Beverages Market
Beverages
Coconut Milk Beverages Market