
 Africa Dairy Based Beverages Market | 2026-2036
Africa Dairy Based Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Dairy Based Beverages Market Outlook
Multi-serve pouch bundling is consolidating rural penetration strategies across East and West Africa. Danone S.A. leverages its cold-chain partnerships to anchor urban availability in Francophone markets. Nestlé S.A. sustains brand recognition through micronutrient-fortified formulations targeting school nutrition programs. Fan Milk Limited dominates street-vendor channels with frozen dairy pushcart distribution that competes directly with informal fresh-milk sellers.
Africa dairy based beverages comprise processed liquid dairy products formulated for ambient or chilled consumption, typically containing minimum milk solids of 2.5% and pasteurized or UHT-treated to extend shelf life under tropical conditions. These products serve as affordable protein and calcium delivery vehicles for populations with limited refrigeration access. Flavored milk captures the widest margin pool due to low price elasticity among children and teenagers. Yogurt drinks represent the fastest-growing category as lactose-tolerant positioning attracts adult wellness seekers. Tetra Packs retain structural dominance where electricity intermittency makes refrigeration-dependent formats commercially risky.
The national food safety regulator in each African country enforces Codex Alimentarius-derived standards for dairy solids content and microbial limits, while the African Union's Sanitary and Phytosanitary (SPS) committee harmonizes cross-border certification requirements under AfCFTA implementation protocols. Dairy processors must navigate dual compliance with national standards and regional mutual recognition agreements to access neighboring markets without redundant testing. Stakeholders should monitor how AfCFTA tariff phase-outs alter competitive dynamics between regional dairy cooperatives and multinational processors with established cross-border logistics.
Market Dynamics
The AfCFTA protocol is rewriting cross-border dairy trade rules, forcing processors to rebuild logistics networks around mutual recognition agreements rather than national silos. This structural shift concentrates competitive advantage among operators with pre-existing cold-chain partnerships spanning multiple jurisdictions.
Growth Catalysts
- Urban household expansion:Nigeria, Kenya, and South Africa are seeing concentrated demand from city dwellers seeking affordable protein delivery without refrigeration dependency.
- AfCFTA tariff phase-outs:The African Union's SPS committee harmonization reduces redundant testing burdens for dairy solids certification across member states.
- UHT processing scale-up:Tetra Pack dominance in electricity-intermittent zones enables ambient distribution reach where chilled formats fail commercially.
Market Restraints
- Input cost volatility:Powdered milk imports face currency fluctuation exposure in Francophone West Africa, compressing processor margins unpredictably.
- Supply concentration risk:Regional dairy cooperatives in East Africa control raw milk collection, limiting multinational backward integration options.
- Technical limitation:Lactose intolerance prevalence among adult populations caps fresh milk penetration, forcing reformulation investments.
Strategic Opportunities
- Rural pouch bundling:Multi-serve formats in East and West Africa unlock price points inaccessible to single-serve urban packaging.
- School nutrition mandates:Government micronutrient fortification programs create institutional procurement channels with multi-year visibility.
- Frozen pushcart channels:Street-vendor distribution networks in coastal cities bypass formal retail infrastructure entirely.
Industry Challenges
- Cold-chain technician scarcity:Qualified refrigeration maintenance personnel are concentrated in South Africa and Kenya, leaving other markets underserved.
- Dual compliance complexity:Processors must satisfy both national Codex-derived standards and AfCFTA mutual recognition timelines simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Dairy Based Beverages Market |
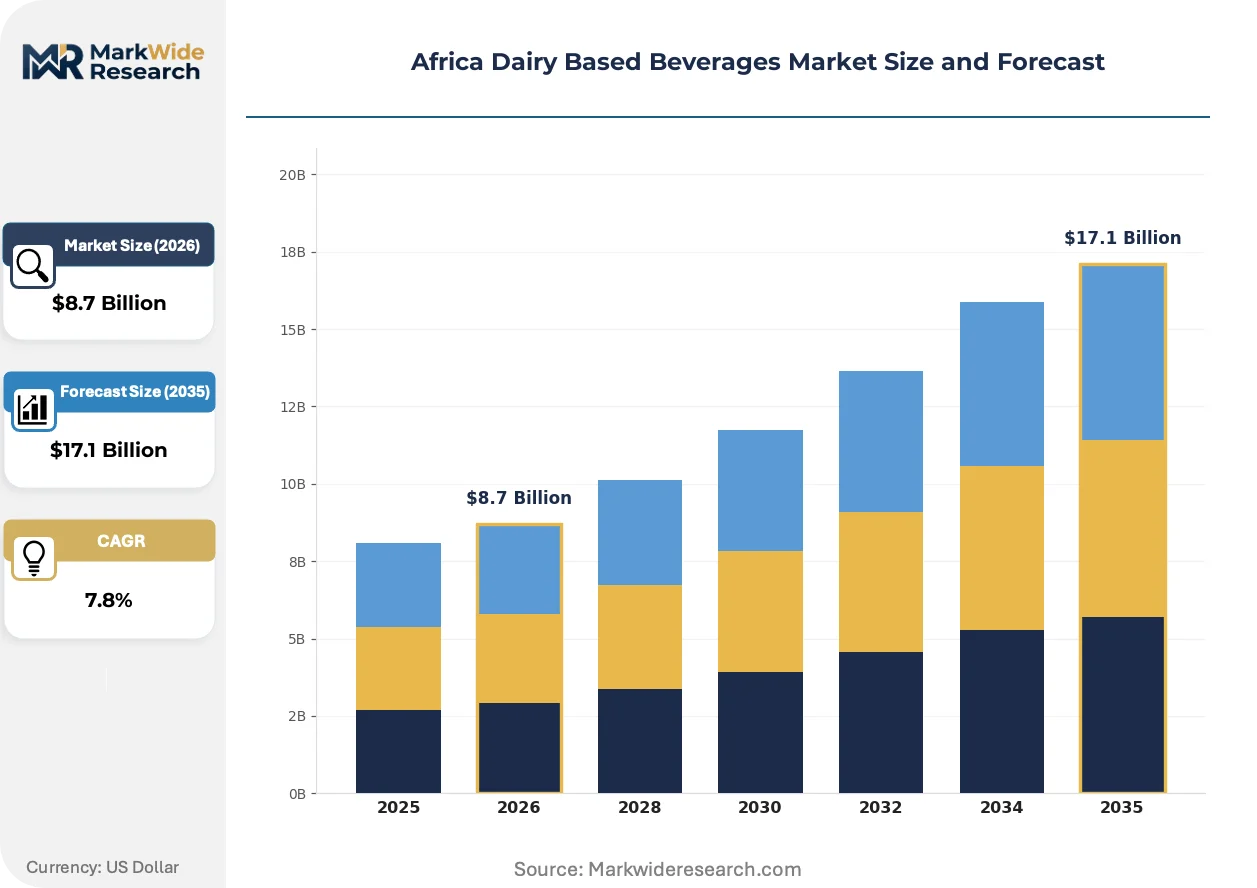
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Milk, Yogurt Drinks, Milkshakes, Buttermilk End User: Children, Adults, Athletes, Seniors Packaging Type: Tetra Packs, Bottles, Cans, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesalers |
| Companies Covered | Danone S.A., Nestlé S.A., Clover S.A. (Pty) Ltd, Groupe Lactalis, Brookside Dairy Ltd, First Choice Dairy, Fan Milk Limited, Obour Land, Dairibord Holdings, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Dairy Based Beverages Market Strategic Shifts
Processing technology and distribution architecture are converging to solve the refrigeration gap that has historically limited dairy penetration across tropical Africa. Three developments are compressing the cost-to-serve equation.
Aseptic filling systems paired with laminated carton structures are rewriting shelf-life economics for ambient distribution. Nigerian and Kenyan processors are adopting these lines fastest, enabling 6-month stability without cold-chain investment. The structural consequence is displacement of fresh-milk cooperatives in secondary cities where electricity reliability remains poor.
The African Union's Sanitary and Phytosanitary committee under AfCFTA implementation is forcing harmonized microbial limit standards across member states. This regulatory convergence reduces border detention incidents for cross-shipped UHT milk. Kenyan processors with existing Tanzania and Uganda routes are repositioning compliance teams to capture first-mover certification advantages.
Urban teenagers are shifting consumption toward yogurt drinks positioned for lactose tolerance and wellness claims. This behavioral pivot is visible most acutely in Lagos and Nairobi, where gym culture and social media health messaging intersect. Traditional flavored milk brands are responding with probiotic line extensions to defend shelf space in modern trade outlets.
Africa Dairy Based Beverages Market Segmentation
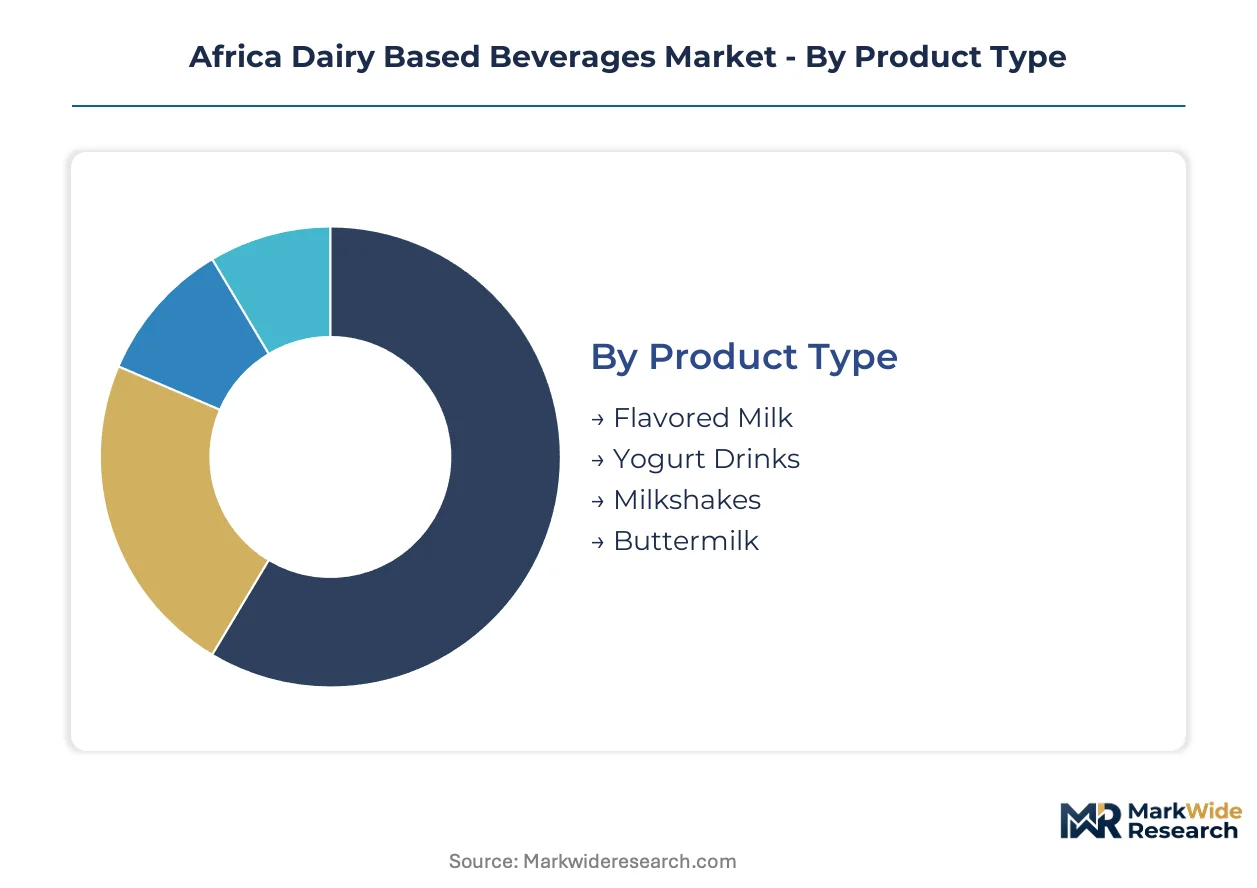
Segmentation in African dairy beverages reveals how product-positioning, packaging-technology, and channel-access combine to unlock purchasing power across income tiers and electricity-constrained geographies. Each dimension carries distinct certification and cold-chain requirements that reshape competitive economics.
Product Type:
Flavored milk carries the lightest regulatory burden among ambient-stable formats, requiring only basic Codex Alimentarius compliance for dairy solids and pasteurization documentation. Yogurt drinks face heavier scrutiny from national food safety regulators due to live-culture claims and shorter shelf-life windows.
- Flavored Milk:UHT-treated formulations with 2.5% minimum milk solids deliver ambient stability for 6 months without refrigeration. Demand concentrates in Nigerian and Kenyan urban households where children drive repeat purchase and electricity intermittency rules out chilled alternatives.
- Yogurt Drinks:Fermented dairy beverages with probiotic positioning require cold-chain maintenance below 8°C and attract adult wellness seekers in Lagos and Nairobi gym culture. Lactose-tolerant marketing expands addressable market beyond traditional fresh-milk consumers.
- Milkshakes:Higher-fat formulations targeting treat occasions carry premium pricing in South African modern trade.
- Buttermilk:Traditional fermented variants retain niche demand in East African rural markets with established dairy cooperatives.
Flavored milk sits at the top of the volume ranking, with yogurt drinks climbing the fastest.
End User:
Cost tier and nutritional positioning diverge sharply across age and activity segments, with institutional procurement creating volume anchors for specific demographics.
- Children:Micronutrient fortification mandates in school nutrition programs anchor institutional volume. Nigerian and Kenyan government tenders specify iron, zinc, and vitamin A enrichment, creating multi-year procurement visibility for compliant processors.
- Adults:Wellness-positioned yogurt drinks with lactose-reduced formulations capture discretionary spending in Nairobi and Lagos formal employment clusters. Gym culture and social media health messaging accelerate trial rates among 25-40 year-olds.
- Athletes:Protein-fortified recovery beverages remain concentrated in South African specialty retail with limited cross-border penetration.
- Seniors:Calcium-fortified ambient formats target limited-income pensioners in Francophone West African secondary cities.
Children command the largest procurement volumes through institutional channels, while adults drive the steepest expansion trajectory via premium wellness positioning.
Packaging Type:
Electricity reliability across target geographies dictates viable packaging economics, with ambient-stable formats commanding wider distribution reach.
- Tetra Packs:Laminated carton aseptic filling enables 6-month shelf stability without cold-chain investment. Nigerian processors adopting these lines fastest displace fresh-milk cooperatives in electricity-intermittent secondary cities.
- Pouches:Multi-serve bundling unlocks rural price points below single-serve urban packaging in East and West Africa. Sachet formats bypass formal retail infrastructure entirely through informal vendor networks.
- Bottles:PET and HDPE formats require refrigeration-dependent distribution, limiting penetration to South African and Kenyan urban centers with reliable cold-chain infrastructure.
- Cans:Metal packaging retains minimal presence outside South African premium positioning and export-oriented production.
Tetra Packs dominate volume through ambient distribution advantages, with pouches gaining share fastest in rural penetration strategies.
Distribution Channel:
Channel selection determines margin capture versus volume reach, with modern trade and informal pathways serving fundamentally different consumer economics.
- Supermarkets:Modern trade outlets in South African and Nigerian cities command premium shelf placement fees and drive brand-building for multinational processors. Refrigerated display requirements limit category participation to chilled-format specialists with established cold-chain partnerships.
- Wholesalers:Bulk breaking and credit extension to small retailers anchor rural penetration in East African markets. Kenyan dairy cooperatives leverage existing collection network relationships to push ambient UHT formats through informal trade.
- Convenience Stores:Urban proximity retail in Lagos and Nairobi captures impulse purchase for single-serve flavored milk and yogurt drinks.
- Online Retailers:E-commerce penetration remains concentrated in South African metropolitan areas with reliable last-mile cold-chain execution.
Wholesalers move the highest absolute volumes through fragmented retail networks, while supermarkets capture the fastest value growth in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy beverage industrialization in Africa traces to colonial-era processing cooperatives in Kenya and South Africa, which established the continent's first pasteurization infrastructure during the mid-twentieth century. These historical foundations shaped today's geographic concentration of processing capacity.
Nigeria
Lagos and Kano drive flavored milk consumption through urban household expansion and school nutrition procurement programs. The National Agency for Food and Drug Administration and Control enforces dairy solids standards derived from Codex Alimentarius protocols. Northern dairy cooperatives around Kaduna supply raw milk to processors expanding UHT lines for ambient distribution.
Kenya
Nairobi anchors East African demand through formal employment clusters purchasing wellness-positioned yogurt drinks. The Kenya Dairy Board regulates pasteurization compliance and cross-border certification for Tanzania and Uganda routes. Rift Valley dairy cooperatives control collection networks that limit multinational backward integration into raw supply.
South Africa
Gauteng and Western Cape provinces concentrate premium milkshake and protein-fortified recovery beverage demand among gym culture participants. The Department of Health enforces food safety standards aligned with regional SPS harmonization under AfCFTA. Cape Town cold-chain infrastructure supports the continent's most developed refrigerated distribution networks.
Egypt
Cairo and Alexandria generate institutional volume through government school feeding mandates specifying micronutrient fortification. The Egyptian Organization for Standardization and Quality oversees dairy solids certification for cross-Mediterranean export. Nile Delta dairy clusters supply processors reformulating for lactose-reduced adult positioning.
Ghana
Accra and Kumasi street-vendor channels push frozen dairy pushcart distribution competing with informal fresh-milk sellers. The Food and Drugs Authority regulates microbial limits for ambient-stable formats. Coastal processing facilities leverage Fan Milk Limited's established vendor networks to bypass formal retail infrastructure.
Africa Dairy Based Beverages Market Competitive Environment
The competitive structure tilts toward multinational processors with pre-existing cold-chain partnerships spanning multiple jurisdictions. National dairy cooperatives retain raw milk collection control in East Africa, creating fragmented upstream supply. Three archetypes dominate: multinational UHT specialists, regional cooperative processors, and street-vendor channel operators. Capacity expansion and AfCFTA compliance repositioning constitute the primary competitive moves.
Among multinational processors, Danone S.A. and Nestlé S.A. exemplify cold-chain partnership strategies anchoring urban availability, while Fan Milk Limited occupies a distinctive position in frozen pushcart distribution. These three companies represent divergent channel archetypes rather than direct product competition, with each anchoring separate distribution economics across Francophone, Anglophone, and coastal West African markets.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestlé S.A. |
| Clover S.A. (Pty) Ltd |
| Groupe Lactalis |
| Brookside Dairy Ltd |
| First Choice Dairy |
| Fan Milk Limited |
| Obour Land |
| Dairibord Holdings |
| Others |
Value Chain & Pricing Dynamics
School nutrition procurement programs in Nigeria and Kenya anchor volume-based contract pricing that compresses per-unit margins while guaranteeing multi-year offtake. This institutional buyer concentration forces processors to absorb input cost volatility through formula-flexibility clauses rather than pass-through mechanisms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UHT-flavored milk for urban households from probiotic yogurt drinks and multi-serve rural pouches. Price differentiation rests on certification grade for Codex Alimentarius compliance and cold-chain infrastructure requirements. Pricing pressure stems from powdered milk import currency exposure in Francophone West Africa. Rural households exhibit highest price sensitivity, while gym-culture wellness seekers in Lagos and Nairobi tolerate premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with East African dairy cooperatives controlling Rift Valley raw milk collection networks. Geographic supply concentration centers on Kenya, South Africa, and Nigeria for processing capacity, with Egypt and Ghana as secondary hubs. Raw material dependencies draw from powdered milk imports, laminated carton packaging, and live-culture starter strains. Supply chain risk manifests as tariff exposure under AfCFTA phase-out timelines. Distribution runs through wholesaler bulk-breaking networks in East Africa and frozen pushcart channels in coastal West African cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa dairy beverages market functions as a regulatory compounder where AfCFTA SPS harmonization is accelerating cross-border certification demand and consolidating procurement around compliant processors.
For Market Incumbents: Deepen cold-chain technician training partnerships in South Africa and Kenya to extend service reach into underserved Francophone markets. Anchor backward integration into Rift Valley and Northern Nigerian dairy cooperatives before regional competitors consolidate collection network control. Defend against informal fresh-milk sellers by accelerating UHT line investments that displace cooperative presence in electricity-intermittent secondary cities.
For New Entrants and Emerging Players: Enter via frozen pushcart distribution in Accra and Kumasi where Fan Milk Limited's vendor networks demonstrate channel viability without formal retail infrastructure. Target calcium-fortified ambient formats for limited-income pensioners in Francophone West African secondary cities as the most penetrable white-space segment. Pursue government micronutrient fortification tenders as the primary go-to-market anchor.
For Investors and Strategic Acquirers: Regional dairy cooperatives with established collection networks and AfCFTA-compliant certification are the most active acquirer targets in this space. Long-term viability hinges on processors capturing institutional procurement channels with multi-year visibility rather than commodity spot-market exposure. Watch AfCFTA mutual recognition agreement implementation speed as the signal indicating when cross-border logistics investments will yield margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| AfCFTA Compliance Certification | Harmonized SPS standards reduce border detention incidents for Kenyan processors shipping to Tanzania and Uganda. |
| UHT Processing Scale-Up | Aseptic filling lines in Nigeria displace fresh-milk cooperatives in electricity-intermittent secondary cities. |
| Rural Pouch Bundling | Multi-serve formats unlock price points below single-serve urban packaging in East and West African markets. |
| Cold-Chain Partnership Expansion | Danone's Francophone logistics networks anchor urban availability where refrigeration infrastructure remains sparse. |
| School Nutrition Program Capture | Government tenders for iron, zinc, and vitamin A fortification create multi-year procurement visibility. |
Study Parameters
Bottom-up household consumption modeling reconciled against top-down dairy processor capacity tracking forms the analytical core of this study. Primary interviews with dairy processing executives, cold-chain logistics operators, national food safety regulators, and school nutrition program procurement officers combined with secondary validation from African Union SPS committee documentation, national Codex Alimentarius enforcement records, and customs trade data for powdered milk imports. Triangulation across these sources calibrated volume estimates against actual production line deployments.
Historical trendline analysis of UHT adoption rates and flavored milk penetration informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, packaging technology, end-user demographic, and distribution channel, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from elasticity-adjusted demand curves incorporating electricity reliability indices and urban household expansion trajectories. Forecast inputs included AfCFTA tariff phase-out schedules and school nutrition program budget allocations.
Inputs from dairy cooperative collection network surveys and processor capacity announcements were available through the study window; gaps in informal fresh-milk volume estimation introduce uncertainty bands around rural penetration assumptions. Forecasts reflect documented assumptions about SPS harmonization implementation speed and currency stability in Francophone markets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Italy Probiotic Drinks Market
Beverages
South America Bottled Water Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
United States and Australia Coconut Water Market
Beverages
Cold Pressed Juice Market
Beverages
Bottled Air Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Ready to Drink Shakes Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Powdered Beverages Market
Beverages
Spring Water Market
Beverages
Blackstrap Molasses Market
Beverages
Milk Tea Powder Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Beverage Premix Market
Beverages
North America Energy Drink Market