
 Global Soft Drinks Concentrate Market | 2026-2036
Global Soft Drinks Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soft Drinks Concentrate Market Outlook
Restaurant and cafe fountain systems is consolidating as the fastest-growing end-use channel for soft drinks concentrate, displacing traditional retail bottle reliance. The Coca-Cola Company anchors North American fountain infrastructure through extensive foodservice partnerships. PepsiCo Inc. leverages its concentrate-to-cup equipment ecosystem to control downstream margins in quick-service restaurants. Dohler GmbH specializes in natural flavor concentrates, competing on clean-label formulations against commodity suppliers.
Soft drinks concentrate denotes a reduced-volume syrup or powder base, typically containing 15-80% soluble solids, designed for dilution with carbonated or still water prior to consumption. Manufacturers employ vacuum evaporation, membrane filtration, or freeze concentration to preserve volatile aromatic compounds while achieving shelf-stable water activity below 0.85. Carbonated concentrate maintains mature volume leadership in fountain and bottler operations, though functional concentrate containing added vitamins, electrolytes, or botanical extracts captures expanding margin pools in health-positioned channels. Non-carbonated concentrate grows fastest in tropical and herbal flavor profiles as cafes diversify beyond cola-centric menus.
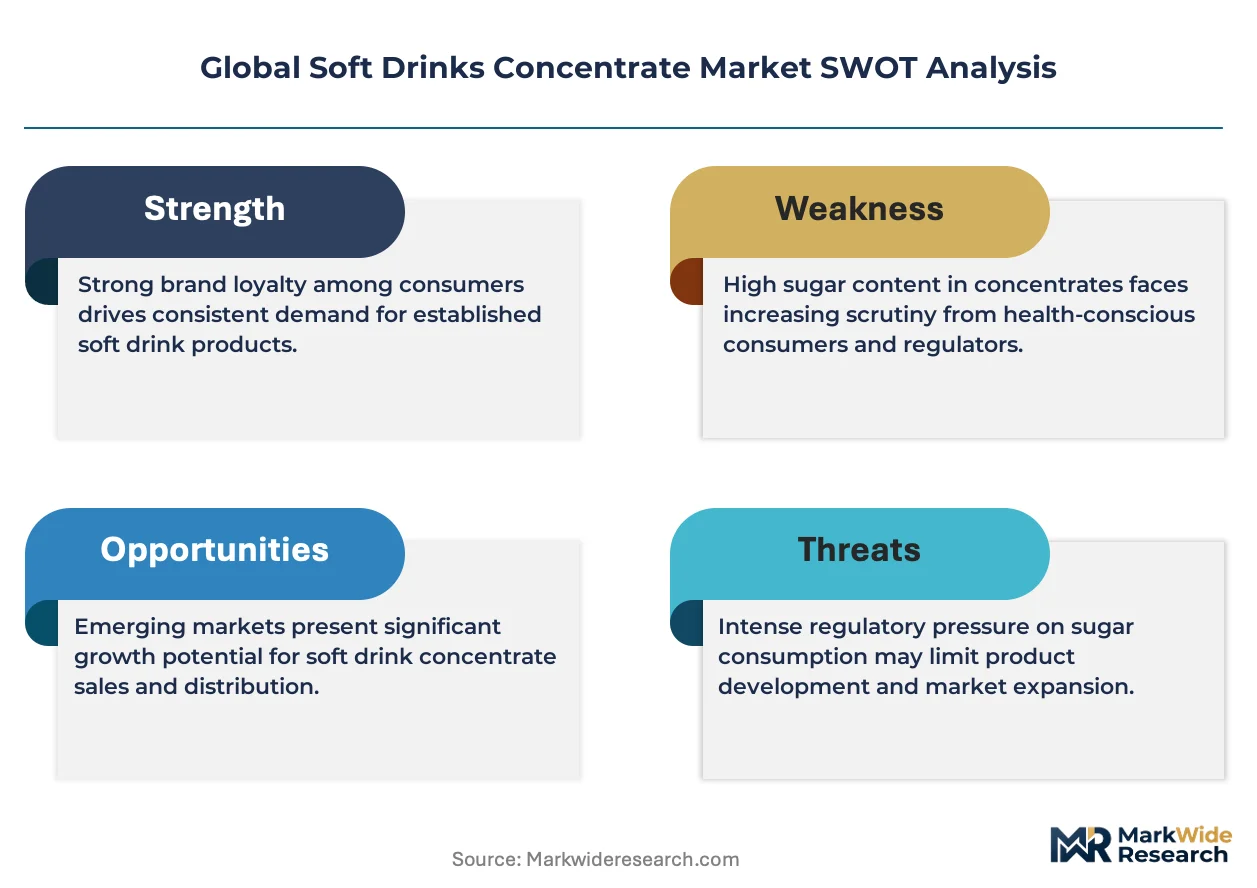
FDA GRAS determinations and EPA water quality standards govern concentrate manufacturing inputs and processing environments in the United States, while EU REACH and F-Gas Regulation restrict synthetic refrigerants used in fountain dispensing equipment. Sugar taxation frameworks in Mexico, the United Kingdom, and South Africa directly alter concentrate formulation economics, pushing manufacturers toward high-intensity sweetener blends or reduced-sugar bases. Stakeholders must monitor evolving front-of-pack labeling requirements across Brazil, India, and Southeast Asian markets to anticipate reformulation investments before compliance deadlines tighten.
Market Dynamics
Fountain-dispensed beverage infrastructure is consolidating control over soft drinks concentrate volume, compressing traditional retail bottling economics while forcing manufacturers to engineer syrup formulations compatible with post-mix carbonation systems and ice-bin cooling constraints.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in fountain dispensing equipment is accelerating equipment replacement cycles, creating concentrated demand for compatible concentrate formulations across foodservice networks in Germany, France, and Italy.
- Quick-service restaurant expansion:Drive-thru beverage programs in Brazil, India, and Mexico are converting from post-mix powder systems to liquid concentrate dispensing, pulling volume through centralized fountain supply contracts.
- Membrane filtration advances:Cross-flow microfiltration and reverse osmosis concentration methods are preserving volatile aromatic compounds at lower thermal exposure, enabling cleaner-label concentrates with extended ambient shelf stability.
Market Restraints
- Sugar input volatility:Beet and cane sugar price swings in commodity markets directly compress concentrate manufacturing margins, particularly for full-sugar cola bases that remain volume-dominant in emerging markets.
- High-intensity sweetener supply concentration:Sucralose and stevia glycoside production clusters heavily in China, creating single-source vulnerability for reformulated reduced-sugar concentrates targeting sugar taxation jurisdictions.
- Technical limitation in natural preservation:Clean-label concentrates lacking synthetic preservatives face accelerated microbial spoilage in tropical ambient distribution, constraining shelf-life claims and export reach.
Strategic Opportunities
- Functional beverage convergence:Electrolyte-enhanced and botanical-infused concentrates are capturing margin pools in gym chains and workplace wellness programs, displacing plain carbonated bases in premium fountain accounts.
- India PLI scheme alignment:Production-linked incentives for food processing infrastructure are enabling greenfield concentrate manufacturing capacity to serve domestic foodservice growth and regional export.
- Direct-store-delivery bypass:Bulk concentrate-to-fountain logistics are eliminating intermediate bottling steps, allowing manufacturers to capture value previously extracted by packaged goods distributors in quick-service channels.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise spanning natural extract stability, high-intensity sweetener synergy, and fountain equipment compatibility is concentrating among a narrow cohort of specialists, inflating compensation and slowing product development cycles.
- Multi-jurisdiction compliance layering:Simultaneous adherence to FDA GRAS determinations, EU REACH additive restrictions, and FSSAI labeling mandates is fragmenting SKU portfolios and complicating global formulation standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soft Drinks Concentrate Market |
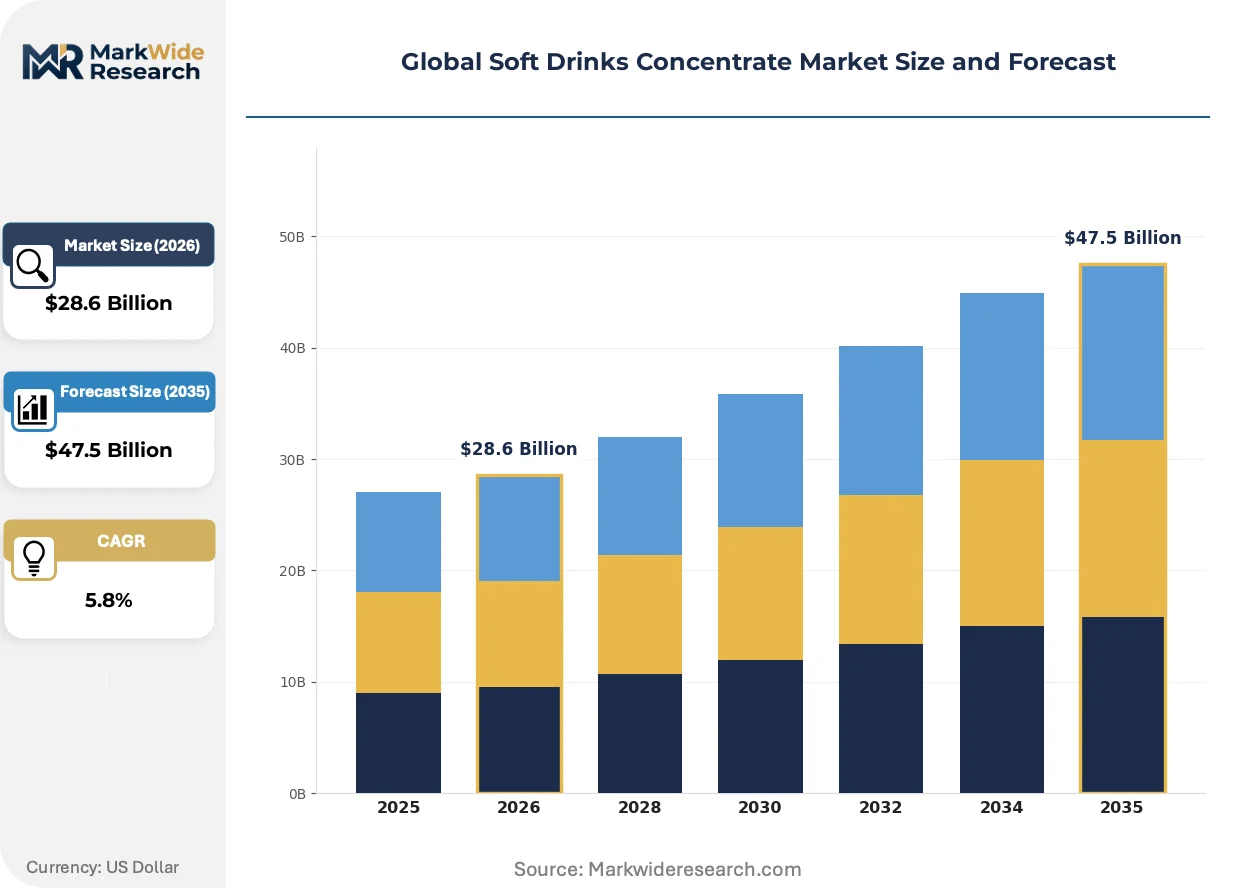
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Functional, Flavored End User: Retailers, Restaurants, Cafes, Wholesale Distributors Packaging Type: Bottles, Tetra Packs, Cans, Pouches Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc., Dohler GmbH, Keurig Dr Pepper Inc., Monster Beverage Corporation, Archer Daniels Midland Co., Batory Foods, Cott Corporation, Royal Cosun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soft Drinks Concentrate Market Strategic Shifts
Reformulation science and dispensing technology are converging to reshape how concentrate manufacturers capture value, with regulatory pressure on sugar content and refrigerant chemistry forcing simultaneous adaptation across product and equipment dimensions.
Aseptic cold-fill concentrate processing is electrifying fountain supply economics by eliminating thermal degradation of heat-sensitive natural flavors while enabling ambient distribution logistics. Quick-service operators in the United States are retrofitting existing fountain towers with compatible bag-in-box connectors at accelerating pace. This technology compression is collapsing the traditional trade-off between clean-label positioning and supply chain cost efficiency.
EU F-Gas Regulation mandates are cascading through fountain equipment supply chains, prohibiting new installations using refrigerants with global warming potential above specified thresholds after 2025. Equipment manufacturers are engineering alternative cooling architectures using hydrocarbon or CO2-based systems. Concentrate suppliers must now validate viscosity and carbonation uptake performance across wider temperature operating ranges, particularly affecting deployment in Southern European markets with limited climate-controlled storage.
Café channel procurement is consolidating around multi-flavor dispensing platforms that rotate seasonal concentrates through shared equipment infrastructure. Independent coffee chains in São Paulo, Mexico City, and Mumbai are displacing bottled ready-to-drink alternatives with on-tap herbal and tropical formulations. This behavior shift is most visible in urban clusters where real estate constraints favor smaller-format dispensing over packaged beverage cooler footprint.
Global Soft Drinks Concentrate Market Segmentation
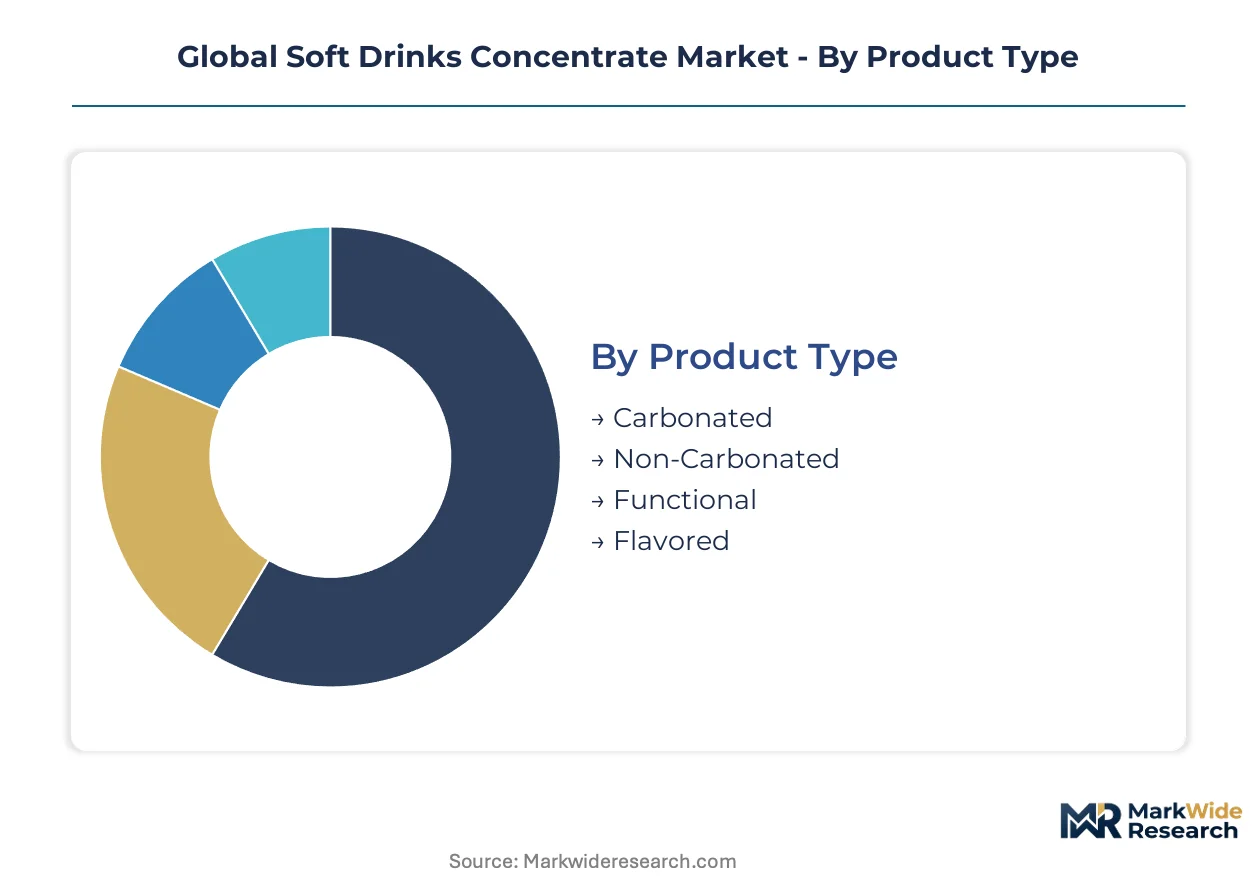
Soft drinks concentrate manufacturers engineer distinct formulations for each channel's equipment constraints and margin structures. Product specifications diverge sharply between fountain-dispensed foodservice applications and retail-packaged concentrate formats.
Product Type:
Buyers in this category differentiate by carbonation compatibility and health-positioning requirements rather than price alone.
- Carbonated:These concentrates contain calibrated acidulants and flavor systems engineered for post-mix carbonation uptake in fountain equipment. Demand concentrates in quick-service restaurant chains across Brazil, India, and Mexico as drive-thru beverage programs expand. Full-sugar cola bases still dominate volume, though reformulation pressure from sugar taxation frameworks is accelerating high-intensity sweetener adoption.
- Functional:Electrolyte-enhanced and botanical-infused formulations capture premium margin pools in gym chains and workplace wellness programs. Manufacturers leverage membrane filtration advances to preserve heat-sensitive active compounds while achieving ambient shelf stability. FDA GRAS determinations govern added vitamin and mineral claims in the United States.
- Non-Carbonated:Tropical and herbal flavor profiles serve café channel diversification beyond cola-centric menus, particularly in São Paulo and Mumbai urban clusters.
- Flavored:Clean-label natural extracts compete on aromatic intensity against synthetic flavor systems in European markets subject to EU REACH additive restrictions.
Volume sits with Carbonated; growth tilts toward Functional.
End User:
Procurement patterns in this category split between centralized fountain supply contracts and fragmented retail distribution economics.
- Restaurants:Quick-service operators are converting from post-mix powder systems to liquid concentrate dispensing, pulling volume through bag-in-box logistics that eliminate intermediate bottling steps. Chains in Mexico and India are retrofitting equipment to capture value previously extracted by packaged goods distributors.
- Cafes:Independent coffee chains in São Paulo, Mexico City, and Mumbai are displacing bottled ready-to-drink alternatives with on-tap herbal and tropical formulations. Real estate constraints favor smaller-format dispensing over packaged beverage cooler footprint.
- Retailers:Supermarket and convenience store channels rely on bottled concentrate formats for home dilution, though this segment faces compression as fountain infrastructure consolidates control.
- Wholesale Distributors:These intermediaries serve fragmented foodservice accounts lacking direct manufacturer relationships, particularly in secondary Indian cities.
Restaurants command the largest volume share; cafes are climbing the fastest.
Packaging Type:
Packaging selection in this category trades off shelf-life extension against equipment compatibility and logistics cost.
- Bottles:PET and glass formats dominate retail shelf presence for home-use concentrate, with specifications varying by market sugar taxation exposure.
- Tetra Packs:Aseptic carton systems enable ambient distribution of clean-label concentrates lacking synthetic preservatives, though tropical ambient storage remains a constraint.
- Cans:Aluminum formats serve single-serve dilution occasions in convenience channels, particularly in Mexican and Brazilian markets.
- Pouches:Flexible bag-in-box systems are electrifying fountain supply economics through direct-store-delivery bypass, with quick-service operators in the United States retrofitting compatible connectors at accelerating pace.
Bottles retain volume leadership; pouches are gaining share fastest through foodservice channel conversion.
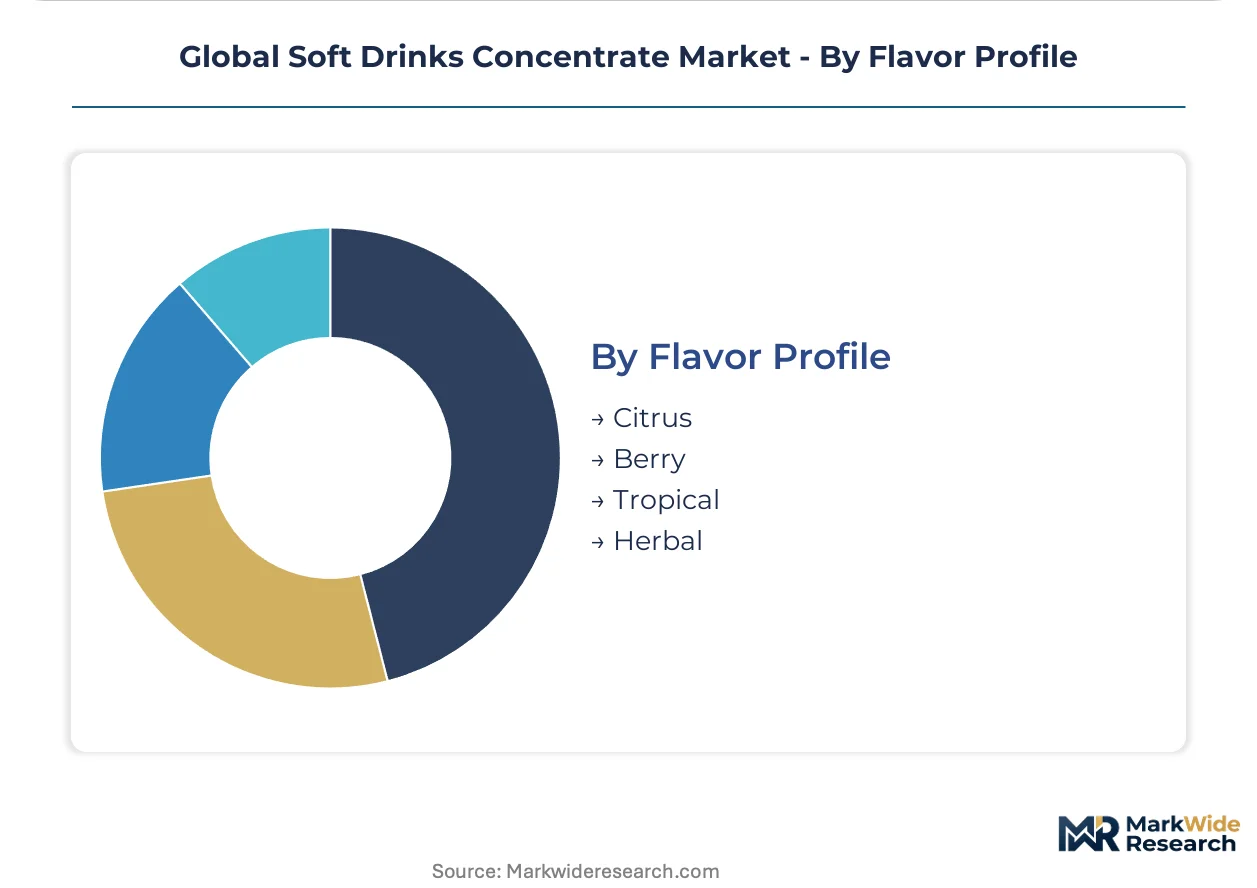
Flavor Profile:
Flavor preferences in this category track regional palate variation and health-positioning trends rather than global standardization.
- Citrus:Lemon-lime and orange systems anchor mature fountain portfolios, with formulation adjustments for high-intensity sweetener synergy in reduced-sugar variants.
- Tropical:Mango, passionfruit, and guava concentrates are expanding fastest in Brazilian and Indian café channels as operators diversify beyond cola-centric menus.
- Berry:Cranberry and mixed berry profiles serve functional beverage convergence with antioxidant positioning, though natural color stability challenges clean-label formulation.
- Herbal:Botanical-infused concentrates capture premium positioning in European wellness channels, with EFSA health claim assessments governing functional marketing.
Citrus maintains volume dominance; tropical profiles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrate production clusters in Germany and the United States, while consumption growth concentrates in Brazil, India, and Mexico as foodservice infrastructure expands.
United States
Fountain-dispensed beverage programs at quick-service chains drive concentrate volume through bag-in-box logistics. FDA GRAS determinations govern formulation inputs for functional concentrates with added vitamins. Atlanta anchors North American concentrate manufacturing through extensive foodservice partnership networks.
Germany
Equipment replacement cycles accelerate under EU F-Gas Regulation mandates for low-global-warming-potential refrigerants. ECHA REACH restrictions shape clean-label formulation decisions for natural flavor concentrates. Bavaria hosts specialized suppliers engineering compatible syrup formulations for hydrocarbon-cooled fountain systems.
Brazil
Drive-thru beverage expansion converts quick-service operators from powder to liquid concentrate dispensing. ANVISA labeling requirements influence front-of-pack communication for reduced-sugar variants. São Paulo urban clusters displace bottled ready-to-drink alternatives with on-tap tropical formulations in café channels.
India
FSSAI mandates on sugar content and labeling drive reformulation investments for domestic foodservice growth. Production-linked incentive schemes enable greenfield concentrate manufacturing capacity for regional export. Maharashtra and Karnataka industrial corridors concentrate new processing infrastructure serving quick-service restaurant networks.
Mexico
Sugar taxation frameworks alter concentrate economics, pushing manufacturers toward high-intensity sweetener blends. Quick-service chains retrofit equipment to capture value previously extracted by packaged goods distributors. Mexico City metro area anchors café channel procurement for multi-flavor dispensing platforms.
Global Soft Drinks Concentrate Market Competitive Environment
Top-tier vendors anchor fountain supply contracts with quick-service chains, while mid-tier specialists compete on clean-label formulations and regional foodservice penetration. The vendor base stratifies across three archetypes: integrated beverage conglomerates controlling equipment ecosystems, natural ingredient specialists competing on aromatic intensity, and private-label suppliers serving fragmented wholesale accounts. Dominant competitive moves include strategic partnerships with fountain equipment manufacturers and portfolio diversification into functional beverage bases.
Within the integrated beverage tier, The Coca-Cola Company and PepsiCo Inc. occupy positions defined by fountain infrastructure control and foodservice network density. Dohler GmbH exemplifies the natural formulation specialist archetype, competing on clean-label positioning against commodity suppliers. These three anchors represent distinct strategic vectors: equipment-integrated volume leadership, aromatic compound specialization, and regional private-label flexibility.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc. |
| Dohler GmbH |
| Keurig Dr Pepper Inc. |
| Monster Beverage Corporation |
| Archer Daniels Midland Co. |
| Batory Foods |
| Cott Corporation |
| Royal Cosun |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap flavor houses in Southern Germany and Northern Italy anchor premium concentrate supply, translating aromatic compound specialization into pricing discipline that commodity suppliers struggle to replicate. Their captive extraction facilities insulate margin structures from volatile natural extract spot markets while forcing price premiums for clean-label formulations.
Pricing Analysis
Margin tightening in functional concentrate tiers reflects stevia glycoside supply concentration in China and membrane filtration equipment lead times stretching 18-24 months. Three-tier pricing structure across premium, standard, and economy levels separates EU REACH-compliant natural extracts from synthetic flavor systems and private-label commodity bases. Price differentiation hinges on certification grade (FDA GRAS self-affirmed versus third-party validated) and volume scale in fountain supply contracts. Quick-service restaurant procurement teams show highest price sensitivity, while gym chains and workplace wellness programs absorb premiums for electrolyte-enhanced positioning.
Supply Chain Analysis
Direct-to-fountain bag-in-box channels handle hyperscale quick-service demand, eliminating intermediate bottling steps that previously extracted value through packaged goods distributors. Concentrate manufacturing clusters in Germany, the United States, and India draw from beet sugar supply in France and Germany, high-intensity sweetener inputs from China, and natural flavor extracts from Madagascar and Indonesia. Single-source vulnerability in sucralose production creates tariff exposure risk if trade policy shifts disrupt cross-Pacific chemical flows. Distribution runs through foodservice network partnerships anchored by equipment-integrated suppliers rather than fragmented wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor chemist talent scarcity props pricing for formulation services, constraining new product development velocity across mid-tier suppliers and sustaining incumbent margin capture.
For Market Incumbents: Cement fountain equipment ecosystem control through exclusive syrup formulation partnerships that lock in quick-service restaurant retrofit cycles. Expand backward integration into natural extract cultivation in Madagascar and Indonesia to secure aromatic compound supply against climate volatility. Prioritize EU F-Gas Regulation compliance investments in hydrocarbon-cooled dispensing compatibility to defend German and Italian foodservice contracts.
For New Entrants and Emerging Players: The gap between premium functional concentrates and economy cola bases offers entry space for mid-positioned botanical-infused formulations targeting independent café chains. White-space concentrates in tropical flavor profiles for Brazilian and Indian urban clusters, plus aseptic cold-fill processing capabilities for clean-label positioning without synthetic preservatives. Pursue direct-store-delivery partnerships with quick-service operators retrofitting from powder to liquid concentrate systems.
For Investors and Strategic Acquirers: Accelerating equipment replacement cycles under EU F-Gas mandates are the leading indicator that fountain infrastructure consolidation will concentrate volume among syrup suppliers with validated low-temperature performance. Long-term viability favors specialists with captive natural extraction capabilities and membrane filtration IP. Monitor ANVISA and FSSAI labeling mandate implementation timelines for reformulation investment spikes that strain mid-cap balance sheets.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Processing Scale-Up | Preserves heat-sensitive natural flavors while enabling ambient distribution economics in tropical markets. |
| Backward Integration into Natural Extract Cultivation | Secures aromatic compound supply against Madagascar and Indonesia climate volatility and price spikes. |
| Fountain Equipment Partnership Expansion | Locks in quick-service restaurant retrofit cycles through exclusive syrup formulation compatibility. |
| Functional Beverage Base Diversification | Captures gym chain and workplace wellness margin pools with electrolyte-enhanced positioning. |
| India PLI-Aligned Manufacturing Capacity | Enables greenfield concentrate production serving domestic foodservice growth and regional export. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews with fountain equipment engineers, quick-service restaurant procurement directors, flavor chemists at natural extract suppliers, and foodservice distribution channel managers. FDA GRAS determinations, ECHA REACH substance restrictions, and FSSAI labeling mandates provided formulation compliance benchmarks. Bottom-up volume modeling triangulated against top-down value estimates from concentrate manufacturing capacity assessments.
Reconciliation of shipment data, equipment installation records, and foodservice contract disclosures informed segmentation modeling across carbonated, functional, and non-carbonated product types; restaurant, café, and retail end-use channels; and bag-in-box, bottle, and tetra pack formats. CAGRs derived from fountain infrastructure deployment curves and emerging market foodservice expansion trajectories. Sugar taxation framework implementation timelines and EU F-Gas Regulation phase-down schedules served as policy scenario inputs.
Inputs from trade associations and regulatory databases were available through the study window; gaps in real-time foodservice contract terms and private-label pricing introduce uncertainty bands around channel share estimates. Forecasts reflect documented assumptions on equipment replacement cycles and reformulation investment pacing. Practitioners should monitor ANVISA front-of-pack labeling rulemaking and India PLI scheme disbursement rates for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Soft Serves Market
Beverages
Global Electrolyte Drinks Market
Beverages
Fusion Beverages Market
Beverages
Fruit Juice Market
Beverages
Powdered Beverages Market
Beverages
Fruit Beverages Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Hot Beverages Market
Beverages
Herb Infused Water Market
Beverages
Indonesia Bottled Water Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Soy Drinks Market
Beverages
North America Kombucha Market
Beverages
Blenders Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Packaged Natural Mineral Water Market