
 Ready to Drink Shakes Market | 2026-2036
Ready to Drink Shakes Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Drink Shakes Market Intelligence
E-commerce distribution is fragmenting as direct-to-consumer platforms and specialized health portals capture share from traditional retail. Premier Protein leverages its manufacturing scale to anchor shelf presence in mass retail channels. Orgain competes through organic certification and plant-based positioning that appeals to clean-label consumers. Muscle Milk dominates sports nutrition positioning with protein density formulations that sustain gym-based sales.
Ready to drink shakes are pre-mixed, shelf-stable beverages typically containing 15-40 grams of protein per serving, manufactured through ultra-high temperature processing and aseptic filling to achieve ambient storage stability. Protein shakes lead volume as the most mature category with established consumer habits, while functional shakes represent the fastest-growing segment as adaptogen and nootropic formulations attract premium pricing. Meal replacement shakes concentrate margin pools among weight management consumers seeking complete macronutrient profiles.
FDA nutrition labeling rules and EFSA health claim regulations shape permissible marketing language and substantiation requirements across formulations. The USDA organic seal and EU organic certification create tiered market access based on ingredient sourcing standards. Stakeholders must monitor evolving protein source regulations around novel ingredients and sustainability disclosure mandates.
Market Dynamics
Clean-label formulation mandates from the FDA and EFSA are compressing formulation cycles and forcing manufacturers to revalidate supply chains for novel protein sources and natural stabilizers.
Growth Catalysts
- Fitness Culture Normalization:Gym memberships and home workout equipment adoption in the United States and Germany have institutionalized post-exercise protein consumption as a daily ritual rather than niche athletic behavior.
- REACH and CSRD Compliance:European sustainability disclosure requirements are accelerating packaging innovation toward recyclable mono-material bottles and carbon footprint labeling that commands shelf preference.
- UHT-Aseptic Processing:Advances in ultra-high temperature sterilization and barrier packaging are extending ambient shelf life without refrigeration dependency, unlocking convenience store and vending distribution.
Market Restraints
- Whey Protein Price Volatility:Dairy commodity fluctuations and energy-intensive drying processes create margin pressure that constrains mid-tier brand pricing flexibility.
- Novel Ingredient Approval Timelines:EFSA novel food dossier requirements and FDA GRAS self-affirmation complexity delay algae, insect, and fermented protein market entry by 18-36 months.
- Sugar Reduction Technical Limits:Stevia aftertaste and texture degradation from sugar alcohols restrict clean-label sweetness optimization without consumer acceptance trade-offs.
Strategic Opportunities
- Geriatric Nutrition Penetration:Japan's aging demographic and METI functional foods framework create demand for high-protein, low-viscosity shakes targeting sarcopenia prevention in institutional care.
- Direct-to-Consumer Subscription Models:Personalized nutrition platforms using biometric data integration are capturing lifetime value through recurring revenue versus transactional retail.
- Adaptogen-Functional Convergence:Ashwagandha, lion's mane, and L-theanine formulations are opening premium positioning beyond protein density toward stress and cognitive performance claims.
Industry Challenges
- Clean-Label Formulation Expertise Scarcity:Food scientists capable of balancing shelf stability, mouthfeel, and minimal ingredient decks command compensation premiums that strain R&D budgets.
- Co-Manufacturer Capacity Constraints:Aseptic filling line availability bottlenecks at contract manufacturers are extending production lead times and constraining new product velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Drink Shakes Market |
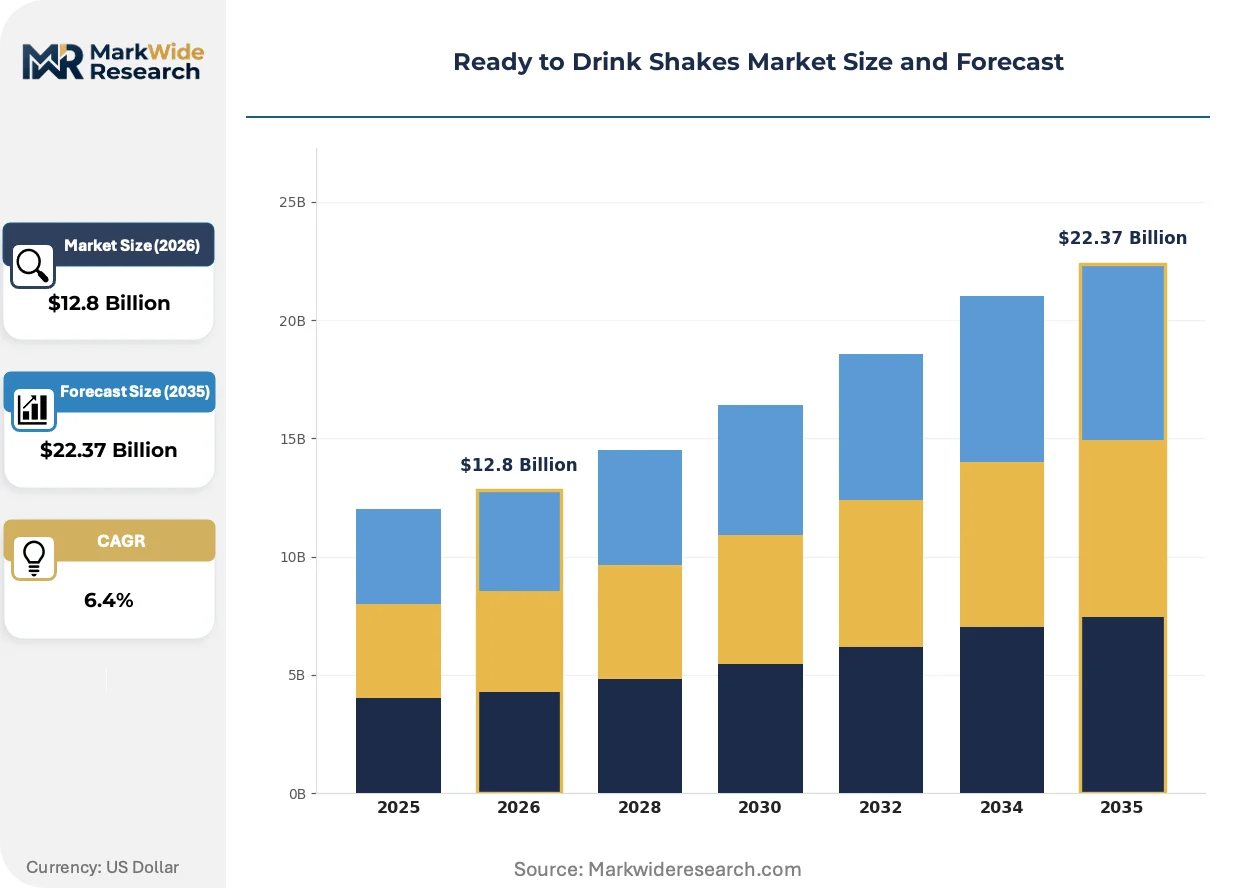
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Shakes, Meal Replacement Shakes, Nutritional Shakes, Functional Shakes Flavor Profile: Chocolate, Vanilla, Strawberry, Coffee Distribution Channel: Supermarkets, Health Stores, Online Retail, Gyms Target Audience: Athletes, Fitness Enthusiasts, Weight Watchers, Busy Professionals |
| Companies Covered | Premier Protein, Orgain, Muscle Milk, Ensure, Boost, Naked Nutrition, Soylent, Atkins Nutritionals, Fairlife, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Drink Shakes Market Strategic Shifts & Innovations
Processing technology convergence and regulatory disclosure mandates are compressing traditional competitive advantages in formulation secrecy while elevating transparency and sustainability verification as differentiation vectors.
Precision fermentation-derived whey and casein alternatives are achieving functional parity with dairy proteins at commercial scale. Brands targeting climate-conscious consumers in Germany and the United Kingdom are reformulating around these ingredients. Animal-free protein identity is rendering obsolete the pasture-to-bottle traceability claims that dominated premium positioning through 2023.
EFSA health claim substantiation requirements and FDA nutrition labeling updates are tightening permissible marketing language around muscle maintenance and satiety. Companies must now invest in clinical trial infrastructure or license existing approved claims. Meal replacement formulations in Europe face the steepest compliance burden as weight management assertions attract heightened scrutiny.
Subscription-based replenishment models are displacing impulse-driven grocery purchases among core users. Specialized health portals and brand-owned storefronts capture recurring revenue while eroding mass retail foot traffic. This channel rotation is most pronounced in the United States, where Prime delivery expectations have normalized just-in-time home stocking over pantry loading.
Ready to Drink Shakes Market Segmentation
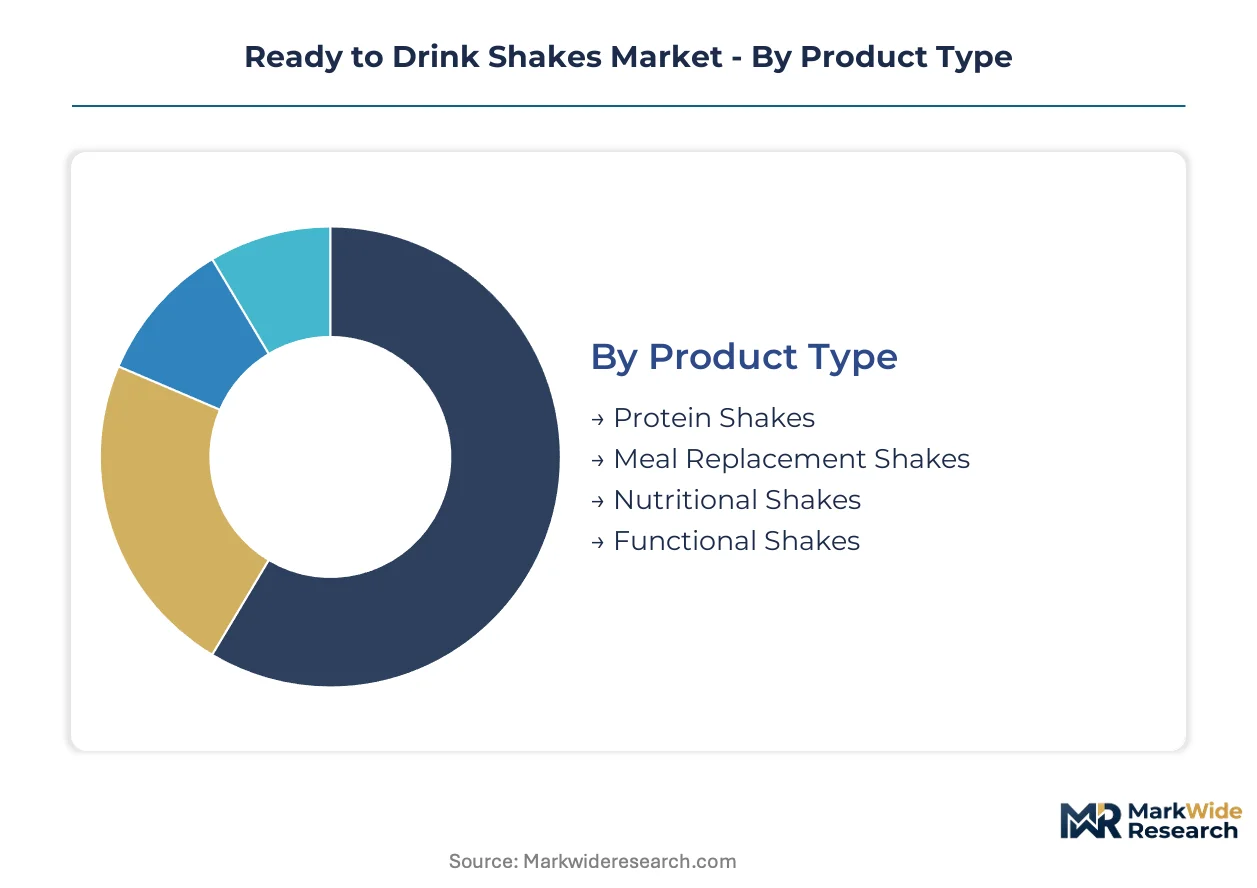
Segmentation in the ready to drink shakes market reveals how formulation specifications, channel access, and consumer lifestyle patterns create distinct margin pools. Understanding these divisions enables manufacturers to align R&D investment with the highest-velocity demand corridors and optimize shelf positioning across fragmented retail environments.
Product Type:
After-sales intensity varies sharply across product types, with functional shakes demanding ongoing consumer education and subscription support while protein shakes rely on established consumption rituals with minimal service interaction.
- Protein Shakes:Pre-mixed beverages delivering 15-40 grams of protein per serving through UHT processing and aseptic filling. Demand concentrates among gym-based consumers in the United States and Germany where post-workout consumption has become a daily ritual rather than niche athletic behavior. Whey protein price volatility and clean-label formulation mandates from the FDA and EFSA compress margin flexibility for mid-tier brands.
- Meal Replacement Shakes:Complete macronutrient formulations targeting weight management consumers seeking satiety and nutritional completeness. Demand clusters among institutional care settings and subscription-based direct-to-consumer platforms where recurring revenue models capture lifetime value. EFSA health claim substantiation requirements impose the steepest compliance burden as weight management assertions attract heightened scrutiny.
- Nutritional Shakes:Balanced formulations targeting general wellness and dietary supplementation needs. Geriatric nutrition penetration in Japan's aging demographic creates demand for high-protein, low-viscosity variants under METI functional foods framework.
- Functional Shakes:Adaptogen and nootropic formulations incorporating ashwagandha, lion's mane, and L-theanine. Precision fermentation-derived proteins and novel ingredient approval timelines from EFSA and FDA delay algae and fermented protein market entry by 18-36 months.
Protein shakes hold the largest share; momentum sits with functional shakes.
Flavor Profile:
Flavor selection operates as a cost-tier discriminator, with premium positioning commanding shelf space through exotic variants while mass-market penetration depends on familiar profiles that minimize trial risk.
- Chocolate:The most mature flavor category with established consumer habits and supply chain optimization. Dominates mass retail shelf presence in the United States and United Kingdom through Premier Protein and Muscle Milk distribution scale.
- Vanilla:Clean-label formulation compatibility makes vanilla a preferred base for organic certification and plant-based positioning that appeals to EFSA and FDA compliance-focused consumers in Germany.
- Strawberry:Sugar reduction technical limits constrain strawberry formulations as stevia aftertaste and texture degradation from sugar alcohols restrict clean-label sweetness optimization without consumer acceptance trade-offs.
- Coffee:Caffeine-adjacent functional positioning attracts busy professionals seeking meal replacement convenience with cognitive performance claims. Coffee flavor penetration concentrates in United States direct-to-consumer channels where subscription models displace impulse-driven grocery purchases.
Chocolate dominates volume; coffee is expanding most quickly.
Distribution Channel:
Channel selection determines margin structure, with specialized health portals capturing premium pricing through curation while mass retail optimizes throughput via manufacturing scale and shelf presence.
- Supermarkets:Premier Protein leverages manufacturing scale to anchor shelf presence through mass retail channel dominance. Co-manufacturer capacity constraints at aseptic filling lines extend production lead times and constrain new product velocity for shelf-stable distribution.
- Health Stores:Orgain competes through organic certification and plant-based positioning that appeals to clean-label consumers seeking curated product discovery. REACH and CSRD compliance requirements accelerate packaging innovation toward recyclable mono-material bottles that command shelf preference in European health stores.
- Online Retail:E-commerce distribution fragmentation captures share from traditional retail as direct-to-consumer platforms and specialized health portals enable personalized nutrition platforms using biometric data integration. Prime delivery expectations in the United States normalize just-in-time home stocking over pantry loading.
- Gyms:Muscle Milk dominates sports nutrition positioning with protein density formulations that sustain gym-based sales. Fitness culture normalization in Germany and the United States institutionalizes post-exercise protein consumption as a daily ritual.
Supermarkets retain the largest share; online retail is gaining share fastest.
Target Audience:
Audience segmentation maps directly to application intensity, with athletes and fitness enthusiasts driving volume through habitual consumption while weight watchers and busy professionals create premium pricing opportunities through convenience valuation.
- Athletes:Protein density formulations with 30-40 grams per serving target competitive and recreational athletes with elevated macronutrient requirements. UHT-aseptic processing advances extend ambient shelf life without refrigeration dependency, unlocking convenience store and vending distribution for on-the-go athletic consumption.
- Fitness Enthusiasts:Home workout equipment adoption and gym membership growth in the United States and Germany normalize post-exercise protein consumption beyond niche athletic behavior. Clean-label formulation expertise scarcity strains R&D budgets as food scientists capable of balancing shelf stability and minimal ingredient decks command compensation premiums.
- Weight Watchers:Meal replacement formulations concentrate margin pools among consumers seeking complete macronutrient profiles with controlled caloric density. FDA nutrition labeling rules and EFSA health claim regulations tighten permissible marketing language around satiety assertions.
- Busy Professionals:Adaptogen-functional convergence attracts premium positioning beyond protein density toward stress and cognitive performance claims. Subscription-based replenishment models capture recurring revenue from time-constrained consumers in the United States where specialized health portals erode mass retail foot traffic.
Fitness enthusiasts represent the largest addressable base; busy professionals show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and the United Kingdom where EFSA compliance costs and clean-label certification create margin buffers, while mid-tier brands in the United States absorb commodity volatility through manufacturing scale.
United States
Fitness culture normalization and Prime-enabled subscription models drive habitual consumption among gym-goers and busy professionals. FDA nutrition labeling rules tighten permissible marketing language around muscle maintenance claims. Southern California and Texas host the densest concentrations of co-manufacturing capacity for aseptic filling lines serving mass retail distribution.
Germany
REACH and CSRD compliance requirements accelerate packaging innovation toward recyclable mono-material bottles that command shelf preference. EFSA health claim substantiation rules impose steep compliance burdens on weight management formulations. Bavaria anchors organic certification demand through its food manufacturing clusters around Munich.
United Kingdom
Precision fermentation-derived protein adoption advances fastest among climate-conscious consumers seeking animal-free alternatives. EFSA-aligned regulatory scrutiny post-Brexit maintains stringent novel food approval timelines. London and the Southeast concentrate direct-to-consumer platform headquarters capturing subscription revenue from time-constrained professionals.
Japan
METI functional foods framework creates institutional demand for geriatric nutrition targeting sarcopenia prevention in aging care facilities. PMDA oversight ensures rigorous safety substantiation for adaptogen and nootropic formulations. Kanto region manufacturers lead low-viscosity formulation development for elderly swallowing compatibility.
Canada
Health Canada regulations align with FDA frameworks while permitting distinct natural health product claims that attract cross-border formulation testing. Prairie dairy supply chains feed protein isolate production for export-oriented brands. Ontario and Quebec host the primary co-packing infrastructure serving North American ambient shelf-stable distribution.
Ready to Drink Shakes Market Key Industry Players
Mass-market scale players and clean-label specialists split the market into divergent margin architectures. Three to four manufacturers control shelf presence in supermarkets through manufacturing scale and slotting fee capacity, while mid-tier entrants compete through subscription models and health portal curation. Strategic archetypes include dairy-integrated commodity producers, organic-certified plant-based formulators, and precision fermentation technology licensees. Dominant competitive moves center on co-manufacturer capacity capture and direct-to-consumer platform buildout.
Within the mass-market tier, Premier Protein and Muscle Milk occupy positions anchored by retail distribution density and protein density formulations respectively. Orgain exemplifies the clean-label specialist archetype through organic certification and plant-based positioning. These three entities represent the strategic poles—scale-driven dairy integration, sports nutrition density, and certified organic differentiation—around which smaller competitors cluster.
| Leading Market Players |
|---|
| Premier Protein |
| Orgain |
| Muscle Milk |
| Ensure |
| Boost |
| Naked Nutrition |
| Soylent |
| Atkins Nutritionals |
| Fairlife |
| Others |
Cost & Logistics Intelligence
Whey protein price volatility compresses margin flexibility across all tiers while simultaneously forcing manufacturers toward backward integration into dairy processing or precision fermentation alternatives. This commodity exposure widens spreads between mass-market brands anchored in manufacturing scale and premium specialists commanding certification premiums through organic supply chains.
Pricing Analysis
The customization-premium spread separates subscription-configured functional shakes from standard protein formulations in mass retail. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and protein source transparency, with EFSA organic seals and animal-free protein identity commanding shelf price premiums. Pricing pressure stems from stevia aftertaste remediation costs and sugar alcohol texture engineering in clean-label reformulations. Mass-market gym consumers exhibit highest price sensitivity; geriatric nutrition and adaptogen-functional segments show lowest sensitivity due to health outcome valuation.
Supply Chain Analysis
Upstream feedstock concentration centers on United States dairy cooperatives, German organic ingredient processors, and United Kingdom precision fermentation facilities. Aseptic filling lines, barrier packaging films, and UHT sterilization equipment constitute critical component dependencies. Single-source vulnerability concentrates at co-manufacturer capacity bottlenecks extending production lead times. Distribution runs through mass retail supermarkets, specialized health portals, and direct-to-consumer subscription platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities concentrate in subscription-based replenishment models and biometric-integrated personalized nutrition platforms, both expanding faster than transactional retail hardware. Recurring revenue capture through direct-to-consumer channels outpaces one-time purchase velocity in established segments.
For Market Incumbents: Pre-empt precision fermentation protein adoption by securing exclusive licensing agreements with alternative dairy technology providers before EFSA novel food approvals accelerate competitive entry. Defend shelf position through captive aseptic filling capacity additions in Southern California and Texas manufacturing clusters. Co-manufacturer capacity constraints threaten new product velocity; backward integration into UHT processing insulates against production bottlenecks. For New Entrants and Emerging Players: Pursue geriatric nutrition penetration in Japan's institutional care settings where METI functional foods framework creates regulatory clarity absent in Western markets. Target busy professional segments through adaptogen-functional convergence with ashwagandha and lion's mane formulations. White-space exists in low-viscosity high-protein shakes for sarcopenia prevention; direct-to-consumer subscription with biometric data integration offers defensible go-to-market positioning against mass retail incumbents. For Investors and Strategic Acquirers: The market sits at a formulation transparency phase that favors clean-label specialists with organic certification and novel protein sourcing capabilities over commodity dairy-integrated scale players. Long-term viability across the next decade hinges on regulatory navigation expertise and co-manufacturer relationship depth. Acquisition targets should demonstrate EFSA health claim substantiation infrastructure or FDA GRAS self-affirmation capabilities. Signal to monitor: EFSA novel food approval acceleration for precision fermentation proteins as inflection indicator for technology-licensing value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Licensing | Animal-free whey alternatives achieve functional parity with dairy proteins at commercial scale in Germany. |
| Direct-to-Consumer Platform Buildout | Subscription models capture lifetime value from busy professionals through biometric-integrated personalization in United States. |
| Aseptic Filling Capacity Expansion | Co-manufacturer bottlenecks constrain new product velocity; captive production secures shelf-stable distribution access. |
| EFSA Health Claim Substantiation Investment | Clinical trial infrastructure enables permissible marketing language around muscle maintenance and satiety assertions. |
| Recyclable Mono-Material Packaging Transition | REACH and CSRD compliance commands shelf preference among climate-conscious consumers in United Kingdom health stores. |
Research Approach
The analysis maps protein shakes, meal replacement formulations, functional adaptogen blends, and geriatric nutrition variants, each validated through food science R&D directors, retail category buyers, co-manufacturer operations managers, and regulatory affairs specialists. Primary interviews with supply chain planners at dairy processors and precision fermentation technology providers combined with secondary validation from FDA nutrition labeling guidance documents, EFSA novel food approval databases, USDA organic certification records, and METI functional foods framework filings. Bottom-up volume modeling across distribution channels triangulates against top-down macroeconomic demand indicators.
Assumption sets held regulatory approval timelines and commodity price volatility bands fixed while varying subscription adoption rates and precision fermentation scale-up curves across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, distribution channel, and target audience with protein source origin as industry-specific overlay. CAGRs derive from historical consumption pattern analysis projected through fitness culture normalization curves and aging demographic trajectories. Forecast inputs incorporate gym membership growth rates and Prime-enabled delivery expectation penetration as demand proxies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation technology licensees or direct-to-consumer platform specialists would shift outcomes through accelerated channel rotation. Cross-checking against Nielsen retail audit data and customs records for protein isolate trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
United States Soy Beverages Market
Beverages
Superfood Infused Beverages Market
Beverages
Wellness Water Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Europe Bottled Water Market
Beverages
NFC JUICE Market
Beverages
Carbonate Drink Maker Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Global Squash Drinks Market
Beverages
Tonic Water Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
Ready to Drink Margarita Market
Beverages
Juice Market
Beverages
Water Bottle Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Botanical Infused Beverages Market