
 Aloe Vera Drinks Market | 2026-2036
Aloe Vera Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Aloe Vera Drinks Market Intelligence
The shift toward single-serving formats and value-oriented multi-packs is broadening consumer access to aloe vera drinks. This configuration allows for trial and convenience, appealing to new demographics. OKF Corporation leverages its extensive global distribution network to capitalize on this trend. Forever Living Products sustains its market presence through a direct sales model, while Patanjali Ayurved Limited competes by integrating Ayurvedic principles into its formulations for the Indian market.
Aloe vera drinks are beverages formulated with gel, juice, or concentrate extracted from the inner leaf of the Aloe barbadensis miller plant. These formulations often undergo stabilization and pasteurization processes to preserve bioactive compounds like polysaccharides and ensure shelf stability. Ready-to-drink juice formats dominate retail volume, sold primarily through supermarkets. Higher-margin gel products and concentrates find a dedicated customer base in specialized health stores and online retail channels.
Labeling and health claim regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) govern market access and marketing language. In India, the FSSAI sets standards for food additives and purity, impacting formulation choices for manufacturers targeting the region. Navigating the patchwork of international food safety and labeling standards remains a critical competency for brand expansion.
Market Dynamics
The central structural force shaping the aloe vera drinks market is the consumer-led push for functional beverages with transparent, clean-label ingredients. This demand pattern pressures manufacturers to ensure sourcing integrity and adopt transparent processing methods, all while navigating a complex web of international food safety standards.
Growth Catalysts
- Health and Wellness Integration:Consumer adoption of functional drinks into daily wellness routines, especially in established markets like South Korea and Germany, provides a consistent volume base and drives category growth.
- Clean-Label Mandates:Regulatory frameworks, including European Food Safety Authority (EFSA) guidelines on health claims, encourage brands to develop simpler, more natural formulations, which aligns with aloe vera's inherent properties.
- Format Innovation:The expansion of single-serving and value-oriented multi-pack configurations is broadening consumer access, allowing for easier trial and convenience that appeals to new demographics.
Market Restraints
- Aloin Content Regulation:Strict regulatory limits on aloin, a naturally occurring compound in the aloe leaf, by agencies such as the US FDA, necessitate expensive purification processes that increase final product cost.
- Agricultural Volatility:The supply of raw Aloe barbadensis miller leaf is exposed to climate-related risks, pest infestations, and logistical disruptions in primary cultivation zones, leading to input price instability.
- Functional Beverage Competition:Aloe vera drinks face intense shelf-space competition from a wide array of other functional beverages, including kombucha, coconut water, and plant-based protein drinks, for the same consumer segment.
Strategic Opportunities
- Emerging Market Penetration:Significant growth potential exists in Latin American and Southeast Asian markets, where rising disposable incomes and a growing interest in wellness trends create a receptive environment for new product entry.
- Functional Blends and Fortification:Formulating aloe vera drinks with complementary ingredients such as probiotics, vitamins, or adaptogens offers a pathway to create higher-margin, specialized products targeting specific health needs.
- Direct-to-Consumer Channels:Developing robust online D2C sales platforms enables brands to bypass traditional retail gatekeepers, cultivate direct customer relationships, and control brand messaging with greater precision.
Industry Challenges
- Navigating Regulatory Patchwork:Ensuring product compliance with a fragmented landscape of international food safety and labeling standards, from India's FSSAI to the US FDA, remains a critical and complex hurdle for global expansion.
- Bioactive Compound Preservation:A persistent technical challenge for manufacturers is maintaining the stability and efficacy of bioactive polysaccharides during commercial-scale pasteurization and processing without relying on artificial preservatives.
- Health Claim Substantiation:Brands must carefully balance educating consumers on the benefits of aloe vera with adhering to stringent regulations from bodies like EFSA that govern marketing language and health claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aloe Vera Drinks Market |
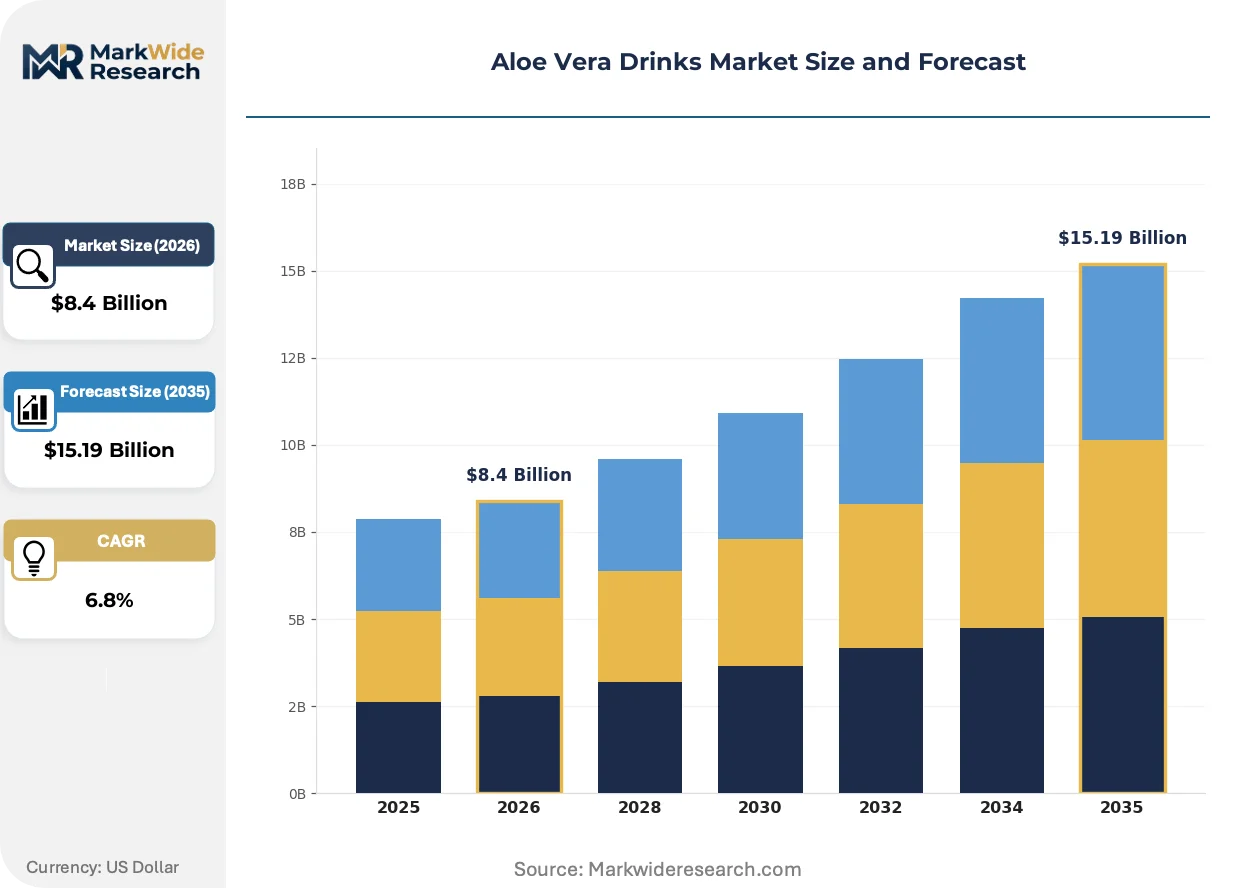
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juice, Gel, Powder, Concentrate End User: Retail Consumers, Food Service, Health Enthusiasts, Fitness Professionals Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Flavor: Original, Mango, Peach, Coconut |
| Companies Covered | OKF Corporation, ALO Drink, Forever Living Products, Lotte Chilsung Beverage, Patanjali Ayurved Limited, Houssy Global, Lily of the Desert, Herbalife Nutrition, Aloe Farms Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aloe Vera Drinks Market Strategic Shifts & Innovations
The aloe vera drinks market is evolving toward greater product integrity and supply chain visibility. Current innovations focus on preserving the plant's natural bioactivity while satisfying stringent clean-label requirements demanded by both regulators and increasingly educated consumers.
High-Pressure Processing (HPP) is a non-thermal pasteurization method used to preserve the bioactive compounds, flavor, and texture of fresh aloe vera juice. Premium and organic-focused brands are adopting HPP to appeal to consumers seeking minimally processed beverages. This technology is automating the move away from traditional heat treatments, enabling extended shelf life without the need for chemical preservatives.
European Food Safety Authority (EFSA) actions are tightening the requirements for botanical health claims, demanding robust scientific backing for any marketed benefits. This regulatory pressure compels manufacturers to either invest heavily in clinical research or shift marketing communications toward general wellness and naturalness. The higher-margin gel and concentrate segments, which often rely on specific functional claims, are most affected by this shift.
A distinct shift in consumption patterns sees consumers integrating aloe vera drinks into specific functional routines, such as post-workout recovery or daily digestive support. This behavioral change moves the product beyond a simple refreshment, disrupting its placement in the traditional juice aisle and carving out new space in dedicated wellness sections of retail stores. This trend is most visible in urban centers across North America and Europe.
Aloe Vera Drinks Market Segmentation
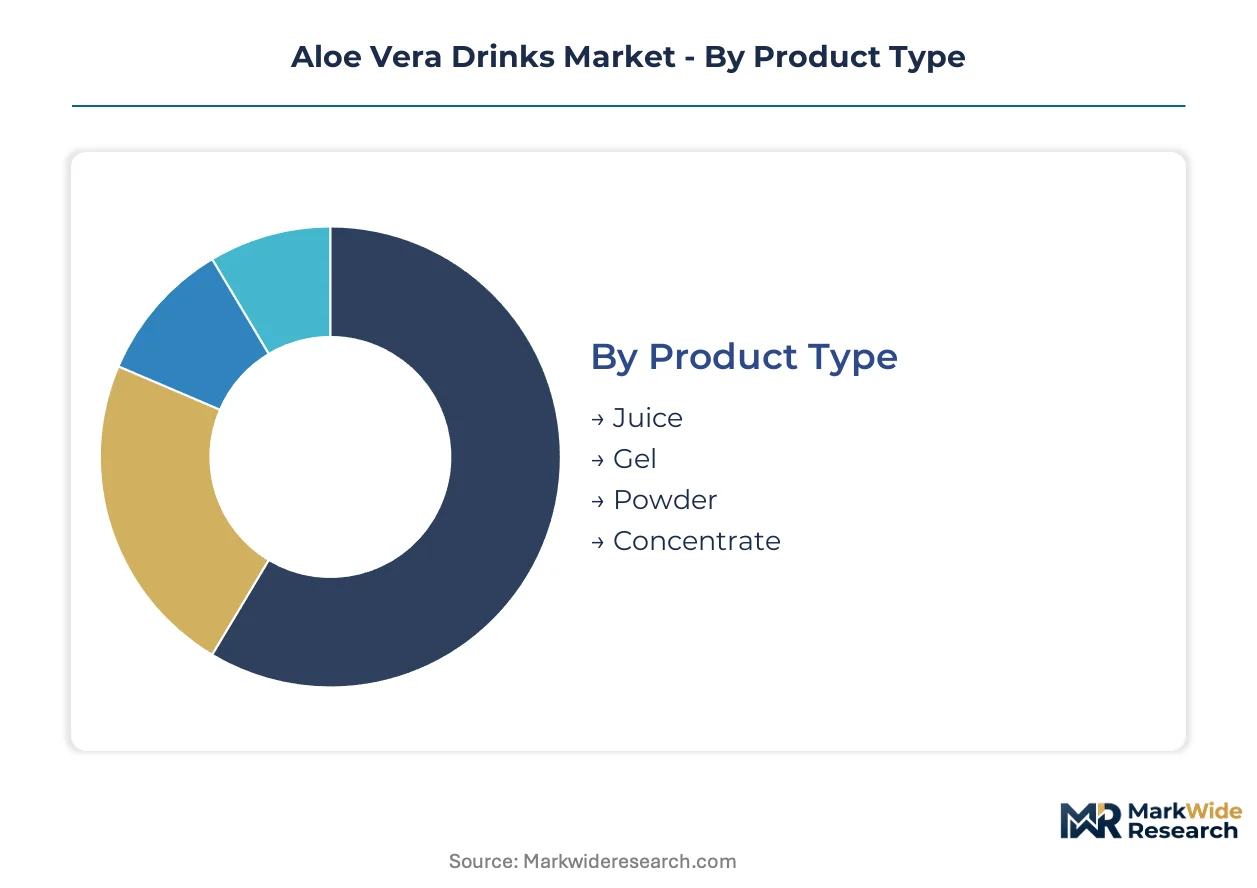
The aloe vera drinks market exhibits diverse consumer preferences and purchasing behaviors across various product forms and distribution channels. Understanding these segments helps manufacturers tailor formulations, marketing strategies, and supply chain logistics to capture specific consumer groups, from health-conscious individuals to food service providers.
Product Type:
What differentiates buyers in this category is their preference for the form factor and concentration of aloe vera in their beverage.
- Juice:These ready-to-drink beverages typically contain a high percentage of aloe vera juice, often blended with water or other fruit juices for palatability. Demand concentrates in supermarkets and convenience stores across North America and Europe, driven by its accessibility as a daily wellness drink.
- Gel:Formulations with a higher concentration of aloe vera gel offer a thicker texture and are often perceived to have more potent health benefits due to higher bioactive compound retention. Specialized health stores and online platforms in Germany and South Korea represent significant demand centers, appealing to consumers seeking premium functional products.
- Powder:Aloe vera powder is a dehydrated form of the gel or juice, offering extended shelf life and ease of incorporation into other food and beverage products. Manufacturers use powder as an ingredient in functional mixes or dietary supplements.
- Concentrate:These highly potent liquid forms require dilution before consumption, providing a cost-effective option for bulk users or those who prefer to customize their drink strength. Food service establishments and industrial ingredient buyers frequently procure concentrates.
Volume sits with Juice; growth tilts toward Gel.
End User:
Customer type defines consumption patterns and purchasing motivations within the aloe vera drinks market.
- Retail Consumers:Individual consumers purchasing aloe vera drinks for personal consumption through various retail outlets. This segment values convenience, flavor variety, and perceived health benefits for daily wellness routines.
- Food Service:Restaurants, cafes, hotels, and institutional caterers offering aloe vera drinks as part of their beverage menu. Bulk purchasing and consistent supply are critical for this segment.
- Health Enthusiasts:Individuals actively seeking functional beverages to support specific health goals like digestion, immunity, or detoxification. These consumers prioritize natural ingredients, clean labels, and scientific backing for health claims.
- Fitness Professionals:Athletes, trainers, and sports enthusiasts integrating aloe vera drinks into their pre- or post-workout recovery regimens. This group often seeks products with added electrolytes or protein.
Demand for Retail Consumers drives current market size, while Health Enthusiasts present future expansion.
Distribution Channel:
Accessibility and product visibility are paramount, determining how aloe vera drinks reach their target consumers.
- Online Retail:E-commerce platforms and brand-specific websites offer a broad selection of aloe vera drinks, including specialized and niche products. This channel provides convenience and direct access to a global customer base.
- Supermarkets:Large grocery chains and hypermarkets serve as primary points of sale for mass-market aloe vera juice products. High foot traffic and broad consumer reach define this channel.
- Health Stores:Specialty health food stores, pharmacies, and organic markets stock premium and organic aloe vera gel and concentrate products. These outlets cater to health-conscious consumers seeking natural and functional options.
- Direct Sales:Network marketing and multi-level marketing companies distribute aloe vera drinks directly to consumers through independent representatives. This model fosters personalized customer relationships and product education.
Accessibility through Supermarkets remains critical, with Online Retail gaining traction for specialized products.
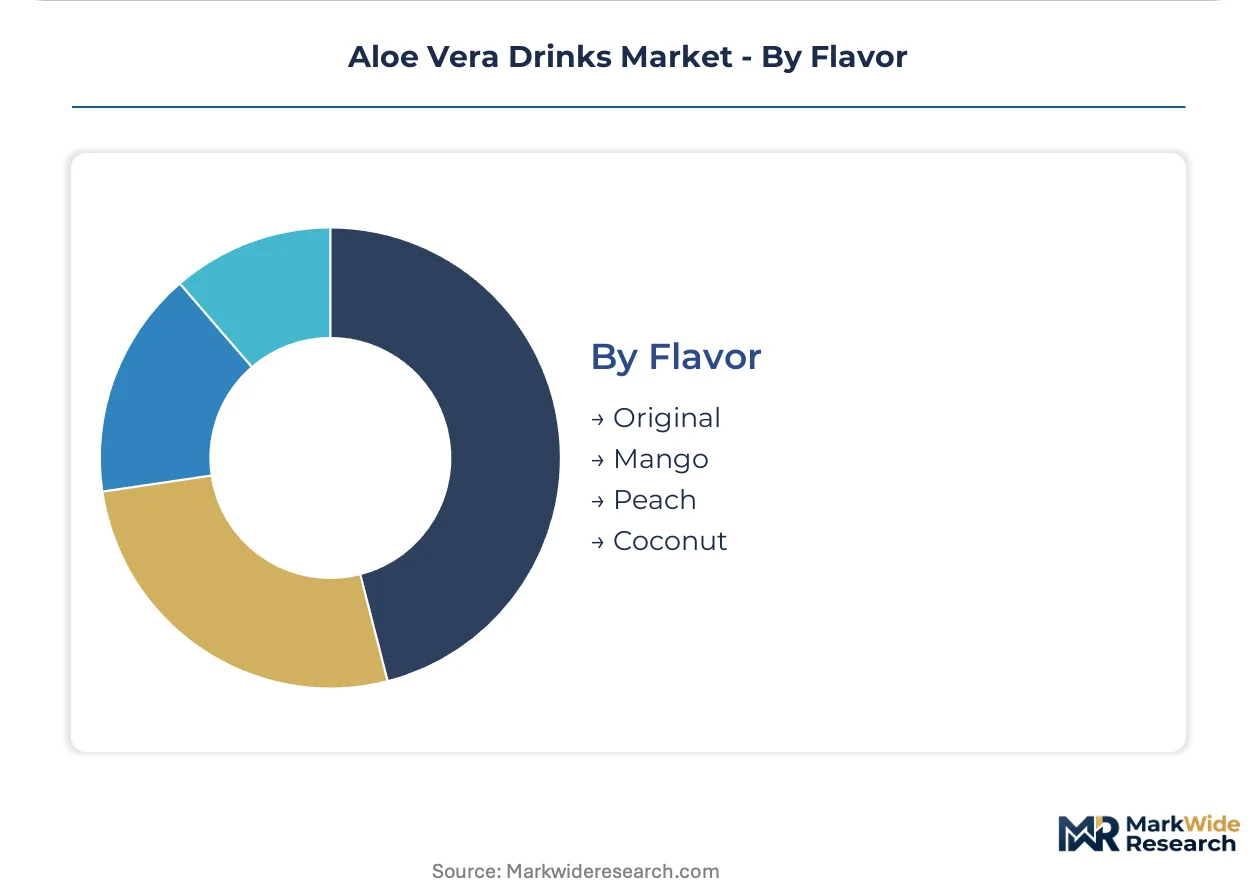
Flavor:
Consumer preference for taste profiles significantly influences product development and market appeal.
- Original:Unflavored aloe vera drinks, often preferred by consumers who appreciate the natural taste of aloe or intend to mix it with other beverages. This classic option emphasizes the inherent properties of the plant.
- Mango:Tropical fruit flavors like mango are popular additions, masking the natural bitterness of aloe vera and enhancing palatability. Mango-flavored aloe vera drinks appeal to a wide demographic seeking a sweet and refreshing taste.
- Peach:Peach offers a subtle sweetness and aromatic profile, making it another popular choice for flavored aloe vera beverages. This flavor often targets consumers who prefer a milder fruit taste.
- Coconut:Coconut flavor provides a unique, exotic, and often creamy taste profile, appealing to consumers seeking innovative and tropical beverage options. This flavor often aligns with wellness trends.
Core preference centers on Original, with Mango flavors attracting niche segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aloe vera drinks market exhibits a distinct split, with production often concentrated in agricultural zones, while consumption gravitates toward health-conscious urban populations. This dynamic necessitates robust supply chains and localized marketing efforts for brand penetration. Regulatory bodies across continents influence market entry and product formulation.
South Korea
South Korean consumers integrate functional beverages into daily wellness routines, driving consistent demand for aloe vera drinks. The country's Ministry of Food and Drug Safety (MFDS) sets purity standards for food ingredients, impacting local manufacturers. Seoul and Busan represent significant urban consumption hubs, where health and beauty trends often originate and quickly spread.
Germany
German consumers prioritize natural ingredients and transparent labeling, creating a strong market for premium aloe vera products. The European Food Safety Authority (EFSA) guidelines on health claims influence marketing language and product development. Major cities like Berlin and Munich show high per capita consumption, reflecting an established wellness culture.
United States
Health enthusiasts across the United States increasingly seek functional beverages for digestive support and overall wellness. The US FDA regulates the aloin content in aloe vera products, necessitating purification processes for market access. California's health-conscious demographic and innovative food scene drive new product adoption and consumption patterns.
India
Rising disposable incomes and a growing interest in Ayurvedic principles fuel demand for aloe vera drinks in India. The Food Safety and Standards Authority of India (FSSAI) establishes standards for food additives and purity, influencing local formulations. Urban centers like Mumbai and Delhi are experiencing rapid growth in functional beverage consumption.
Brazil
Brazilian consumers are increasingly adopting wellness trends, creating significant growth potential for aloe vera drinks in Latin America. ANVISA, Brazil's health surveillance agency, oversees food safety and ingredient approvals for beverages. São Paulo's large metropolitan area acts as a key distribution and consumption hub, reflecting evolving dietary preferences.
Aloe Vera Drinks Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a dynamic competitive environment within the aloe vera drinks market. The market structure is characterized by a mix of large beverage companies and niche health-focused brands. Strategic archetypes include global distributors leveraging scale and regional players focusing on specific cultural preferences. Geographic expansion and portfolio diversification represent dominant competitive moves.
Among established players, OKF Corporation exemplifies a global distribution network, enabling broad market reach across continents. Forever Living Products sustains its market presence through a direct sales model, cultivating personalized customer relationships. Patanjali Ayurved Limited anchors the Indian market by integrating traditional Ayurvedic principles into its formulations, appealing to a specific consumer segment.
| Leading Market Players |
|---|
| OKF Corporation |
| ALO Drink |
| Forever Living Products |
| Lotte Chilsung Beverage |
| Patanjali Ayurved Limited |
| Houssy Global |
| Lily of the Desert |
| Herbalife Nutrition |
| Aloe Farms Inc. |
| Others |
Cost & Logistics Intelligence
Aloin purification costs, a significant named cost component, trace from upstream processing requirements through to the final pricing tiers for premium aloe vera products. Raw material pricing for Aloe barbadensis miller leaf also influences finished goods costs.
Pricing Analysis
Cost-down pressure on mass-market aloe vera juice intensifies due to intense competition from other functional beverages. The dominant pricing structure features transactional per-unit sales for retail juice and contract-based long-term offtake for concentrates. Price differentiation stems from quality grade, such as organic certification, and specific brand premium. Health enthusiasts exhibit lower price sensitivity for premium gel products, while general retail consumers are highly sensitive to juice pricing.
Supply Chain Analysis
Workforce availability in primary cultivation regions like Mexico and India influences raw material harvesting and initial processing. The supply chain draws from geographically concentrated cultivation zones for Aloe barbadensis miller leaf. Key raw material dependencies include aloe leaf, water, and natural fruit concentrates for flavored variants. Agricultural volatility, including climate-related risks, represents a significant structural risk. Downstream distribution runs through a hybrid model combining mass-market retail channels with specialized online and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players increasingly pursuing upstream control over raw material sourcing and processing. Downstream, direct-to-consumer channels are also a key lever.
For Market Incumbents:
Extend existing global distribution networks into underpenetrated emerging markets, particularly in Latin America and Southeast Asia. Diversify product portfolios with functional blends incorporating probiotics or adaptogens to counter rising functional beverage competition. Invest in High-Pressure Processing (HPP) technology to maintain product integrity and meet clean-label demands. Scientific backing for health claims represents a crucial lever against regulatory scrutiny from bodies like the EFSA.
For New Entrants and Emerging Players:
Online retailers represent a strategic entry point for niche aloe vera products, bypassing traditional retail gatekeepers. Target the specialized functional blends segment by formulating products with complementary ingredients for specific health goals. Health enthusiasts seeking digestive support or immunity benefits represent the most penetrable consumer segment. A clean-label, organic positioning, supported by transparent sourcing, offers a compelling go-to-market angle.
For Investors and Strategic Acquirers:
Increased investment in clinical research for specific health claims is the leading indicator that brands are seeking long-term differentiation. The aloe vera drinks market offers long-term viability, driven by sustained global wellness trends and demand for natural ingredients. Acquisition targets should include brands with proprietary processing technologies like HPP or strong regional market share in high-growth countries. Regulatory harmonization across major markets, particularly concerning aloin content, signals a more stable operating environment.
| Strategic Initiative | Industry Significance |
|---|---|
| Raw Material Sourcing Partnerships | Secures consistent supply of Aloe barbadensis miller leaf amid agricultural volatility. |
| High-Pressure Processing (HPP) Adoption | Preserves bioactive compounds and extends shelf life for premium clean-label products. |
| Direct-to-Consumer (D2C) Channel Development | Cultivates direct customer relationships and enhances brand messaging control for manufacturers. |
| Functional Ingredient Blending | Creates higher-margin, specialized products targeting specific consumer health needs. |
| Regulatory Compliance and Certification Investment | Ensures market access and builds consumer trust across diverse international food safety standards. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. The study triangulated insights from primary interviews with beverage manufacturers, raw material suppliers, retail buyers, and food scientists. Both bottom-up and top-down approaches validated market size and growth projections.
Data-stream reconciliation integrated historical market performance with future projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-user, distribution channel, and flavor. Compound Annual Growth Rates (CAGRs) derived from a weighted average of historical trends and projected future demand. Consumer wellness spending trends and aloin purification technology advancements served as key industry-specific forecast inputs.
Caveats apply where major regulatory changes or significant climate events could materially shift the outlook. Forecasts reflect assumptions regarding consumer preferences and technological advancements. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fusion Beverages Market
Beverages
Germany Probiotic Drinks Market
Beverages
Europe Beverage Market
Beverages
Coconut Milk Beverages Market
Beverages
NFC JUICE Market
Beverages
Cold Pressed Juice Market
Beverages
South East Asia Bottled Water Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Root Beer Market
Beverages
Hot Chocolate Market
Beverages
Sparkling Bottled Water Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Fiber Fortified Beverages Market
Beverages
North America Juices Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Sparkling Soda Market