
 Global Beverage Emulsion Market | 2026-2036
Global Beverage Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beverage Emulsion Market Foresight
Multi-source ingredient procurement is repositioning how beverage formulators manage emulsion stability and cost volatility. Kerry Group leverages its integrated taste and nutrition platform to supply customized emulsion systems across carbonated and functional drink categories. Givaudan anchors its competitive stance through deep specialization in flavor-emulsion co-design for premium beverage portfolios. Cargill competes by controlling upstream hydrocolloid supply chains that underpin O/W emulsion matrices for dairy alternatives.
Beverage emulsions are thermodynamically unstable dispersions of immiscible liquids—typically oil droplets suspended in aqueous phase—stabilized by surfactants, proteins, or polysaccharides at particle sizes ranging from 0.1 to 100 micrometers. Their primary commercial purpose is to deliver lipophilic flavors, colors, vitamins, and bioactive compounds into hydrophilic beverage matrices while maintaining optical clarity and shelf stability. Nanoemulsion systems lead product-type innovation due to superior kinetic stability and enhanced nutrient absorption profiles. High pressure homogenization dominates formulation technology deployment at industrial scale, though microfluidization captures margin pools in pharmaceutical-grade functional beverage applications.
FDA GRAS determinations and EFSA food additive evaluations govern emulsifier approval pathways, while REACH compliance in Europe restricts certain synthetic surfactant chemistries and redirects R&D toward plant-derived stabilizers. China's SAMR enforces GB standards for emulsion-based food additives that foreign suppliers must meet for import clearance. Stakeholders must monitor evolving clean-label certification thresholds as regulatory bodies tighten scrutiny of artificial emulsifier exemptions across multiple jurisdictions.
Market Dynamics
Europe's F-Gas Regulation and REACH compliance requirements are accelerating the displacement of solvent-based emulsion systems by water-based alternatives, forcing reformulation investments across multinational beverage portfolios while reshaping supplier qualification criteria.
Growth Catalysts
- Clean-label reformulation mandates:Functional beverage manufacturers in Germany and France are eliminating synthetic surfactants to meet EFSA scrutiny thresholds, creating pull-through demand for plant-derived stabilizer systems.
- Nanoemulsion bioavailability advantages:Tropical fruit juice processors in Thailand and Vietnam are adopting high-pressure homogenization to enhance lipophilic vitamin dispersion in ambient-stable products.
- Carbonated soft drink flavor innovation:Oil-in-water emulsion systems enable stable incorporation of citrus terpenes and clouding agents for premium positioning in Mexico and Brazil.
Market Restraints
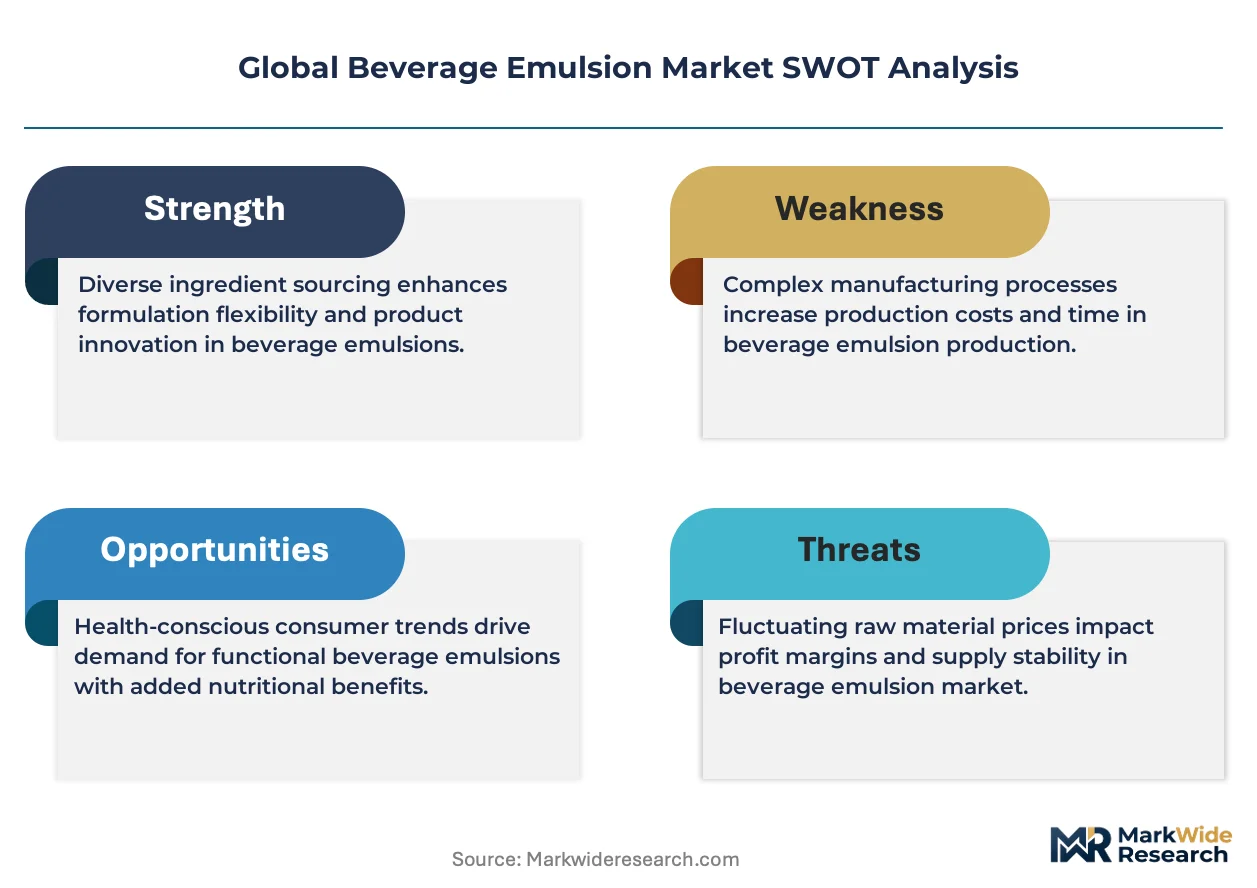
- Hydrocolloid supply concentration:Guar gum and modified starch sourcing depends on agricultural output volatility in India and Pakistan, creating input cost instability for O/W matrix formulators.
- Technical stability limitations:Thermodynamic instability of conventional emulsions restricts shelf life below twelve months in high-temperature supply chains across Southeast Asia.
- Regulatory approval friction:China's SAMR GB standard enforcement creates eighteen-to-twenty-four month clearance timelines for novel plant-derived emulsifiers, delaying product launches.
Strategic Opportunities
- Underpenetrated African markets:Beverage manufacturers in Nigeria and Kenya lack local nanoemulsion production capacity, creating first-mover advantages for technology licensors.
- Regulatory tailwind from EU Green Deal:Biobased emulsifier mandates will redirect public procurement toward renewable surfactant systems by 2030.
- Pharmaceutical-grade functional beverages:Convergence of microfluidization with liposomal encapsulation enables prescription-adjacent nutraceutical positioning in Japan and South Korea.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in interfacial rheology and droplet size distribution control concentrates among aging technical staff in European and North American R&D centers.
- Clean-label certification complexity:Divergent standards between USDA Organic, EU Organic, and JAS Organic create multi-audit burdens for exporters targeting multiple premium channels.
- Legacy equipment retrofit costs:Transitioning from conventional homogenizers to high-pressure systems requires capital outlays that strain mid-tier co-manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beverage Emulsion Market |
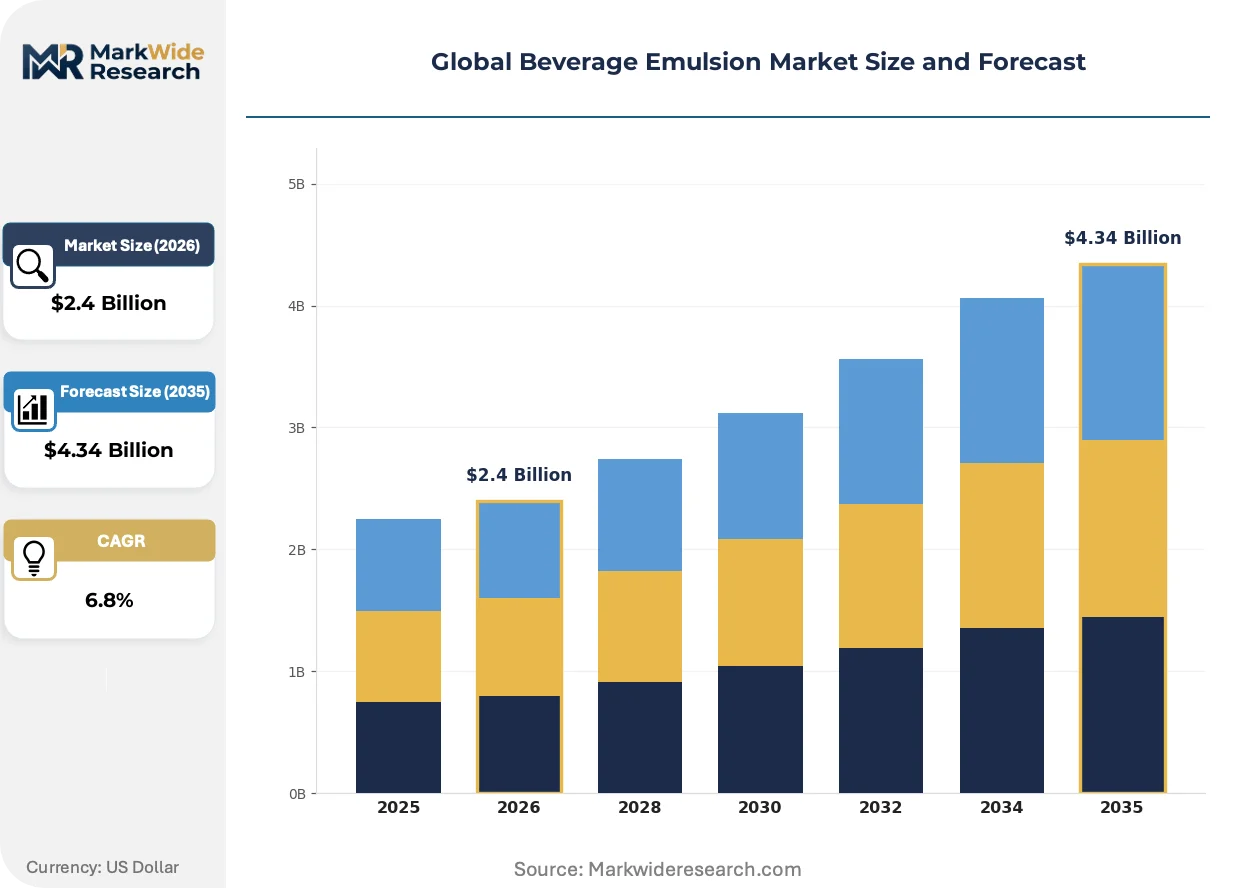
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O/W Emulsion, W/O Emulsion, Multiple Emulsion, Microemulsion, Nanoemulsion Application: Carbonated Drinks, Functional Beverages, Dairy Beverages, Fruit Juices, Energy Drinks Customer Type: Beverage Manufacturers, Flavor Houses, Contract Beverage Producers, Ingredient Suppliers, Bottlers Formulation Technology: High Pressure Homogenization, Ultrasonic Emulsification, Membrane Emulsification, Microfluidization, Rotor-Stator Mixing |
| Companies Covered | Givaudan, Kerry Group, Tate & Lyle, Sensient Technologies, Ingredion Incorporated, ADM, CP Kelco, International Flavors & Fragrances, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beverage Emulsion Market Shifts & Advancements
Formulation science is converging with regulatory chemistry and precision manufacturing to redefine how lipophilic actives integrate into hydrophilic beverage matrices. Three interconnected developments are compressing development cycles while expanding functional possibilities.
Microfluidization is unifying pharmaceutical-grade precision with beverage-scale throughput. Premium functional drink manufacturers in Switzerland and the Netherlands are adopting this technology to achieve sub-200 nanometer droplet distributions. The process is unifying previously separate quality tiers, enabling pharmaceutical nutraceuticals and mainstream beverages to share production infrastructure.
REACH authorization restrictions on per- and polyfluoroalkyl substances are forcing emulsifier portfolio restructuring across European formulators. Industrial consequence includes accelerated R&D timelines for fluorine-free stabilizer alternatives. Dairy alternative segments in Germany and France are most affected, with oat and almond milk processors reformulating clouding systems ahead of 2025 substance evaluation deadlines.
Direct-to-brand ingredient supply contracts are displacing traditional distributor intermediation in North American and European procurement. Mid-sized functional beverage startups in California and Massachusetts now source customized emulsion systems through technical partnerships rather than catalog purchasing. This pattern is most visible in adaptogenic and nootropic beverage verticals where co-development of stability matrices provides competitive differentiation.
Global Beverage Emulsion Market Segmentation
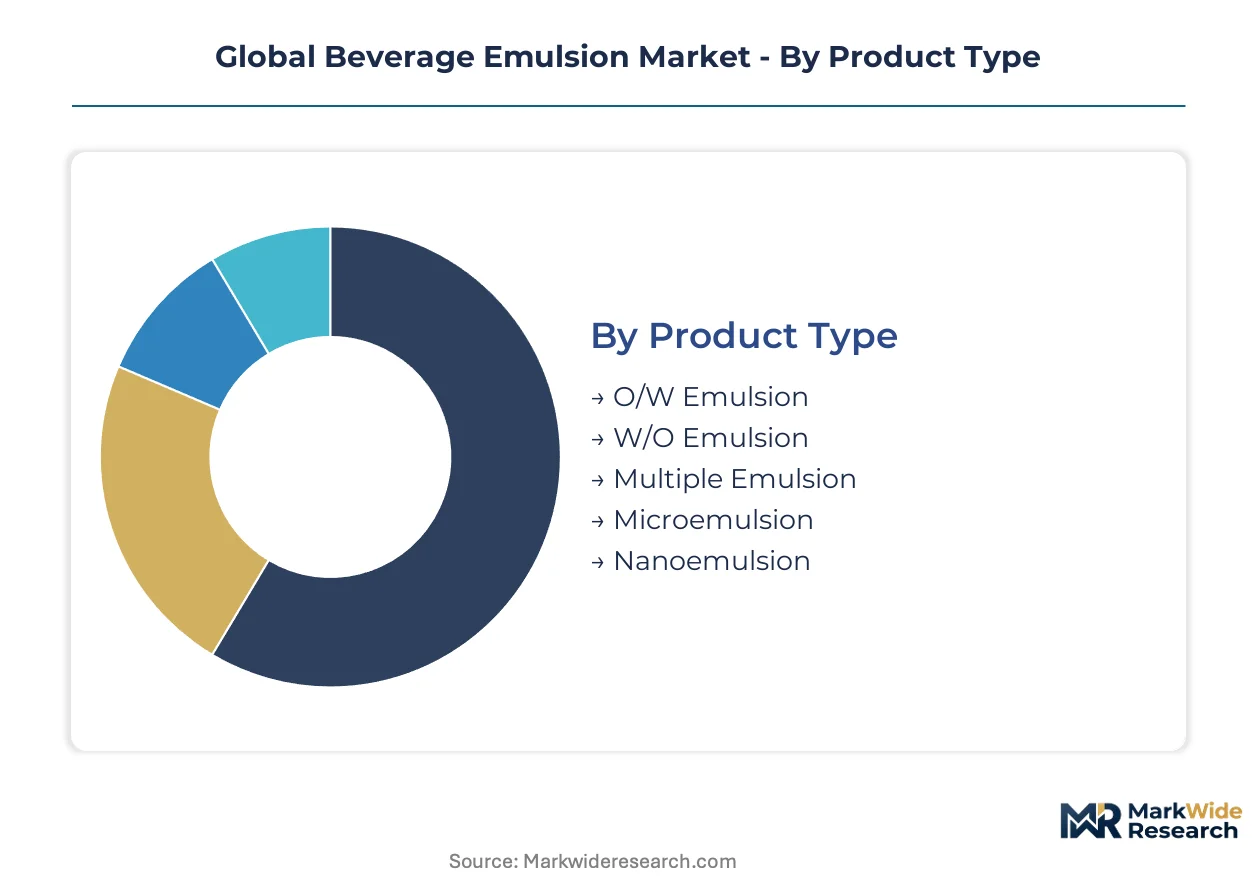
Beverage emulsion segmentation reflects divergent technical requirements across stability demands, optical clarity thresholds, and bioavailability targets. Formulators select emulsion architectures and processing technologies based on end-use shelf life, regulatory jurisdiction, and clean-label positioning mandates.
Product Type:
Buyers in this category differentiate by kinetic stability requirements and droplet size distribution tolerances for their target beverage matrices.
- Nanoemulsion:Thermodynamically metastable systems with droplet sizes below 200 nanometers deliver enhanced lipophilic nutrient bioavailability. Tropical fruit juice processors in Thailand deploy these systems for ambient-stable vitamin fortification where optical clarity is mandatory.
- O/W Emulsion:Oil-in-water architectures dominate commercial deployment, suspending lipophilic flavors and clouding agents within continuous aqueous phases. Dairy alternative manufacturers in Germany favor plant-derived stabilizer versions to meet EFSA clean-label thresholds.
- W/O Emulsion:Water-in-oil systems serve niche high-fat beverage applications requiring moisture encapsulation.
- Multiple Emulsion:W/O/W or O/W/O structures enable controlled release of bioactive compounds in pharmaceutical-grade functional drinks.
- Microemulsion:Thermodynamically stable transparent systems find limited beverage use due to high surfactant load requirements.
O/W emulsion leads volumes today; nanoemulsion is gaining share fastest.
Application:
End-use selection hinges on shelf stability duration, temperature exposure during distribution, and consumer transparency expectations.
- Functional Beverages:Adaptogenic and nootropic formulations demand sub-200 nanometer emulsion systems for bioactive absorption. California-based startups source customized stability matrices through direct technical partnerships rather than catalog purchasing.
- Carbonated Drinks:Oil-in-water systems stabilize citrus terpenes and clouding agents against CO₂-induced phase separation. Premium positioning in Mexico and Brazil drives flavor-emulsion co-design investments.
- Fruit Juices:High-pressure homogenization enables lipophilic vitamin dispersion in ambient-stable tropical products.
- Dairy Beverages:Oat and almond milk processors reformulate clouding systems ahead of REACH substance evaluation deadlines.
- Energy Drinks:Rapid absorption requirements favor nanoemulsion delivery of lipophilic stimulants and vitamins.
Carbonated drinks anchor current demand; functional beverages show the steepest expansion trajectory.
Customer Type:
Procurement sophistication varies by in-house formulation capability and volume scale across the value chain.
- Beverage Manufacturers:Integrated multinationals specify customized emulsion systems for proprietary flavor and nutrient delivery platforms. Direct-to-brand technical partnerships are displacing traditional distributor intermediation in North America.
- Flavor Houses:Specialized suppliers anchor competitive stance through deep co-development capabilities for premium beverage portfolios.
- Contract Beverage Producers:Mid-tier co-manufacturers face capital strain when retrofitting from conventional homogenizers to high-pressure systems.
- Ingredient Suppliers:Hydrocolloid and surfactant specialists control upstream supply chains that underpin emulsion matrix stability.
- Bottlers:Final-stage processors depend on supplied emulsion concentrates for consistent finished product quality.
Beverage manufacturers command the largest procurement volumes; flavor houses are expanding technical service revenues most quickly.
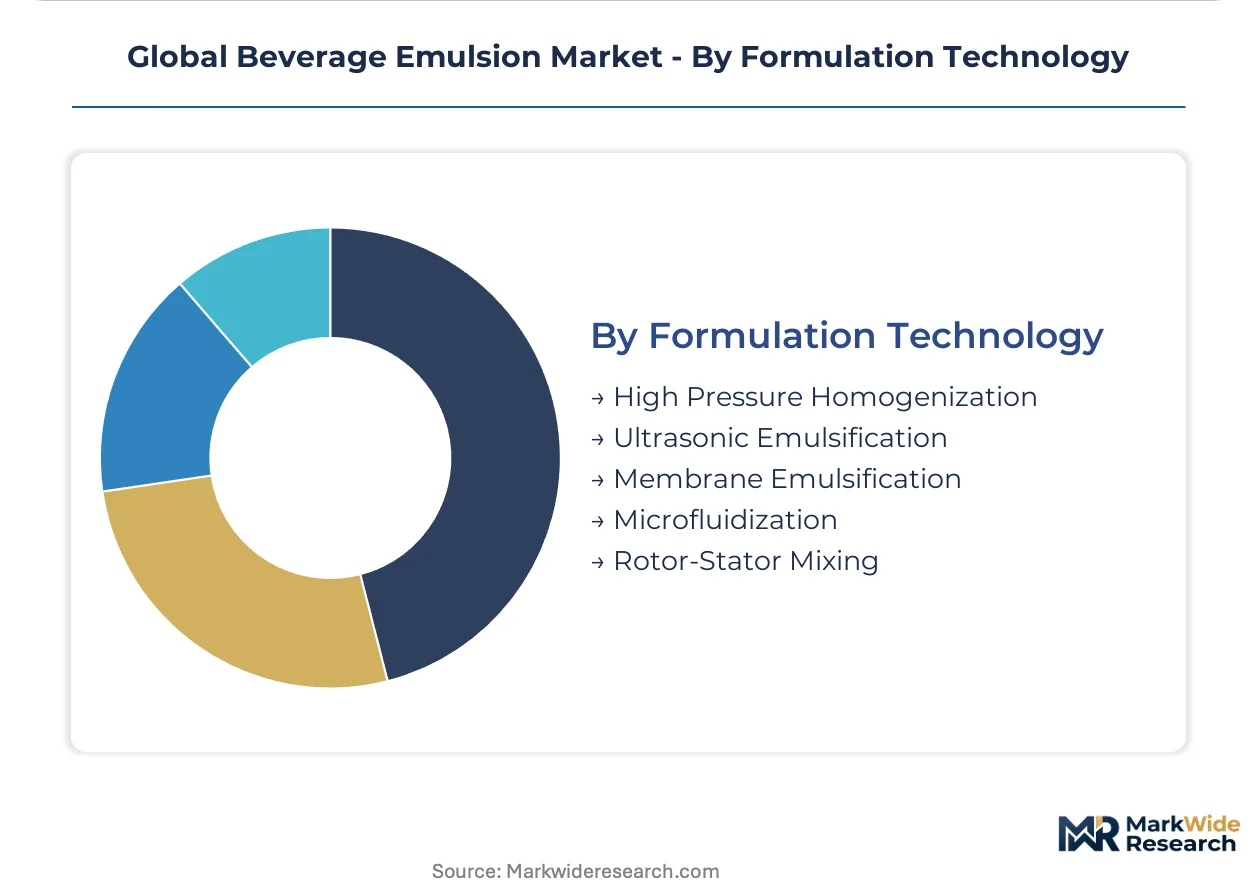
Formulation Technology:
Technology selection balances capital intensity, throughput requirements, and droplet size precision for target applications.
- High Pressure Homogenization:Industrial-scale deployment achieves 100-500 nanometer distributions at beverage production volumes. Southeast Asian juice processors scale this technology for enhanced bioavailability in ambient-stable products.
- Microfluidization:Pharmaceutical-grade precision achieves sub-200 nanometer uniformity for premium functional drinks. Swiss and Dutch manufacturers adopt this convergence of nutraceutical and mainstream beverage production infrastructure.
- Ultrasonic Emulsification:Acoustic cavitation suits laboratory-scale development and specialty low-volume production.
- Membrane Emulsification:Controlled pore-size membranes enable narrow droplet distributions for sensitive bioactive encapsulation.
- Rotor-Stator Mixing:Conventional mechanical shear remains economical for coarse emulsions with relaxed stability requirements.
High pressure homogenization dominates installed capacity; microfluidization is climbing the fastest among precision-dependent applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting beverage emulsion production toward jurisdictions with streamlined clean-label certification pathways, as REACH compliance costs in Europe widen cost-of-compliance gaps with Southeast Asian manufacturing hubs.
Germany
Dairy alternative manufacturers in Bavaria and North Rhine-Westphalia are reformulating clouding systems ahead of EFSA substance evaluation deadlines. The country's F-Gas Regulation implementation is accelerating displacement of solvent-based emulsion systems by water-based alternatives. Cologne-based formulators are investing in high-pressure homogenization capacity to serve pan-European oat milk processors.
United States
California and Massachusetts functional beverage startups are sourcing customized emulsion systems through direct technical partnerships rather than traditional distributor channels. FDA GRAS determinations govern emulsifier approval pathways for adaptogenic and nootropic formulations. Greater Los Angeles clusters concentrate nanoemulsion R&D for pharmaceutical-grade nutraceutical applications.
Thailand
Tropical fruit juice processors in Bangkok and surrounding provinces are scaling high-pressure homogenization for ambient-stable vitamin fortification where optical clarity is mandatory. The country's national food regulator enforces additive standards that foreign suppliers must meet for import clearance. Eastern Economic Corridor manufacturing zones attract nanoemulsion technology licensors serving ASEAN export markets.
China
SAMR GB standard enforcement creates eighteen-to-twenty-four month clearance timelines for novel plant-derived emulsifiers, delaying product launches for international suppliers. Yangtze River Delta beverage manufacturers are retrofitting conventional homogenizers to meet clean-label export requirements. Shanghai-based ingredient distributors are building technical service capabilities to navigate regulatory friction.
Brazil
Carbonated soft drink manufacturers in São Paulo and Minas Gerais are investing in oil-in-water emulsion systems for citrus terpene stabilization and premium clouding applications. ANVISA regulates emulsion-based food additives with compliance requirements that favor established multinational suppliers. Campinas industrial clusters concentrate flavor-emulsion co-design capabilities for Latin American beverage portfolios.
Global Beverage Emulsion Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade precision and direct-to-brand technical partnerships. The vendor base stratifies across integrated taste-and-nutrition platforms, specialized flavor houses, and upstream hydrocolloid controllers. Three archetypes dominate: multinational ingredient conglomerates with captive emulsion capabilities, independent flavor specialists with deep co-development expertise, and regional technology licensors serving underpenetrated markets. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Within the integrated platform tier, Kerry Group and Givaudan exemplify contrasting strategic positions. Kerry leverages its combined taste and nutrition infrastructure to supply customized emulsion systems across carbonated and functional drink categories. Givaudan anchors its stance through flavor-emulsion co-design specialization for premium beverage portfolios. Cargill occupies a position defined by upstream hydrocolloid supply chain control that underpins O/W emulsion matrices for dairy alternatives.
| Leading Market Players |
|---|
| Givaudan |
| Kerry Group |
| Tate & Lyle |
| Sensient Technologies |
| Ingredion Incorporated |
| ADM |
| CP Kelco |
| International Flavors & Fragrances |
| Cargill |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up hydrocolloid specialists in India and Pakistan anchor supply-side pricing power, translating agricultural output volatility into input cost instability that beverage formulators must absorb or hedge through long-term offtake contracts.
Pricing Analysis
Distributor margins of 15-25% separate standard-grade O/W emulsions from pharmaceutical-grade nanoemulsion systems delivered direct-to-brand. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence between EFSA-compliant plant-derived stabilizers and conventional synthetic surfactants. Pricing pressure stems from REACH-driven reformulation costs in Europe. Mid-tier co-manufacturers exhibit highest price sensitivity due to legacy equipment retrofit burdens, while premium functional beverage startups accept premium positioning for bioavailability advantages.
Supply Chain Analysis
Guar gum supply rests on agricultural output in Rajasthan and Sindh provinces, with modified starch sourcing concentrated in Thailand and Vietnam processing hubs. High-pressure homogenization equipment draws from German and Swiss precision engineering clusters. Single-source vulnerability concentrates in Southeast Asian tropical fruit concentrate supply for nanoemulsion feedstocks. Distribution runs through regional ingredient distributors with technical service capabilities, though direct-to-brand partnerships are displacing traditional intermediation in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Beverage Emulsion Market functions as a stable compounder anchored by irreversible clean-label reformulation mandates across European and North American functional beverage portfolios.
For Market Incumbents: Extend technical service capabilities into direct-to-brand partnerships to capture margin pools fleeing traditional distributor channels. Deepen backward integration into plant-derived stabilizer supply chains ahead of EFSA substance evaluation deadlines. Capacity additions in Thailand and Vietnam manufacturing zones will defend share against regional technology licensors targeting ASEAN export markets. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade microfluidized systems and conventional homogenized emulsions creates entry space for mid-precision technology licensors. Underpenetrated African markets in Nigeria and Kenya offer first-mover positioning where local nanoemulsion production capacity remains absent. License high-pressure homogenization technology to regional beverage manufacturers rather than competing on capital-intensive equipment manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier flavor houses with deep co-development expertise but limited geographic footprint. Long-term viability frames around regulatory chemistry capabilities that navigate multi-jurisdictional approval pathways. Acquisition targets should demonstrate SAMR GB standard navigation experience for China market access. Watch EFSA clean-label threshold tightening as inflection signal for plant-derived stabilizer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Derived Stabilizers | Secures supply chains against REACH authorization restrictions on synthetic surfactants in Germany and France. |
| High-Pressure Homogenization Capacity Expansion | Enables Southeast Asian juice processors to scale ambient-stable vitamin fortification for export markets. |
| Direct-to-Brand Technical Partnership | Captures margin pools in California adaptogenic beverage startups displacing traditional distributor channels. |
| Microfluidization Technology Licensing | Opens pharmaceutical-grade functional beverage positioning in Swiss and Dutch precision manufacturing clusters. |
| Regulatory Chemistry Capability Buildout | Accelerates SAMR GB standard clearance timelines for novel plant-derived emulsifiers in China. |
Research Methodology
Direct dialogue with beverage formulation chemists, procurement leads at multinational manufacturers, flavor house technical directors, and hydrocolloid supply chain managers grounded qualitative insights. Secondary validation drew from EFSA food additive evaluations, SAMR GB standards documentation, FDA GRAS determinations, and trade flow data through Indian and Pakistani agricultural export registries. Bottom-up and top-down triangulation cross-checked emulsion system demand against installed homogenization capacity across identified manufacturing clusters.
Bottom-up modeling segmented volume and value across product type, application, customer archetype, and formulation technology dimensions throughout the forecast period. CAGRs derived from trend extrapolation of nanoemulsion adoption rates in tropical fruit juice processing, O/W emulsion reformulation timelines in European dairy alternatives, and microfluidization penetration in pharmaceutical-grade functional beverages. Industry-specific inputs included REACH substance evaluation deadlines, F-Gas Regulation implementation phases, and clean-label certification threshold evolution.
Caveats apply where regulatory timeline delays, agricultural commodity price spikes, or equipment supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions around EFSA scrutiny threshold trajectories and SAMR enforcement consistency. A small set of named triggers warrants ongoing watch: REACH authorization list expansion, India-Pakistan guar harvest variability, and high-pressure homogenization equipment lead time extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Yerba Mate Market
Beverages
Europe Bottled Water Processing Market
Beverages
Kvass Market
Beverages
Soft Serves Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Apple Juice Concentrate Market
Beverages
Global Soda Maker Market
Beverages
Global Vinegar Market
Beverages
United States Soy Beverages Market
Beverages
Collagen Drinks Market
Beverages
GCC Juice Market
Beverages
Ready to Drink Margarita Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Bottled Air Market