
 Edible Alcohol Market | 2026-2036
Edible Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Alcohol Market Insights
Craft distilleries and premium beverage producers are reorganizing supply relationships away from commodity ethanol suppliers toward specialty-grade producers with traceable grain origins. Cargill leverages its North American grain origination network to secure consistent feedstock for food-grade alcohol distillation. MGP Ingredients differentiates through its Lawrenceburg facility's capacity to produce both neutral grain spirits and customized specialty alcohols for branded customers. Roquette Frères anchors European supply with its Lestrem plant's non-GMO wheat fermentation capabilities.
Edible alcohol denotes ethanol purified to food-grade specifications, typically achieving minimum purity of 96% alcohol by volume through multi-stage distillation and carbon filtration to remove congeners and methanol traces; it serves as the foundational solvent in beverage manufacturing, flavor extraction, and pharmaceutical tinctures. Spirits production dominates value generation due to premiumization trends in whiskey and vodka categories, while flavored alcohols represent the fastest-expanding segment as younger demographics seek lower-ABV, taste-forward options. Ingredient type segmentation reveals distilled alcohol commands higher margin pools than fermented bases owing to energy-intensive rectification requirements and tighter specification compliance.
The FDA governs food-grade alcohol safety under 21 CFR regulations, while the TTB administers tax classification and labeling standards for beverage alcohol in the United States; EU REACH and EFSA frameworks impose additional purity thresholds on ethanol imports entering European food and drink applications. China's SAMR enforces GB standards for edible alcohol methanol content and heavy metal limits, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving biofuel policy intersections, as agricultural subsidy shifts in major grain-producing regions directly redirect feedstock availability between fuel and food-grade alcohol channels.
Market Dynamics
Premium craft distilleries are reorganizing procurement around smaller-batch botanical sourcing, forcing specialty-grade ethanol producers to reconfigure grain origination networks and traceability systems to capture margin pools previously held by commodity suppliers.
Growth Catalysts
- EU REACH Purity Thresholds:Stricter EFSA frameworks on ethanol imports into European food applications are advantaging certified specialty producers over commodity traders.
- Flavor Extraction Demand:Pharmaceutical tincture manufacturers are expanding food-grade alcohol procurement for botanical extraction processes.
- Rhine-Ruhr Industrial Cluster:Germany's concentrated ethanol processing infrastructure creates procurement gravity for high-volume beverage manufacturers.
Market Restraints
- Grain Feedstock Volatility:Agricultural subsidy shifts in major grain-producing regions redirect feedstock availability between fuel and food-grade channels.
- Rectification Energy Costs:Multi-stage distillation and carbon filtration processes impose energy-intensive cost structures that compress margins during price spikes.
- Methanol Trace Compliance:China's SAMR enforces GB standards with divergent methanol content limits, creating fragmented compliance burdens for multinational suppliers.
Strategic Opportunities
- Lower-ABV Flavored Segments:Younger demographics seeking taste-forward, reduced-alcohol options are opening formulation white space for customized specialty alcohols.
- TTB Labeling Flexibility:Evolving tax classification standards in the United States create openings for novel product categorization and premium positioning.
- Non-GMO Fermentation:Wheat-based non-GMO production capabilities are capturing price premiums in European markets with strict traceability requirements.
Industry Challenges
- Congener Removal Expertise:Distilleries face talent scarcity in multi-stage rectification engineering required for 96% ABV purity achievement.
- Legacy Equipment Retrofit:Carbon filtration system upgrades demand capital deployment that strains mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Alcohol Market |
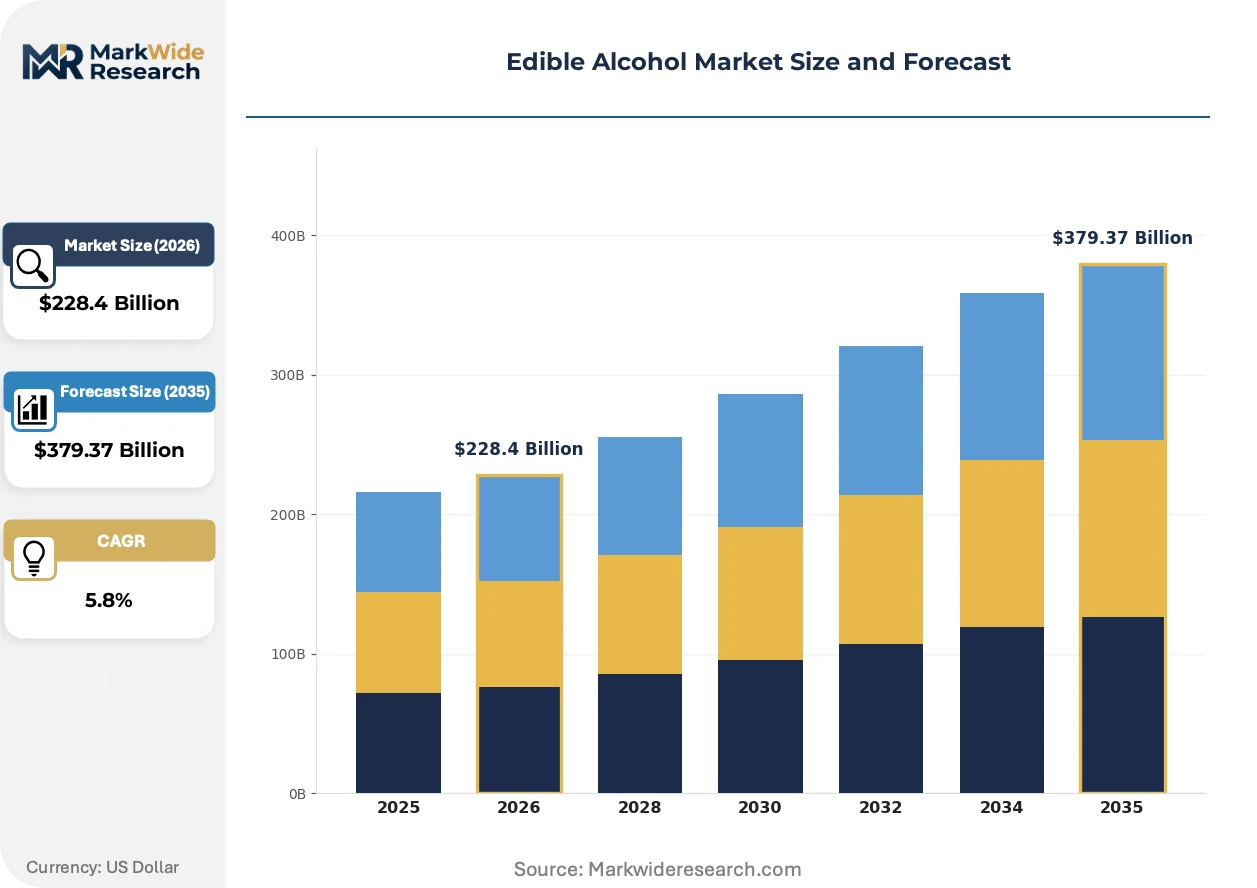
| Market Size in 2026 | $228.4 Billion |
| Market Size in 2035 | $379.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirits, Liqueurs, Fortified Wines, Flavored Alcohols Consumer Type: Millennials, Gen Z, Baby Boomers, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Bars & Restaurants Ingredient Type: Fermented, Distilled, Natural Extracts, Artificial Flavors |
| Companies Covered | Cargill, Archer Daniels Midland Company, MGP Ingredients, Wilmar International, Roquette Frères, Grain Processing Corporation, Cristalco, Manildra Group, Greenfield Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Alcohol Market Trends and Innovations
Carbon filtration and precision rectification technologies are compressing production timelines while regulatory divergence between FDA and SAMR frameworks is fragmenting compliance architectures across supply networks.
Membrane filtration systems are displacing traditional multi-stage distillation in neutral grain spirits production. Mid-scale craft distilleries are adopting these systems to reduce energy consumption and water usage. This technology is displacing incumbent rectification equipment vendors and compressing the capital intensity barrier for new market entrants.
China's SAMR GB standards for edible alcohol methanol content and heavy metal limits are tightening faster than harmonization efforts with FDA 21 CFR frameworks. This divergence forces multinational suppliers to maintain parallel production specifications and quality systems. European exporters to Chinese beverage markets are most affected, responding with dedicated export-only production lines.
Direct sourcing contracts between distilleries and specialty-grade producers are replacing spot-market commodity ethanol procurement. Branded beverage manufacturers are disintermediating traditional grain ethanol traders to secure traceable origins. This pattern concentrates in Germany's Rhine-Ruhr metropolitan region where industrial ethanol processors face pressure to demonstrate batch-level provenance.
Edible Alcohol Market Segmentation
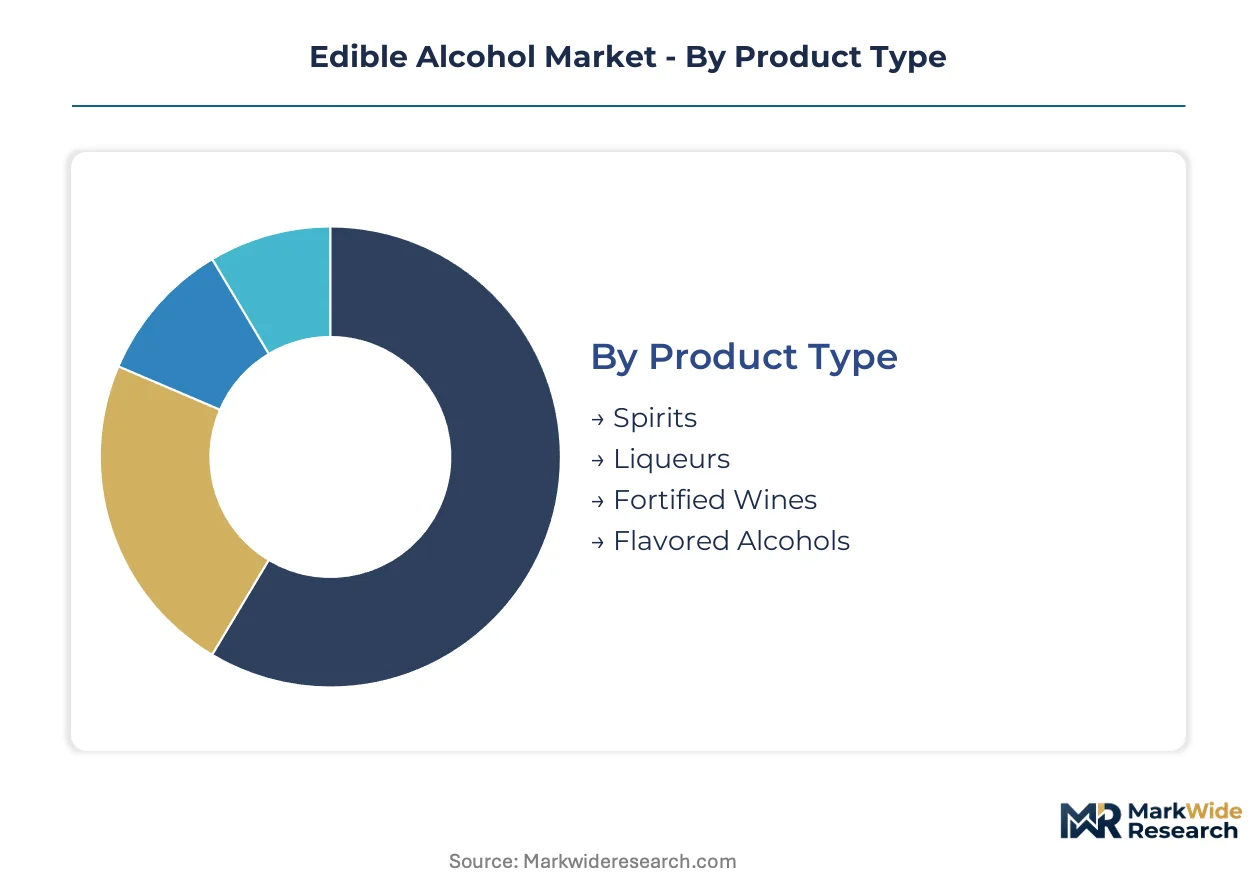
Segmentation in edible alcohol markets reveals divergent procurement patterns between commodity-grade bulk buyers and specialty-grade craft distillers seeking traceable origins. Each dimension—product formulation, consumer cohort, channel configuration, and ingredient processing—carries distinct margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Domestic consumption concentrates in heritage spirit categories across mature European and North American markets, while export-led growth accelerates in flavored alcohols targeting emerging Asian consumer bases.
- Spirits:Whiskey, vodka, and gin formulations achieve 96% ABV purity through multi-stage rectification. Demand clusters in Germany's Rhine-Ruhr industrial corridor where high-volume beverage manufacturers source neutral grain spirits for blending operations. Premiumization trends in aged whiskey categories command sustained price premiums over unaged alternatives.
- Flavored Alcohols:Lower-ABV, taste-forward formulations incorporate botanical extracts and natural essences post-distillation. Younger demographics in urban Chinese and Indian markets drive procurement expansion, forcing specialty ethanol producers to configure smaller-batch traceability systems.
- Liqueurs:Sugar-infused, lower-proof formulations rely on neutral grain spirits as base solvents.
- Fortified Wines:Wine-based products with added distilled spirits serve established European aperitif traditions.
Spirits commands the established base. The steepest expansion runs through flavored alcohols.
Consumer Type:
Cost-tier stratification separates premium-seeking cohorts willing to pay traceability premiums from volume-driven segments prioritizing accessibility.
- Millennials:Experience-oriented consumption patterns favor craft distillery provenance and limited-batch releases. This cohort concentrates spending in specialty retail and direct-to-producer channels, compressing traditional distributor margins.
- Gen Z:Digital-native purchasing behavior accelerates online retail penetration for lower-ABV flavored products. Preference for sustainability credentials and transparent sourcing forces producers to maintain batch-level documentation.
- Baby Boomers:Established brand loyalty sustains heritage spirit categories through conventional supermarket and on-premise channels.
- Health-Conscious Consumers:Reduced-alcohol and organic-certified segments drive formulation innovation in natural extract categories.
Millennials anchor current value generation. Gen Z shows the steepest expansion trajectory.
Distribution Channel:
Channel concentration varies sharply by geography—on-premise bars and restaurants dominate mature European markets while online retail captures share fastest in digitally penetrated Asian economies.
- Bars & Restaurants:On-premise consumption drives premium spirits attachment and mixology-driven ingredient demand. Germany's concentrated Rhine-Ruhr hospitality cluster creates procurement gravity for specialty-grade ethanol distributors.
- Online Retail:Direct-to-consumer platforms disintermediate traditional wholesale networks for craft and limited-release products. Regulatory fragmentation between FDA 21 CFR and China's SAMR GB standards complicates cross-border e-commerce fulfillment.
- Supermarkets:Mass-market volume concentration favors standardized, commodity-grade ethanol suppliers with scale economies.
- Specialty Stores:Curated selection and staff expertise sustain premium positioning for traceable-origin spirits.
Bars and restaurants command the established base. Online retail shows the steepest expansion trajectory.
Ingredient Type:
Margin structure separates energy-intensive distilled categories from lower-capital fermented bases, with natural extracts commanding scarcity premiums in European traceability-regulated markets.
- Distilled:Multi-stage rectification to 96% ABV achieves food-grade purity specifications required for pharmaceutical tinctures and premium spirits. Roquette Frères' Lestrem facility and MGP Ingredients' Lawrenceburg plant anchor supply concentration for this highest-margin category.
- Fermented:Lower-purity bases serve bulk beverage manufacturing and industrial food applications with reduced energy intensity. Grain feedstock volatility under agricultural subsidy shifts creates pricing pressure across this commoditized segment.
- Natural Extracts:Botanical-derived flavor compounds face sourcing constraints from climate-sensitive cultivation regions.
- Artificial Flavors:Synthetic alternatives compete on cost in price-sensitive mass-market formulations.
Distilled ingredients command the established base. Natural extracts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor's integrated rail-river logistics infrastructure anchors European ethanol processing gravity, while Mississippi River barge networks and Great Lakes shipping lanes underwrite North American feedstock flows into food-grade distillation.
United States
Pharmaceutical tincture manufacturers in New Jersey and North Carolina expand food-grade alcohol procurement for botanical extraction. FDA 21 CFR regulations govern purity specifications, creating compliance benchmarks for domestic and export production. The Lawrenceburg, Indiana industrial cluster concentrates neutral grain spirits capacity serving branded beverage manufacturers.
Germany
Rhine-Ruhr metropolitan processors face pressure to demonstrate batch-level provenance as craft distilleries reorganize procurement relationships. EU REACH and EFSA frameworks impose stringent purity thresholds on ethanol imports entering food applications. Düsseldorf and Cologne anchor high-volume beverage manufacturing procurement gravity for specialty-grade distributors.
China
Urban millennial and Gen Z consumers in Shanghai and Beijing accelerate demand for lower-ABV flavored formulations. SAMR enforces GB standards with divergent methanol content and heavy metal limits compared to Western frameworks. Yangtze River Delta processing facilities maintain parallel production specifications for domestic and export markets.
France
Heritage spirit categories sustain established consumption patterns through conventional channels in Paris and Lyon metropolitan areas. ECHA and ANSM regulatory overlap creates layered compliance architectures for ethanol destined for pharmaceutical and beverage applications. The Lestrem industrial zone anchors non-GMO wheat fermentation capabilities capturing European traceability premiums.
India
Rising disposable incomes in Maharashtra and Karnataka drive spirits consumption expansion across premium and standard tiers. FSSAI standards govern food-grade alcohol safety specifications for domestic manufacturing and import clearance. Mumbai-Pune industrial corridor concentrates flavor extraction and pharmaceutical tincture production requiring certified ethanol inputs.
Edible Alcohol Market Competitive Landscape
Concentration sits with diversified agricultural processors possessing integrated grain origination networks. The vendor base spans multinational conglomerates with captive feedstock supply and mid-scale specialty distillers focused on traceability-certified production. Two strategic archetypes dominate: vertically integrated grain-to-ethanol operators and custom-distillation service providers. Capacity expansion and direct sourcing contract proliferation constitute the primary competitive vectors reshaping supplier relationships.
Among North American agricultural processors, Cargill and Archer Daniels Midland Company exemplify scale-driven feedstock integration archetypes. MGP Ingredients occupies a specialist position within the custom-distillation tier, anchoring service capabilities for branded beverage customers. European supply concentration includes Roquette Frères, whose Lestrem facility represents non-GMO fermentation specialization. These three entities collectively illustrate the competitive spectrum from commodity-scale grain processing to premium-grade certified production.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| MGP Ingredients |
| Wilmar International |
| Roquette Frères |
| Grain Processing Corporation |
| Cristalco |
| Manildra Group |
| Greenfield Global |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at multi-stage rectification facilities shapes both supply concentration and price floors across specialty-grade ethanol tiers. Grain origination scale at North American agricultural processors compresses per-unit costs for neutral grain spirits, while smaller-batch botanical sourcing requirements at craft distilleries sustain premium pricing power for traceable-origin producers.
Pricing Analysis
Volume-discount tiering structures stratify across premium certified, standard food-grade, and economy bulk ethanol levels. Price differentiation rests on certification grade—FDA 21 CFR versus EU REACH compliance—and grain traceability documentation. Cost compression in standard tiers is intensifying because agricultural subsidy shifts redirect feedstock toward biofuel channels. Mass-market beverage manufacturers exhibit highest price sensitivity, while pharmaceutical tincture producers accept premiums for documented purity.
Supply Chain Analysis
The United States and Germany anchor food-grade ethanol production through integrated grain origination and rectification infrastructure. Feedstock supply draws from North American corn belts and European wheat cultivation zones, with carbon filtration membranes and precision rectification equipment as critical capital inputs. Single-source vulnerability concentrates in membrane filtration system vendors serving mid-scale craft distilleries. Distribution runs through direct sourcing contracts that disintermediate traditional commodity ethanol traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-alcoholic botanical spirits and fermented low-ABV alternatives pose substitution threats that incumbent ethanol suppliers must navigate through provenance differentiation and formulation partnership strategies.
For Market Incumbents: Shield market position by deepening backward integration into specialty grain origination networks with batch-level traceability systems. Secure capacity expansion slots at Rhine-Ruhr processing clusters before feedstock competition intensifies. Prioritize certification investment in dual FDA-SAMR compliance to capture Chinese beverage export demand. For New Entrants and Emerging Players: EU organic certification fast-tracks open white-space penetration in non-GMO wheat fermentation segments where Roquette Frères anchors incumbent supply. Target India's Maharashtra flavor extraction corridor through pharmaceutical tincture partnerships requiring certified ethanol inputs. Pursue direct-to-craft-distillery distribution to bypass entrenched commodity trader networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom-distillation service providers with multi-year branded beverage contracts. Five-to-ten year viability favors facilities with membrane filtration technology adoption and dual-hemisphere regulatory certification. Monitor agricultural subsidy policy shifts as inflection indicators for feedstock cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Grain Origination | Cargill's North American network demonstrates captive feedstock security against biofuel channel competition. |
| Dual FDA-SAMR Certification Investment | Parallel compliance systems unlock Yangtze River Delta beverage manufacturing procurement. |
| Membrane Filtration Technology Adoption | Energy-efficient production compresses capital barriers for mid-scale craft distillery market entry. |
| Direct Sourcing Contract Proliferation | Batch-level provenance documentation captures premium positioning in German Rhine-Ruhr hospitality clusters. |
| Non-GMO Fermentation Capacity Expansion | Roquette Frères' Lestrem facility validates price premiums in European traceability-regulated markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with distillery procurement directors, pharmaceutical tincture manufacturing executives, and agricultural grain origination specialists; and secondary validation through FDA 21 CFR regulatory filings, EU EFSA purity threshold documentation, SAMR GB standard publications, and customs trade flow records. Bottom-up facility capacity assessments and top-down consumption demand estimates underwent cross-triangulation to reconcile volume figures.
The projection horizon spans multi-year analytical modeling across product type segmentation—spirits, flavored alcohols, liqueurs, fortified wines—consumer cohort tiers, distribution channel configurations, and ingredient processing categories. CAGRs were derived from trend extrapolation of premiumization patterns and regulatory divergence impacts. Forecast inputs incorporated energy cost trajectories for rectification processes and agricultural subsidy policy scenarios affecting feedstock allocation.
Underlying assumptions cover sustained premiumization in whiskey and vodka categories, with deviation risk concentrated in biofuel policy intersections that redirect grain supply. Recalibration cycles align with material shifts in EU REACH enforcement, SAMR standard updates, and membrane filtration technology adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Cordial Drink Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Hogshead Barrel Market