
 United Kingdom Energy Drink Market | 2026-2036
United Kingdom Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Energy Drink Market Outlook
Natural caffeine extracts and botanical adaptogens is rebalancing cost structures as brands reformulate away from synthetic stimulants. Red Bull GmbH leverages its Austrian heritage and extreme sports sponsorship architecture to sustain premium positioning across British retail channels. Monster Beverage Corporation anchors its UK portfolio in larger-format cans and gaming culture alignment. Britvic Plc competes through its established supermarket relationships and private-label manufacturing capabilities.
Energy drinks are non-alcoholic beverages formulated with caffeine, taurine, B-vitamins, and additional functional compounds designed to enhance mental alertness and physical performance, typically containing between 80mg and 300mg of caffeine per serving depending on regulatory limits and product positioning. The sugar-free segment leads volume growth as British consumers migrate away from high-sugar formulations under persistent health messaging and fiscal pressure from the Soft Drinks Industry Levy. Carbonated variants still dominate absolute revenue pools through established brand loyalty and impulse-purchase visibility in convenience retail, though organic positioning now commands the highest per-unit margins.
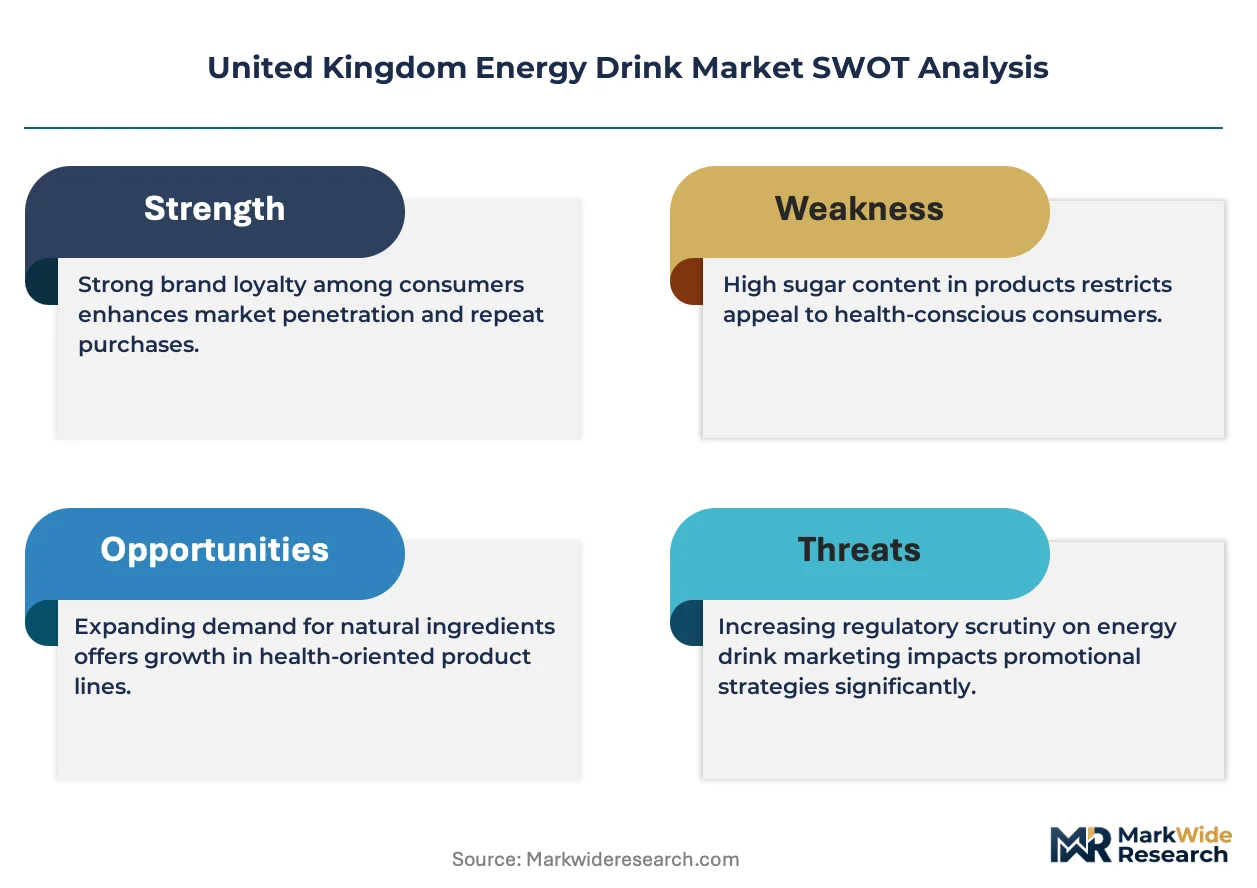
The Food Standards Agency enforces caffeine content labeling and marketing restrictions toward minors, while the Competition and Markets Authority monitors promotional pricing practices that could distort consumer choice. Advertising Standards Authority rulings have tightened further on claims linking energy drinks to enhanced athletic or academic performance. Stakeholders must track how pending adjustments to the Soft Drinks Industry Levy threshold and evolving school proximity sales bans reshape channel strategy and portfolio architecture.
Market Dynamics
The Soft Drinks Industry Levy is forcing wholesale reformulation across British energy drink portfolios as manufacturers absorb sugar tax costs or pivot to artificial sweetener systems.
Growth Catalysts
- Functional wellness migration:Health enthusiasts in Greater London and the South East corridor are driving demand for adaptogen-infused and nootropic-positioned beverages.
- Channel expansion into gaming and esports:Energy drink placement within streaming platforms and competitive gaming venues is creating new consumption occasions among 18-34 year-old males.
- Sugar-free portfolio acceleration:The Soft Drinks Industry Levy threshold adjustments are accelerating brand investment in zero-sugar R&D and clean-label positioning.
Market Restraints
- Input cost volatility:Natural caffeine extract prices fluctuate with Brazilian arabica harvest cycles and climate disruption in East African growing regions.
- Regulatory friction:The Advertising Standards Authority's tightened rulings on performance claims restrict marketing vocabulary around athletic and academic enhancement.
- Substitution pressure:Cold brew coffee and functional sparkling waters are capturing share of occasions previously dominated by carbonated energy drinks.
Strategic Opportunities
- Botanical adaptogen convergence:Ashwagandha, rhodiola, and lion's mane mushroom extracts offer differentiation pathways beyond caffeine-centric positioning.
- Convenience retail automation:Chilled vending networks in transport hubs and university campuses enable impulse purchase capture outside traditional grocery.
- School proximity ban navigation:Reformulation to sub-150mg caffeine thresholds opens access to retail locations within mandated exclusion zones.
Industry Challenges
- Flavor system complexity:Masking bitterness from high-dose B-vitamins and botanical actives requires expensive taste-modulation technology and extended formulation cycles.
- Supply chain reconfiguration friction:Shifting from synthetic to natural caffeine sources demands new supplier qualification and traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Energy Drink Market |
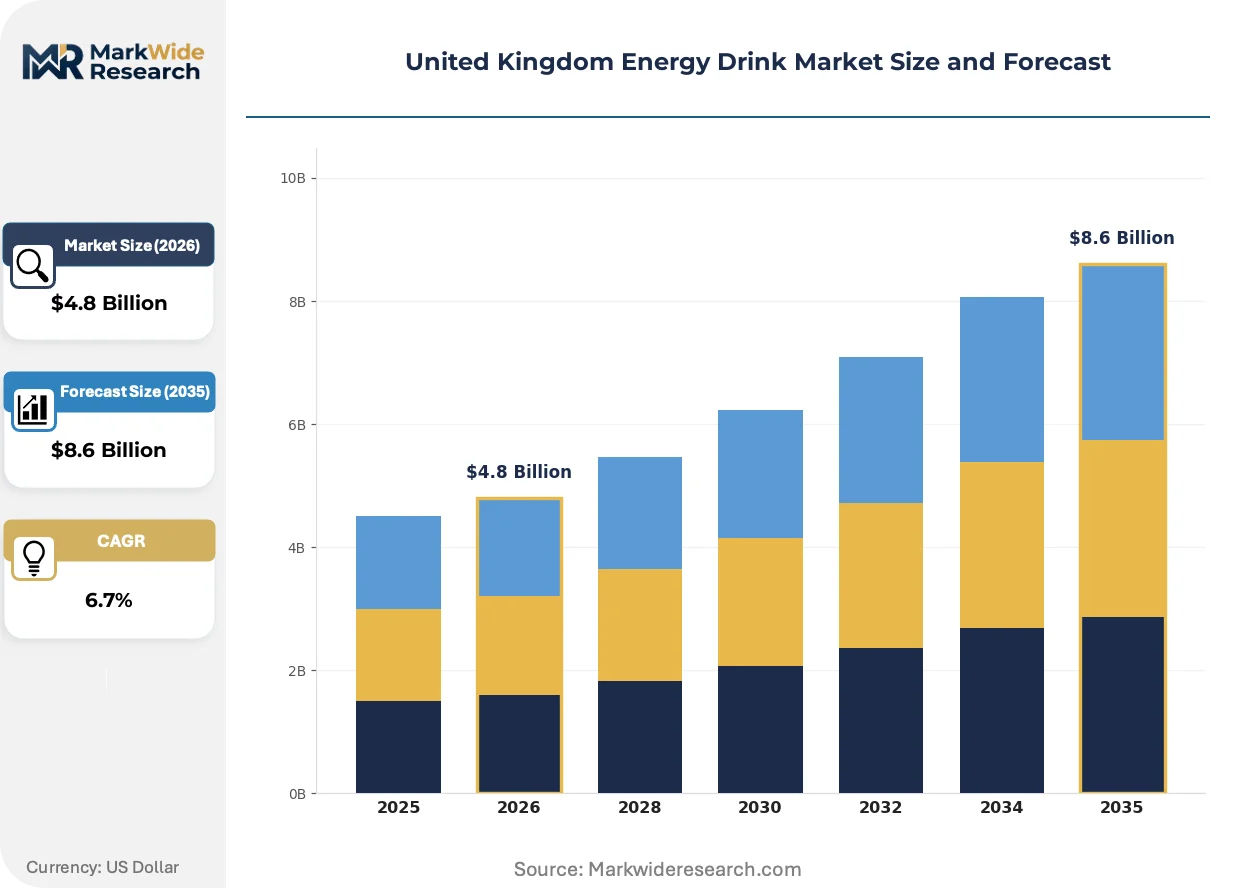
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Organic, Sugar-Free End User: Athletes, Students, Professionals, Health Enthusiasts Flavor: Citrus, Berry, Tropical, Herbal Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Fitness Centers |
| Companies Covered | Red Bull GmbH, Monster Beverage Corporation, PepsiCo Incorporated, The Coca-Cola Company, Suntory Holdings Limited, Britvic Plc, Tenzing Natural Energy, Boost Drinks Ltd, Carabao Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Energy Drink Market Strategic Shifts
Beverage technology is converging with digital health tracking and personalized nutrition platforms, reshaping how British consumers select and consume functional drinks.
Precision fermentation-derived caffeine is converging with enzymatic sugar reduction technologies to create clean-label stimulant systems. Premium health retailers in Chelsea and Notting Hill are piloting these formulations at 40% price premiums to conventional products. This convergence is compressing the cost gap between synthetic and bio-identical active ingredients.
The Food Standards Agency's caffeine content labeling mandates are tightening disclosure requirements for products exceeding 150mg per serving. Manufacturers must now display prominent warnings and recommended daily limits on front-of-pack designs. Sugar-free variants face the strictest scrutiny as they often contain the highest caffeine concentrations per milliliter.
Subscription-based replenishment models are displacing supermarket bulk purchasing among urban professionals. Direct-to-consumer channels in Manchester and Birmingham are capturing repeat buyers through personalized frequency algorithms and flavor rotation systems. This behavioral shift concentrates lifetime value in data-rich relationships rather than impulse retail.
United Kingdom Energy Drink Market Segmentation
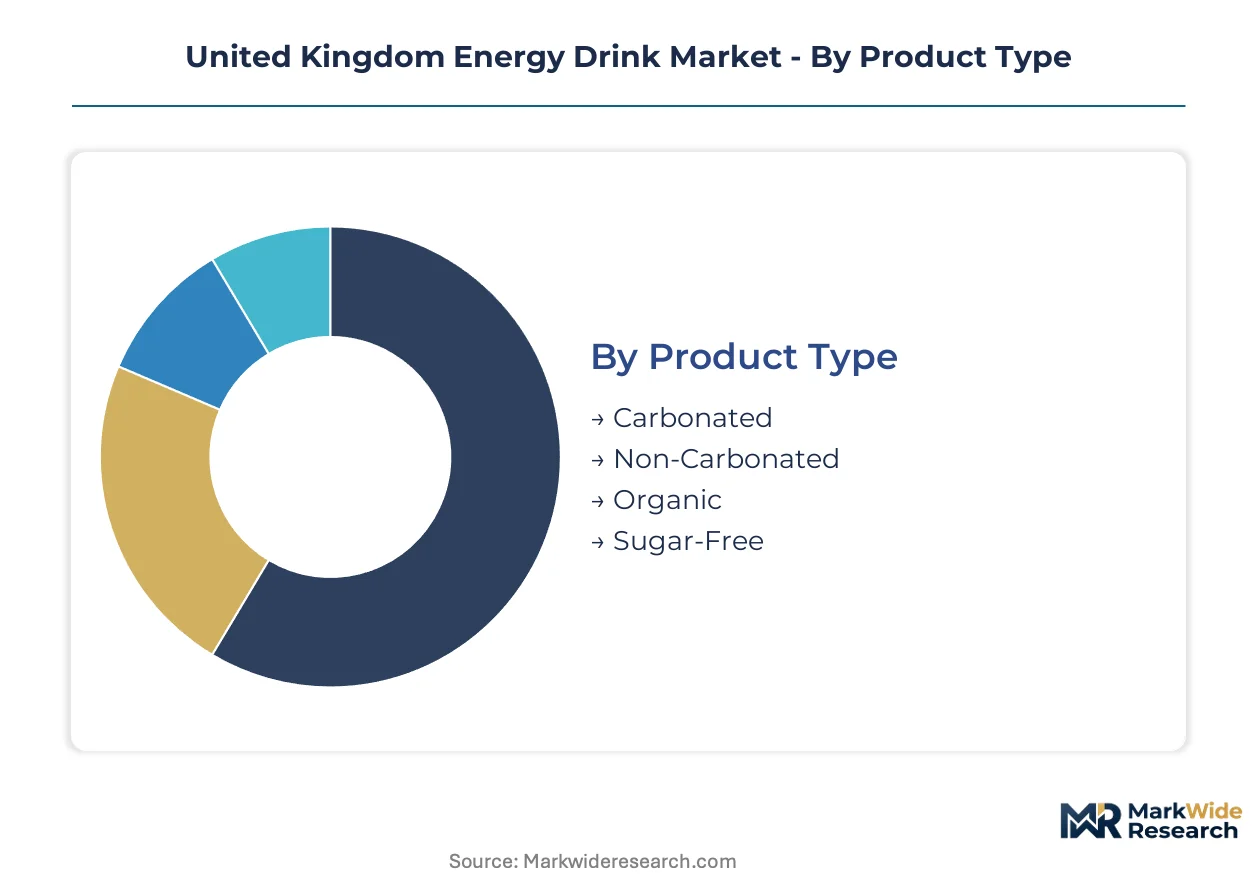
Segmentation in the United Kingdom Energy Drink Market reveals how formulation choices, consumption contexts, and channel access fragment demand. British consumers select products based on caffeine tolerance, sugar policy exposure, and lifestyle alignment rather than brand loyalty alone. Understanding these divisions enables targeted portfolio architecture and channel investment decisions.
Product Type:
Buyers in this category differentiate primarily by health policy exposure and ingredient transparency preferences rather than taste alone.
- Sugar-Free:Formulations rely on artificial sweetener systems or sugar alcohols to maintain palatability while eliminating Soft Drinks Industry Levy liability. Demand concentrates among professionals in Greater London who face persistent health messaging and workplace wellness programs. This segment commands the steepest expansion trajectory as reformulation investments mature.
- Carbonated:Traditional effervescent delivery systems dominate absolute volume through established brand equity and impulse-purchase visibility in convenience retail. Greater London and the South East corridor anchor consumption, though carbonation adds production complexity and shipping weight that elevates landed costs.
- Organic:Certified formulations exclude synthetic caffeine and artificial additives, appealing to Chelsea and Notting Hill health retailers. Premium positioning at 40% above conventional products restricts mass penetration.
- Non-Carbonated:Still formulations reduce packaging pressure requirements and enable larger single-serve volumes popular in fitness center channels. The Food Standards Agency's caffeine labeling mandates apply equally regardless of carbonation status.
Volume sits with Carbonated; growth tilts toward Sugar-Free.
End User:
Consumption occasion and caffeine sensitivity thresholds separate buyers across professional, athletic, and lifestyle contexts.
- Health Enthusiasts:This buyer cohort prioritizes adaptogen-infused and nootropic-positioned beverages with botanical credentials. Demand clusters in the South East corridor where functional wellness retail density is highest. Clean-label positioning and subscription replenishment models capture lifetime value.
- Professionals:Urban knowledge workers in Manchester and Birmingham drive sugar-free adoption through direct-to-consumer channels with personalized frequency algorithms. Caffeine serves sustained cognitive performance rather than physical exertion.
- Students:Price-sensitive consumption concentrates around university campuses where school proximity sales bans restrict access to high-caffeine formulations. Reformulation to sub-150mg thresholds opens retail locations within mandated exclusion zones.
- Athletes:Performance-oriented buyers seek larger-format cans with electrolyte fortification and branched-chain amino acid inclusion. Gym vending networks and fitness center direct distribution bypass traditional grocery markups.
Revenue concentrates with Professionals; share gains flow fastest to Health Enthusiasts.
Flavor:
Palate preference and bitterness masking requirements create formulation complexity that separates premium from mass-market positioning.
- Citrus:Acidic profiles naturally complement caffeine's bitter notes, reducing reliance on expensive taste-modulation technology. Lemon-lime and grapefruit variants anchor supermarket multipack offerings.
- Berry:Anthocyanin-derived coloring and natural flavor systems appeal to health-conscious positioning. Raspberry and mixed berry profiles dominate organic product lines.
- Tropical:Mango, passionfruit, and pineapple variants mask botanical bitterness from ashwagandha and lion's mane extracts. Premium health retailers pilot these at substantial markups.
- Herbal:Ginger, turmeric, and botanical blends align with adaptogen convergence trends. Extended formulation cycles and supplier qualification demands elevate cost structures.
Mainstream volume flows through Citrus; Tropical climbs fastest on premium positioning.
Distribution Channel:
Channel selection determines margin capture, data access, and regulatory exposure across the British market.
- Supermarkets:Established retail relationships anchor volume through promotional pricing and multipack mechanics. The Competition and Markets Authority monitors pricing practices that could distort consumer choice.
- Online Retail:Direct-to-consumer channels in Manchester and Birmingham capture repeat buyers through subscription algorithms and flavor rotation systems. Data-rich relationships concentrate lifetime value outside impulse retail.
- Convenience Stores:Chilled vending networks in transport hubs enable impulse purchase capture with premium single-serve pricing. Visibility depends on refrigerated space allocation negotiations.
- Fitness Centers:Gym-based distribution bypasses grocery markups and targets post-workout consumption occasions. Placement requires reformulation to sub-150mg caffeine thresholds in school proximity zones.
Absolute volume rests with Supermarkets; Online Retail expands most quickly on subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates heavily in Greater London and the South East corridor, where health-conscious professionals and functional wellness retail density create the highest per-capita consumption rates. The Midlands and North England follow with distinct channel preferences shaped by urban university clusters and industrial city workforces.
Greater London
Health enthusiasts and knowledge workers drive premium positioning for adaptogen-infused formulations. The Food Standards Agency enforces strict caffeine labeling mandates for products exceeding 150mg per serving. Chelsea and Notting Hill health retailers pilot precision fermentation-derived formulations at substantial markups to conventional products.
South East Corridor
Functional wellness retail density and subscription-based replenishment models capture repeat buyers among urban professionals. The Soft Drinks Industry Levy continues reshaping formulation requirements toward zero-sugar portfolios. Brighton and Oxford anchor demand for organic certified products with botanical credentials.
Midlands
University campuses in Birmingham and Manchester concentrate price-sensitive student consumption around reformulated sub-150mg caffeine thresholds. School proximity sales bans restrict access to high-caffeine formulations near educational institutions. Direct-to-consumer channels with personalized frequency algorithms capture professional segments in city centers.
North England
Industrial city workforces sustain demand for larger-format cans through convenience retail and gym vending networks. The Competition and Markets Authority monitors promotional pricing practices in supermarket multipack mechanics. Leeds and Liverpool fitness center distribution bypasses traditional grocery markups for performance-oriented buyers.
Scotland
Gaming culture alignment and esports venue placement create consumption occasions among 18-34 year-old males in Glasgow and Edinburgh. The Advertising Standards Authority's tightened rulings restrict marketing vocabulary around athletic enhancement claims. Chilled vending networks in transport hubs enable impulse purchase capture with premium single-serve pricing.
United Kingdom Energy Drink Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with established beverage conglomerates anchoring supermarket volume while nimble natural energy startups capture premium health retail margins. The vendor base arranges into three tiers: global stimulant beverage giants with extreme sports sponsorship architecture, mid-scale domestic formulators leveraging private-label manufacturing capabilities, and botanical-focused challengers occupying clean-label positioning. Consolidation pressure operates most intensely in the sugar-free portfolio space where reformulation investments demand scale. Capacity expansion into precision fermentation-derived actives and strategic partnerships with gaming streaming platforms represent the dominant competitive vectors.
Within the premium natural positioning tier, Tenzing Natural Energy and Boost Drinks Ltd exemplify the botanical adaptogen convergence that commands 40% price premiums in London health retail. Red Bull GmbH occupies the established global specialist position, its Austrian heritage sustaining premium pricing across British convenience channels. Monster Beverage Corporation anchors the gaming culture alignment vector with larger-format can portfolios. These three archetypes—natural challenger, global heritage brand, and occasion-focused scale player—collectively map the competitive terrain that new entrants must navigate through differentiated formulation or channel-specific capture strategies.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Monster Beverage Corporation |
| PepsiCo Incorporated |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Britvic Plc |
| Tenzing Natural Energy |
| Boost Drinks Ltd |
| Carabao Group PLC |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in British beverage manufacturing anchor supply discipline through centralized procurement and reformulation investment mandates, compressing margin variability across tiered product portfolios while the Soft Drinks Industry Levy forces pricing recalibration toward zero-sugar thresholds.
Pricing Analysis
Volume concentrates in carbonated supermarket multipacks where promotional mechanics and bulk purchasing dominate, while margin capture tilts toward organic and adaptogen-infused variants commanding substantial premiums in Greater London health retail. Three-tier pricing structure across premium, standard, and economy levels separates botanical-certified formulations from conventional synthetic-caffeine products and private-label alternatives. Cost compression in sugar-free R&D is intensifying because natural caffeine extract and taste-modulation technology investments elevate production expenses. Students near university campuses exhibit highest price sensitivity, whereas health enthusiasts in Chelsea and Notting Hill demonstrate lowest elasticity for clean-label positioning.
Supply Chain Analysis
Dual-sourcing requirements from major British retailers mandate multi-supplier qualification for natural caffeine extracts spanning Brazilian arabica processors and East African green coffee traders, alongside botanical adaptogen suppliers from India and China. Raw material dependencies center on caffeine extracts, ashwagandha root powder, and lion's mane mushroom biomass, with artificial sweetener systems drawing from Chinese sucralose and European stevia processors. Single-source vulnerability in Brazilian harvest cycles creates exposure to climate disruption and commodity price spikes. Distribution runs through chilled logistics networks serving supermarket regional distribution centers, convenience retail vending operators, and direct-to-consumer fulfillment hubs in Manchester and Birmingham.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where reformulation capital requirements and regulatory compliance burdens force sub-scale private-label manufacturers toward exit or acquisition.
For Market Incumbents: Anticipate substitution pressure from cold brew coffee and functional sparkling waters by accelerating botanical adaptogen convergence and securing exclusive supplier relationships with East African caffeine processors. Backward integration into precision fermentation-derived actives reduces exposure to agricultural commodity volatility. Channel control through refrigerated vending network expansion in transport hubs and university campuses captures impulse occasions outside price-competitive grocery. For New Entrants and Emerging Players: Health enthusiasts seeking nootropic-positioned beverages represent the most penetrable buyer archetype given their willingness to absorb premium pricing for certified clean-label credentials. Subscription-based replenishment models in the South East corridor offer lower customer acquisition costs than supermarket slotting fee battles. Direct-to-consumer launch with personalized frequency algorithms bypasses entrenched retail gatekeepers and concentrates lifetime value in data-rich relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale domestic formulators with private-label manufacturing capabilities and established supermarket relationships in the Midlands, where school proximity bans have compressed valuations for high-caffeine portfolios. Five-to-ten year viability hinges on successful navigation toward sub-150mg caffeine thresholds and zero-sugar positioning. Watch pending Soft Drinks Industry Levy threshold adjustments as the critical inflection signal for portfolio restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Adaptogen Convergence | Ashwagandha and lion's mane integration differentiates premium positioning beyond caffeine-centric formulations in London health retail. |
| Direct-to-Consumer Channel Launch | Subscription algorithms in Manchester and Birmingham capture repeat buyers outside impulse-driven convenience retail mechanics. |
| Reformulation to Sub-150mg Thresholds | School proximity ban compliance opens university campus vending locations previously restricted under Food Standards Agency mandates. |
| Precision Fermentation Investment | Enzymatic caffeine production compresses cost gap between synthetic and bio-identical actives for clean-label portfolios. |
| Gaming and Esports Partnership | Streaming platform placement creates consumption occasions among 18-34 year-old males in Scotland's urban centers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with brand managers at beverage conglomerates, category buyers at British supermarket chains, supply planners at contract manufacturers, and regulatory affairs leads navigating Food Standards Agency caffeine labeling mandates. Secondary sources encompassed Advertising Standards Authority rulings, Competition and Markets Authority pricing monitoring reports, Soft Drinks Industry Levy implementation data, and chilled logistics operator capacity disclosures. Bottom-up channel volume estimates triangulated against top-down category expenditure flows from retail audit databases.
Granularity-level modeling disaggregated the analysis window by product type, end user archetype, flavor system, and distribution channel, with regional splits across Greater London, South East corridor, Midlands, North England, and Scotland. CAGRs derived from segment-level growth trajectory analysis incorporating reformulation investment cycles, regulatory phase-in schedules, and channel shift elasticity parameters. Industry-specific forecast inputs included natural caffeine extract price indices from Brazilian and East African commodity markets, and subscription service adoption curves from Manchester and Birmingham direct-to-consumer pilots.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Soft Drinks Industry Levy threshold adjustments, Advertising Standards Authority claim restriction expansions, and climate disruption impacts on Brazilian arabica harvest yields. Deviation in natural caffeine extract commodity prices or school proximity ban enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Canned Beverages Market
Beverages
Bottled Air Market
Beverages
Sarsaparilla Market
Beverages
Soft Serve Premix Market
Beverages
Nitro-Infused Cola Market
Beverages
Aloe Vera Drinks Market
Beverages
India Bottled Water Market
Beverages
Drinking Water Market
Beverages
Growlers Market
Beverages
Peanut Oil Market
Beverages
Europe Beverage Market
Beverages
Wellness Water Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Fruit Beverages Market