
 United States and Australia Coconut Water Market | 2026-2036
United States and Australia Coconut Water Market Size, Share, and Industry Trends Forecast 2026-2036
United States and Australia Coconut Water Market Intelligence
The FDA's updated beverage labeling requirements is repositioning coconut water toward stricter electrolyte and sugar disclosure standards. The Vita Coco Company, Inc. leverages its retail shelf presence across major US grocery chains to sustain volume leadership. Harmless Harvest Inc. anchors its market position through high-pressure processing technology and organic certification. Amy & Brian Naturals competes through family-owned operational scale and direct sourcing from Southeast Asian cooperatives.
United States and Australia coconut water denotes the sterile, minimally processed liquid endosperm extracted from mature or young Cocos nucifera fruits, typically standardized to 95-100% coconut water content with pH ranging 4.5-5.5 and total dissolved solids between 4-6 Brix, serving primarily as a natural isotonic beverage for hydration and electrolyte replacement. Pure coconut water dominates shelf space in conventional retail due to its clean-label positioning and established consumer recognition among fitness enthusiasts and health-conscious consumers. Flavored coconut water variants occupy faster-growing positions as manufacturers introduce low-sugar infusions targeting younger demographics seeking taste differentiation without artificial additive penalties. Tetra packs lead packaging configurations for ambient distribution efficiency, while bottles command premium placement in health food stores and cold-chain convenience channels.
Food Standards Australia New Zealand enforces strict nutritional claims verification that limits how coconut water brands market potassium and magnesium content, while the FDA's GRAS notification pathway governs novel processing additives in US formulations. The USDA organic seal and Australian Certified Organic standard create dual certification complexity for brands operating across both markets. Stakeholders must monitor evolving sugar-content thresholds in both jurisdictions as regulators tighten restrictions on naturally sweetened beverages marketed to children.
Market Dynamics
FDA beverage labeling revisions and Food Standards Australia New Zealand nutritional claims verification are compressing formulation flexibility while elevating transparency requirements across both markets. These regulatory pressures reshape how brands communicate electrolyte content and natural sugar levels to fitness-focused consumers.
Growth Catalysts
- High-pressure processing (HPP):Cold pasteurization technology preserves nutrient integrity and extends shelf life without thermal degradation. California and Queensland health food retailers prioritize HPP-treated inventory.
- FDA GRAS pathway clarity:Streamlined notification procedures for novel processing additives accelerate product reformulation timelines. US manufacturers leverage this to introduce functional ingredient variants.
- Post-workout hydration pivot:Fitness enthusiasts in metropolitan Sydney and Los Angeles are displacing synthetic sports drinks with isotonic coconut water. Gym chains and boutique fitness studios now stock ambient tetra packs at point-of-sale.
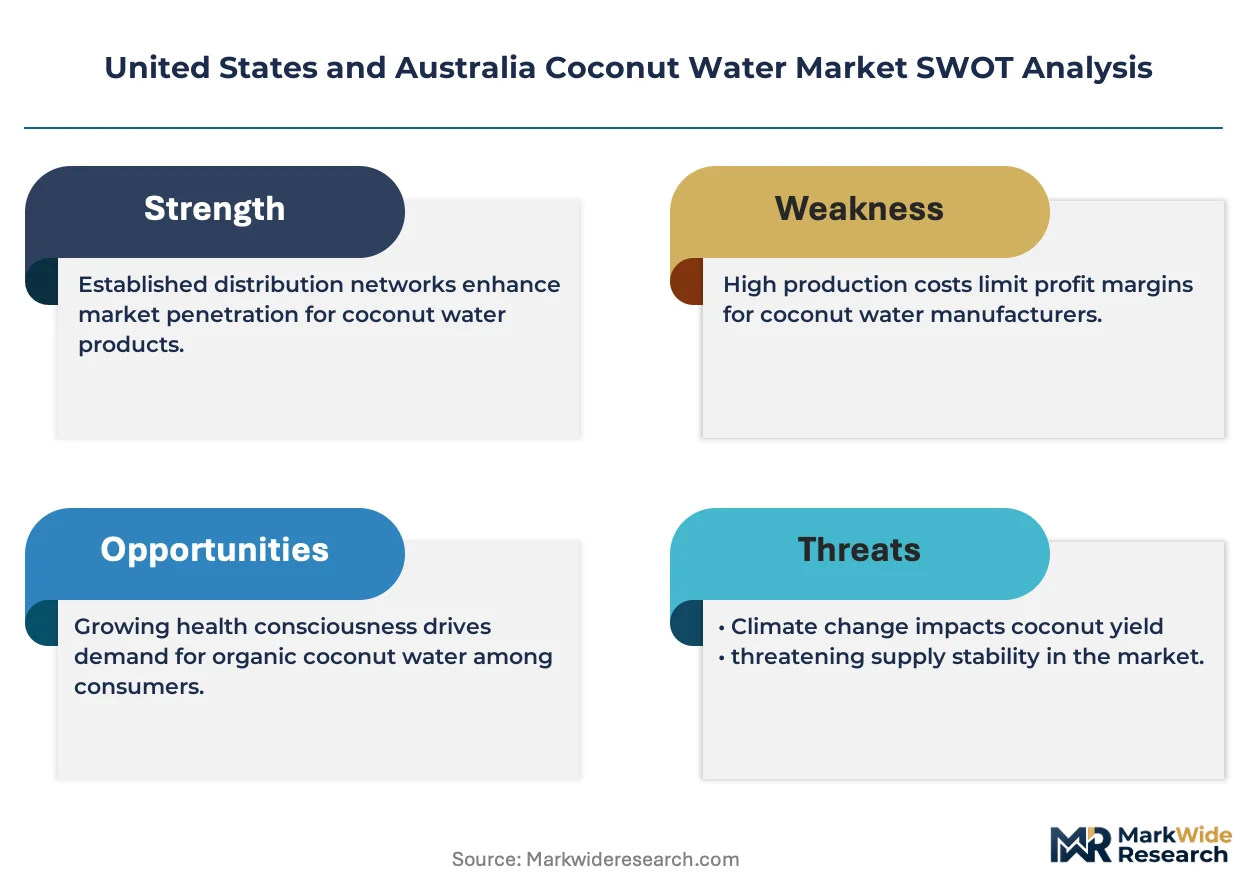
Market Restraints
- Southeast Asian supply concentration:Over 80% of raw coconut water originates from Thai and Indonesian cooperatives. Climate volatility and shipping bottlenecks create input cost instability.
- FSANZ potassium claim restrictions:Australian and New Zealand regulators limit quantitative electrolyte marketing unless verified through standardized testing protocols. This constrains premium positioning strategies.
- Flavored seltzer substitution:Zero-calorie carbonated alternatives capture price-sensitive younger demographics seeking hydration variety without natural sugar content.
Strategic Opportunities
- Direct-to-subscription channels:Melbourne and San Francisco urban professionals demonstrate willingness to commit to recurring delivery of organic-certified SKUs. This bypasses traditional retail slotting fee structures.
- Dual organic certification:USDA Organic and Australian Certified Organic standards create export arbitrage potential for brands with compliant supply chains. Cross-market SKU rationalization reduces formulation complexity.
- Pediatric hydration positioning:Naturally sweetened formulations without artificial additives align with tightening sugar-content thresholds for children's beverages in both jurisdictions.
Industry Challenges
- Cold-chain infrastructure gaps:Premium bottled variants requiring refrigerated distribution face last-mile temperature control failures in secondary Australian markets and US inland states.
- Cooperative supplier coordination:Direct sourcing from Southeast Asian farming collectives demands multilingual procurement teams and seasonal volume forecasting capabilities most mid-tier brands lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States and Australia Coconut Water Market |
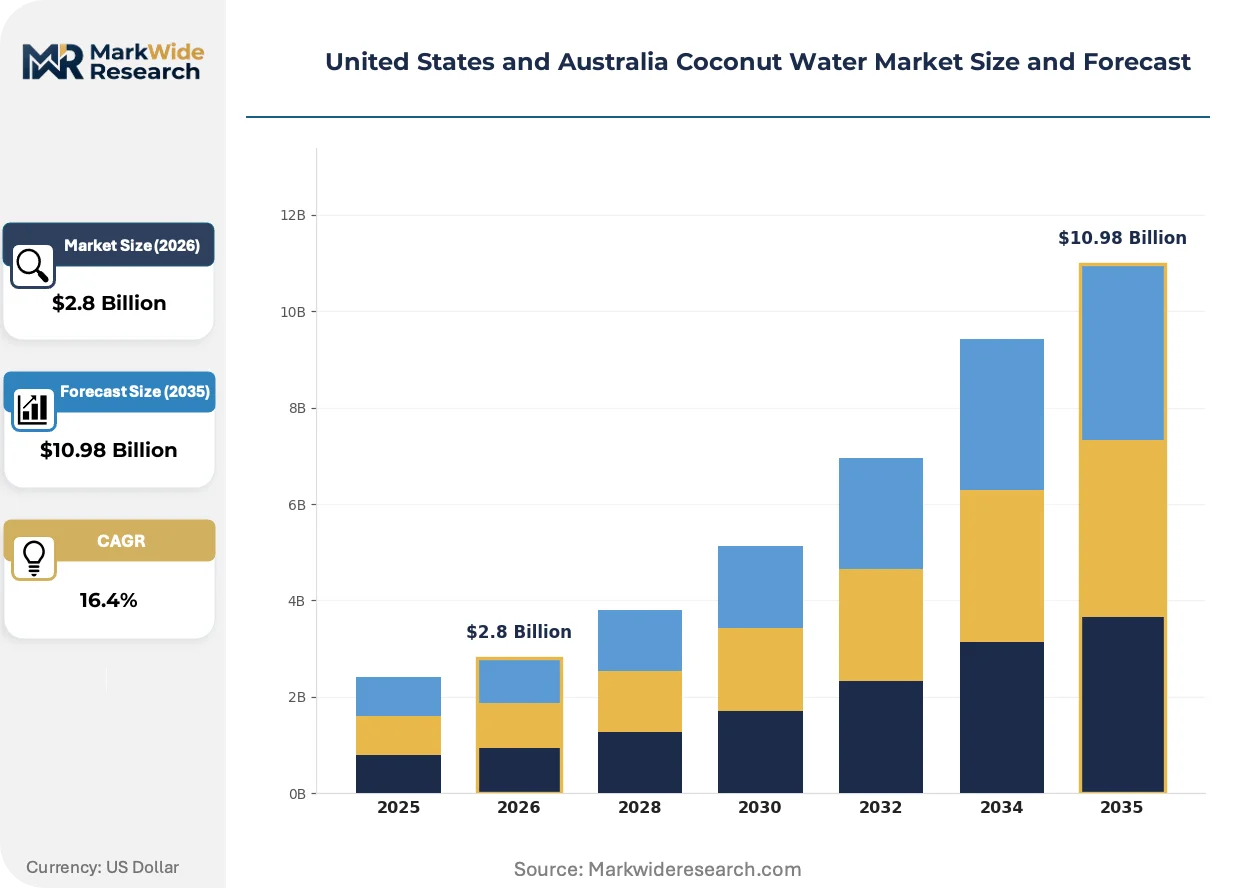
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Coconut Water, Flavored Coconut Water, Coconut Water Mixes, Organic Coconut Water Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores End User: Fitness Enthusiasts, Health Conscious Consumers, Culinary Use, General Consumers Packaging Type: Bottles, Cartons, Pouches, Tetra Packs |
| Companies Covered | All Market Inc., Amy & Brian Naturals, The Vita Coco Company, Inc., C2O Pure Coconut Water, Harmless Harvest Inc., Celebes Coconut Corporation, ZICO Rising, Inc., Taste Nirvana International, Inc., Goya Foods, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States and Australia Coconut Water Market Strategic Shifts & Innovations
Processing technology convergence with regulatory transparency mandates is restructuring competitive advantage around verifiable nutrient retention rather than marketing claims alone. Three developments merit particular attention.
HPP equipment deployment is decentralizing production geography away from centralized thermal pasteurization facilities. Regional bottling operations in California's Central Valley and Queensland's Sunshine Coast now handle raw import processing locally. This compresses cold-chain requirements and enables fresher product positioning for health food store channels.
Food Standards Australia New Zealand's 2023 nutritional claims framework revision tightens evidentiary standards for potassium and magnesium content declarations. Brands must now submit laboratory verification for any quantitative electrolyte marketing. Premium positioning strategies in Australian supermarkets increasingly depend on third-party testing documentation rather than generic natural beverage claims.
Fitness enthusiasts are consolidating purchase decisions around subscription replenishment models rather than impulse retail acquisition. Boutique gym partnerships in Los Angeles and Sydney displace conventional grocery velocity as the primary volume driver. This channel rotation forces brands to reconfigure trade spend away from slotting fees toward partnership revenue-sharing arrangements.
United States and Australia Coconut Water Market Segmentation
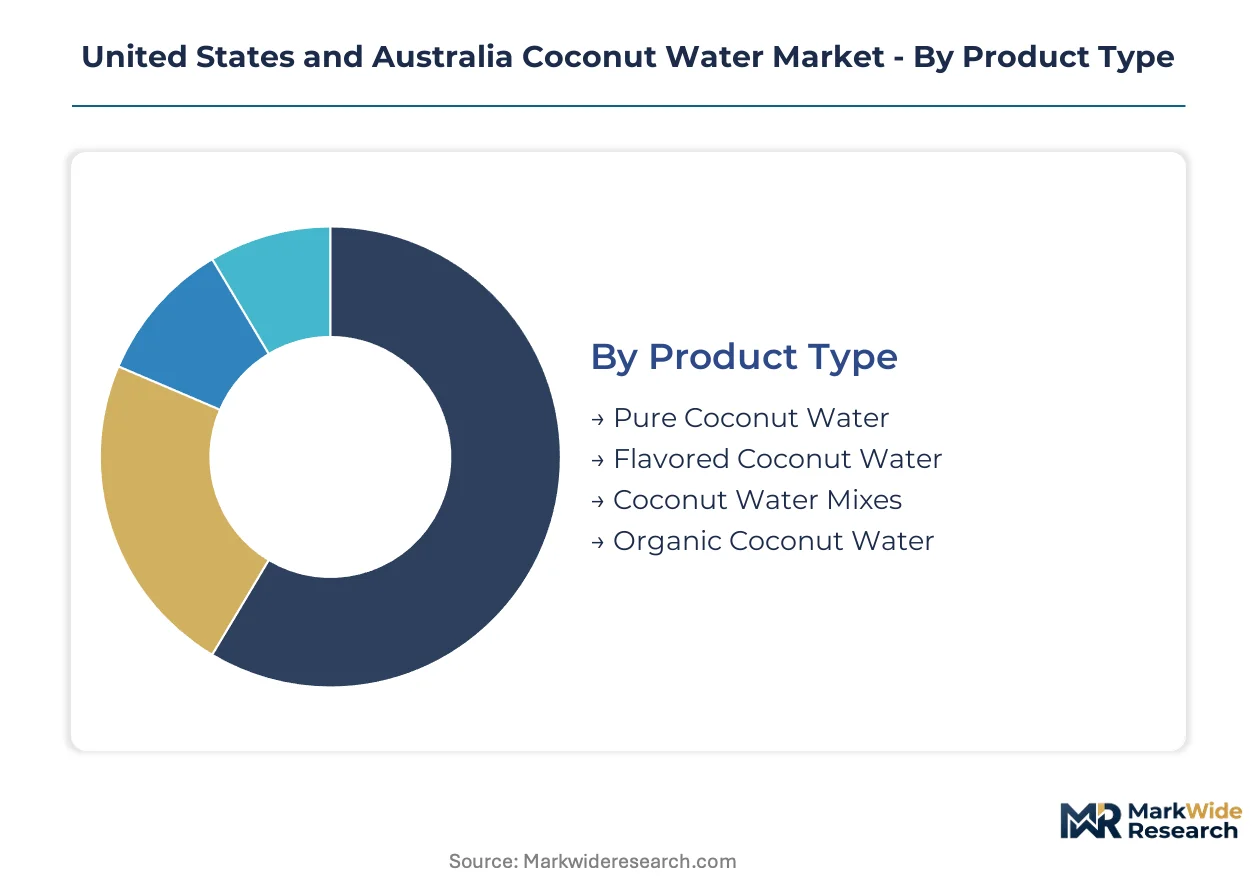
Coconut water manufacturers calibrate formulation, packaging, and channel strategy against distinct buyer willingness-to-pay thresholds and usage occasions. Segment boundaries in this market reflect tension between clean-label purity seekers and convenience-driven taste optimizers.
Product Type:
Purchase frequency and price tolerance diverge sharply between ritual hydration users and experimental flavor adopters across California and Queensland metropolitan markets.
- Pure Coconut Water:Single-ingredient formulations with 95-100% coconut water content dominate conventional retail shelf space. Fitness enthusiasts in Los Angeles and Sydney gyms treat this as a post-workout staple, displacing synthetic sports drinks through electrolyte transparency and minimal processing claims.
- Flavored Coconut Water:Low-sugar infusions with natural fruit essences target younger demographics seeking taste differentiation without artificial additive penalties. Melbourne and San Francisco convenience channels report stronger velocity for mango and pineapple variants than unflavored alternatives.
- Coconut Water Mixes:Powder and concentrate formats reduce shipping weight and enable at-home dilution control. Backpacking and travel segments in Queensland's tourism corridor favor this format for portability.
- Organic Coconut Water:Dual USDA Organic and Australian Certified Organic certification commands 20-40% shelf price premiums. Health food stores in California's Central Valley and Brisbane prioritize this SKU for margin contribution.
Volume sits with Pure Coconut Water; growth tilts toward Flavored Coconut Water.
Distribution Channel:
Channel selection determines margin structure and brand positioning intensity, with cold-chain requirements filtering which formats reach which touchpoints.
- Supermarkets:Ambient tetra pack placement in conventional grocery generates baseline volume through promotional pricing and family-pack sizing. Slotting fees in major US chains exceed independent health food store annual marketing budgets.
- Convenience Stores:Single-serve chilled bottles at point-of-sale capture impulse hydration occasions. Queensland's coastal highway stops and California's interstate corridors show strongest per-square-foot velocity for premium bottled variants.
- Online Retail:Subscription replenishment models bypass retail margin stacking for organic-certified SKUs. San Francisco and Melbourne urban professionals demonstrate highest subscription commitment rates for recurring delivery.
- Health Food Stores:HPP-treated inventory with third-party nutrient verification commands premium placement. Los Angeles and Sydney boutique fitness studio partnerships increasingly route volume through this channel rather than traditional grocery.
Supermarkets anchor current volume; online retail is expanding most quickly.
End User:
Usage context shapes formulation requirements, with electrolyte replacement demands diverging from culinary application specifications.
- Fitness Enthusiasts:Post-workout isotonic hydration drives purchase timing and potassium content scrutiny. Gym chain partnerships in metropolitan Sydney and Los Angeles now stock ambient packs at point-of-sale, displacing conventional sports drink contracts.
- Health Conscious Consumers:Clean-label positioning and sugar-content vigilance prioritize organic certification and minimal processing claims. Queensland's Sunshine Coast and California's Bay Area show highest per-capita consumption correlation with wellness-focused demographics.
- Culinary Use:Smoothie base and fermentation applications require specific pH and brix consistency. Restaurant and café procurement in Melbourne and San Francisco favors larger-format cartons for kitchen efficiency.
- General Consumers:Occasional hydration and taste-driven trial characterize this segment's lower purchase frequency and higher price sensitivity. Flavored variants in convenience channels capture this demographic most effectively.
Fitness Enthusiasts concentrate volume; Health Conscious Consumers show steepest expansion trajectory.
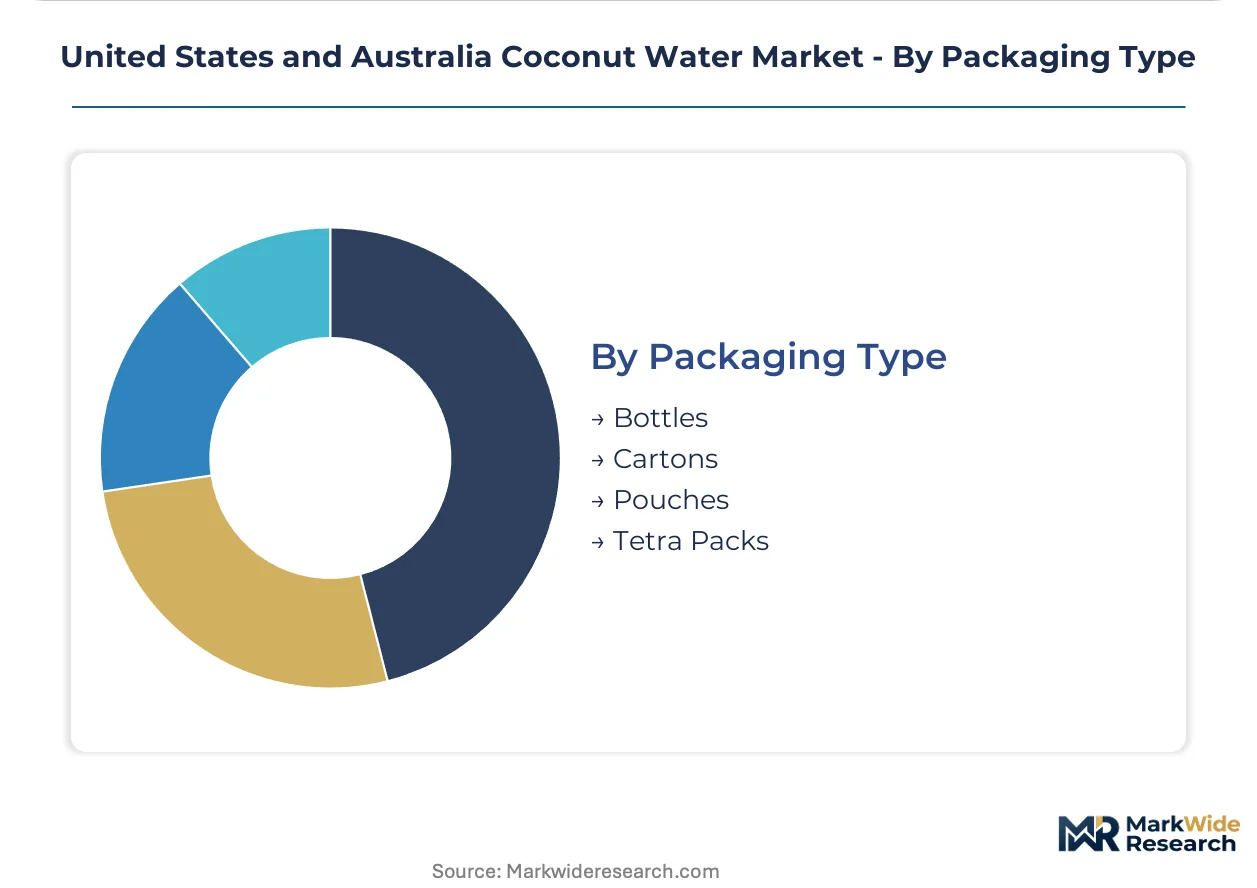
Packaging Type:
Material and format selection trade distribution economics against freshness signaling and environmental positioning.
- Bottles:PET and glass formats enable refrigerated premium positioning with transparent visual quality cues. Cold-chain infrastructure gaps in US inland states and secondary Australian markets constrain geographic reach.
- Cartons:Paperboard with plastic laminate balances shelf stability with sustainability messaging. Conventional grocery ambient aisles in both markets standardize on this format for inventory turnover efficiency.
- Pouches:Flexible film reduces material weight and shipping cost for bulk formats. Food service and institutional buyers in Queensland's hospitality sector favor this for storage density.
- Tetra Packs:Aseptic brick packaging dominates ambient distribution efficiency with established recycling infrastructure. California and Queensland retail channels treat this as the default format for household stock-up occasions.
Tetra Packs hold volume leadership; bottles gain share fastest in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw coconut water extraction concentrates in Thailand and Indonesia while consumption gravity pulls toward California and Queensland metropolitan corridors. This production-consumption divide shapes logistics architecture and cold-chain investment priorities across both markets.
California
Fitness enthusiasts in Los Angeles and San Francisco drive post-workout hydration demand through gym partnerships and subscription replenishment models. The FDA's GRAS notification pathway governs novel processing additives for brands reformulating functional variants. HPP-equipped bottling operations in the Central Valley now handle regional raw import processing, compressing distribution timelines for health food store channels.
Queensland
Proximity to tropical supply routes and health-conscious urban populations in Brisbane and the Sunshine Coast create concentrated consumption corridors. Food Standards Australia New Zealand enforces strict nutritional claims verification that limits quantitative electrolyte marketing. Boutique fitness studios in metropolitan Brisbane increasingly stock ambient tetra packs at point-of-sale, displacing conventional sports drink contracts.
New South Wales
Sydney's metropolitan fitness culture sustains premium bottled variant demand through cold-chain convenience channels. FSANZ potassium claim restrictions constrain premium positioning strategies requiring laboratory verification for quantitative marketing. Coastal highway stops and interstate corridors show strongest per-square-foot velocity for single-serve chilled formats.
Victoria
Melbourne's urban professionals demonstrate highest subscription commitment rates for organic-certified SKUs through direct-to-consumer channels. The USDA organic seal and Australian Certified Organic standard create dual certification complexity for cross-market brands. Health food retailers in inner suburbs prioritize HPP-treated inventory with third-party nutrient verification documentation.
United States and Australia Coconut Water Market Key Industry Players
The competitive structure tilts toward brand-led differentiation rather than manufacturing scale concentration. Market participants fragment across three tiers: mass-market retail incumbents with grocery chain shelf presence, premium organic specialists leveraging processing technology claims, and direct-sourcing cooperatives emphasizing supply chain transparency. Dominant competitive moves include strategic partnerships with fitness channel gatekeepers and portfolio diversification into flavored low-sugar variants targeting younger demographics.
Among established retail incumbents, The Vita Coco Company, Inc. and ZICO Rising, Inc. exemplify mass-market archetypes with conventional grocery penetration. Harmless Harvest Inc. occupies a premium-tier position emphasizing processing technology differentiation. Amy & Brian Naturals represents the family-owned cooperative sourcing model with direct Southeast Asian supply relationships. These three archetypes—retail-scale incumbents, technology-positioned premium players, and transparent-source specialists—collectively define competitive positioning vectors in both markets.
| Leading Market Players |
|---|
| All Market Inc. |
| Amy & Brian Naturals |
| The Vita Coco Company, Inc. |
| C2O Pure Coconut Water |
| Harmless Harvest Inc. |
| Celebes Coconut Corporation |
| ZICO Rising, Inc. |
| Taste Nirvana International, Inc. |
| Goya Foods, Inc. |
| Others |
Cost & Logistics Intelligence
Fitness enthusiasts in Los Angeles and Sydney gyms anchor demand concentration that shapes a three-tier pricing structure across premium, standard, and economy levels. Their willingness to pay for organic certification and HPP processing feeds back into supplier selection favoring direct Southeast Asian cooperative relationships.
Pricing Analysis
Pricing pressure intensifies in the standard tier as flavored seltzer alternatives capture younger demographics seeking hydration without natural sugar content. Price differentiation rests on organic certification grade and cold-chain delivery capability, with premium bottled variants commanding shelf premiums over ambient tetra packs. Cost-down pressure on economy SKUs accelerates because supermarket slotting fees consume margin that brands recapture through volume commitments. Health-conscious consumers in California's Central Valley show least price sensitivity, while occasional hydration users in convenience channels exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates are reshaping sourcing as FDA GRAS notification requirements and FSANZ nutritional claims verification push brands toward documented supply chain transparency. Raw coconut water draws from Thai and Indonesian cooperatives, with Philippine and Vietnamese sources gaining share. Supply chain risk centers on single-source vulnerability from climate volatility in Southeast Asian growing regions. Distribution runs through centralized thermal pasteurization facilities and emerging regional HPP bottling operations in California's Central Valley and Queensland's Sunshine Coast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over Southeast Asian cooperative relationships and downstream fitness channel partnerships determine margin capture.
For Market Incumbents: Anchor shelf position through exclusive gym chain partnerships in metropolitan Sydney and Los Angeles that displace synthetic sports drink contracts. Deepen backward integration into Thai and Indonesian cooperative sourcing to insulate against climate-driven input volatility and secure organic certification traceability. Defend against emerging direct-to-subscription entrants by accelerating HPP equipment deployment in regional bottling facilities.
For New Entrants and Emerging Players: Capture white-space in pediatric hydration positioning as FSANZ and FDA tighten sugar-content thresholds for children's beverages. Target Melbourne and San Francisco subscription replenishment models where urban professionals demonstrate highest commitment rates for organic-certified SKUs. Pursue dual USDA Organic and Australian Certified Organic certification to enable cross-market export arbitrage with rationalized formulation complexity.
For Investors and Strategic Acquirers: The window for entry favors brands with compliant Southeast Asian cooperative relationships and established HPP processing infrastructure. Long-term viability hinges on cold-chain last-mile capabilities in secondary Australian markets and US inland states. Monitor FSANZ potassium claim enforcement intensity as inflection indicator for premium positioning strategy viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Subscription Channel Launch | Bypasses retail slotting fees and captures recurring revenue from Melbourne and San Francisco professionals. |
| Dual Organic Certification Investment | Enables export arbitrage between US and Australian markets with unified SKU rationalization. |
| HPP Equipment Regional Deployment | Compresses cold-chain requirements and enables fresher positioning for health food store channels. |
| Fitness Studio Partnership Network | Displaces conventional sports drink contracts at point-of-sale in Los Angeles and Sydney gyms. |
| Pediatric Hydration Line Extension | Aligns with tightening FDA and FSANZ sugar-content thresholds for children's beverage marketing. |
Research Approach
Multi-period observation of gym channel stocking patterns, subscription commitment rates, and HPP equipment deployment anchored the trend analysis, supplemented by interviews with brand managers at coconut water manufacturers, category buyers at major US grocery chains, procurement leads at Australian health food retailers, and supply planners at Southeast Asian cooperative exporters. Secondary validation drew from FDA GRAS notification filings, FSANZ nutritional claims register updates, USDA organic certification databases, and customs import records. Bottom-up volume triangulation across product type, distribution channel, and end-user segments converged with top-down market sizing.
Segment-weighting approaches applied differential growth assumptions across pure coconut water, flavored variants, and organic-certified SKUs, with channel-specific velocity factors for supermarkets, convenience stores, online retail, and health food stores. End-user segmentation incorporated fitness enthusiast, health-conscious consumer, culinary use, and general consumer demand profiles. CAGRs were derived from fitted trend extrapolation moderated by regulatory enforcement intensity and cold-chain infrastructure investment trajectories. Forecast inputs included cooperative supply volume forecasts and metropolitan fitness club expansion pipelines.
The model holds under stable Southeast Asian climate conditions and consistent FDA and FSANZ regulatory enforcement; deviation in tariff regimes or shipping route disruptions would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Aloe Vera Juice Market
Beverages
Beverages Market
Beverages
Packaged Coconut Water Market
Beverages
Bottled Beverages Market
Beverages
North America Dairy Beverages Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
United States Recovery Drinks Market
Beverages
Europe Smoothies Market
Beverages
Apple Cider Vinegar Market
Beverages
Sports Drink Market
Beverages
North America Yerba Mate Market
Beverages
Birch Water Market
Beverages
North America Fruit Juice Market
Beverages
Herb Infused Water Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Europe Beverage Market