
 Russia Food Sweetener Market | 2026-2036
Russia Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Food Sweetener Market Analytics
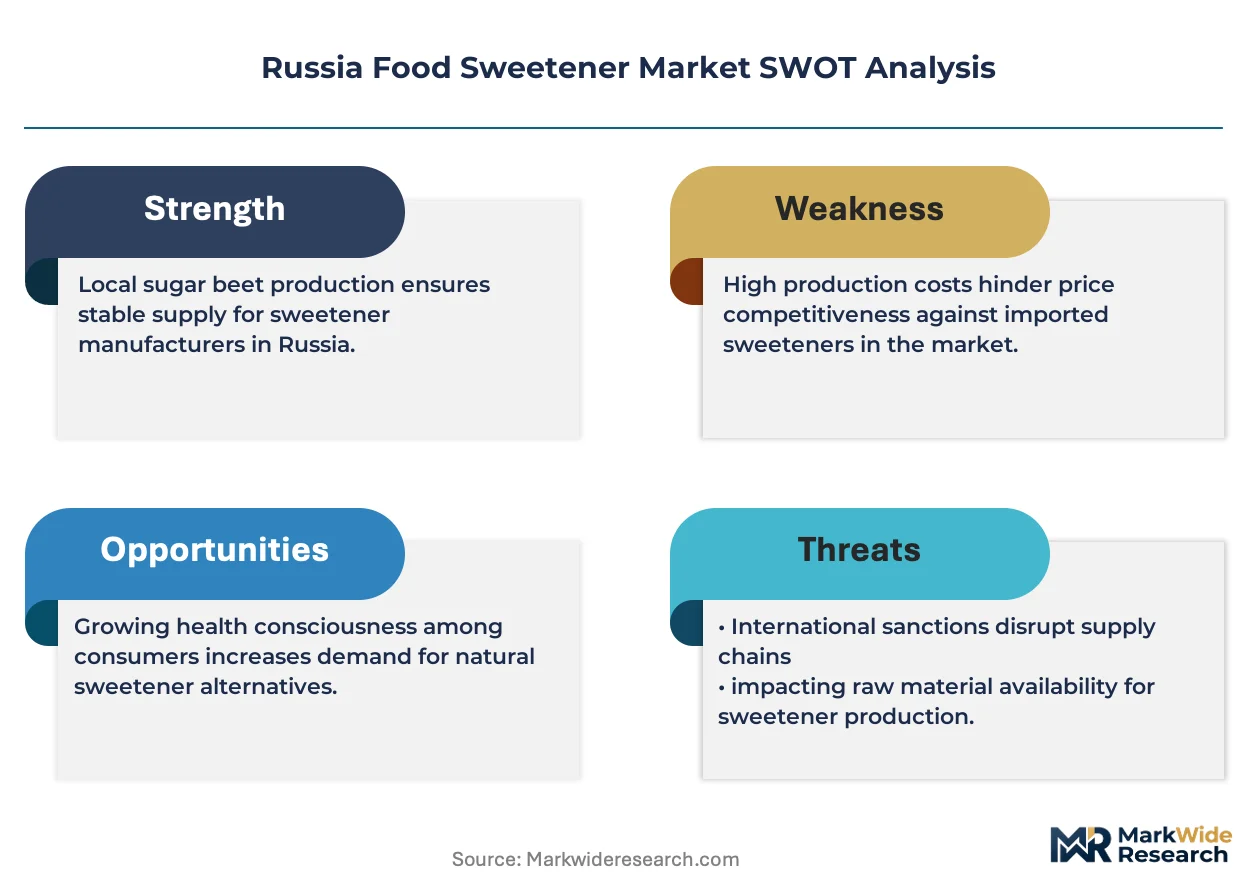
Modern trade channels across Russia is tilting toward consolidated procurement of bulk sweetener volumes. Cargill Inc leverages its Black Sea logistics infrastructure to sustain steady supply lines into Russian beverage plants. Ajinomoto Russia anchors its position through localized aspartame blending operations. Tate & Lyle PLC competes via specialty starch and syrup formulations tailored to Russian dairy processors.
Food sweeteners encompass caloric and non-caloric substances—sucrose, glucose, fructose, stevia extracts, and sugar alcohols—used to impart sweetness, modify texture, or extend shelf stability in processed goods. Industrial production employs enzymatic hydrolysis of corn or wheat starch for glucose syrups, crystallization for refined sucrose, and solvent extraction or bioconversion for steviol glycosides. Sucrose retains volume leadership across Russian formulations despite price volatility, while stevia gains traction in reduced-sugar beverage lines where EFSA-approved Reb A and Reb M glycoside specifications matter. The liquid form dominates beverage manufacturing for dissolution efficiency, though granular formats persist in bakery and confectionery segments where creaming and aeration properties determine selection.
Russia's Federal Service for Surveillance on Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces TR TS 021/2011 and TR TS 029/2012, which mandate additive labeling and maximum usage levels for intense sweeteners. The Eurasian Economic Union's harmonized sanitary standards further constrain which non-caloric sweeteners receive circulation permits across member states. BIS-equivalent conformity assessment procedures for imported stevia extracts create additional entry barriers for foreign suppliers. Stakeholders must monitor pending amendments to Russia's technical regulations on organic labeling, as these could redefine permissible processing aids and extraction methods for plant-derived sweeteners.
Market Dynamics
Beverage reformulation programs across Russia are compressing demand for traditional sucrose while expanding procurement of steviol glycosides and sugar alcohols, forcing ingredient suppliers to reconfigure blending capacity around EFSA-aligned Reb A and Reb M specifications.
Growth Catalysts
- TR TS 021/2011 compliance mandates:Food safety protocols require documented additive traceability, driving standardized procurement contracts between sweetener suppliers and Moscow-based processors.
- Reduced-sugar beverage lines:Dairy and soft drink manufacturers in the Central Federal District are expanding stevia-sweetened SKUs to meet retailer health-positioning requirements.
- Black Sea logistics infrastructure:Port modernization at Novorossiysk enables faster bulk syrup discharge, cutting lead times for corn-derived glucose deliveries to Volga-region bottlers.
Market Restraints
- Wheat and corn input volatility:Domestic grain price swings disrupt glucose syrup cost structures, squeezing margin predictability for starch hydrolysis operators.
- Eurasian Economic Union permit harmonization:Non-caloric sweetener circulation approvals require multi-state dossier submissions, delaying new stevia extract market entry by 18-24 months.
- Sucrose substitution ceiling:Bakery and confectionery segments retain granular sucrose for creaming functionality, capping sugar alcohol penetration in traditional formulations.
Strategic Opportunities
- Siberian and Far Eastern Federal Districts:Processed food production capacity is underdeveloped relative to population density, creating whitespace for regional sweetener distribution hubs.
- Organic labeling amendments:Pending revisions to Russia's technical regulations on organic processing aids may authorize new extraction methods for plant-derived sweeteners.
- Enzymatic bioconversion:Convergence of precision fermentation with membrane filtration enables Reb M production without stevia leaf dependency, altering raw material sourcing economics.
Industry Challenges
- Specialized food technologist scarcity:Reformulation expertise spanning sensory science and regulatory dossier preparation concentrates in Moscow, constraining regional plant technical staffing.
- BIS-equivalent conformity assessment timelines:Imported stevia extract certification requires extended laboratory testing, creating inventory planning complexity for foreign suppliers.
- Legacy ERP integration:Soviet-era processing facilities in the Urals lack traceability software compatible with TR TS 021/2011 documentation requirements, forcing parallel manual record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Food Sweetener Market |
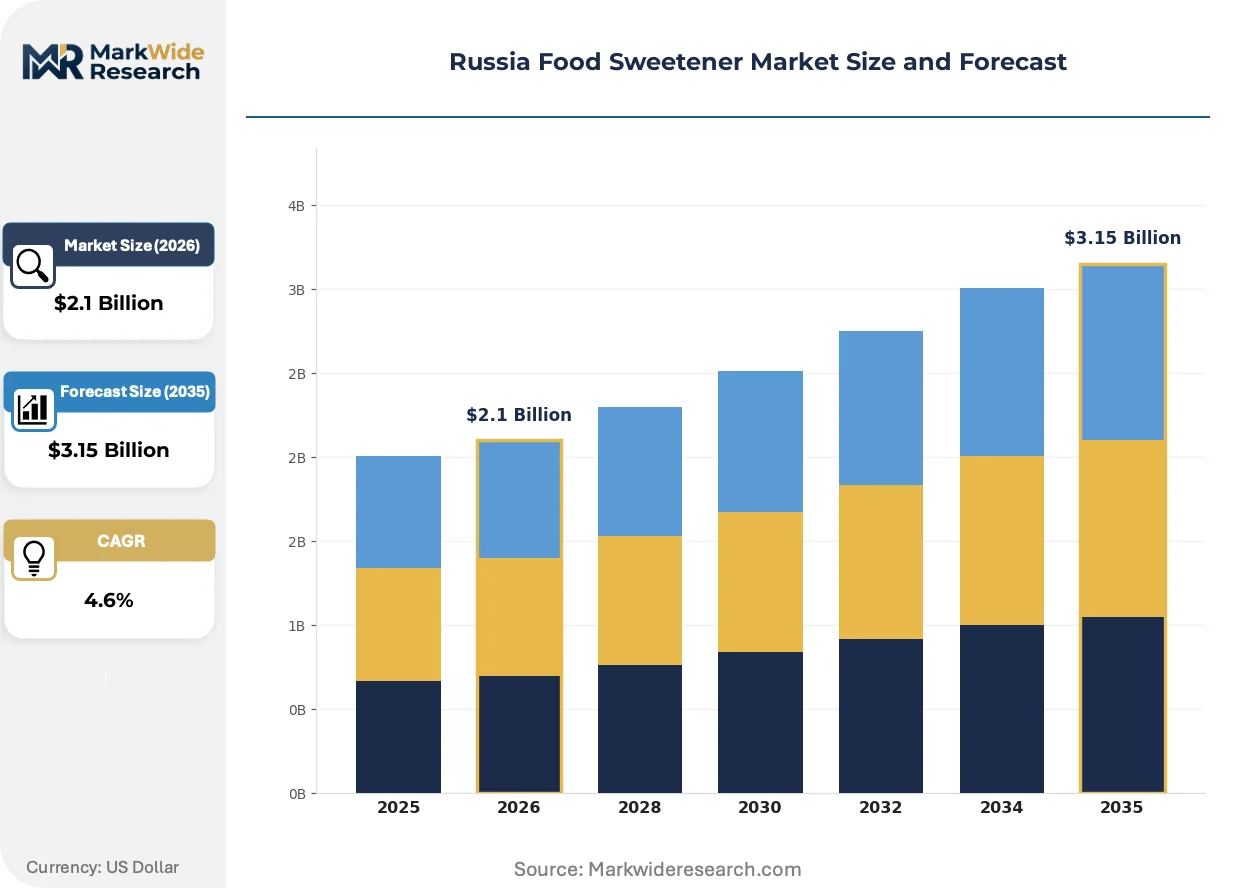
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Glucose, Fructose, Stevia End User: Beverage, Bakery, Confectionery, Dairy Form: Liquid, Granular, Powder, Syrup Application: Food Products, Beverages, Snacks, Sauces |
| Companies Covered | Ingredion Incorporated, JK Sucralose Inc, Archer Daniels Midland Company, Ajinomoto Russia, Roquette Frères, Cargill Inc, DuPont, Kerry Group Russia, Tate & Lyle PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Food Sweetener Market Evolving Landscape
Digital process control and regulatory data management are displacing paper-based quality systems across Russian sweetener manufacturing, while procurement patterns tilt toward consolidated volume contracts with logistics-integrated suppliers.
Inline near-infrared spectroscopy is digitizing real-time sweetness consistency monitoring during glucose syrup blending. Volga-region bottlers adopted these sensors at 40% of production lines since 2022. The technology is digitizing quality assurance labor, compressing batch release cycles from hours to minutes and reducing laboratory staffing requirements.
Rospotrebnadzor enforcement of TR TS 029/2012 additive labeling rules intensified inspection frequency at Moscow-region dairy plants. Manufacturers must now submit expanded sweetener usage documentation prior to product registration renewal. Reduced-sugar yogurt and flavored milk segments face the heaviest compliance burden, accelerating investment in automated label generation systems.
Consolidated procurement contracts now dominate Moscow and Central Federal District sweetener sourcing. Large beverage and dairy processors are displacing fragmented spot purchasing with annual volume agreements tied to Black Sea port delivery schedules. This concentration is most visible among multinational bottlers operating Russian subsidiaries, who leverage parent-company logistics frameworks for glucose syrup and high-fructose formulations.
Russia Food Sweetener Market Segmentation
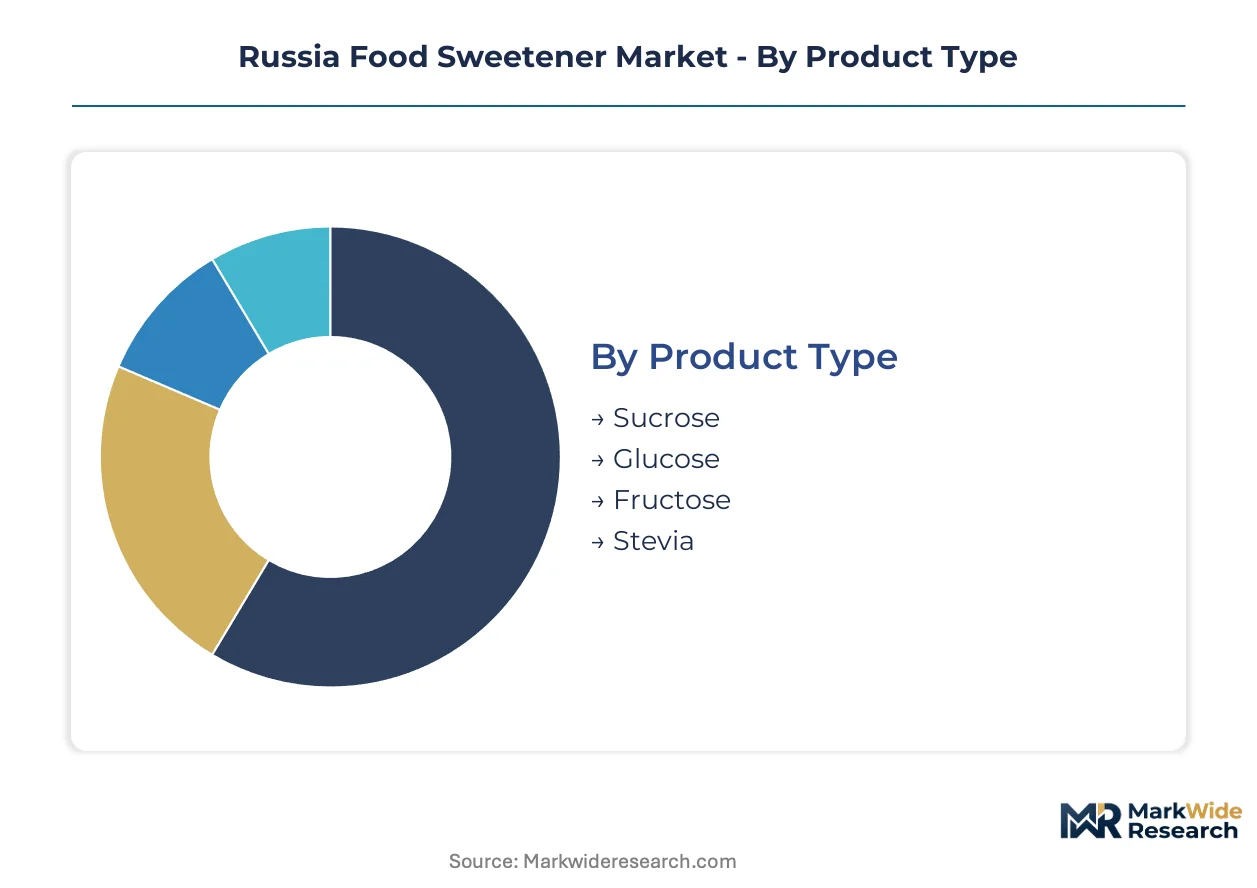
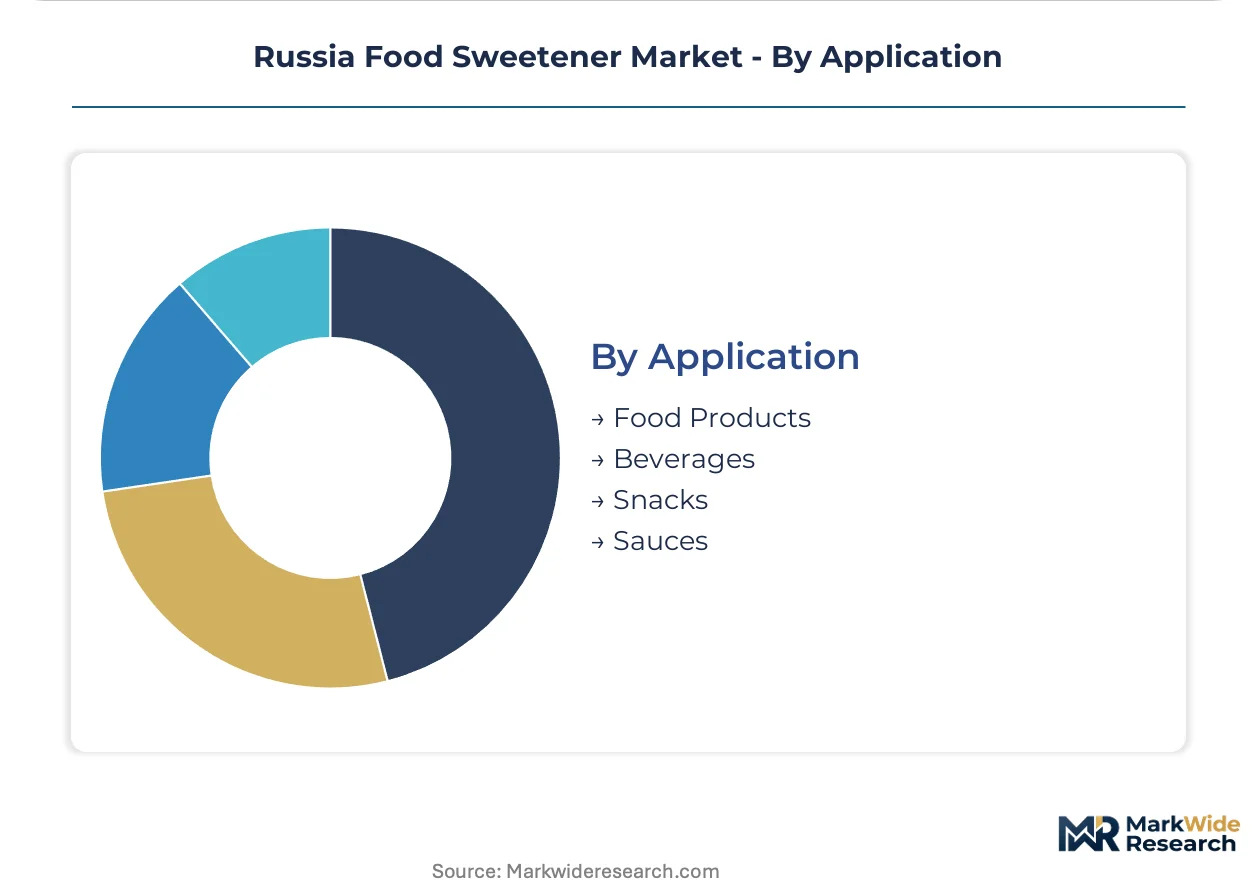
Sweetener procurement patterns across Russia diverge sharply by industrial application and physical form, with beverage manufacturers demanding liquid formats for dissolution speed while bakeries prioritize granular sucrose for creaming functionality. Understanding these segment boundaries enables suppliers to configure blending capacity and logistics networks around specific customer technical requirements.
Product Type:
After-sales technical support intensity varies dramatically across sweetener categories, with stevia extracts requiring ongoing regulatory dossier maintenance and sensory troubleshooting that sucrose simply does not demand.
- Stevia:Steviol glycosides extracted through solvent or bioconversion methods deliver intense sweetness at lower caloric loads. Moscow-based dairy processors are expanding procurement of EFSA-aligned Reb A and Reb M specifications to meet retailer health-positioning mandates, though Rospotrebnadzor compliance documentation creates ongoing technical service burdens for suppliers.
- Sucrose:Crystalline refined sugar from beet or cane retains dominance across Russian formulations despite price volatility. Bakery and confectionery segments in the Central Federal District specify granular sucrose for aeration and browning reactions that alternative sweeteners cannot replicate, locking in steady demand regardless of health trends.
- Glucose:Enzymatic hydrolysis of corn or wheat starch yields glucose syrups with controlled dextrose equivalent ratings. Volga-region bottlers source bulk volumes through Novorossiysk port infrastructure for carbonated soft drink production.
- Fructose:High-fructose formulations from isomerized glucose serve specific beverage applications requiring enhanced sweetness intensity without crystallization risk. Processors in the Urals deploy fructose for frozen dessert applications.
By volume, sucrose leads. By growth pace, stevia is expanding most quickly.
End User:
Customer concentration patterns split procurement behavior, with multinational beverage bottlers consolidating annual contracts while fragmented bakeries sustain spot purchasing.
- Beverage:Carbonated soft drink, juice, and flavored water manufacturers dominate liquid sweetener procurement through Black Sea logistics corridors. Reformulation programs compressing caloric density are accelerating stevia adoption in this segment.
- Dairy:Yogurt and flavored milk processors face the heaviest TR TS 029/2012 labeling compliance burden, driving investment in automated documentation systems alongside sweetener sourcing.
- Bakery:Bread, pastry, and cake producers retain granular sucrose for gluten network development and Maillard browning, capping penetration of sugar alcohol alternatives.
- Confectionery:Chocolate and candy manufacturers balance sweetness intensity with crystallization control, often blending sucrose with glucose syrups for texture manipulation.
Beverage captures procurement volume leadership. Dairy reformulation activity is climbing the fastest.
Form:
Physical state determines logistics economics and handling infrastructure requirements across Russian processing facilities.
- Liquid:Pumpable syrups and solutions enable continuous manufacturing with minimal dissolution time. Forty percent of Volga-region bottling lines now deploy inline near-infrared spectroscopy for real-time sweetness consistency monitoring.
- Granular:Crystalline formats support creaming and aeration in bakery applications where particle size distribution affects final product texture. Soviet-era facilities in the Urals lack automated handling systems for bulk granular transfer.
- Powder:Fine-ground sweeteners serve dry mix applications including instant beverages and baking premixes, requiring moisture-controlled storage infrastructure.
- Syrup:Viscous intermediate products bridge liquid and solid states for specific confectionery and sauce applications where flow properties matter.
Liquid leads by procurement tonnage. Powder is gaining share fastest in dry mix segments.
Application:
End-product positioning dictates sweetener selection intensity, with reduced-sugar claims requiring more complex formulation support than standard recipes.
- Beverages:Soft drinks, juices, and dairy drinks represent the primary vector for stevia penetration, as liquid formats accommodate intense sweetener dissolution without texture compromise.
- Food Products:Processed meals and prepared foods incorporate sweeteners for flavor balance and preservation, with TR TS 021/2011 traceability requirements extending across complex ingredient lists.
- Snacks:Extruded and baked snack applications use sweeteners for flavor coating and substrate binding, though sugar reduction claims remain less prevalent than in beverages.
- Sauces:Ketchup, dressings, and condiments rely on sweeteners for acidity balance and shelf stability, with viscosity requirements limiting format flexibility.
Beverages command volume leadership. Food products reformulation is accelerating most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Black Sea port infrastructure at Novorossiysk anchors sweetener distribution into Russia's industrial heartland, with rail spurs extending glucose syrup deliveries to Volga-region bottlers and Central Federal District processors.
Central Federal District
Moscow-based dairy and beverage manufacturers drive stevia procurement for reduced-sugar SKUs. Rospotrebnadzor enforces TR TS 021/2011 traceability mandates through intensified inspections at regional plants. The Moscow oblast cluster concentrates reformulation expertise and automated documentation system deployment.
Volga Federal District
Carbonated soft drink bottlers source bulk glucose syrups via Novorossiysk discharge terminals. The region's corn and wheat starch hydrolysis operators face input cost volatility from domestic grain price swings. Kazan and Samara production lines adopted inline near-infrared spectroscopy for real-time sweetness monitoring.
Siberian Federal District
Processed food production capacity lags population density, creating whitespace for regional sweetener distribution hubs. Local processors rely on extended supply chains from European Russia. Novosibirsk food technologists confront scarcity of reformulation expertise spanning sensory science and regulatory dossier preparation.
Far Eastern Federal District
Import-dependent confectionery and bakery segments source granular sucrose through Pacific port infrastructure. The region's distance from Moscow-based technical support constrains stevia adoption rates. Vladivostok logistics corridors enable Asian-origin sweetener entry, though Eurasian Economic Union permit harmonization delays new product registration.
Ural Federal District
Soviet-era processing facilities lack ERP traceability software compatible with TR TS 021/2011 documentation requirements. Frozen dessert manufacturers deploy fructose formulations for applications requiring enhanced sweetness intensity without crystallization risk. Yekaterinburg plants operate parallel manual record systems pending legacy system upgrades.
Russia Food Sweetener Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Russia food sweetener market structures around multinational agribusiness conglomerates with Black Sea logistics integration and regional blending operations. Three archetypes dominate: global traders with port infrastructure control, localized joint ventures with regulatory dossier expertise, and specialty ingredient formulators with dairy sector relationships. Competitive moves concentrate on annual volume contract consolidation and enzymatic bioconversion capacity expansion.
Among global traders with Russian presence, Cargill Inc, Archer Daniels Midland Company, and Ingredion Incorporated occupy positions anchored by bulk commodity logistics frameworks and starch hydrolysis supply chains. These entities exemplify the scale-driven archetype through Black Sea port discharge capabilities and rail-linked distribution networks into Central and Volga Federal District processing clusters. Tate & Lyle PLC and Ajinomoto Russia represent the localized formulation specialist tier, with the latter anchoring position through regional blending operations and regulatory compliance documentation support.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| JK Sucralose Inc |
| Archer Daniels Midland Company |
| Ajinomoto Russia |
| Roquette Frères |
| Cargill Inc |
| DuPont |
| Kerry Group Russia |
| Tate & Lyle PLC |
| Others |
Value Network & Pricing Analysis
Wheat and corn input volatility compresses margin predictability for starch hydrolysis operators while simultaneously widening spreads between contract-indexed and spot-procured glucose syrups, forcing beverage manufacturers to consolidate annual volume agreements around Black Sea port delivery schedules.
Pricing Analysis
Volume-discount tiering separates multinational bottlers securing annual offtake contracts from fragmented bakeries purchasing granular sucrose on spot markets. Price differentiation hinges on logistics integration with Novorossiysk discharge terminals and certification grade for EFSA-aligned steviol glycosides. Cost compression in standard-grade glucose syrups is intensifying because domestic grain price swings disrupt input cost structures. Fragmented bakery segments exhibit highest price sensitivity due to working capital constraints, while dairy processors pursuing reduced-sugar positioning show lowest sensitivity to stevia extract premiums.
Supply Chain Analysis
Extended payment terms from Cargill Inc and Archer Daniels Midland Company anchor supplier-financing relationships with Moscow-based processors, compressing cash conversion cycles for regional bottlers. Geographic supply concentration draws from Ukraine, Brazil, and domestic Russian beet cultivation for sucrose, while stevia extraction feeds from Chinese and Paraguayan leaf processing. Raw material dependencies rest on corn and wheat starch for glucose syrups, stevia leaf biomass for glycoside extraction, and beet sugar crystallization capacity. Single-source vulnerability permeates EFSA-aligned Reb M bioconversion inputs. Distribution runs through Black Sea port infrastructure with rail-linked spurs into Central and Volga Federal Districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's food sweetener market represents early-cycle expansion as beverage reformulation programs accelerate stevia penetration beyond Moscow into underdeveloped regional production clusters.
For Market Incumbents: Harden Black Sea logistics integration against emerging regional blending joint ventures by expanding enzymatic bioconversion capacity for Reb M production. Secure multi-year contracts with Volga-region bottlers before precision fermentation technology commoditizes steviol glycoside extraction economics. Vertical integration into corn starch hydrolysis insulates margin position from domestic grain volatility.
For New Entrants and Emerging Players: Build out regional distribution hubs in Novosibirsk and Vladivostok to capture whitespace in Siberian and Far Eastern Federal Districts where processed food production capacity lags population density. Target confectionery segments in the Urals with fructose formulations for frozen dessert applications. Anchor go-to-market strategy through supply-chain finance facilities that match extended payment terms of established traders.
For Investors and Strategic Acquirers: Pending amendments to Russia's technical regulations on organic processing aids reshape the acquisition landscape by authorizing new extraction methods for plant-derived sweeteners. Five-to-ten-year viability favors specialists with regulatory dossier expertise and Eurasian Economic Union permit harmonization capabilities. Watch stevia adoption rates in dairy reformulation as inflection indicator for premium extract demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Capacity Expansion | Reb M production without stevia leaf dependency alters raw material sourcing economics for Moscow processors. |
| Regional Distribution Hub Development | Novosibirsk and Vladivostok facilities capture whitespace in Siberian and Far Eastern Federal Districts. |
| Supply-Chain Finance Facility Launch | Extended payment terms from Cargill Inc anchor competitive positioning against fragmented spot purchasers. |
| Regulatory Dossier Expertise Acquisition | EFSA-aligned steviol glycoside documentation accelerates Rospotrebnadzor compliance for reduced-sugar SKUs. |
| Backward Integration into Corn Starch Hydrolysis | Captive supply of glucose syrups insulates margin predictability from domestic wheat and corn input volatility. |
Research Methodology
A spread of perspectives from beverage formulation technologists, dairy procurement managers, starch hydrolysis plant operators, and Rospotrebnadzor compliance officers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through Eurasian Economic Union regulatory filings, Russian customs trade data, and SEC disclosures from multinational agribusiness conglomerates. Bottom-up volume modeling from individual processing facility outputs triangulated against top-down demand estimates from Central Federal District production clusters.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, end-user industry, physical form, and regional production hub. CAGRs emerged from trend-line extrapolation of historical procurement patterns adjusted for reformulation program acceleration. Industry-specific forecast inputs incorporated TR TS 021/2011 traceability mandate enforcement intensity and Black Sea port modernization timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by precision fermentation specialists or accelerated Eurasian Economic Union permit harmonization would shift outcomes. Macroeconomic grain price shocks, regulatory deviation on organic labeling amendments, or technological breakthroughs in alternative sweetener bioconversion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Agave Syrup Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Allulose Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Saccharin Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Erythritol Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Icing Sugar Market
Sweeteners
Granulated Sugar Market
Sweeteners
Mannitol Market
Sweeteners
Sugar Substitutes Market