
 Lysosomal Acid Lipase (LAL) Deficiency Treatment Market | 2026-2036
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market Outlook
Outcome-based financing and risk-sharing agreements between enzyme manufacturers and public payers is reconfiguring how biologics companies compete in rare disease markets. Alexion Pharmaceuticals leverages its established rare disease infrastructure to sustain market presence in lysosomal storage disorders. AstraZeneca anchors its position through integrated diagnostics-to-therapy platforms that streamline patient identification. Pfizer Inc. competes by controlling global manufacturing scale for biologic supply security.
Lysosomal Acid Lipase Deficiency Treatment encompasses therapeutic interventions that restore or compensate for deficient LAL enzyme activity, primarily through recombinant human enzyme infusions administered intravenously every other week to prevent cholestasis, fibrosis, and premature cardiovascular complications in Wolman disease and cholesteryl ester storage disease. Enzyme Replacement Therapy dominates current revenue as the only approved modality with established infusion protocols and long-term safety data. Gene Therapy represents the fastest-expanding segment as adeno-associated viral vector platforms advance through clinical pipelines, though margin pools remain concentrated in intravenous delivery infrastructure due to hospital-based administration requirements and cold-chain logistics complexity.
FDA orphan drug exclusivity provisions and EMA's priority medicines designation shape development incentives by granting market protection and accelerated review timelines for LAL deficiency therapies, while the EU's F-Gas Regulation imposes containment requirements on cold-chain refrigerants used in biologic distribution. Japan's PMDA sakigake designation offers early conditional approval pathways that reduce time-to-market for innovative rare disease treatments. Stakeholders must monitor evolving gene therapy reimbursement frameworks and manufacturing capacity constraints as pipeline candidates transition from clinical trials to commercial scale.
Market Dynamics
Gene therapy vectors are compressing development timelines for LAL deficiency treatments while intravenous infusion infrastructure locks in hospital-based delivery economics. This technological tension between curative ambition and logistical constraint defines current competitive positioning.
Growth Catalysts
- FDA orphan drug exclusivity:Seven-year market protection accelerates investment in rare disease pipelines by de-risking commercialization timelines for enzyme replacement therapies.
- Pediatric hepatology clinic networks:Specialized metabolic centers in the United States concentrate patient identification expertise and streamline referral pathways for Wolman disease screening.
- Adeno-associated viral vector platforms:Improved transduction efficiency in hepatocyte targeting is expanding addressable patient populations beyond current infusion-dependent cohorts.
Market Restraints
- Cold-chain biologics distribution:EU F-Gas Regulation containment requirements for refrigerants add compliance cost layers to enzyme replacement therapy logistics.
- Single-source manufacturing concentration:Recombinant protein production capacity clusters in contract manufacturing organizations with limited viral vector expertise.
- Intravenous administration burden:Biweekly hospital infusion requirements create adherence friction that compresses effective treatment duration metrics.
Strategic Opportunities
- Japan PMDA sakigake pathway:Early conditional approval frameworks reduce time-to-market for gene therapy candidates targeting cholesteryl ester storage disease.
- Subcutaneous delivery formulation:Route-of-administration innovation could shift treatment site from infusion centers to home health settings.
- Neonatal screening expansion:State-level metabolic panel additions in the United States are identifying presymptomatic patients before organ damage progression.
Industry Challenges
- Gene therapy manufacturing scale-up:Viral vector production bottlenecks constrain supply for late-stage clinical trials and commercial launch readiness.
- Reimbursement evidence generation:Payers require long-term cardiovascular outcome data that exceeds typical clinical trial observation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lysosomal Acid Lipase (LAL) Deficiency Treatment Market |
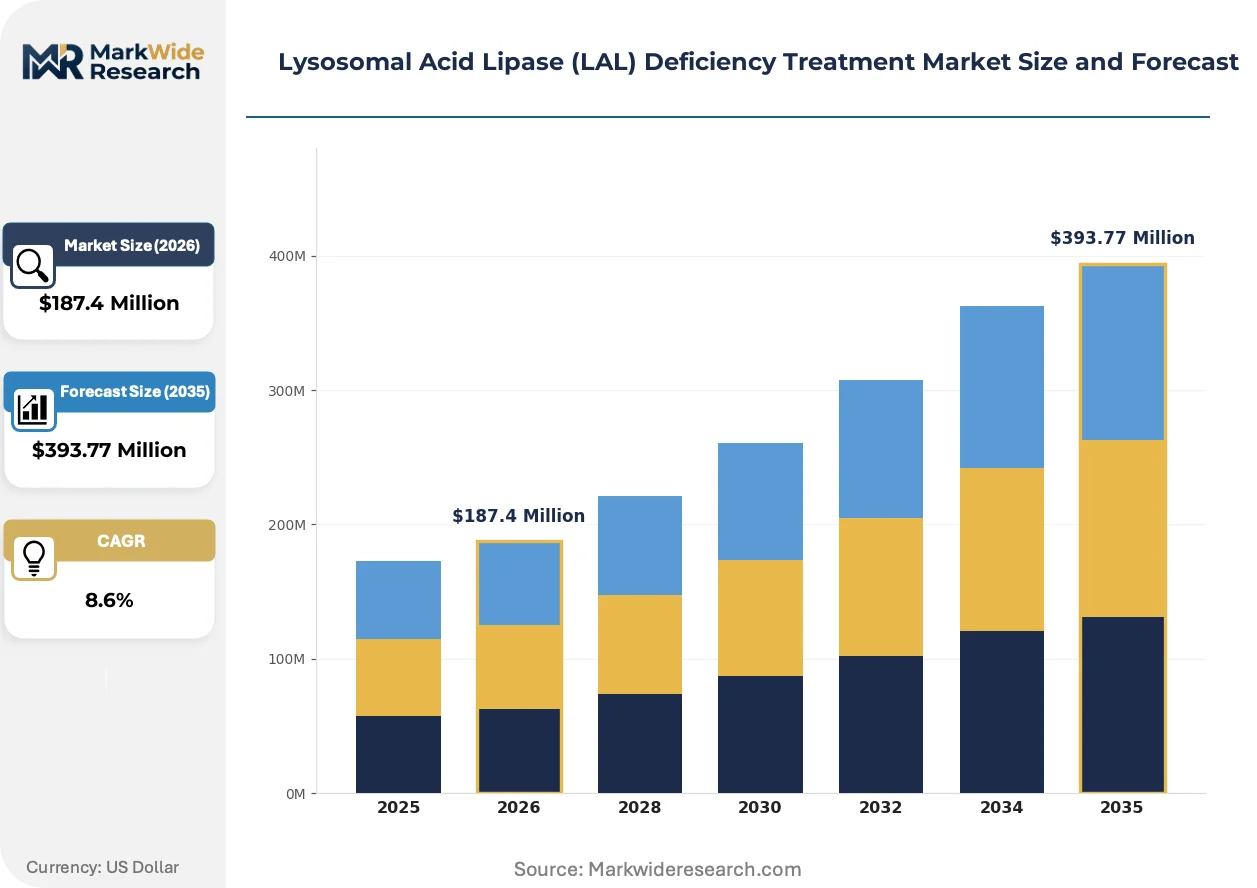
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Small Molecule Inhibitors, Biologics Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Specialty Pharmacies, Home Healthcare Treatment Stage: Diagnosis, Active Treatment, Long-term Management, Palliative Care |
| Companies Covered | Alexion Pharmaceuticals, AstraZeneca, Merck & Co., Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd, Amgen Inc., BioCrick BioTech, Regeneron Pharmaceuticals, Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market Strategic Shifts
Next-generation sequencing integration is compressing diagnostic latency while regulatory frameworks adapt to single-administration curative modalities. These shifts are reconfiguring stakeholder economics across the treatment value chain.
Artificial intelligence platforms are digitizing patient stratification for clinical trial recruitment by analyzing multi-omics datasets to identify LAL deficiency phenotypes earlier than enzymatic assay thresholds allow. Contract research organizations serving rare disease sponsors are deploying these tools to reduce screening failure rates. The structural consequence is a compression in trial enrollment timelines that accelerates regulatory submission schedules.
EMA's priority medicines designation is streamrolling assessment pathways for therapies addressing unmet needs in lysosomal storage disorders by granting accelerated review timelines and enhanced scientific advice access. This regulatory tailwind is concentrating development investment in modalities that demonstrate disease-modifying potential beyond symptomatic management. Manufacturers are responding by prioritizing cardiovascular endpoint trials that satisfy health technology assessment bodies in Germany and France.
Diagnostic service unbundling is fragmenting traditional referral patterns as direct-to-consumer genetic testing platforms identify carrier status and incidental LAL gene variants. Academic medical centers with established metabolic programs are capturing these patients through telemedicine consultation channels before regional hospital systems can establish care relationships. This behavioral shift is most pronounced in the United States where out-of-network genetic counseling regulations vary by state.
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market Segmentation
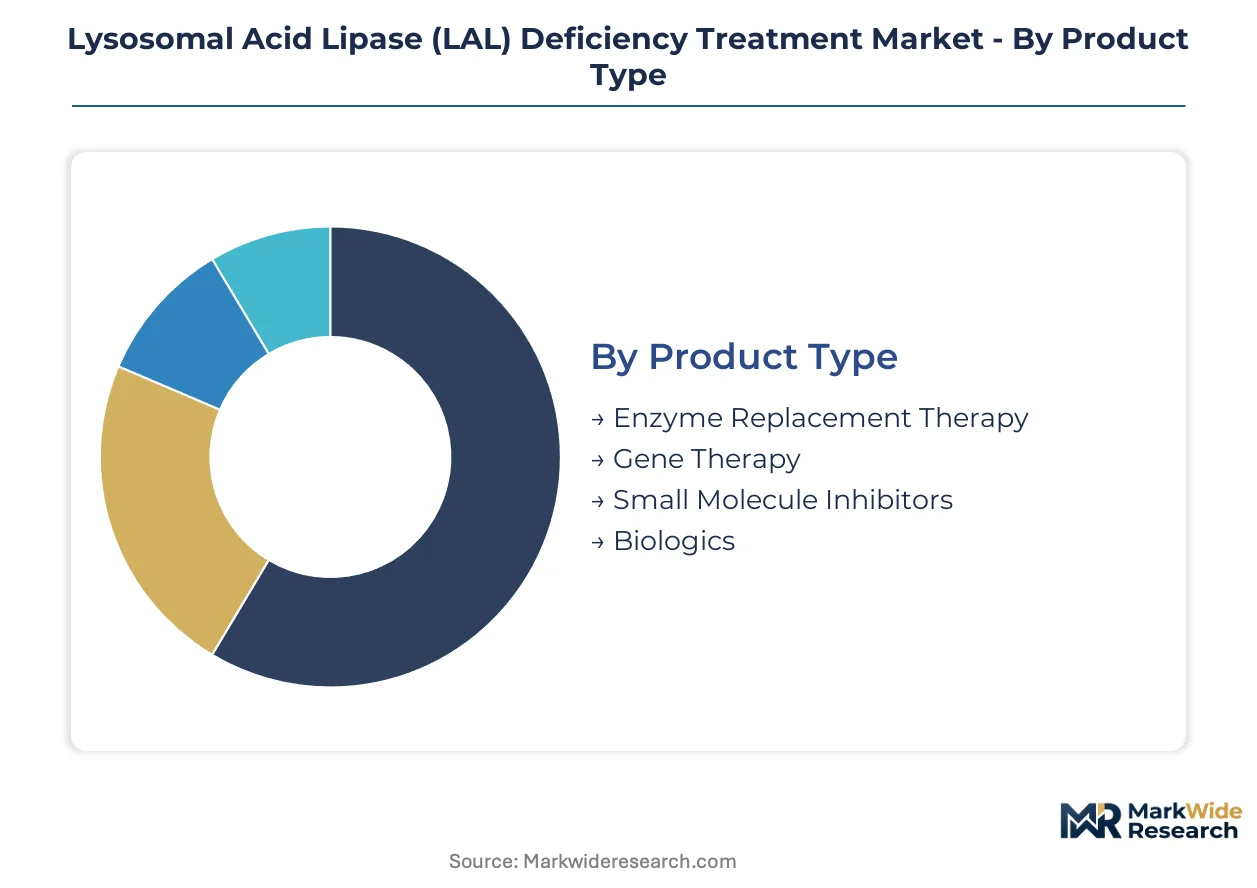
Segmentation in the LAL deficiency treatment market reveals how therapeutic modality, administration route, and care setting interact to determine patient access, reimbursement complexity, and manufacturer margin structure. Each dimension carries distinct regulatory and operational implications that shape competitive positioning across the value chain.
Product Type:
Cycle times vary dramatically across modalities, with enzyme replacement therapy turning over on established biweekly schedules while gene therapy moves toward one-time administration paradigms.
- Enzyme Replacement Therapy:Recombinant human LAL enzyme administered via intravenous infusion compensates for deficient endogenous activity. Demand concentrates in pediatric hepatology clinics across the United States, Germany, and Japan where specialized metabolic centers manage Wolman disease and cholesteryl ester storage disease patients through established infusion protocols.
- Gene Therapy:Adeno-associated viral vectors deliver functional LAL gene constructs to hepatocytes for durable enzyme expression. Development investment clusters around candidates advancing through FDA orphan drug and EMA priority medicines pathways, with manufacturing scale-up representing the primary constraint to commercial readiness.
- Small Molecule Inhibitors:Oral compounds targeting alternative metabolic pathways in lysosomal function.
- Biologics:Adjunctive protein-based interventions supporting primary enzyme restoration approaches.
Enzyme replacement therapy anchors the volume base while gene therapy gains share at the steepest rate.
Delivery Mode:
Cost tier stratification separates hospital-based infusion from emerging home administration possibilities, with route selection directly impacting cold-chain logistics burden and nursing resource allocation.
- Intravenous:Biweekly hospital-based enzyme infusions dominate current practice with established safety monitoring protocols. Patient concentration in academic medical centers with metabolic disease expertise creates geographic access disparities that compress treatment adherence in rural catchment areas.
- Subcutaneous:Investigational formulations aim to shift administration from infusion centers to home health settings, reducing facility overhead and travel burden for patients with mobility limitations.
- Oral:Small molecule candidates targeting absorption and processing pathways.
- Topical:Localized delivery approaches for specific symptom management applications.
Intravenous delivery retains the installed base while subcutaneous development targets the largest adherence improvement opportunity.
End User:
Customer type determines procurement complexity, with institutional purchasers negotiating outcome-based contracts while retail channels manage patient cost-sharing programs.
- Hospitals:Tertiary care centers with dedicated metabolic and hepatology units coordinate multidisciplinary management of LAL deficiency complications. Reimbursement expertise in these settings streamlines prior authorization for high-cost biologic therapies.
- Clinics:Outpatient facilities with pediatric subspecialty focus handle stable patients on maintenance enzyme replacement schedules.
- Specialty Pharmacies:Hub services manage cold-chain distribution and patient adherence monitoring for home infusion candidates.
- Home Healthcare:Nursing services support subcutaneous administration development and patient training programs.
Hospitals command the highest per-patient revenue while specialty pharmacies expand fastest as site-of-care migration accelerates.
Treatment Stage:
Maturity differentiation separates acute intervention from chronic management, with diagnostic latency representing the largest unmet need across the patient journey.
- Diagnosis:Newborn screening expansion and next-generation sequencing integration are compressing time to definitive LAL deficiency identification. State-level metabolic panel additions in the United States are identifying presymptomatic patients before organ damage progression limits therapeutic benefit.
- Active Treatment:Intensive enzyme replacement initiation and monitoring protocols for newly diagnosed patients with established organ involvement.
- Long-term Management:Maintenance therapy optimization and cardiovascular risk modification for stabilized patients.
- Palliative Care:Symptom-focused interventions for advanced disease with limited reversibility.
Active treatment generates the largest current revenue pool while diagnosis represents the fastest-climbing segment as screening penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for recombinant enzyme concentrates in the United States and Germany shapes cross-border supply security calculations. Japan maintains near-complete reliance on imported biologics for rare disease treatment. Export-oriented manufacturing clusters in Switzerland and Ireland supply active pharmaceutical ingredients to metabolic centers worldwide.
United States
Pediatric hepatology networks at Boston Children's Hospital and Children's Hospital of Philadelphia anchor patient identification capacity. FDA orphan drug exclusivity provisions grant seven-year market protection to enzyme replacement therapies. Newborn screening expansion across state-level metabolic panels is compressing diagnostic latency for Wolman disease.
Germany
Specialized metabolic centers in Munich and Heidelberg concentrate reimbursement expertise for high-cost biologic therapies. EMA priority medicines designation streamlines assessment pathways for disease-modifying interventions. The country's statutory health insurance funds negotiate outcome-based contracts for cardiovascular endpoint data.
Japan
PMDA sakigake designation offers early conditional approval pathways that reduce time-to-market for gene therapy candidates. Tokyo and Osaka academic medical centers coordinate multidisciplinary management of cholesteryl ester storage disease. The national health insurance system maintains separate reimbursement tracks for designated orphan drugs.
United Kingdom
NHS England's specialized commissioning framework routes LAL deficiency patients through designated supraregional centers in London and Manchester. NICE technology appraisals require long-term cardiovascular outcome evidence for maintenance therapy authorization. Genomics England's rare disease program is integrating next-generation sequencing into diagnostic pathways.
Switzerland
Swissmedic maintains accelerated authorization procedures for therapies addressing life-threatening lysosomal storage disorders. Basel and Zurich host contract manufacturing organizations supplying recombinant protein production to European markets. The country's compulsory health insurance system caps patient cost-sharing for orphan drugs at manageable thresholds.
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in enzyme production and viral vector manufacturing. The vendor base separates into three distinct layers: multinational biopharmaceutical conglomerates with rare disease infrastructure, mid-cap gene therapy developers advancing AAV platforms, and specialized contract manufacturing organizations with biologics expertise. Competitive positioning hinges on manufacturing scale security, regulatory pathway navigation, and patient identification network penetration. M&A activity concentrates on gene therapy manufacturing capacity acquisition; strategic partnerships link diagnostic platforms to therapy developers.
Among rare disease-focused biopharmaceutical developers, Alexion Pharmaceuticals, AstraZeneca, and Pfizer Inc. occupy positions across the value chain. Alexion exemplifies the established rare disease infrastructure archetype with metabolic center relationships. AstraZeneca represents the integrated diagnostics-to-therapy platform model. Pfizer sits within the manufacturing scale security tier with global biologic supply networks.
| Leading Market Players |
|---|
| Alexion Pharmaceuticals |
| AstraZeneca |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd |
| Amgen Inc. |
| BioCrick BioTech |
| Regeneron Pharmaceuticals, Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
Trans-Atlantic cold-chain corridors linking Swiss and Irish biologics manufacturing hubs to United States metabolic centers concentrate cost dynamics that amplify price differentiation between hospital-based infusion networks and emerging home health alternatives. EU F-Gas Regulation compliance layers add refrigerant containment expenses that compound with single-source enzyme production concentration to sustain premium pricing for intravenous delivery infrastructure.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through outcome-based contracts that tie reimbursement to cardiovascular endpoint achievement. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with bundled care protocols from community hospitals with limited metabolic expertise and rural clinics facing geographic access penalties. Pricing pressure stems from gene therapy pipeline advancement threatening enzyme replacement market share. Pediatric hepatology clinics demonstrate lowest price sensitivity due to specialized reimbursement pathways, while general hospitals with sporadic LAL deficiency caseloads resist premium tier commitments.
Supply Chain Analysis
Contract manufacturing organizations in Basel and Zurich hold recombinant protein production capacity for European and North American markets. Active pharmaceutical ingredient sourcing concentrates in Switzerland, Ireland, and the United States, with viral vector production for gene therapy candidates drawing from emerging capabilities in Massachusetts and North Carolina. Single-source manufacturing concentration for recombinant human LAL enzyme creates vulnerability to batch contamination or facility shutdown. Distribution runs through specialty pharmacy hubs with cold-chain monitoring before final mile delivery to hospital infusion centers or patient homes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy pipeline maturation signals early-cycle expansion as one-time curative modalities displace chronic enzyme replacement paradigms. Neonatal screening expansion across United States state metabolic panels accelerates presymptomatic patient identification before organ damage progression.
For Market Incumbents: Entrench manufacturing scale security through captive viral vector production capacity in Switzerland or Ireland to offset gene therapy supply bottlenecks. Secure pediatric hepatology clinic network exclusivity via integrated diagnostics partnerships that preempt patient identification by emerging competitors. Vertical integration into next-generation sequencing platforms defends against diagnostic service unbundling fragmentation.
For New Entrants and Emerging Players: Pursue subcutaneous formulation development targeting home health administration white space where hospital infusion burden creates adherence friction. Target Japan's PMDA sakigake pathway for accelerated conditional approval of hepatocyte-targeting AAV platforms. Leverage direct-to-consumer genetic testing partnerships for patient identification before academic medical centers establish care relationships.
For Investors and Strategic Acquirers: Mid-cap gene therapy developers with validated AAV hepatocyte transduction efficiency represent acquisition targets before manufacturing scale-up constraints resolve. Long-term viability hinges on cardiovascular outcome data generation that satisfies German and French health technology assessment bodies. Watch FDA gene therapy reimbursement framework evolution as inflection signal for commercial readiness timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Viral vector production capacity expansion in Basel addresses gene therapy supply bottlenecks for late-stage clinical trials. |
| Regulatory Approval Pathway | PMDA sakigake designation reduces time-to-market for innovative rare disease treatments in Japan's national health insurance system. |
| Strategic Partnership | Diagnostic platform alliances with next-generation sequencing providers compress patient identification latency before organ damage. |
| Pipeline Diversification | Subcutaneous delivery formulation development shifts treatment site from infusion centers to home health settings. |
| Reimbursement Strategy | Outcome-based contracts with German statutory health insurance funds satisfy cardiovascular endpoint data requirements. |
Study Parameters
Desk research of FDA orphan drug filings, EMA priority medicines designations, ClinicalTrials.gov entries, and Japanese PMDA sakigake approvals preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from formulary databases, hospital procurement records, and specialized metabolic center annual reports. Bottom-up patient volume estimates triangulated with top-down market size calculations across treatment modality and administration route segments.
Assumptions held fixed include continued FDA orphan drug exclusivity provisions, stable EMA accelerated assessment pathways, and persistent cold-chain logistics requirements for biologics distribution. Segmentation modeling incorporated therapeutic modality, delivery mode, end-user facility type, and treatment stage dimensions across the projection horizon. CAGRs derived from patient population growth, screening penetration rates, and therapy adoption curves with sensitivity testing for gene therapy launch timing and manufacturing capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in biologics reimbursement policy, gene therapy manufacturing scale-up success, or regulatory pathway timelines would shift the trajectory. Forecasts reflect these assumptions with acknowledgment that viral vector production bottlenecks or cardiovascular outcome trial failures could substantially revise projections. Quarterly review of FDA gene therapy guidance documents, EMA assessment reports, and PMDA approval decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Cleft Lip Surgery Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Hyperkalemia Treatment Market