
 US and Japan Platelet Rich Plasma Market | 2026-2036
US and Japan Platelet Rich Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
US and Japan Platelet Rich Plasma Market Insights
Orthopedic application demand is hardening across both countries as sports medicine clinics replace corticosteroid protocols with autologous PRP injections. Zimmer Biomet leverages its established orthopedic implant distribution network to push PRP kits through surgeon-owned ambulatory surgery centers. Arthrex, Inc. anchors its position via specialized centrifuge systems designed for point-of-care preparation in athletic facilities.
Platelet Rich Plasma comprises a concentrated autologous blood fraction with platelet counts typically exceeding baseline levels, prepared through gradient centrifugation to release growth factors that accelerate tissue repair. The autologous PRP segment dominates current volume due to lower immunogenic risk and established reimbursement pathways in US hospital outpatient departments. Aesthetics applications within cosmetic centers represent the fastest-expanding category as Japanese med-spas adopt PRP facial rejuvenation protocols alongside existing orthopedic demand.
FDA oversight of PRP as a minimally manipulated biological product under Section 361 HCT/P rules shapes US market access, while Japan's PMDA applies pharmaceutical-grade scrutiny to allogeneic preparations under the Act on Securing Quality. Stakeholders must monitor whether FDA enforcement discretion tightens on high-dose PRP systems or whether Japan's regenerative medicine safety framework accelerates conditional approvals for expanded indications.
Market Dynamics
The US and Japan Platelet Rich Plasma Market pivots on divergent regulatory philosophies toward autologous versus allogeneic preparations, with FDA enforcement discretion creating faster US commercialization timelines while PMDA pharmaceutical-grade scrutiny delays Japanese allogeneic entry but builds long-term reimbursement credibility.
Growth Catalysts
- FDA Section 361 HCT/P Framework:The FDA's minimally manipulated biological product pathway accelerates autologous PRP kit approvals, enabling orthopedic clinics to launch same-day preparation protocols without IND requirements.
- California Sports Medicine Corridor:Concentrated demand from professional athletic facilities and surgeon-owned ambulatory surgery centers in Los Angeles and San Francisco drives volume for point-of-care centrifuge systems.
- Double-spin centrifugation protocols:Advanced gradient separation techniques achieving 5-7x baseline platelet concentration are displacing single-spin methods in Tokyo's aesthetic clinic clusters.
Market Restraints
- Allogeneic preparation costs:Pathogen inactivation and donor screening requirements under Japan's PMDA Act on Securing Quality inflate per-unit manufacturing costs by 40-60% versus autologous alternatives.
- Reimbursement fragmentation:US Medicare's patchy coverage for PRP injections—limited to specific orthopedic indications in certain MAC jurisdictions—creates payment uncertainty for hospital outpatient departments.
- Platelet concentrate variability:Lack of standardized activation protocols produces inconsistent growth factor release profiles, complicating clinical evidence generation for regulatory submissions.
Strategic Opportunities
- Kansai region aesthetic expansion:Osaka and Kyoto med-spas remain underpenetrated versus Tokyo, presenting white space for PRP facial rejuvenation protocol rollouts alongside existing orthopedic demand.
- Conditional approval pathways:Japan's regenerative medicine safety framework offers accelerated market entry for expanded indications through post-marketing surveillance commitments.
- Direct-to-consumer channel emergence:Telehealth-integrated PRP preparation services are bypassing traditional clinic referrals in US metropolitan markets, compressing patient acquisition costs.
Industry Challenges
- Specialized technician training gaps:Proper centrifuge operation and aseptic handling protocols require certified personnel, creating bottlenecks for multi-site clinic rollouts.
- Clinical trial standardization delays:Absence of harmonized platelet concentration reporting standards across US and Japanese studies complicates meta-analysis and payer evidence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Japan Platelet Rich Plasma Market |
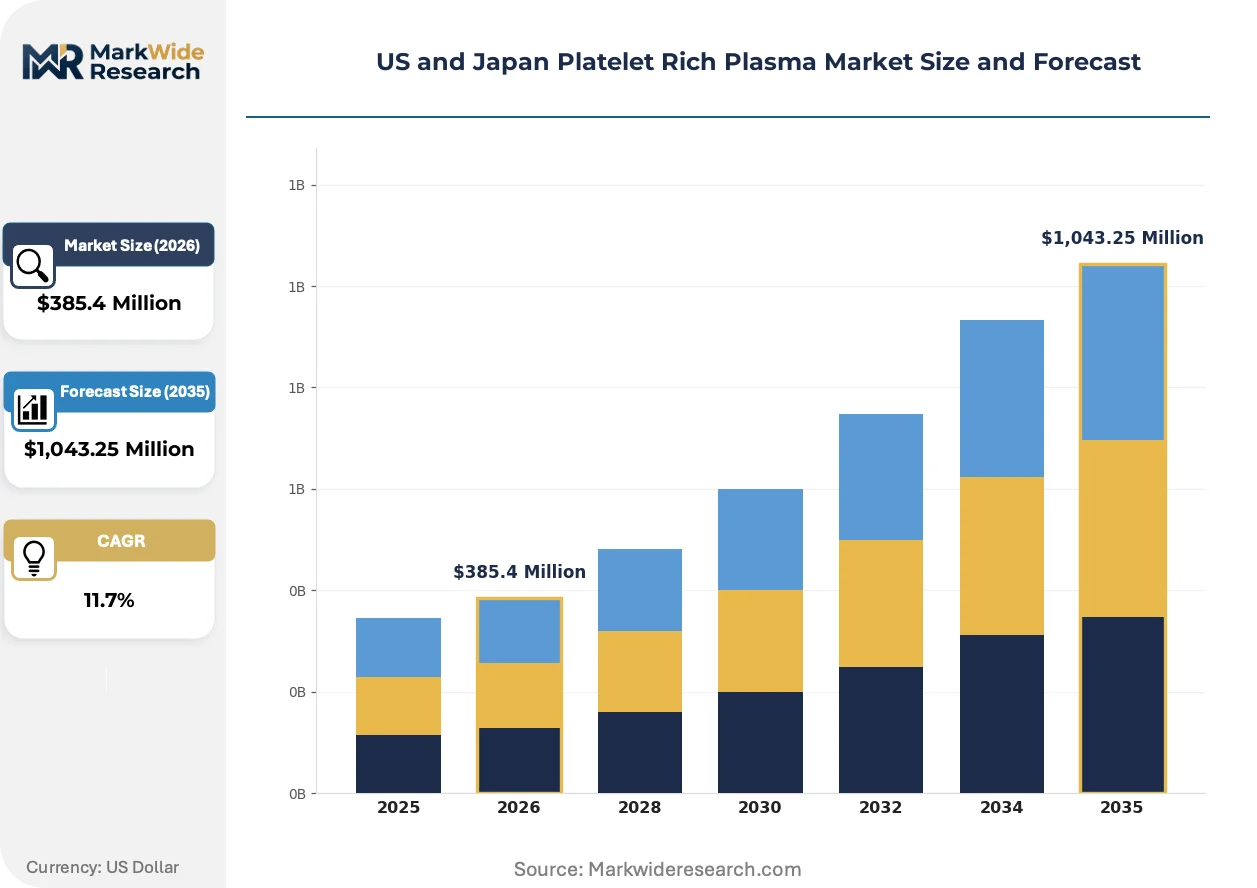
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,043.25 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous PRP, Allogeneic PRP, PRF, PRP Kits Application: Aesthetics, Orthopedics, Sports Medicine, Wound Healing End User: Hospitals, Clinics, Cosmetic Centers, Research Facilities Delivery Mode: Injections, Topical Applications, Surgical Procedures, Others |
| Companies Covered | Zimmer Biomet, Arthrex, Inc., Stryker, Johnson & Johnson Services, Inc., Terumo Corporation, EmCyte Corporation, Regen Lab SA, Apex Biologix, Juventix Regenerative Medical, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Japan Platelet Rich Plasma Market Trends and Innovations
Technological convergence between automated preparation systems and real-time quality analytics is compressing the gap between bedside preparation and laboratory-grade consistency. Regulatory frameworks on both sides of the Pacific are simultaneously tightening safety surveillance and opening conditional approval pathways.
Leukocyte-poor PRP formulations are electrifying orthopedic applications by reducing post-injection inflammation responses. Sports medicine clinics in Texas and Florida are adopting these protocols for tendon and ligament repairs. The shift is compressing recovery timelines and displacing traditional corticosteroid injection volumes in surgeon-owned facilities.
PMDA's 2023 guidance on regenerative medicine products is tightening documentation requirements for allogeneic platelet derivatives while streamlining autologous pathway clarity. Japanese manufacturers are responding by bifurcating product portfolios—pursuing pharmaceutical licenses for allogeneic lines while accelerating 361-equivalent autologous kit distribution. The aesthetic segment faces the steepest compliance burden from enhanced stability testing mandates.
Patient self-referral patterns are fragmenting traditional physician-channel dominance in US metropolitan markets. Direct-to-consumer marketing from standalone PRP clinics in Miami and San Diego is capturing cosmetic and hair restoration volumes previously routed through dermatology practices. The disintermediation is most pronounced in elective applications where out-of-pocket payment already predominates.
US and Japan Platelet Rich Plasma Market Segmentation
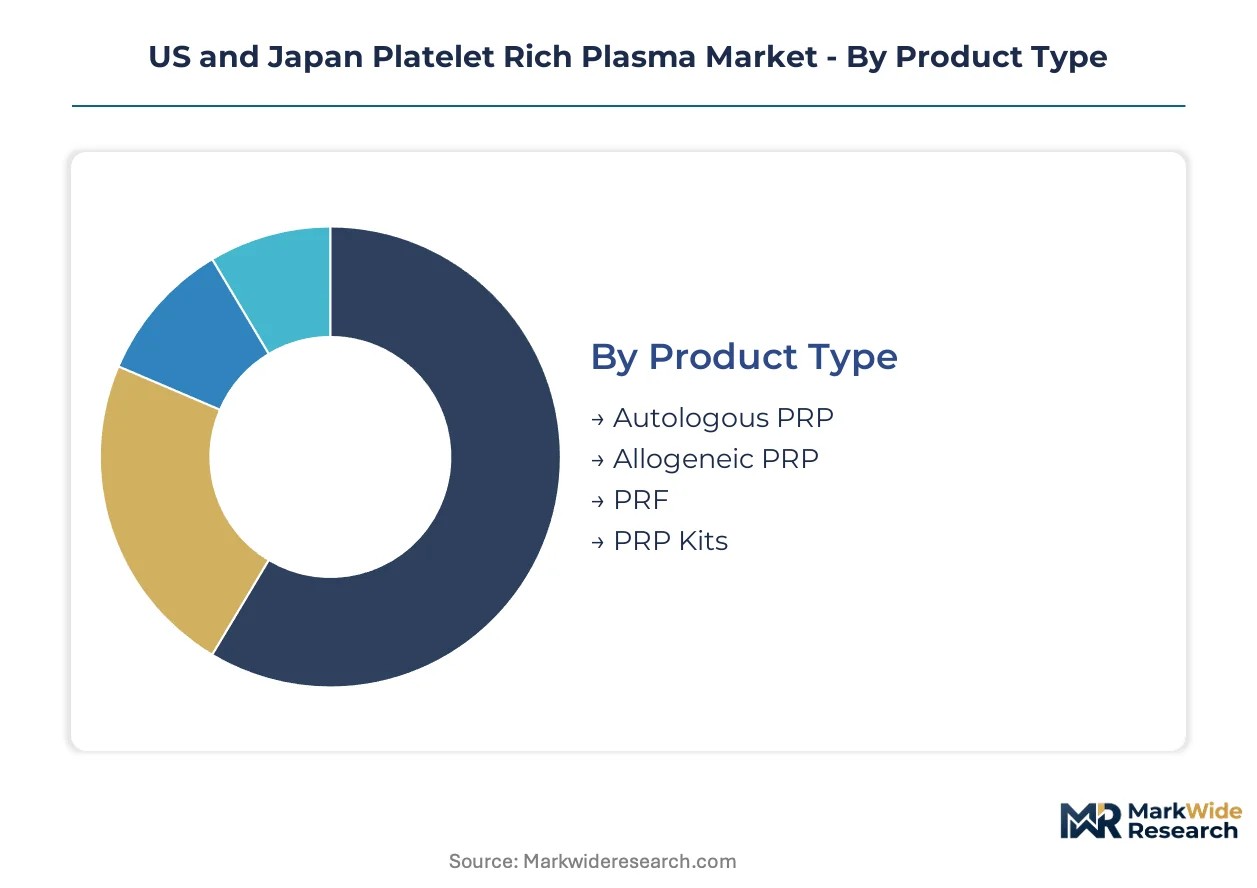
PRP market segmentation reveals divergent commercial trajectories across preparation methodologies and clinical settings. Understanding volume concentration versus premium pricing dynamics enables stakeholders to align manufacturing scale with reimbursement pathways in each geography.
Product Type:
Autologous preparations dominate current volume through lower immunogenic risk and streamlined regulatory access, while allogeneic variants command premium pricing in concentrated urban markets.
- Autologous PRP:Patient-derived blood fraction processed through gradient centrifugation achieves 5-7x baseline platelet concentration. California sports medicine corridors and Tokyo orthopedic clusters drive procurement volume through same-day preparation protocols.
- Allogeneic PRP:Donor-sourced platelet concentrates require pathogen inactivation and extended screening under PMDA pharmaceutical-grade scrutiny. Osaka aesthetic clinics absorb elevated per-unit costs for standardized, off-the-shelf availability.
- PRF:Fibrin matrix formulations release growth factors over extended timelines through natural polymerization without anticoagulants.
- PRP Kits:Pre-configured collection tubes and centrifuge consumables enable point-of-care preparation in ambulatory settings.
Today's leader: Autologous PRP. Tomorrow's challenger: Allogeneic PRP.
Application:
Orthopedic and sports medicine applications anchor reimbursement credibility, while aesthetic protocols expand through out-of-pocket payment channels in metropolitan clusters.
- Aesthetics:Facial rejuvenation and hair restoration protocols command premium pricing in Japanese med-spas and Miami cosmetic centers. Double-spin centrifugation techniques are displacing single-spin methods in Tokyo's clinic clusters.
- Orthopedics:Tendon, ligament, and joint interventions replace corticosteroid protocols in surgeon-owned ambulatory surgery centers. Leukocyte-poor formulations reduce post-injection inflammation responses in Texas and Florida facilities.
- Sports Medicine:Professional athletic facilities demand rapid turnaround preparation systems for acute injury management.
- Wound Healing:Chronic ulcer management in hospital outpatient departments leverages topical and injection delivery modes.
Orthopedics holds current revenue concentration. Aesthetics climbs the fastest through direct-to-consumer channel expansion.
End User:
Facility type determines preparation complexity requirements and regulatory compliance burden across the US and Japan.
- Hospitals:Acute care settings manage complex wound cases and surgical adjunct applications with centralized laboratory preparation.
- Clinics:Orthopedic and sports medicine practices in Los Angeles and San Francisco deploy point-of-care centrifuge systems for same-day patient turnaround.
- Cosmetic Centers:Standalone med-spas in Osaka and Kyoto bypass traditional dermatology referrals through direct-to-consumer marketing.
- Research Facilities:Academic medical centers generate clinical evidence for expanded indications under conditional approval frameworks.
Clinics capture procedure volume leadership. Cosmetic centers present the steepest expansion trajectory.
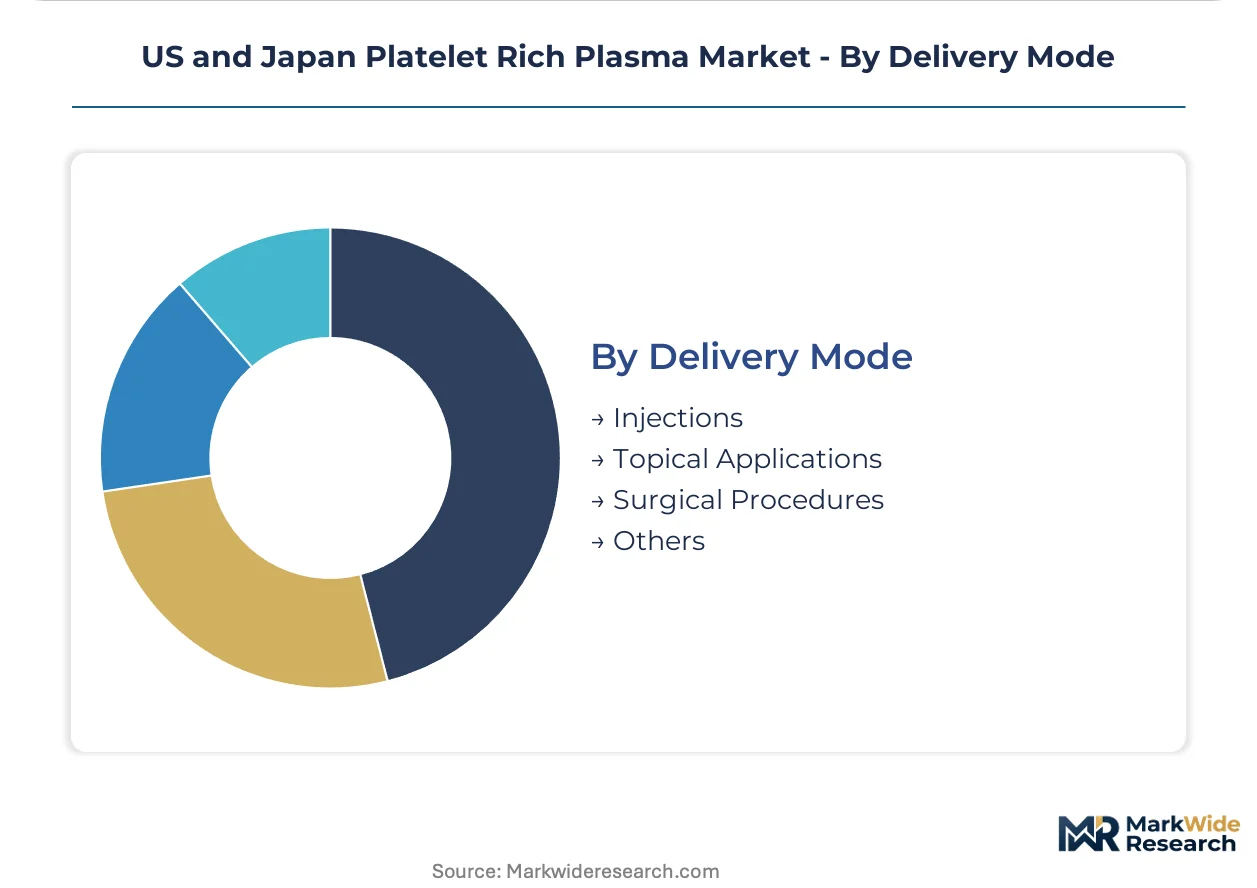
Delivery Mode:
Route of administration shapes product formulation requirements and reimbursement coding complexity in each market.
- Injections:Intra-articular and peri-tendinous delivery dominates orthopedic and sports medicine protocols with established physician reimbursement.
- Topical Applications:Microneedling combination therapies drive cosmetic center adoption in Japanese urban markets.
- Surgical Procedures:Intraoperative adjunct use in orthopedic implantation supports hardware integration.
- Others:Emerging delivery innovations include hydrogel carriers and scaffold-integrated formulations.
Injections maintain procedural dominance. Topical applications gain share fastest through aesthetic protocol diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate autologous PRP preparation in US ambulatory settings while Japan's pharmaceutical-grade compliance costs push allogeneic production toward centralized manufacturing. This divergence shapes facility investment patterns across both markets.
California
Los Angeles and San Francisco surgeon-owned ambulatory surgery centers drive demand for point-of-care centrifuge systems. FDA Section 361 HCT/P enforcement discretion enables same-day preparation protocols without IND requirements. The San Diego-Tijuana corridor experiments with cross-border patient flows for aesthetic applications.
Texas
Houston orthopedic clusters adopt leukocyte-poor PRP formulations for tendon repair protocols. Texas Medical Center institutions generate clinical evidence for expanded indications. Dallas-Fort Worth sports medicine practices compress patient turnaround through automated preparation systems.
Tokyo Metropolitan Area
Shibuya and Ginza aesthetic clinic clusters deploy double-spin centrifugation for facial rejuvenation protocols. PMDA Act on Securing Quality standards streamline autologous pathway clarity while tightening allogeneic documentation. Academic medical centers in Bunkyo Ward conduct post-marketing surveillance under conditional approval frameworks.
Kansai Region
Osaka med-spas absorb elevated per-unit costs for standardized allogeneic preparations. Kyoto cosmetic centers remain underpenetrated versus Tokyo, presenting white space for protocol rollouts. Kobe orthopedic facilities integrate PRP with existing sports medicine infrastructure.
Florida
Miami standalone PRP clinics capture cosmetic and hair restoration volumes through direct-to-consumer marketing. Tampa sports medicine corridors displace corticosteroid protocols with autologous injections. Jacksonville hospital outpatient departments navigate Medicare's patchy coverage for specific orthopedic indications.
US and Japan Platelet Rich Plasma Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with orthopedic implant distributors leveraging existing surgeon relationships while standalone kit suppliers penetrate aesthetic channels. The vendor base concentrates around three strategic archetypes: diversified orthopedic conglomerates with captive PRP lines, specialized regenerative medicine pure-plays, and contract manufacturers serving private-label aesthetic brands. Competitive moves center on M&A to capture ambulatory surgery center networks and technology licensing to compress preparation time.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker occupy positions anchoring the premium tier through established implant distribution infrastructure. Arthrex, Inc. exemplifies the specialized pure-play archetype with dedicated centrifuge systems. Terumo Corporation represents Japanese manufacturing scale with regulatory expertise spanning both FDA and PMDA pathways.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Arthrex, Inc. |
| Stryker |
| Johnson & Johnson Services, Inc. |
| Terumo Corporation |
| EmCyte Corporation |
| Regen Lab SA |
| Apex Biologix |
| Juventix Regenerative Medical, LLC |
| Others |
Pricing and Supply Chain Analysis
Medical-grade sodium citrate anticoagulant pricing volatility cascades through PRP kit manufacturing into three distinct procurement tiers: premium allogeneic preparations for Japanese aesthetic clinics, standard autologous systems for US orthopedic networks, and economy point-of-care consumables for high-volume ambulatory surgery centers.
Pricing Analysis
Distributor margin compression in the 15-25% range separates premium allogeneic kits from standard autologous alternatives. Price differentiation rests on PMDA pharmaceutical-grade certification versus FDA Section 361 HCT/P pathway access. Cost compression in the economy tier intensifies because high-volume California sports medicine corridors negotiate consolidated procurement contracts. Cosmetic center buyers exhibit highest price sensitivity due to direct-to-consumer payment models, while hospital outpatient departments absorb premium pricing through established reimbursement codes.
Supply Chain Analysis
Regional distribution centers in Osaka and Los Angeles anchor hub-and-spoke patterns for temperature-sensitive platelet concentrate logistics. Manufacturing concentration centers on Japan for precision centrifuge systems and the US for disposable collection tube assembly. Raw material dependencies include medical-grade glassware, anticoagulant formulations, and sterile packaging films. Single-source vulnerability in specialized rotor manufacturing creates bottleneck exposure. Distribution runs through orthopedic implant distributors for hospital channels and direct-to-clinic shipments for standalone aesthetic facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on leukocyte-poor formulation premiums displacing commodity PRP kits, while automated preparation systems compress labor costs across high-volume clinic networks.
For Market Incumbents: Acquire ambulatory surgery center network contracts to lock in centrifuge system placement against emerging kit-only competitors. Consolidate position through backward integration into anticoagulant formulation production, securing supply continuity amid pharmaceutical input volatility. Certification investment in PMDA pharmaceutical-grade pathways builds reimbursement credibility for allogeneic line expansion. For New Entrants and Emerging Players: Capture Kansai region aesthetic clinic white space before Tokyo-style double-spin protocols saturate Osaka and Kyoto markets. The most penetrable segment is direct-to-consumer cosmetic centers bypassing traditional dermatology referrals through telehealth-integrated preparation services. Go-to-market execution should anchor on certified technician training programs that resolve multi-site rollout bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized regenerative medicine pure-plays possessing dual FDA-PMDA regulatory expertise. Long-term viability over the five-to-ten year horizon favors manufacturers with conditional approval track records under Japan's regenerative medicine safety framework. Monitor FDA enforcement discretion tightening on high-dose PRP systems as the key inflection signal for portfolio rebalancing toward allogeneic preparation technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | CMS Medicare coverage expansion for specific orthopedic indications secures hospital outpatient department volume. |
| Hospital System Partnership | Texas Medical Center alliances generate clinical evidence for expanded tendon repair protocols. |
| Regulatory Dual-Track Investment | Simultaneous FDA Section 361 and PMDA pharmaceutical-grade filings accelerate geographic diversification. |
| Software Companion Development | Real-time platelet concentration analytics differentiate premium centrifuge systems from commodity alternatives. |
| CE Marking Pathway | European regulatory access creates hedge against US reimbursement fragmentation and Japanese compliance cost inflation. |
Research Methodology
Multiple input streams — orthopedic surgeon interviews, aesthetic clinic operator surveys, and regulatory affairs consultations — were reconciled against FDA 510(k) filings, PMDA approval databases, and hospital procurement contract records. Secondary validation drew from CMS Medicare reimbursement data, Japanese Ministry of Health reimbursement schedules, and trade customs documentation for centrifuge system imports. Bottom-up procedure volume estimates and top-down market size triangulation were cross-referenced for convergence.
Historical adoption curves for autologous biologic therapies were cross-referenced against panel input from sports medicine procurement directors and GPO contract managers. Segmentation modeling spanned preparation methodology, application indication, end-user facility type, and geographic regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to early-adopter penetration data. Forecast inputs included conditional approval pathway utilization rates and direct-to-consumer channel expansion velocity.
Regulatory enforcement discretion shifts, reimbursement policy revisions, and platelet concentrate standardization breakthroughs are the dominant revision risks to modeled projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Nose Reconstruction Market