
 Beta Thalassemia Treatment Market | 2026-2036
Beta Thalassemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Thalassemia Treatment Market Outlook
Modular gene therapy administration protocols are rebalancing how hospitals configure treatment pathways for beta thalassemia patients. bluebird bio leverages its lentiviral vector manufacturing scale to anchor supply security for gene therapy delivery. Vertex Pharmaceuticals competes through CRISPR-based editing platforms that differentiate its approach from viral vector alternatives. Novartis sustains broad hematology infrastructure that extends its reach across transfusion-dependent patient segments.
Beta thalassemia treatment encompasses therapeutic interventions targeting the inherited hemoglobin disorder characterized by reduced or absent beta-globin chain synthesis, requiring lifelong management through transfusion support, iron chelation, or curative cellular therapies. The clinical objective centers on correcting anemia, preventing iron overload organ damage, and achieving transfusion independence through genetic modification of hematopoietic stem cells. Gene therapy segments command premium positioning due to manufacturing complexity and durable clinical outcomes, while blood transfusion and iron chelation therapies occupy mature, high-volume roles with established reimbursement. Bone marrow transplant remains restricted by donor availability constraints, limiting expansion despite curative potential. Intravenous and oral delivery modes dominate current practice, though subcutaneous gene therapy administration is gaining procedural traction in specialized centers.
FDA orphan drug designations and EMA priority medicines frameworks shape development timelines and market access conditions for novel beta thalassemia therapies. The EU AI Act and GDPR provisions increasingly govern real-world evidence collection and patient registry data flows that support post-market surveillance. WHO thalassemia guidelines and national rare disease strategies in Italy, Greece, and Thailand influence screening program design and treatment center certification requirements. Stakeholders must monitor how gene therapy durability data and long-term follow-up obligations will reshape pricing negotiations and value-based contracting structures across payer systems.
Market Dynamics
Gene therapy manufacturing scale is compressing clinical trial timelines and redrawing competitive boundaries between viral vector and CRISPR-based treatment platforms. Hospital systems are consolidating procurement around centers capable of administering complex cellular therapies, forcing infrastructure investments that favor integrated delivery networks over standalone hematology units.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase 3 requirements for rare disease gene therapies, enabling earlier market entry for hematopoietic stem cell modification candidates.
- Thalassemia Patient Registries:Italy's national surveillance system generates real-world evidence that supports reimbursement negotiations and post-market durability claims.
- Lentiviral Vector Manufacturing:Commercial-scale production platforms are resolving supply bottlenecks that previously constrained patient enrollment in gene therapy trials.
Market Restraints
- Donor Availability Constraints:Human leukocyte antigen matching limitations restrict allogeneic bone marrow transplant access to fewer than 30% of eligible transfusion-dependent patients.
- EMA Post-Market Surveillance:The 15-year follow-up mandate for gene therapies inflates total cost of ownership and complicates payer value assessments.
- Iron Chelator Supply Concentration:Deferasirox API production clusters in Indian and Chinese contract manufacturers, exposing formulators to import tariff volatility.
Strategic Opportunities
- Thailand Expansion:The country's Ministry of Public Health is certifying regional thalassemia centers capable of supporting gene therapy administration outside Bangkok.
- Subcutaneous Gene Delivery:Novel administration protocols are converging with outpatient clinic capabilities, reducing inpatient bed requirements.
- EU AI Act Provisions:Automated adverse event detection systems qualify for expedited regulatory review, lowering pharmacovigilance compliance costs.
Industry Challenges
- Vector Manufacturing Talent:Shortages of GMP-compliant cell culture specialists constrain batch release timelines at contract development organizations.
- Reimbursement Code Fragmentation:DRG misalignment between transfusion support and curative therapy categories complicates hospital margin calculations for integrated treatment pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Thalassemia Treatment Market |
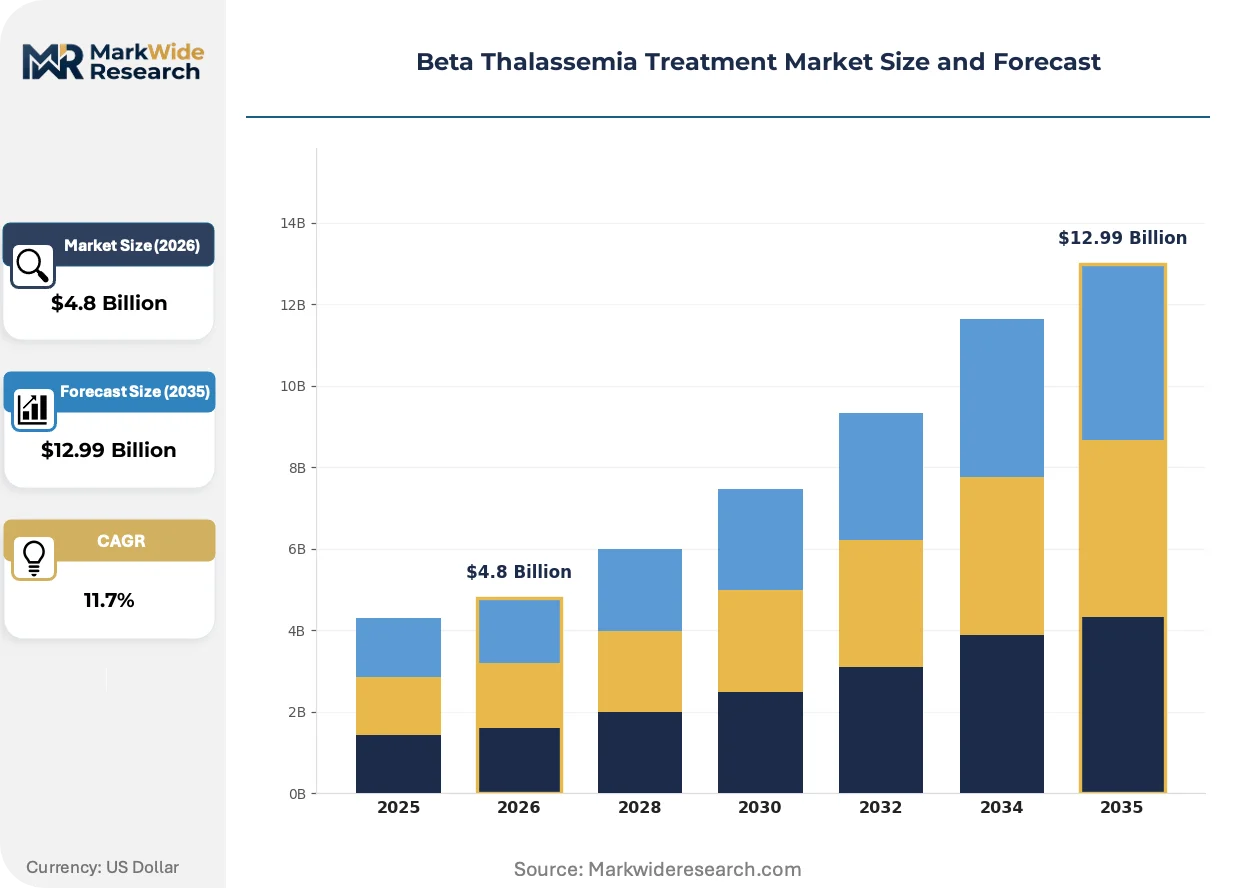
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Blood Transfusion, Iron Chelation Therapy, Bone Marrow Transplant Delivery Mode: Intravenous, Subcutaneous, Oral, Transfusion End User: Hospitals, Clinics, Laboratories, Homecare Indication: Severe Thalassemia, Moderate Thalassemia, Mild Thalassemia, Complications |
| Companies Covered | bluebird bio, Vertex Pharmaceuticals, Bristol-Myers Squibb, Novartis, Agios Pharmaceuticals, Celgene, ApoPharma, Apotex, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Thalassemia Treatment Market Strategic Shifts
Next-generation editing platforms are compressing the therapeutic window between diagnosis and curative intervention. Treatment paradigms are shifting from lifelong transfusion management toward one-time cellular modification, with manufacturing and delivery infrastructure racing to match clinical capabilities.
Base editing technology is converging with hematopoietic stem cell expansion protocols, enabling precision modification without double-strand DNA breaks. Pediatric hematology centers in Boston and Milan are piloting these platforms for adolescent patients prior to transfusion dependence onset. The approach is converging with existing apheresis infrastructure, reducing the need for dedicated gene therapy suites.
EMA's priority medicines framework is compressing assessment timelines for therapies addressing unmet transfusion-dependence needs. The regulation mandates rolling review procedures that parallel clinical development rather than sequential submission. Gene therapy developers targeting beta-globin disorders are restructuring regulatory affairs teams to maintain continuous data flow.
Specialized treatment centers are consolidating procurement authority through centralized pharmacy and therapeutics committees. Independent hematology practices in Greece and Cyprus are affiliating with hospital networks to access gene therapy administration credentials. Thailand's provincial health systems are replicating this consolidation pattern to qualify for ministry reimbursement.
Beta Thalassemia Treatment Market Segmentation
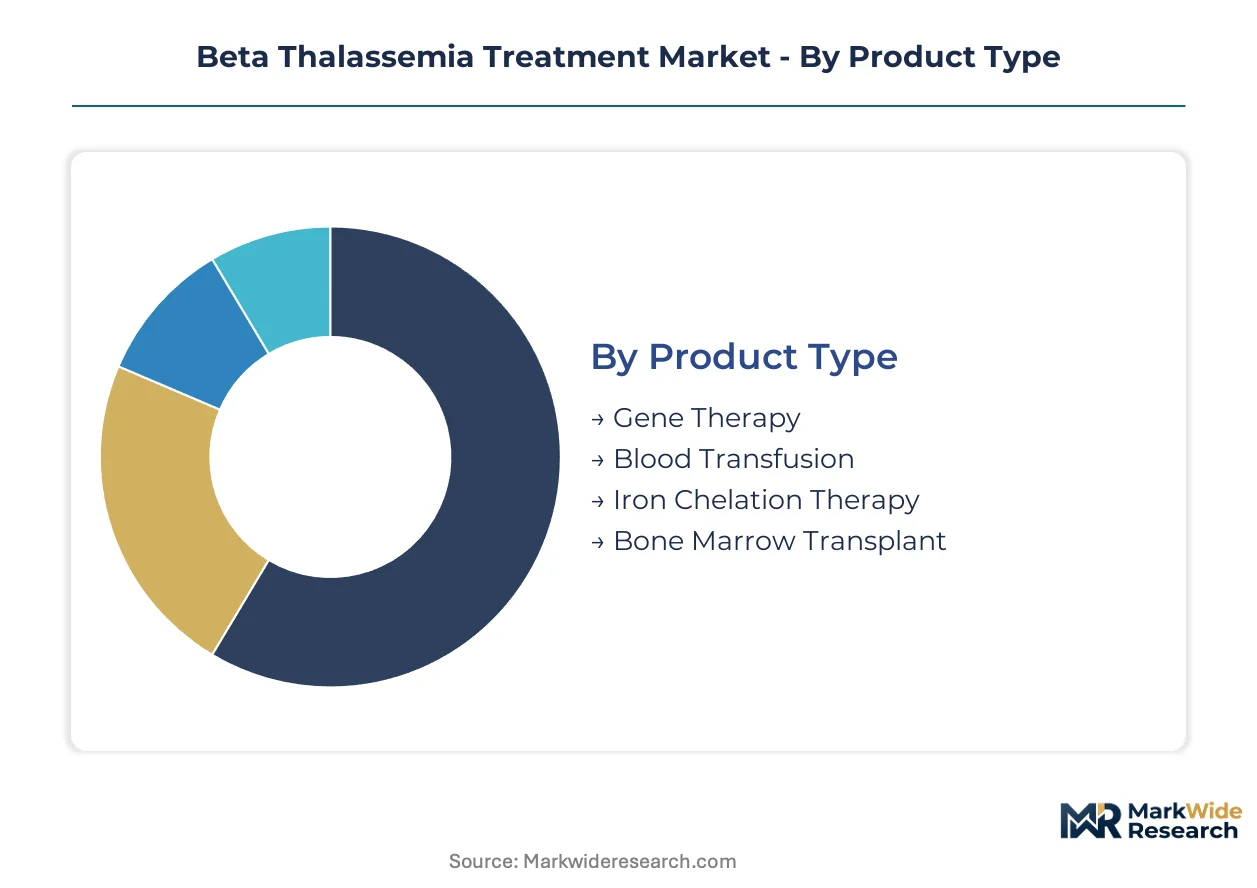
Beta thalassemia treatment pathways diverge sharply across curative versus chronic modalities, with gene therapy disrupting established transfusion-dependent economics. Segmentation clarity enables stakeholders to map manufacturing investments, reimbursement negotiations, and infrastructure requirements against specific patient trajectories.
Product Type:
Upgrade cycles from chronic management to one-time curative intervention are compressing as gene therapy durability data matures and manufacturing scale expands.
- Gene Therapy:Lentiviral vector-based and CRISPR-edited autologous stem cell products deliver transfusion independence through single administration. Demand clusters in Italy's national thalassemia centers and Thailand's emerging regional hubs where specialized apheresis and cell processing infrastructure exists. FDA accelerated approval pathways and EMA priority medicines status are shortening development-to-commercialization timelines for hematopoietic stem cell modification candidates.
- Blood Transfusion:Chronic erythrocyte replacement remains the foundation of severe thalassemia management, requiring biweekly to monthly hospital visits and iron monitoring. Volume concentrates in established Mediterranean and Southeast Asian treatment networks where screening programs identify patients early; the segment faces displacement pressure as curative alternatives demonstrate sustained efficacy.
- Iron Chelation Therapy:Deferasirox, deferoxamine, and deferiprone formulations prevent organ damage from transfusion-induced iron overload. Oral deferasirox dominates patient preference in outpatient settings.
- Bone Marrow Transplant:Allogeneic stem cell replacement offers curative potential but requires HLA-matched donors available to fewer than 30% of eligible patients. Procedure volume remains constrained by donor registry limitations and graft-versus-host disease risk profiles.
Volume placements concentrate in Blood Transfusion; the faster expansion belongs to Gene Therapy.
Delivery Mode:
Cost tier differentiation separates hospital-based cellular interventions from outpatient pharmaceutical management, with administration complexity driving site-of-care decisions.
- Intravenous:Gene therapy infusion and deferoxamine chelation require controlled inpatient environments with cardiac monitoring capability. Italy's thalassemia centers and Boston's pediatric hematology units anchor procedural volume for complex cellular therapies.
- Subcutaneous:Emerging gene therapy administration protocols and deferoxamine pump delivery enable partial outpatient migration. Thailand's Ministry of Public Health is certifying regional centers for subcutaneous cellular therapy administration outside metropolitan hospital networks.
- Oral:Deferasirox tablets and emerging small-molecule modifiers support home-based chronic management. Patient compliance and gastrointestinal tolerability shape prescribing patterns across Mediterranean and Middle Eastern markets.
- Transfusion:Erythrocyte concentrate delivery through central venous access or peripheral lines remains procedure-intensive. Cross-matching protocols and alloimmunization monitoring requirements tie volume to hospital-based blood bank infrastructure.
Transfusion and Intravenous modes absorb current volume; Subcutaneous protocols are gaining share fastest as outpatient gene therapy administration matures.
End User:
Customer type stratification reflects capability thresholds for cellular therapy administration versus chronic disease management.
- Hospitals:Integrated delivery networks with apheresis units, stem cell processing laboratories, and gene therapy suites command curative procedure volume. Consolidation in Greece and Cyprus is affiliating independent hematology practices with hospital systems to access administration credentials.
- Clinics:Outpatient transfusion centers and chelation monitoring sites manage stable chronic patients. Italy's regional thalassemia networks distribute transfusion volume across certified clinic sites with standardized iron monitoring protocols.
- Laboratories:HLA typing, vector quality control, and post-therapy chimerism analysis support treatment decisions. Centralized testing concentration in Milan and Bangkok reflects regional patient registry density.
- Homecare:Oral chelation administration and emerging subcutaneous pump therapies enable partial treatment migration. Patient education requirements and adverse event response protocols limit expansion to stabilized adult populations.
Hospital systems capture premium cellular therapy volume; Homecare is climbing the fastest as oral and subcutaneous modalities expand.
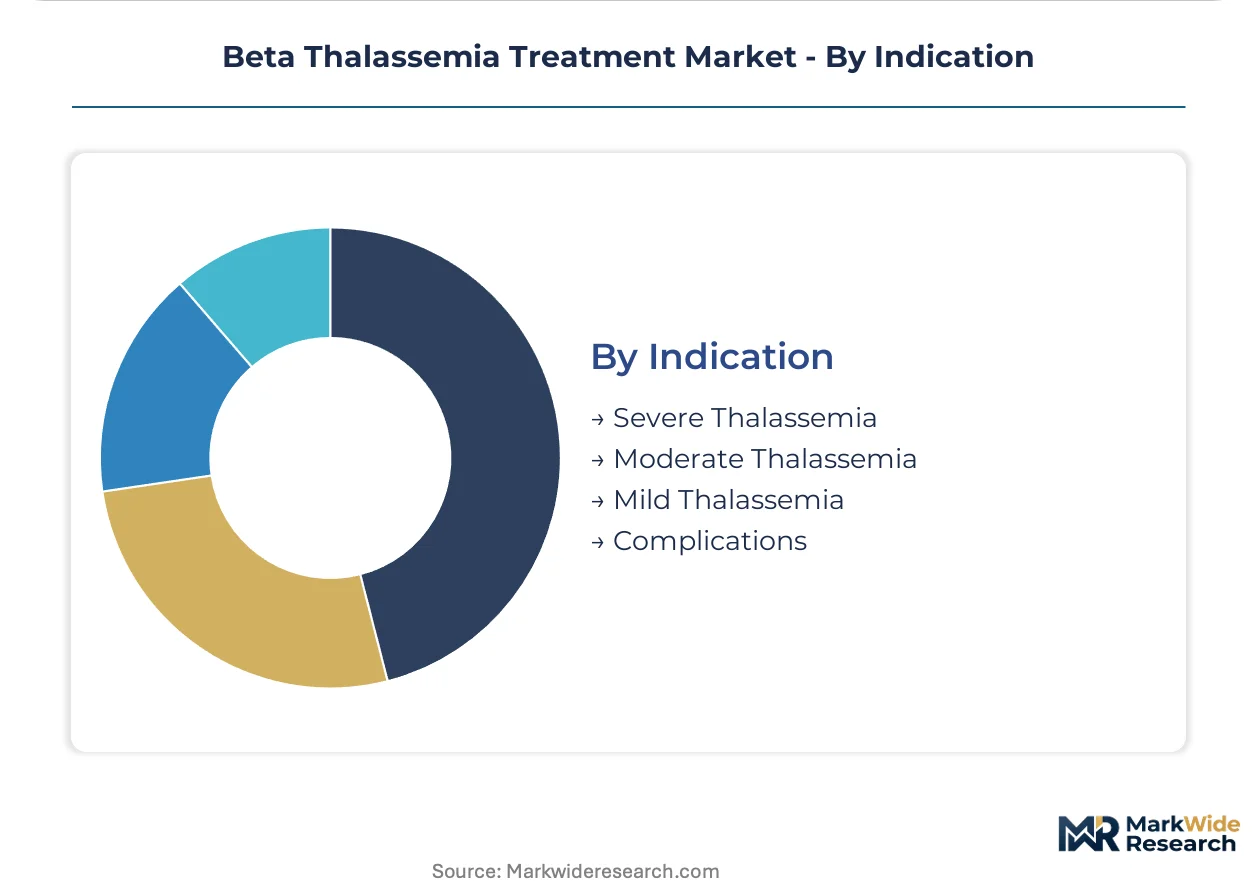
Indication:
Maturity gradients separate established transfusion-dependent populations from emerging preventive intervention targets.
- Severe Thalassemia:Transfusion-dependent patients with beta-zero or beta-plus mutations requiring lifelong management or curative intervention. Patient registries in Italy, Greece, and Thailand enable precise prevalence tracking and treatment center planning.
- Moderate Thalassemia:Intermittent transfusion needs and variable iron loading create management complexity. Timing of gene therapy intervention versus transfusion initiation is shifting as pediatric eligibility criteria expand.
- Mild Thalassemia:Asymptomatic or minimally symptomatic carriers typically require monitoring rather than active intervention. Screening program expansion in Southeast Asia is identifying this population for genetic counseling.
- Complications:Iron overload cardiomyopathy, endocrinopathy, and thrombotic events require specialized management. EMA post-market surveillance mandates for gene therapies are generating long-term durability data on complication prevention.
Volume concentrates in Severe Thalassemia; Moderate Thalassemia represents the steepest expansion trajectory as earlier intervention protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing concentrates in the United States and Switzerland, while patient treatment volume clusters in Mediterranean countries and Thailand where thalassemia prevalence drives specialized center development.
United States
FDA accelerated approval pathways compress Phase 3 timelines for hematopoietic stem cell modification candidates. The agency's orphan drug designation program provides tax incentives and market exclusivity for rare disease therapies. Boston's pediatric hematology centers anchor clinical trial enrollment and first commercial administration sites.
Italy
National thalassemia registries generate real-world evidence that supports reimbursement negotiations for curative therapies. The country's rare disease strategy mandates screening program integration with specialized treatment center certification. Milan's regional networks distribute transfusion volume while concentrating gene therapy capabilities at academic medical centers.
Thailand
Ministry of Public Health certification programs expand regional center capacity for gene therapy administration outside Bangkok. WHO thalassemia guidelines inform national screening protocols and patient registry design. Provincial health systems in northern and northeastern regions replicate consolidation patterns to qualify for ministry reimbursement.
Switzerland
Swissmedic's rolling review procedures align with EMA priority medicines frameworks for advanced therapy medicinal products. The country's central location supports vector manufacturing supply chains serving European treatment centers. Basel's pharmaceutical cluster hosts quality control and batch release operations for lentiviral production.
Greece
Independent hematology practices affiliate with hospital networks to access gene therapy administration credentials. National rare disease strategies coordinate with EU cross-border healthcare directives for patient mobility. Athens and Thessaloniki anchor specialized treatment infrastructure serving Cyprus and Balkan referral patterns.
Beta Thalassemia Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across viral vector manufacturing and CRISPR editing platforms. The market structure tiers between integrated pharmaceutical conglomerates with broad hematology portfolios and biotechnology specialists with single-disease concentration. Three archetypes dominate: viral vector scale players, gene editing technology developers, and transfusion support incumbents. Competitive moves center on manufacturing capacity expansion and strategic partnerships for apheresis network access.
Among the focused biotechnology specialists, bluebird bio and Vertex Pharmaceuticals exemplify divergent platform strategies, with the former representing lentiviral vector manufacturing scale and the latter occupying CRISPR-based editing positions. Novartis sits within the diversified conglomerate tier, leveraging established hematology infrastructure across transfusion-dependent patient segments.
| Leading Market Players |
|---|
| bluebird bio |
| Vertex Pharmaceuticals |
| Bristol-Myers Squibb |
| Novartis |
| Agios Pharmaceuticals |
| Celgene |
| ApoPharma |
| Apotex |
| Fresenius Kabi |
| Others |
Value Chain & Pricing Dynamics
Captive lentiviral vector manufacturing by bluebird bio and Vertex Pharmaceuticals anchors supply security for gene therapy delivery while supporting premium pricing for transfusion-independent outcomes. This integration choice concentrates pricing power with vector-scale players and compresses margins for blood product formulators facing commoditization pressure.
Pricing Analysis
Cost-down pressure on chronic transfusion and chelation therapies accelerates because hospital procurement committees prioritize curative cellular interventions with durable outcome guarantees. Three-tier pricing structure across gene therapy premium, transplant standard, and chronic management economy levels reflects manufacturing complexity and clinical durability differentiation. Price differentiation rests on FDA accelerated approval status and EMA priority medicines designation as certification tiers. Blood transfusion services exhibit highest price sensitivity due to DRG misalignment with curative therapy categories, while gene therapy buyers accept premium positioning for transfusion independence guarantees.
Supply Chain Analysis
Direct-to-hospital channels handle gene therapy demand through specialized apheresis networks in Italy, Thailand, and the United States. Vector manufacturing concentrates in Switzerland and the United States, while API production for deferasirox draws from Indian and Chinese contract manufacturers. Supply chain risk centers on single-source vulnerability for GMP-compliant cell culture specialists at contract development organizations. Distribution runs through integrated delivery networks consolidating procurement authority around centers with stem cell processing laboratory credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing scale constraints prop pricing power for vector-capable players while limiting patient access expansion. Hospital systems face capacity bottlenecks in GMP-compliant cell culture specialists that sustain premium positioning for qualified suppliers.
For Market Incumbents: Extend vector manufacturing capacity in Switzerland and the United States to defend against CRISPR platform displacement from emerging editing specialists. Deepen backward integration into plasmid DNA supply to reduce batch release timeline exposure from contract development organization talent shortages. Anchor hospital system partnerships through apheresis network access guarantees that lock out viral vector competitors. For New Entrants and Emerging Players: Capture subcutaneous gene therapy administration protocol development as the most penetrable white space, targeting Thailand's provincial health systems outside Bangkok for first-mover certification. Prioritize pediatric moderate thalassemia intervention timing before transfusion dependence onset as the underserved patient trajectory. Pursue go-to-market angles through affiliation with Greece's consolidating independent hematology practices seeking hospital network credentials. For Investors and Strategic Acquirers: Exit pathways concentrate in platform licensing transactions and Big Pharma hematology portfolio expansion rather than standalone IPO windows. Long-term viability hinges on durability data maturation across the 15-year EMA post-market surveillance horizon. Acquisition target archetype: CRISPR editing specialists with rolling review EMA submissions and established apheresis partnerships. Watch gene therapy chimerism failure rates as the inflection indicator for platform technology shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Resolves GMP cell culture specialist shortages constraining batch release timelines at Swiss and US vector facilities. |
| Regulatory Approval Pathway | FDA accelerated approval and EMA priority medicines status compress development-to-commercialization timelines for stem cell modification candidates. |
| Hospital System Partnership | Secures apheresis network access and gene therapy suite credentials in Italy's national thalassemia centers and Thailand's emerging regional hubs. |
| Pipeline Diversification | Base editing platforms converge with pediatric eligibility expansion to capture moderate thalassemia patients prior to transfusion dependence. |
| Licensing Agreement | Thailand's Ministry of Public Health certification programs enable regional center capacity expansion outside metropolitan Bangkok networks. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with WHO thalassemia guidelines and national patient registry data from Italy and Thailand. Primary interviews with gene therapy development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation through bottom-up patient prevalence modeling and top-down market sizing triangulation.
Historical trendline analysis across approved gene therapy pricing and transfusion center procedure volumes established baseline growth patterns. The analytical framework segmented by treatment modality, delivery mode, and patient severity indication across the projection horizon. CAGRs derived from vector manufacturing capacity expansion curves and hospital system infrastructure investment patterns, with gene therapy durability data and iron chelator API supply concentration as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA post-market surveillance mandate modifications and vector manufacturing talent pipeline development. Forecasts reflect assumptions on regulatory pathway continuity and reimbursement code consolidation. Periodic stress-testing of base assumptions is recommended against gene therapy adverse event profiles and cross-border healthcare directive harmonization shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market