
 Adenomyosis Treatment Market | 2026-2036
Adenomyosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Adenomyosis Treatment Market Analysis
Project finance and leasing arrangements for surgical equipment is narrowing the competitive field to players with strong capital partnerships. Novartis AG leverages its established oncology financing infrastructure to extend into gynecological therapeutics. Pfizer Inc. anchors its position through manufacturing scale across hormonal therapy portfolios. Bayer AG competes by controlling distribution networks in European and North American specialty channels.
Adenomyosis treatment encompasses pharmacological, surgical, and hormonal interventions targeting ectopic endometrial tissue within the myometrium, with procedures ranging from MRI-guided focused ultrasound to laparoscopic procedures preserving uterine integrity. Medications and hormonal therapy represent mature revenue pools with stable prescribing patterns, while surgery captures premium margins as minimally invasive techniques displace open hysterectomy protocols. Delivery mode segmentation shows oral formulations dominating volume, though transdermal routes are gaining traction among patients seeking adherence flexibility.
FDA oversight of gynecological devices and EPA standards for pharmaceutical manufacturing residuals shape product development timelines and facility investment requirements. EMA's Medical Device Regulation and REACH chemical compliance frameworks add parallel certification burdens for multinational portfolios. Stakeholders must monitor how evolving reimbursement criteria for conservative uterine-sparing procedures reshape provider economics and patient access pathways.
Market Dynamics
The FDA's evolving guidance on gynecological devices is compressing product development cycles while simultaneously elevating capital requirements for market entry, forcing smaller manufacturers into strategic partnerships with established players possessing robust quality management infrastructure.
Growth Catalysts
- Minimally Invasive Technique Adoption:Specialty clinics across the United States are expanding MRI-guided focused ultrasound capabilities, reducing recovery times and preserving uterine function for patients seeking fertility preservation.
- REACH Chemical Compliance Framework:European pharmaceutical manufacturers are accelerating reformulation efforts to meet residual solvent thresholds, creating competitive differentiation for compliant hormonal therapy portfolios.
- Integrated Women's Health Networks:Consolidated referral pathways in metropolitan hospital systems are standardizing conservative uterine-sparing procedures as first-line interventions.
Market Restraints
- Specialized Surgical Equipment Costs:High-intensity focused ultrasound systems and advanced laparoscopic platforms require substantial capital deployment, limiting adoption to tertiary care centers with dedicated gynecological surgery volumes.
- EMA Medical Device Regulation Certification Burden:Parallel conformity assessment procedures for multinational portfolios extend time-to-market by 18-24 months for novel interventional devices.
- Hysterectomy Substitution Threat:Open abdominal hysterectomy remains the default procedure in resource-constrained settings where advanced imaging guidance and specialized surgical training are unavailable.
Strategic Opportunities
- Transdermal Hormonal Delivery:Novel patch and gel formulations address adherence gaps in oral therapy regimens, targeting working-age patients seeking dosing flexibility without daily pill burden.
- Conservative Procedure Reimbursement Expansion:United States payers are piloting bundled payment models for uterine-sparing interventions, aligning provider economics with patient preference for fertility-preserving options.
- AI-Enhanced Diagnostic Imaging:Machine learning algorithms applied to pelvic MRI interpretation are hybridizing with conventional radiology workflows to reduce diagnostic latency and treatment initiation delays.
Industry Challenges
- Interventional Radiology Skill Pipeline:MRI-guided focused ultrasound requires cross-trained specialists combining gynecological surgical expertise with advanced imaging interpretation, creating recruitment bottlenecks at expanding treatment centers.
- Legacy Electronic Health Record Integration:Conservative adenomyosis procedures generate distinct coding and documentation requirements that conflict with established hysterectomy-centric billing workflows in hospital revenue cycle systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adenomyosis Treatment Market |
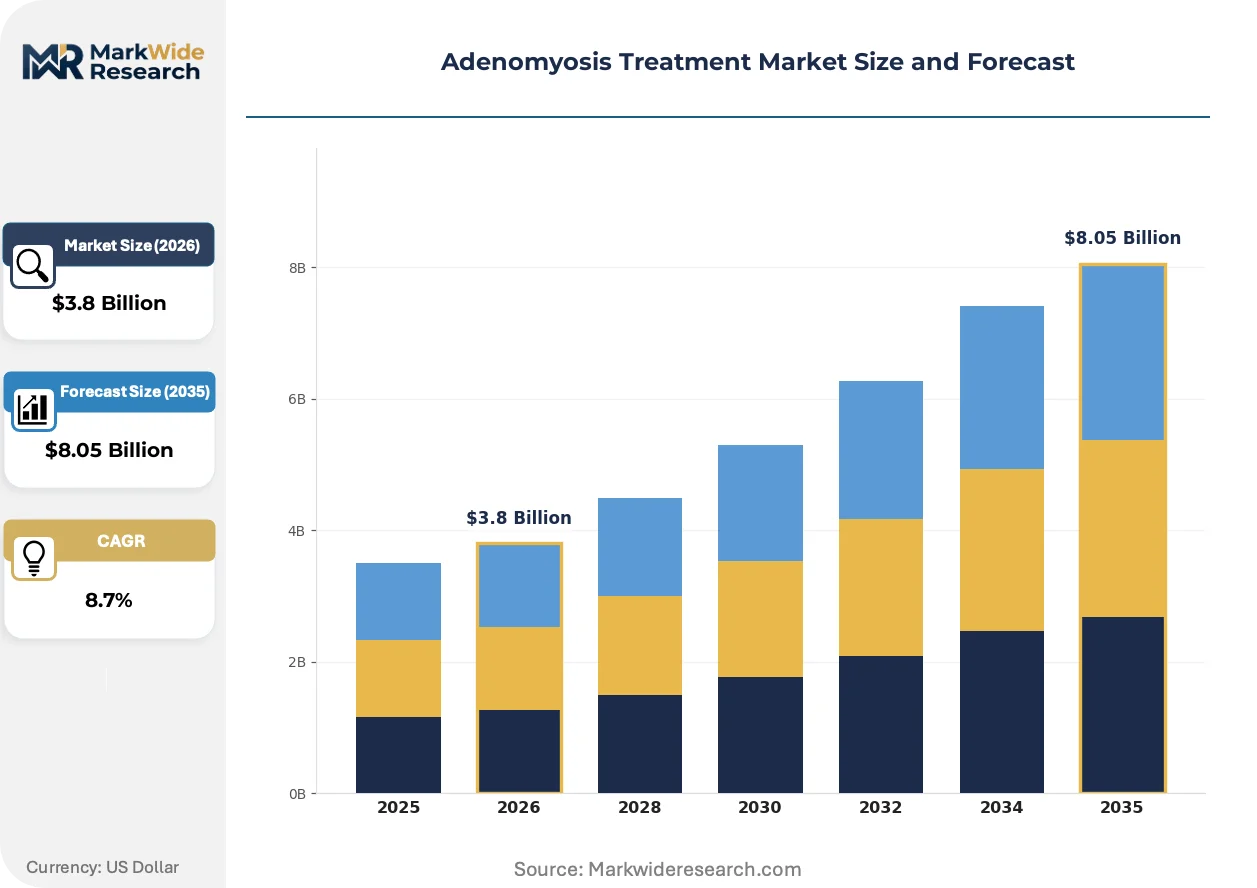
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgery, Hormonal Therapy, Lifestyle Changes Delivery Mode: Oral, Injectable, Transdermal, Surgical End User: Hospitals, Outpatient Clinics, Home Healthcare, Specialty Clinics Therapy Area: Gynecology, Pain Management, Reproductive Health, Holistic Care |
| Companies Covered | Novartis AG, Pfizer Inc., Bayer AG, AstraZeneca plc, AbbVie Inc., Ferring B.V., Merck KGaA, GlaxoSmithKline plc, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adenomyosis Treatment Market Emerging Trajectories
Adenomyosis treatment is undergoing platform-level transformation as diagnostic precision, minimally invasive technique refinement, and patient-centered delivery models converge to displace conventional hysterectomy protocols.
Magnetic resonance-guided focused ultrasound surgery is hybridizing thermal ablation precision with real-time tissue monitoring, enabling same-day discharge protocols. Academic medical centers in Boston and San Francisco are establishing dedicated adenomyosis centers of excellence, compressing the interval between symptom presentation and definitive intervention. This convergence is reshaping competitive positioning toward integrated care delivery rather than discrete device or pharmaceutical transactions.
REACH chemical compliance deadlines are forcing European contract manufacturing organizations to retrofit solvent recovery systems and validate alternative purification processes. Pharmaceutical sponsors with existing oncology manufacturing infrastructure are repurposing capacity for gynecological hormonal synthesis, capturing economies of scale unavailable to pure-play women's health developers. The regulatory friction is concentrating formulation expertise among manufacturers with diversified therapeutic portfolios.
Patients are demanding fertility-preserving alternatives with increasing specificity, disrupting the traditional hysterectomy-default referral pattern in United States gynecological practices. Direct-to-patient education platforms and advocacy organization certification programs are shifting initial consultation expectations, compelling community hospitals to invest in conservative procedure capabilities or lose referrals to specialized centers. This behavioral shift is most pronounced in coastal metropolitan markets with higher specialist density and established patient navigation infrastructure.
Adenomyosis Treatment Market Segmentation
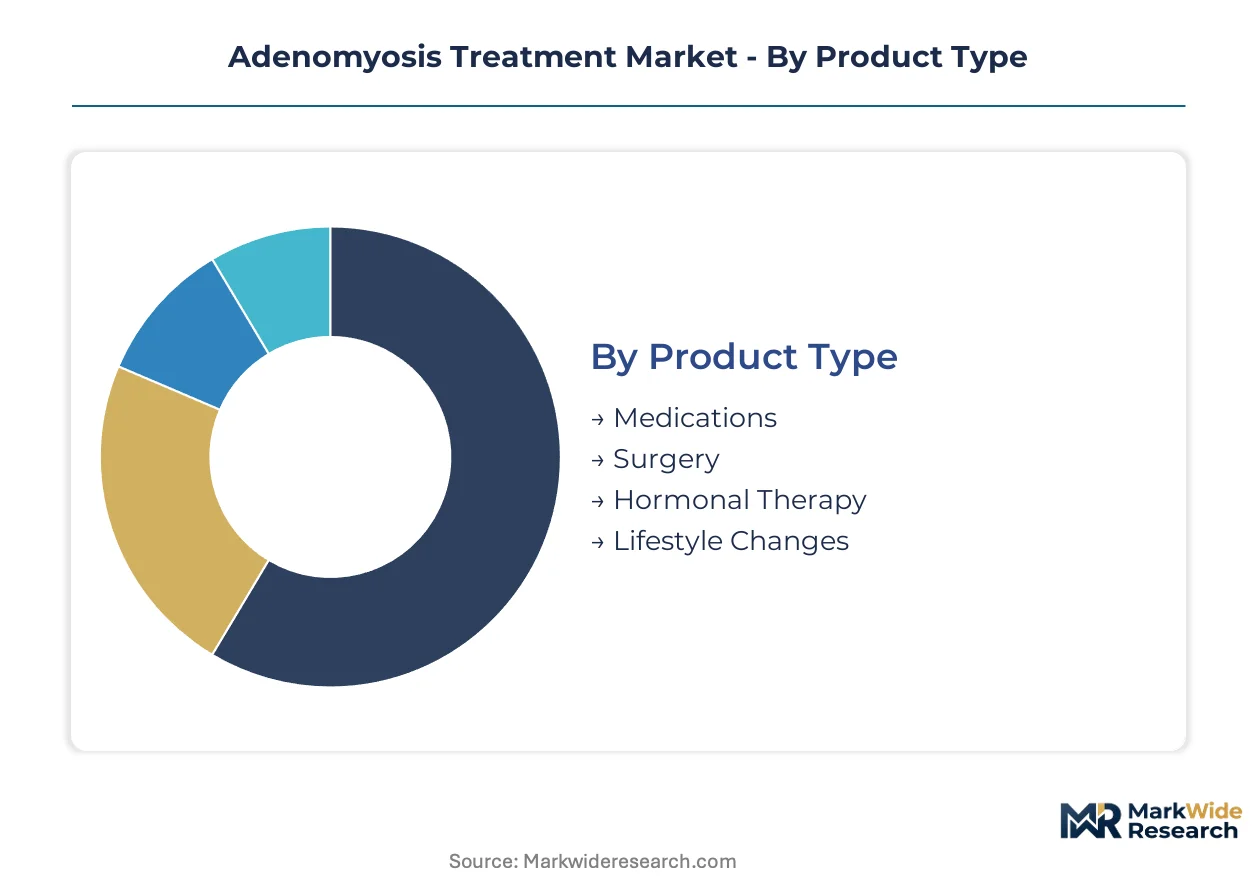
Adenomyosis treatment segmentation reveals divergent margin structures across therapeutic modalities, with minimally invasive interventions commanding premium pricing while pharmacological approaches compete on volume scale. Understanding these segment dynamics illuminates where capital deployment and R&D investment generate sustainable returns.
Product Type:
Use cases span from acute symptom management through definitive surgical resolution, with fertility preservation preferences increasingly shaping therapeutic selection.
- Medications:Non-steroidal anti-inflammatory drugs and tranexamic acid formulations address dysmenorrhea and heavy menstrual bleeding through cyclical administration protocols. Demand concentrates in community gynecology practices across the United States where patients prioritize fertility preservation, though reimbursement compression limits margin expansion for generic portfolios.
- Surgery:MRI-guided focused ultrasound and laparoscopic adenomyomectomy preserve uterine integrity while excising ectopic endometrial tissue. Academic medical centers in Boston and San Francisco are establishing dedicated centers of excellence, capturing referral volume from community hospitals lacking specialized interventional radiology infrastructure.
- Hormonal Therapy:Continuous progestin and GnRH agonist regimens induce amenorrhea and lesion regression through endocrine suppression.
- Lifestyle Changes:Dietary modification and pain management protocols serve as adjunctive interventions alongside pharmacological or surgical primary therapy.
The dominant share belongs to Hormonal Therapy, while Surgery is closing the gap fastest.
Delivery Mode:
Cost tier stratification separates high-touch surgical interventions from self-administered pharmaceutical regimens, with reimbursement design favoring outpatient administration settings.
- Oral:Tablet and capsule formulations dominate prescription volume through established manufacturing scale and pharmacy distribution networks. Integrated women's health networks in metropolitan United States markets standardize oral progestins as first-line therapy, though adherence gaps persist among working-age patients facing daily dosing burdens.
- Surgical:Same-day discharge protocols for focused ultrasound and laparoscopic procedures capture premium reimbursement under ambulatory surgery center billing codes. Tertiary care centers with dedicated gynecological surgery volumes amortize capital equipment costs across high case throughput, creating barriers for community hospital entry.
- Injectable:Depot formulations extend dosing intervals through sustained-release mechanisms.
- Transdermal:Patch and gel delivery systems address adherence flexibility demands.
Oral formulations retain volume leadership, though Surgical delivery commands the steepest expansion trajectory as minimally invasive technique adoption accelerates.
End User:
Customer type concentration reflects referral pathway consolidation, with integrated health networks directing patients toward specialized intervention sites.
- Specialty Clinics:Dedicated adenomyosis centers combine diagnostic imaging, interventional radiology, and fertility counseling under single-roof coordination. Coastal metropolitan markets with higher specialist density are seeing patient navigation infrastructure steer complex cases away from general gynecology practices.
- Hospitals:Academic medical centers anchor conservative uterine-sparing procedure development through residency training pipelines and clinical trial access. Revenue cycle systems in these institutions are adapting billing workflows to accommodate distinct coding requirements for fertility-preserving interventions.
- Outpatient Clinics:Community-based settings manage stable patients on maintenance hormonal therapy.
- Home Healthcare:Self-administered transdermal and oral regimens minimize facility utilization.
Specialty Clinics are gaining share fastest, while Hospitals retain the largest patient volume base.
Therapy Area:
Application maturity varies across clinical domains, with gynecological subspecialization advancing faster than pain management integration.
- Gynecology:Subspecialty fellowship training in minimally invasive surgery and reproductive endocrinology concentrates expertise at tertiary referral centers. FDA device guidance evolution is compressing product development cycles for uterine-sparing intervention platforms, elevating capital requirements for market entry.
- Reproductive Health:Fertility preservation counseling has become standard-of-care for adenomyosis patients of reproductive age. Patient advocacy organization certification programs and direct-to-patient education platforms are shifting initial consultation expectations toward conservative procedure options.
- Pain Management:Multimodal analgesic protocols address chronic pelvic pain symptomatology.
- Holistic Care:Integrative approaches combine conventional medical therapy with complementary interventions.
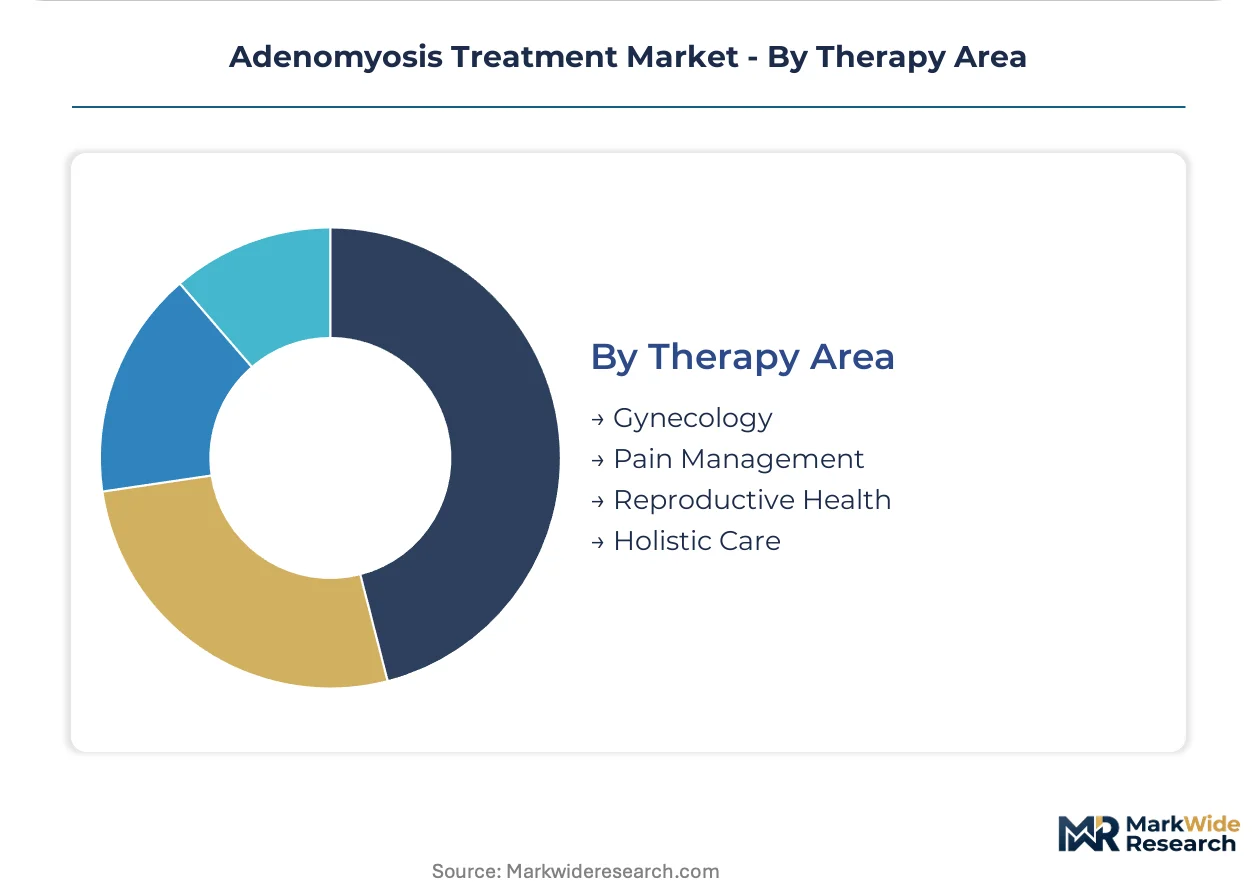
Gynecology dominates therapeutic decision-making, while Reproductive Health is expanding its influence fastest through patient-driven demand for fertility-preserving alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in gynecological therapeutics, exporting hormonal formulations to European and Asian markets while importing specialized interventional devices from German and Japanese manufacturers. Import dependence for MRI-guided focused ultrasound systems creates procurement bottlenecks at expanding treatment centers.
United States
Integrated women's health networks in metropolitan markets consolidate referral pathways toward specialized adenomyosis centers. FDA guidance evolution on gynecological devices compresses product development cycles while elevating capital requirements for market entry. Boston and San Francisco academic medical centers anchor conservative uterine-sparing procedure development through dedicated centers of excellence.
Germany
EMA Medical Device Regulation certification burdens extend time-to-market for novel interventional devices by 18-24 months. REACH chemical compliance deadlines force contract manufacturing organizations to retrofit solvent recovery systems for hormonal therapy production. The Baden-Württemberg industrial corridor concentrates pharmaceutical manufacturing infrastructure repurposable for gynecological therapeutics.
Japan
PMDA regulatory pathways for novel hormonal delivery systems maintain stringent efficacy demonstration requirements. METI industrial policy supports domestic manufacturing capacity for advanced medical devices including focused ultrasound platforms. The Kansai region around Osaka hosts specialized gynecological device clusters serving Asia-Pacific export markets.
United Kingdom
NICE reimbursement criteria for conservative uterine-sparing procedures reshape provider economics and patient access pathways. MHRA post-Brexit regulatory divergence creates parallel certification requirements for multinational pharmaceutical portfolios. London's tertiary hospital networks pilot bundled payment models for fertility-preserving interventions.
China
NMPA accelerated review pathways for innovative gynecological devices attract multinational sponsors seeking earlier market access. Domestic manufacturers in the Yangtze River Delta scale production of generic hormonal therapies for Southeast Asian export markets. Shanghai's academic medical centers establish training pipelines for MRI-guided focused ultrasound specialists.
Adenomyosis Treatment Market Vendor Landscape
On the supply side, the industry is consolidating around pharmaceutical incumbents with diversified therapeutic portfolios and specialized device manufacturers with captive imaging technology. Three archetypes dominate: multinational pharmaceutical conglomerates leveraging oncology manufacturing infrastructure, pure-play women's health developers seeking strategic partnerships, and medical device specialists integrating diagnostic and therapeutic platforms. Competitive moves concentrate on M&A for technology access and capacity expansion through contract manufacturing organization partnerships.
Among Swiss-based pharmaceutical conglomerates, Novartis AG occupies a position exemplifying the diversified-portfolio archetype. German chemical-pharmaceutical groups including Bayer AG represent the integrated supply-chain model. American multinational Pfizer Inc. anchors the scale-driven manufacturing tier.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Bayer AG |
| AstraZeneca plc |
| AbbVie Inc. |
| Ferring B.V. |
| Merck KGaA |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Single-source dependency for MRI-guided focused ultrasound systems determines both premium pricing spreads for surgical delivery and the geographic concentration of supply chain nodes. Tariff exposure on German and Japanese interventional devices widens cost tiers between tertiary academic centers and community hospitals lacking capital equipment partnerships.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations across three-tier structures separating premium device-integrated procedures from standard hormonal therapy and economy generic medications. Price differentiation stems from FDA device classification tier and geographic delivery cost to ambulatory surgery centers. Pricing pressure intensifies as integrated women's health networks consolidate volume and demand bundled discounts. Community gynecology practices exhibit highest price sensitivity due to reimbursement compression on oral progestin portfolios.
Supply Chain Analysis
Extended payment terms from specialty clinics to device manufacturers compress working capital cycles upstream. Manufacturing concentrates in Germany, Japan, and the United States for focused ultrasound platforms, while active pharmaceutical ingredients draw from Indian and Chinese contract manufacturing organizations. Supply chain risk centers on single-source vulnerability for high-intensity transducer components. Distribution runs through integrated health network procurement consortia and GPO contracts at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open abdominal hysterectomy persists as the default substitute in resource-constrained settings, forcing incumbents to demonstrate clear value differentiation for conservative uterine-sparing alternatives.
For Market Incumbents: Pre-empt hysterectomy-default referral patterns by embedding fertility preservation counseling into standard gynecology workflows. Secure backward integration into MRI-compatible device component supply to reduce import dependency exposure. Anchor market position through exclusive equipment leasing arrangements with expanding specialty clinic networks. For New Entrants and Emerging Players: Pursue transdermal hormonal delivery white space targeting working-age patients with adherence flexibility demands. Target community hospital systems in coastal metropolitan markets seeking to retain adenomyosis referrals currently leaking to academic centers. Lead with direct-to-patient education platforms that reshape initial consultation expectations. For Investors and Strategic Acquirers: FDA guidance evolution on gynecological devices reshapes the acquisition landscape toward quality management infrastructure capabilities. Long-term viability hinges on diversified therapeutic portfolios spanning pharmacological and interventional modalities. Signal to watch: bundled reimbursement pilot expansion for uterine-sparing procedures in United States commercial payers.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive supply agreements with Boston and San Francisco academic centers lock in referral volume. |
| CE Marking Pathway | EMA MDR certification accelerates European market access for novel interventional platforms. |
| Reimbursement Strategy | NICE criteria alignment in the United Kingdom reshapes provider economics for conservative procedures. |
| Software Companion Development | AI-enhanced pelvic MRI interpretation reduces diagnostic latency at expanding treatment centers. |
| Manufacturing Scale-Up | Repurposed oncology synthesis capacity captures economies of scale in hormonal therapy production. |
Methodological Framework
Operator-level perspectives from gynecological surgeons, interventional radiologists, hospital procurement managers, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital GPO contract disclosures. Bottom-up patient volume estimates and top-down pharmaceutical shipment data triangulated across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across treatment modality, delivery mode, end-user facility type, and regional regulatory cluster. CAGRs derived from procedure volume trends, pricing trajectory assumptions, and therapeutic substitution elasticity parameters. Forecast inputs incorporated REACH compliance cost pass-through and bundled payment pilot expansion rates.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting hospital capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory approval timelines and reimbursement policy evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Allergy Treatment Market