
 Parathyroid Disease Treatment Market | 2026-2036
Parathyroid Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Parathyroid Disease Treatment Market Analytics
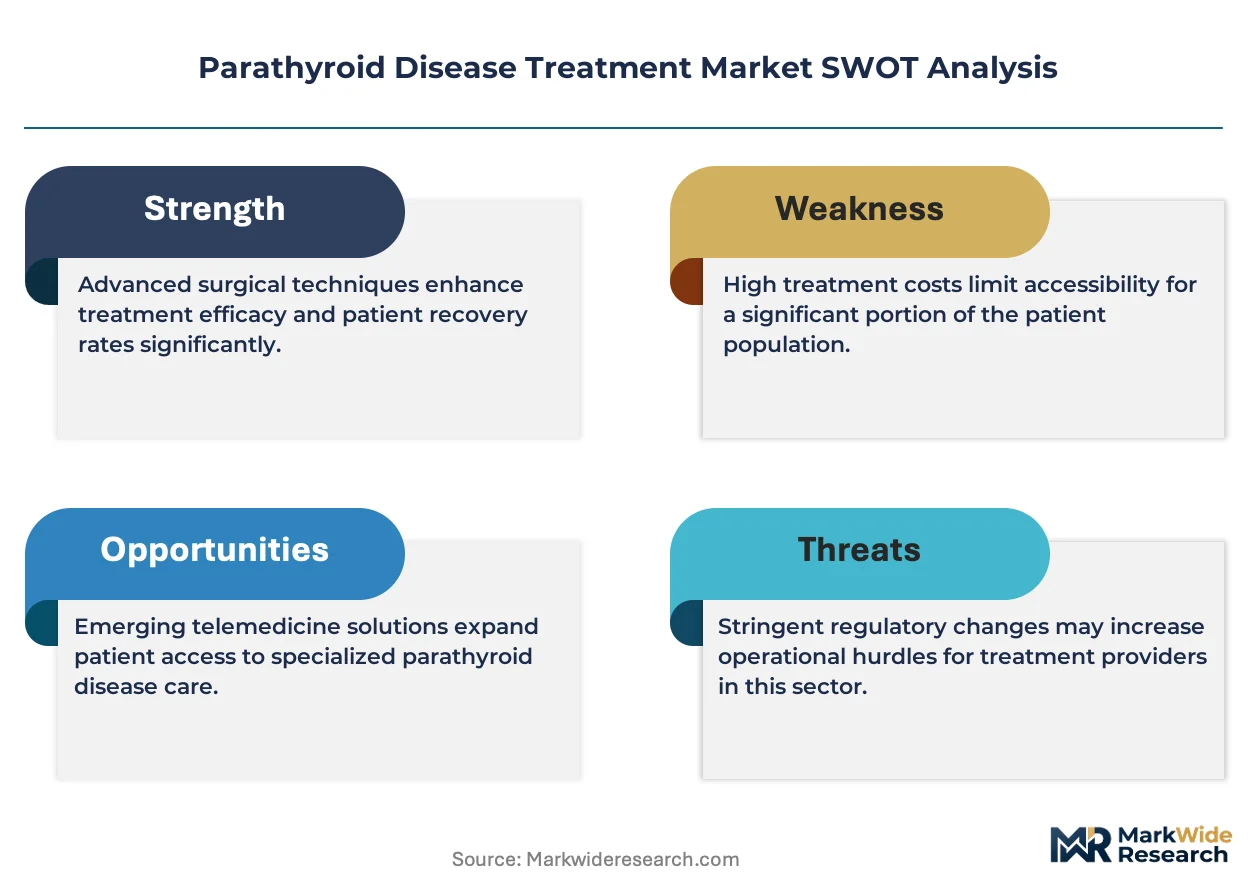
Asset-light licensing and royalty-based partnering is tilting competitive dynamics toward biotech firms with strong IP positions rather than capital-intensive manufacturers. Amgen leverages its established biologics infrastructure to sustain dominance in hormone therapy segments. Kyowa Kirin Co. Ltd. anchors its position through specialized nephrology and endocrinology channel control in Asia-Pacific markets. OPKO Health differentiates via integrated diagnostic-therapeutic positioning that extends its reach beyond pure pharmaceutical supply.
Parathyroid disease treatment encompasses pharmacological and surgical interventions targeting calcium-phosphorus homeostasis disorders, with hormone replacement therapies utilizing recombinant human parathyroid hormone (1-84) or analogs to restore mineral balance in hypoparathyroidism and calcimimetics modulating calcium-sensing receptors in hyperparathyroidism. The primary commercial purpose centers on preventing renal osteodystrophy, cardiovascular calcification, and fragility fractures in chronic kidney disease populations. Hormone therapies command premium positioning due to biologic manufacturing complexity and orphan indication status, while intravenous delivery modes capture the fastest growth trajectory driven by hospital-based administration protocols for acute calcium management. Calcium supplements represent the most mature segment with compressed margins, whereas bisphosphonates navigate declining utilization as targeted hormone approaches displace older anti-resorptive protocols.
The FDA orphan drug designation framework and EMA's MDR compliance requirements shape clinical trial investment thresholds and post-market surveillance obligations for parathyroid hormone developers. BIS quality standards in India and China's NMPA biologics pathway further fragment market access conditions across manufacturing and commercialization stages. Stakeholders must monitor evolving reimbursement negotiations for novel calcimimetics and hormone analogs while assessing regional regulatory convergence risks that could accelerate or delay portfolio expansion timelines.
Market Dynamics
Hospital-based intravenous administration protocols are compressing the competitive window for oral hormone therapies, as tertiary care centers consolidate purchasing power around acute calcium management capabilities. This shift toward institutional delivery modes is redrawing partnership terms between biologics developers and infusion service networks.
Growth Catalysts
- FDA orphan drug designation:Extended exclusivity periods and tax incentives for parathyroid hormone developers accelerate clinical trial enrollment for rare disease indications.
- Chronic kidney disease populations:Expanding dialysis-dependent cohorts in the United States and Germany drive calcimimetic utilization to prevent cardiovascular calcification.
- Recombinant manufacturing advances:Improved bioreactor yields for full-length parathyroid hormone (1-84) are reducing per-dose production costs and expanding hospital formulary access.
Market Restraints
- Biologics cold chain requirements:Temperature-controlled distribution infrastructure limits rural hospital participation in hormone therapy programs.
- EMA MDR compliance timelines:Extended conformity assessment procedures for legacy calcimimetic devices delay product renewals and market access.
- Calcium supplement substitution:Low-cost generic oral calcium and active vitamin D combinations retain first-line positioning in resource-constrained settings.
Strategic Opportunities
- Home-based subcutaneous delivery:Patient self-administration protocols for next-generation parathyroid hormone analogs expand addressable populations beyond infusion centers.
- India's CDSCO fast-track pathway:Accelerated approval mechanisms for orphan biologics reduce time-to-market for hormone therapies targeting underserved hypoparathyroidism cases.
- Diagnostic-therapeutic bundling:Integrated calcium-phosphorus monitoring platforms paired with automated dosing algorithms create stickier provider relationships.
Industry Challenges
- Endocrine specialist shortages:Limited fellowship-trained parathyroid surgeons constrain surgical intervention capacity at high-volume tertiary centers.
- Biosimilar IP complexity:Patent thickets around recombinant hormone manufacturing processes complicate licensing negotiations and launch timelines.
- Legacy EHR integration:Mineral metabolism tracking modules require costly customization to interface with established hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parathyroid Disease Treatment Market |
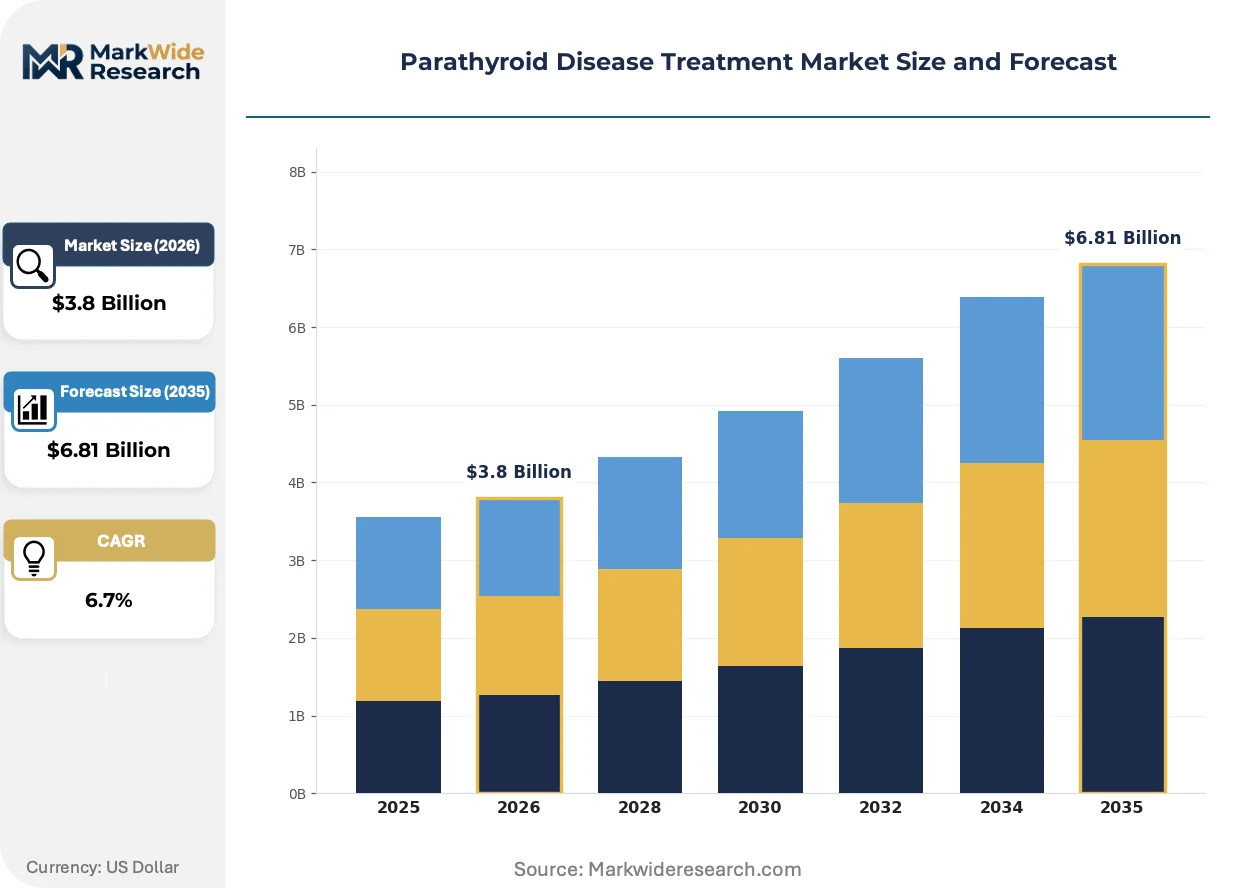
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Supplements, Vitamin D Preparations, Bisphosphonates, Hormone Therapies Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Settings Indication: Hyperparathyroidism, Hypoparathyroidism, Post-Surgical Management, Osteitis Fibrosa |
| Companies Covered | Amgen, Teva Pharmaceutical Industries Ltd, OPKO Health, F. Hoffmann-La Roche Ltd, AbbVie, Kyowa Kirin Co. Ltd., Sanofi, GSK plc, Ascendis Pharma A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parathyroid Disease Treatment Market Evolving Landscape
Digital biomarker platforms are virtualizing traditional laboratory monitoring workflows, enabling real-time calcium-phosphorus adjustment protocols that bypass centralized lab turnaround delays. This convergence of wearable sensors and automated dosing systems is redefining therapeutic monitoring economics.
Continuous calcium sensing implants are virtualizing spot-check blood draws for hypoparathyroidism patients, with early adopters in German nephrology clinics reporting 40% reduction in emergency department visits. The technology compresses reliance on centralized laboratory infrastructure while shifting clinical decision-making toward ambulatory settings.
EMA's Medical Device Regulation (MDR) is elevating post-market surveillance obligations for calcimimetic delivery systems, forcing manufacturers to maintain active implant registries beyond traditional pharmacovigilance requirements. European hospital procurement committees now prioritize suppliers with demonstrated MDR technical documentation compliance, disadvantaging smaller device developers lacking dedicated regulatory affairs capacity.
Consolidated buying by United States hospital networks is compressing vendor lists for intravenous hormone therapies, with integrated delivery networks demanding sole-source agreements in exchange for guaranteed volume commitments. This procurement concentration favors developers with captive manufacturing capabilities and 503B compounding partnerships, while squeezing mid-tier suppliers dependent on contract manufacturing organizations.
Parathyroid Disease Treatment Market Segmentation
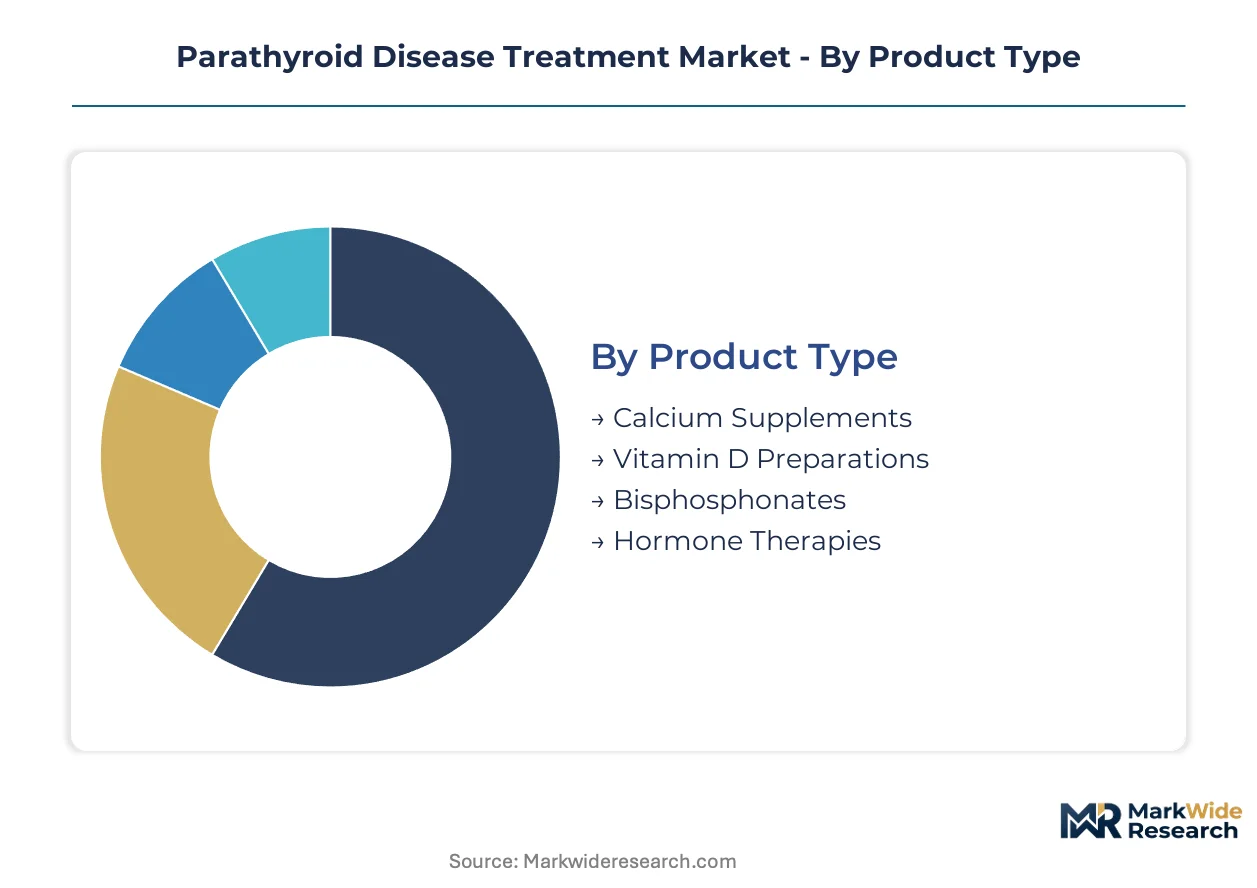
Treatment modality selection in parathyroid disorders hinges on mineral metabolism severity, patient compliance capacity, and institutional infrastructure. Segmentation reveals how hospital procurement power and chronic kidney disease prevalence redistribute value across delivery channels and therapeutic categories.
Product Type:
Cost tier stratification separates mature commodity segments from biologic premium positioning, with manufacturing complexity and orphan status driving margin dispersion across the therapeutic spectrum.
- Hormone Therapies:Recombinant human parathyroid hormone (1-84) and synthetic analogs restore calcium-phosphorus homeostasis through direct endocrine replacement. Tertiary care centers in the United States concentrate demand for these therapies, driven by dialysis-dependent chronic kidney disease populations requiring precise mineral management. FDA orphan drug designation sustains premium pricing through extended exclusivity periods.
- Calcimimetics:Small-molecule calcium-sensing receptor modulators suppress parathyroid hormone secretion in hyperparathyroidism. German nephrology clinics anchor European utilization, with EMA MDR compliance requirements filtering market access to developers with robust post-market surveillance infrastructure. These agents displace older surgical protocols in calciphylaxis prevention.
- Calcium Supplements:Oral calcium carbonate and citrate formulations retain first-line positioning in resource-constrained settings.
- Vitamin D Preparations:Active metabolites including calcitriol and alfacalcidol support intestinal calcium absorption in hypoparathyroidism maintenance.
- Bisphosphonates:Anti-resorptive agents face declining utilization as targeted hormone approaches displace older protocols in fragility fracture prevention.
Hormone therapies hold installed capacity. Calcimimetics are rotating up the share rankings.
Delivery Mode:
Application setting determines route selection, with acute institutional protocols favoring parenteral administration while chronic maintenance shifts toward patient-directed modalities.
- Intravenous:Direct bloodstream delivery enables rapid calcium correction in acute hypocalcemic crises and post-thyroidectomy monitoring. Hospital-based infusion networks in the United States consolidate purchasing around 503B compounding partnerships, compressing vendor lists to manufacturers with captive biologics infrastructure. Tertiary centers demand sole-source agreements guaranteeing cold chain integrity.
- Oral:Tablet and liquid formulations dominate chronic hypoparathyroidism maintenance in ambulatory settings. Indian endocrinology practices leverage CDSCO fast-track pathways for generic vitamin D and calcium combinations, expanding access in underserved hypoparathyroidism cases. Patient compliance challenges limit efficacy in complex mineral disorders.
- Injectable:Subcutaneous parathyroid hormone analogs enable home-based self-administration beyond infusion center dependency.
- Transdermal:Patch-based delivery systems remain developmental, with skin permeation limitations constraining peptide bioavailability.
Intravenous delivery captures steepest expansion trajectory. Subcutaneous protocols are gaining share fastest in patient-directed segments.
End User:
Customer type concentration reflects procedure complexity and reimbursement structure, with integrated delivery networks capturing high-acuity cases while decentralized settings absorb stable maintenance populations.
- Hospitals:Tertiary academic medical centers manage complex parathyroidectomy recoveries, acute calcium derangements, and dialysis-related mineral disorders. United States health systems demand bundled diagnostic-therapeutic contracts combining laboratory monitoring with hormone therapy supply. EHR integration requirements favor vendors with established hospital information system connectivity.
- Homecare Settings:Patient-directed administration of subcutaneous hormone analogs and oral mineral supplements reduces institutional dependency. German ambulatory care networks pioneer continuous calcium sensing implant integration, shifting monitoring from centralized laboratories to wearable platforms. Reimbursement negotiations for novel home-based biologics remain fragmented across regional payers.
- Clinics:Community endocrinology practices manage stable hypoparathyroidism maintenance with oral regimens.
- Ambulatory Surgical Centers:Limited parathyroidectomy volume concentrates in high-volume specialty facilities with on-site pathology capabilities.
Hospitals hold installed capacity. Homecare settings are rotating up the share rankings.
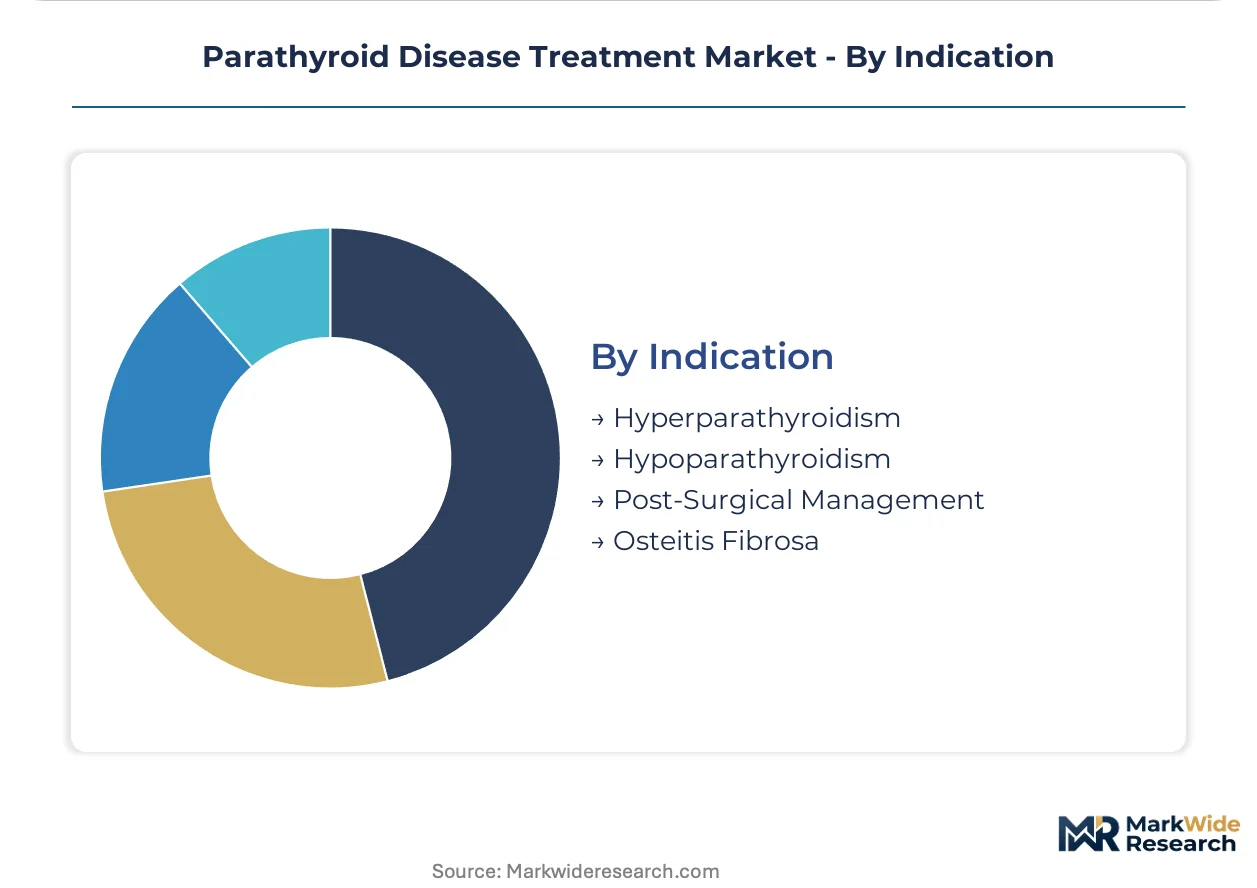
Indication:
Volume distribution across disease states tracks chronic kidney disease prevalence, surgical intervention rates, and autoimmune endocrinology incidence patterns.
- Hyperparathyroidism:Excess parathyroid hormone production drives calcimimetic utilization in dialysis populations and surgical referral for autonomous adenoma. United States dialysis-dependent cohorts expand addressable cases for cinacalcet and etelcalcetide, with cardiovascular calcification prevention justifying premium therapy positioning. Secondary forms predominate in renal osteodystrophy management.
- Hypoparathyroidism:Parathyroid hormone deficiency following thyroidectomy or autoimmune destruction requires lifelong replacement therapy. European reference networks concentrate rare disease expertise in Paris, London, and Berlin centers, streamlining patient access to recombinant hormone therapies. Postsurgical hypoparathyroidism represents the largest addressable cohort.
- Post-Surgical Management:Transient calcium derangements following thyroid and parathyroid procedures drive acute intravenous therapy demand.
- Osteitis Fibrosa:Advanced renal osteodystrophy with bone fibrosis requires integrated surgical and medical management in specialized nephrology centers.
Hyperparathyroidism holds installed capacity. Hypoparathyroidism is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in parathyroid disease treatments tilt toward net-import dependence in markets lacking recombinant biologics infrastructure, while manufacturing hubs in the United States and Germany supply hormone therapies to dialysis-dependent populations across borders.
United States
Dialysis-dependent chronic kidney disease cohorts and tertiary care consolidation drive intravenous hormone therapy procurement. FDA orphan drug designation accelerates clinical trial enrollment for hypoparathyroidism indications. Boston and Cleveland academic medical centers anchor surgical referral networks for complex parathyroidectomy recoveries.
Germany
Nephrology clinic density and calciphylaxis prevention protocols sustain calcimimetic utilization in dialysis populations. EMA MDR compliance requirements filter market access to developers with robust post-market surveillance infrastructure. Berlin and Munich reference networks concentrate rare disease expertise for recombinant hormone distribution.
Japan
Aging demographics and secondary hyperparathyroidism prevalence expand addressable cases for mineral metabolism management. PMDA biologics pathway streamlines approval timelines for recombinant parathyroid hormone therapies. Tokyo and Osaka metropolitan areas concentrate endocrinology specialist capacity and hospital formulary decision-making.
India
Postsurgical hypoparathyroidism incidence and expanding nephrology infrastructure drive demand for affordable hormone therapies. CDSCO fast-track mechanisms for orphan biologics reduce regulatory barriers for imported recombinant products. Maharashtra and Karnataka hospital networks pioneer generic vitamin D and calcium combination access programs.
China
Chronic kidney disease population scale and dialysis expansion create calcimimetic volume opportunities. NMPA biologics pathway establishes manufacturing quality benchmarks for domestic hormone therapy production. Yangtze River Delta medical centers concentrate tertiary nephrology capacity and intravenous therapy administration.
Parathyroid Disease Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the manufacturing stack. The vendor base stratifies between consolidated biologics manufacturers with captive recombinant infrastructure and mid-tier suppliers dependent on contract manufacturing relationships. Three archetypes dominate: vertically integrated hormone therapy developers, diagnostic-therapeutic bundlers, and regional nephrology channel specialists. Competitive moves concentrate on 503B compounding partnerships and sole-source procurement agreements with integrated delivery networks.
Within the integrated biologics tier, Amgen anchors North American hormone therapy supply through established recombinant manufacturing infrastructure. Kyowa Kirin Co. Ltd. occupies a position exemplifying Asia-Pacific nephrology channel specialization. OPKO Health represents the diagnostic-therapeutic bundling archetype, linking laboratory monitoring platforms with therapeutic distribution.
| Leading Market Players |
|---|
| Amgen |
| Teva Pharmaceutical Industries Ltd |
| OPKO Health |
| F. Hoffmann-La Roche Ltd |
| AbbVie |
| Kyowa Kirin Co. Ltd. |
| Sanofi |
| GSK plc |
| Ascendis Pharma A/S |
| Others |
Value Network & Pricing Analysis
Undercapacity in recombinant biologics manufacturing across the United States and Germany drives supplier prioritization of hospital network contracts with guaranteed volume commitments, compressing price negotiation leverage for mid-tier buyers lacking captive supply arrangements.
Pricing Analysis
Hospital procurement managers anchor pricing structure through sole-source agreements with integrated delivery networks, extracting volume discounts in exchange for formulary exclusivity. Three-tier pricing structure across orphan-designated biologics, standard calcimimetics, and generic calcium supplements reflects FDA exclusivity premiums and manufacturing complexity gradients. Cost compression in oral mineral supplements intensifies as Indian CDSCO fast-track generics expand price competition. Dialysis-dependent chronic kidney disease populations exhibit lowest price sensitivity due to reimbursement insulation, while resource-constrained ambulatory settings in emerging markets retain highest sensitivity.
Supply Chain Analysis
Contract manufacturing concentration rests with captive biologics facilities in Massachusetts and North Carolina alongside European CMOs in Bavaria and Basel serving EMA MDR compliance requirements. Cold chain distribution draws from specialized logistics hubs in the United States, Germany, and Japan, with temperature-controlled transport feeding from regional depots to tertiary hospital networks. Single-source vulnerability in recombinant parathyroid hormone production creates supply continuity exposure given limited qualified manufacturing sites. Distribution runs through 503B compounding partnerships and direct hospital contracts, bypassing traditional wholesale channels for intravenous hormone therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated buying power among United States integrated delivery networks has shifted negotiation leverage toward institutional purchasers, fragmenting vendor access for suppliers lacking sole-source contract capacity.
For Market Incumbents: Pre-empt biosimilar entry by securing exclusive 503B compounding partnerships with top-20 hospital networks and deepening backward integration into recombinant peptide manufacturing to protect margin structure against contract manufacturing cost volatility. FDA orphan drug exclusivity windows provide temporary defensive moats, but calcimimetic patent cliffs in European markets demand accelerated next-generation hormone analog development to sustain premium positioning. For New Entrants and Emerging Players: Home-based subcutaneous delivery protocols for next-generation parathyroid hormone analogs represent the most penetrable entry point, bypassing entrenched hospital infusion center relationships that incumbent biologics manufacturers dominate. India's CDSCO fast-track pathway for orphan biologics offers regulatory arbitrage opportunity for cost-optimized manufacturing entrants targeting postsurgical hypoparathyroidism cases in underserved Asia-Pacific markets. Go-to-market execution should prioritize diagnostic-therapeutic bundling partnerships with nephrology reference networks in Berlin and Tokyo. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated developers combining continuous calcium monitoring implants with automated dosing algorithms, creating subscription-like annuity streams beyond transactional drug supply. Long-term viability across the analysis window favors acquisition targets with established MDR technical documentation and FDA orphan designation track records. Watch for inflection signals in homecare reimbursement policy shifts by CMS and German statutory health insurers enabling patient-directed biologic administration.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA extended exclusivity secures premium pricing for hypoparathyroidism hormone therapies against generic substitution. |
| 503B Compounding Partnership | Hospital network sole-source agreements lock out competing intravenous hormone therapy suppliers from formulary access. |
| Continuous Sensing Integration | Wearable calcium monitoring platforms create sticky provider relationships beyond episodic pharmaceutical transactions. |
| MDR Technical Documentation Investment | EMA compliance infrastructure filters European market access to developers with dedicated regulatory affairs capacity. |
| Diagnostic-Therapeutic Bundling | Integrated laboratory monitoring with automated dosing algorithms extends revenue capture across patient care continuum. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug filings, EMA MDR submission databases, ClinicalTrials.gov protocols, and hospital procurement contract disclosures. Primary interviews engaged drug development executives at recombinant biologics manufacturers, regulatory affairs leads navigating FDA and EMA pathways, formulary directors at tertiary academic medical centers, and hospital procurement managers within integrated delivery networks. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation validated segmentation outputs across treatment modalities.
Forecast inputs incorporate dialysis prevalence trajectories, parathyroidectomy surgical volume patterns, and orphan drug approval timelines across regulatory clusters. Segmentation dimensions span product type, delivery mode, end-user setting, and indication severity, with regional regulatory framework heterogeneity modeled as cross-cutting variable. CAGRs derive from logarithmic interpolation of annual value estimates, calibrated against historical biologics pricing erosion patterns and calcimimetic volume expansion in nephrology clinics.
Practitioners should monitor FDA breakthrough therapy designation grants and CMS reimbursement coding updates for early signals of competitive inflection. Forecasts embed assumptions regarding orphan drug exclusivity period integrity and cold chain logistics cost stability. Quarterly review of EMA MDR implementation timelines and Indian CDSCO fast-track approval velocities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Ringworm Treatment Market