
 Graft Delivery Devices Market | 2026-2036
Graft Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Graft Delivery Devices Market Foresight
Minimally invasive delivery architecture is fragmenting across competing platform approaches, forcing manufacturers to choose between integrated systems and modular component strategies. Stryker leverages its orthopedic implant ecosystem to bundle delivery tools with biologic graft materials. Medtronic anchors its position through spine and cardiovascular application breadth, while Arthrex, Inc. specializes in arthroscopic delivery configurations for sports medicine procedures.
Graft delivery devices are precision instruments engineered to transport bone, tissue, or synthetic matrices to targeted anatomical sites, typically incorporating luminal diameters between 2.5 mm and 6.0 mm and ergonomic handles calibrated for tactile feedback during minimally invasive access. These systems serve orthopedic, vascular, and neurologic interventions where controlled deposition directly influences fusion rates and healing outcomes. Balloon catheter platforms command substantial installed base loyalty in vascular therapy areas, while bioabsorbable technology segments attract premium positioning as surgeons seek to eliminate secondary retrieval procedures. Drug-eluting delivery systems represent the fastest-expanding technology category as manufacturers integrate localized pharmacologic release with mechanical scaffolding functions.
The FDA's 510(k) framework and the EU Medical Device Regulation (MDR) impose distinct clinical evidence thresholds that shape product development timelines and market access sequencing for combination graft technologies. ISO 13485 quality management certification and Japan's PMDA ministerial ordinances further condition commercial eligibility across major demand centers. Stakeholders must monitor evolving reimbursement classifications for bioabsorbable and drug-eluting platforms as payors recalibrate coverage thresholds against demonstrated clinical utility.
Market Dynamics
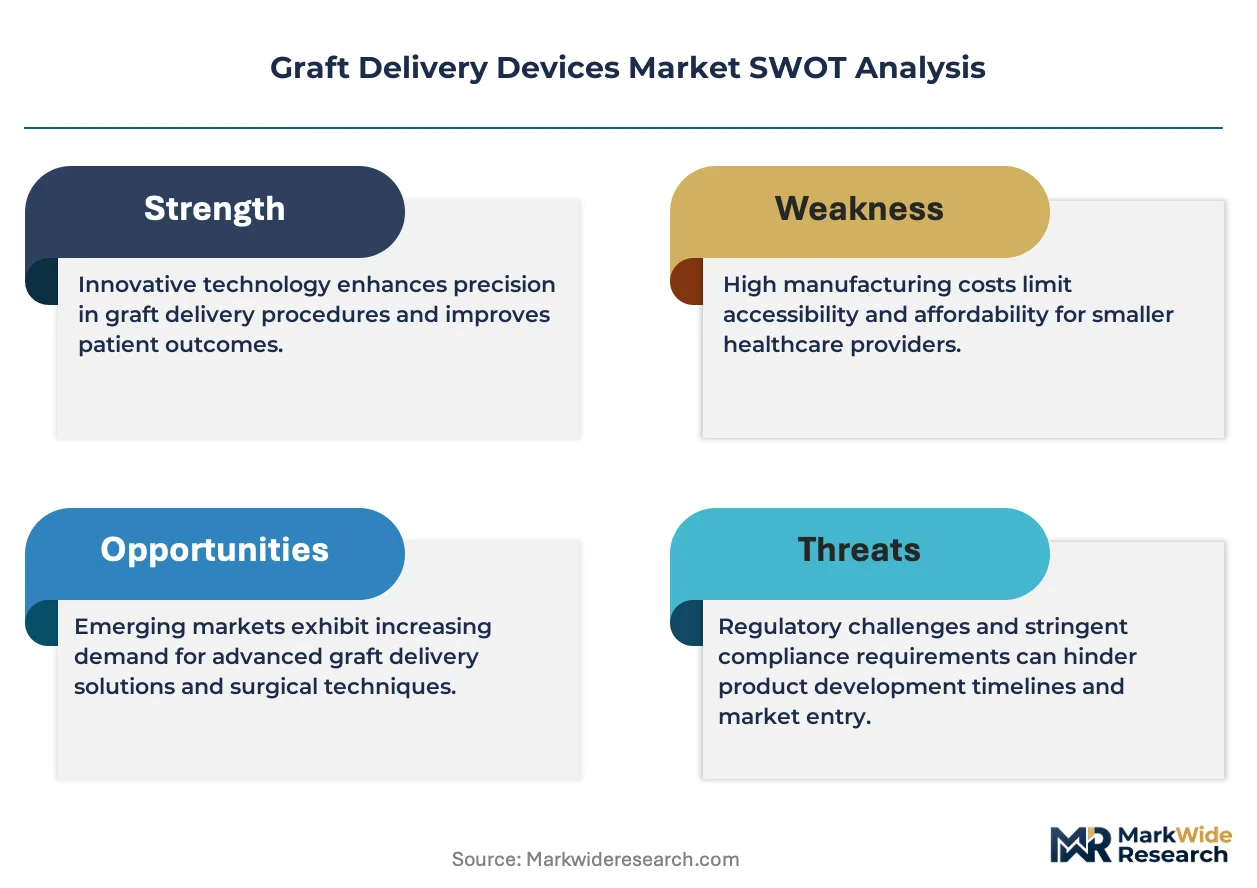
Drug-eluting delivery platforms are compressing development timelines as manufacturers race to integrate localized pharmacologic release with mechanical scaffolding, forcing legacy pure-play instrument vendors to acquire biologic capabilities or exit the orthopedic spine segment entirely.
Growth Catalysts
- Japan's PMDA streamlining:Updated ministerial ordinances for combination product review are accelerating commercial entry timelines for bioabsorbable graft systems in the world's fastest-aging orthopedic market.
- Orthopedic surgical center expansion:Ambulatory surgery centers in the United States are installing precision graft delivery suites to capture migrating spine and sports medicine volumes from inpatient settings.
- Bioabsorbable polymer advancement:Next-generation polylactic acid formulations with tunable degradation profiles are eliminating secondary retrieval procedures and expanding addressable procedure pools.
Market Restraints
- EU MDR clinical evidence thresholds:The Medical Device Regulation's expanded requirements for combination graft technologies are extending development timelines and freezing pipeline commitments from mid-cap manufacturers lacking trial infrastructure.
- Biologic graft material concentration:Sourcing for demineralized bone matrix and synthetic ceramic matrices clusters among three dominant tissue banks and two specialty chemical suppliers, creating input vulnerability.
- Reimbursement compression:CMS and commercial payors in the United States are narrowing coverage for fusion procedures without demonstrated radiographic outcome differentiation, pressuring device ASPs.
Strategic Opportunities
- German outpatient clinic penetration:Reimbursement alignment for minimally invasive spine procedures in ambulatory settings remains underdeveloped relative to surgical volume potential, creating first-mover positioning for integrated delivery system vendors.
- Neurologic application expansion:Delivery platforms originally developed for orthopedic fusion are adapting to dural repair and peripheral nerve conduit placement, opening procedure categories with limited incumbent competition.
- ISO 13485 certification arbitrage:Manufacturers holding dual US-EU quality management credentials can sequence market entry to capture 510(k) clearance data for subsequent MDR technical documentation, compressing total time-to-revenue.
Industry Challenges
- Cross-functional talent scarcity:Engineers possessing simultaneous expertise in catheter-based delivery mechanics and biologic material science command premium compensation and limited availability, constraining R&D velocity for platform extensions.
- Legacy sterilization validation:Ethylene oxide and gamma irradiation protocols established for metallic instruments require complete revalidation for bioabsorbable polymer matrices, extending manufacturing qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graft Delivery Devices Market |
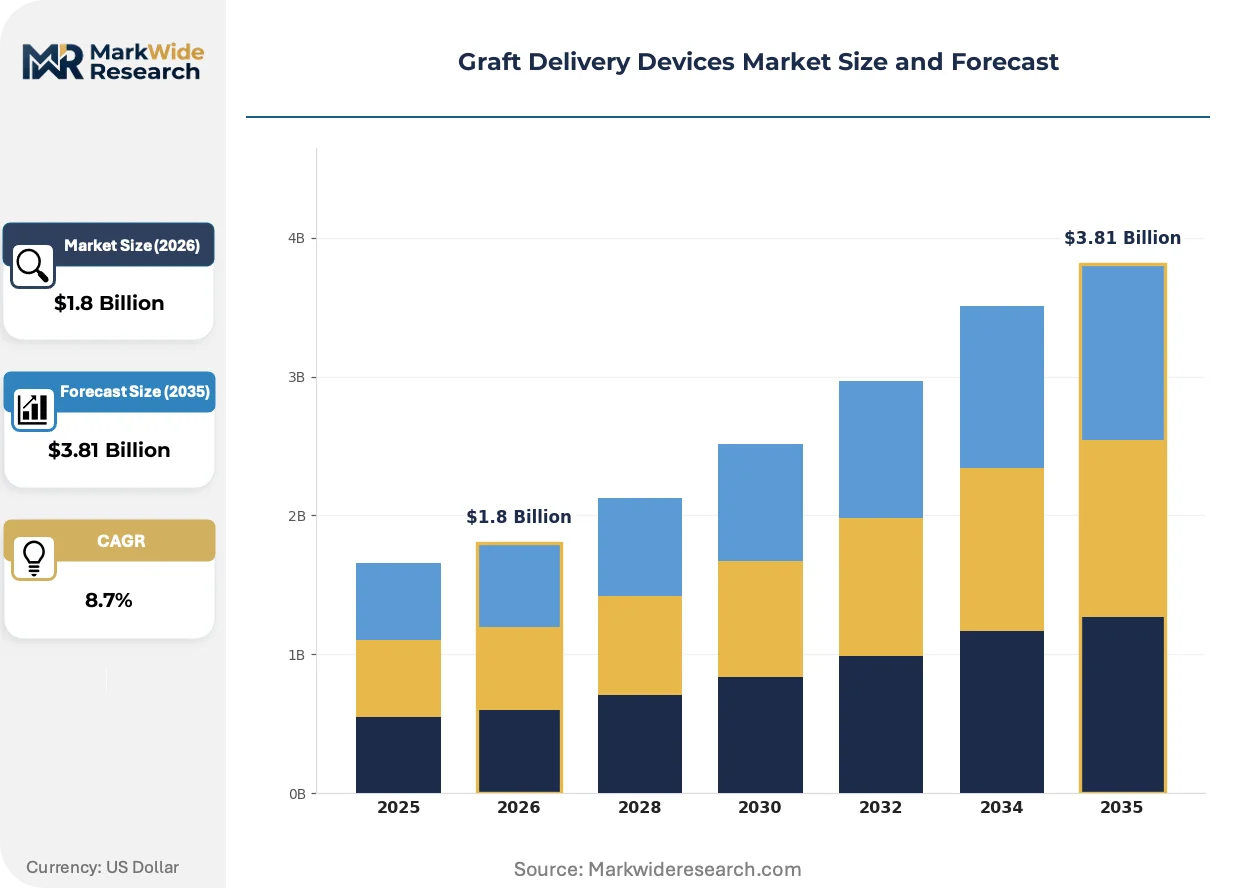
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Stent Grafts, Delivery Systems, Guides Therapy Area: Vascular, Orthopedic, Neurology, Urology End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Labs Technology: Minimally Invasive, Bioabsorbable, Drug-Eluting, Combination |
| Companies Covered | Arthrex, Inc., Stryker, Medtronic, Nordson Corporation, MEDMIX SYSTEMS AG, SurGenTec, Pinnacle Spine Group, Kleiner Device Labs, LLC, Orthofix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graft Delivery Devices Market Shifts & Advancements
Convergence between mechanical delivery precision and localized therapeutic release is redefining competitive boundaries, with instrument manufacturers acquiring pharmacologic capabilities and biologic suppliers building captive delivery platforms.
Drug-eluting graft delivery systems incorporate antiresorptive or osteoinductive agents directly into polymer matrices, enabling controlled release kinetics at fusion sites. Spine surgeons in high-volume United States academic centers are adopting these platforms for complex multi-level procedures where pseudarthrosis risk exceeds baseline. Pure-play mechanical delivery is migrating from standalone instrument sales toward bundled biologic-mechanical offerings that capture procedure economics previously allocated to separate pharmaceutical interventions.
The FDA's updated 510(k) clearance pathways for combination product devices are compressing premarket review timelines for graft delivery systems incorporating pharmacologic components. This regulatory efficiency is redirecting development investment toward drug-device integration rather than incremental mechanical refinement. Orthopedic and spine application segments are responding with accelerated pipeline commitments, while vascular delivery platforms remain subject to more stringent PMA requirements that favor incumbents with established clinical trial infrastructure.
Hospital procurement committees are consolidating vendor relationships around full-procedure solutions rather than discrete instrument purchases. Integrated delivery platforms that bundle graft material, delivery mechanism, and postoperative monitoring are displacing modular component sourcing in United States health system purchasing. This concentration is most visible in integrated delivery networks where standardization incentives override surgeon-specific instrument preferences, compressing available supplier slots and elevating scale requirements for market participation.
Graft Delivery Devices Market Segmentation
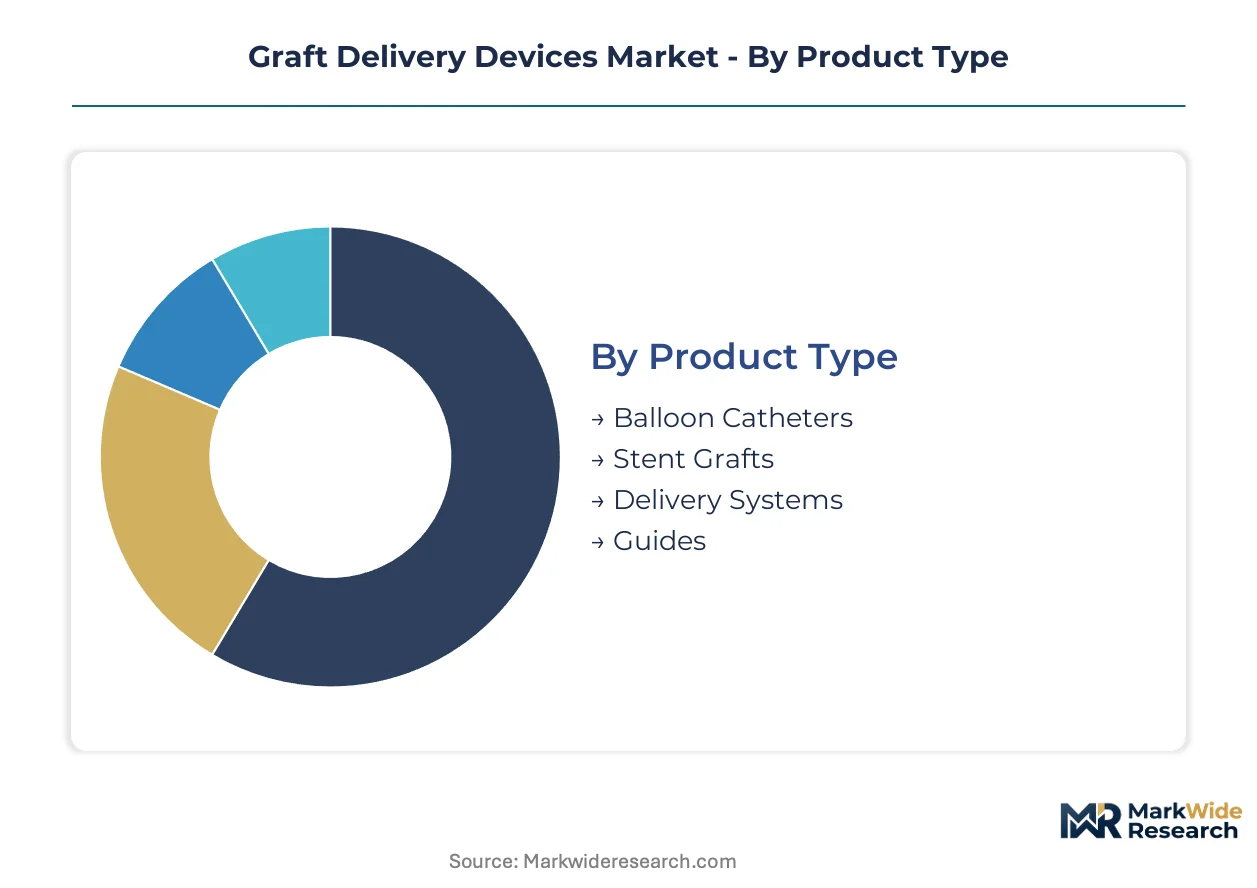
Graft delivery devices fragment across four intersecting dimensions that determine procurement patterns and R&D investment allocation. Product type and technology cycles operate on different refresh timelines, forcing portfolio managers to balance near-term revenue stability against long-term platform transitions.
Product Type:
Balloon catheter platforms turn over fastest as catheter-based delivery mechanics advance, while stent grafts and guides maintain longer installed-base loyalty due to surgeon training investments and validation requirements.
- Balloon Catheters:Elastomeric balloon membranes mounted on catheter shafts enable controlled expansion and graft positioning within vascular lumens. Demand concentrates in United States academic medical centers where complex aortic procedures require precise diameter modulation. Secondary retrieval rates and restenosis incidence drive replacement cycles faster than competing platforms.
- Stent Grafts:Metallic or polymeric scaffolds pre-loaded within delivery sheaths provide structural support at anastomosis sites. German cardiovascular centers anchor demand for thoracic endovascular applications, where durability requirements extend product lifecycles and reduce switching incentives.
- Delivery Systems:Integrated mechanical platforms combining insertion, positioning, and deployment functions in single-use configurations.
- Guides:Accessory instruments providing trajectory stabilization and depth calibration during graft placement.
Stent grafts dominate installed base. Balloon catheters are where expansion concentrates.
Therapy Area:
Orthopedic applications command premium pricing due to biologic graft material bundling, while vascular volumes scale through procedure repetition in high-throughput catheterization labs.
- Vascular:Endovascular delivery to arterial and venous structures for aneurysm repair and bypass procedures. Japanese stroke centers are expanding adoption of flow-diverting delivery platforms for cerebral aneurysm management.
- Orthopedic:Bone void filling and fusion promotion in spine and extremity reconstruction. United States ambulatory surgery centers are capturing migrating spine volumes through dedicated graft delivery suites.
- Neurology:Dural repair and peripheral nerve conduit placement using adapted orthopedic delivery architectures.
- Urology:Ureteral and bladder wall reconstruction with synthetic and biologic matrices.
Orthopedic applications generate highest revenue per procedure. Vascular segments scale through volume density.
End User:
Procurement authority shifts dramatically across settings, with hospitals demanding full-procedure bundles and ambulatory centers prioritizing instrument cost efficiency.
- Hospitals:Integrated delivery networks in the United States are consolidating vendor relationships around platforms that bundle graft material, delivery mechanism, and postoperative monitoring capabilities.
- Ambulatory Surgical Centers:Standalone facilities capturing spine and sports medicine volumes from inpatient settings require compact, single-use delivery systems with minimal sterilization infrastructure.
- Clinics:Outpatient settings with limited procedure volume favor modular component sourcing over capital-intensive integrated platforms.
- Research Labs:Academic and commercial R&D facilities driving preclinical validation of bioabsorbable and drug-eluting technologies.
Hospitals anchor current revenue. Ambulatory surgical centers are climbing the fastest.
Technology:
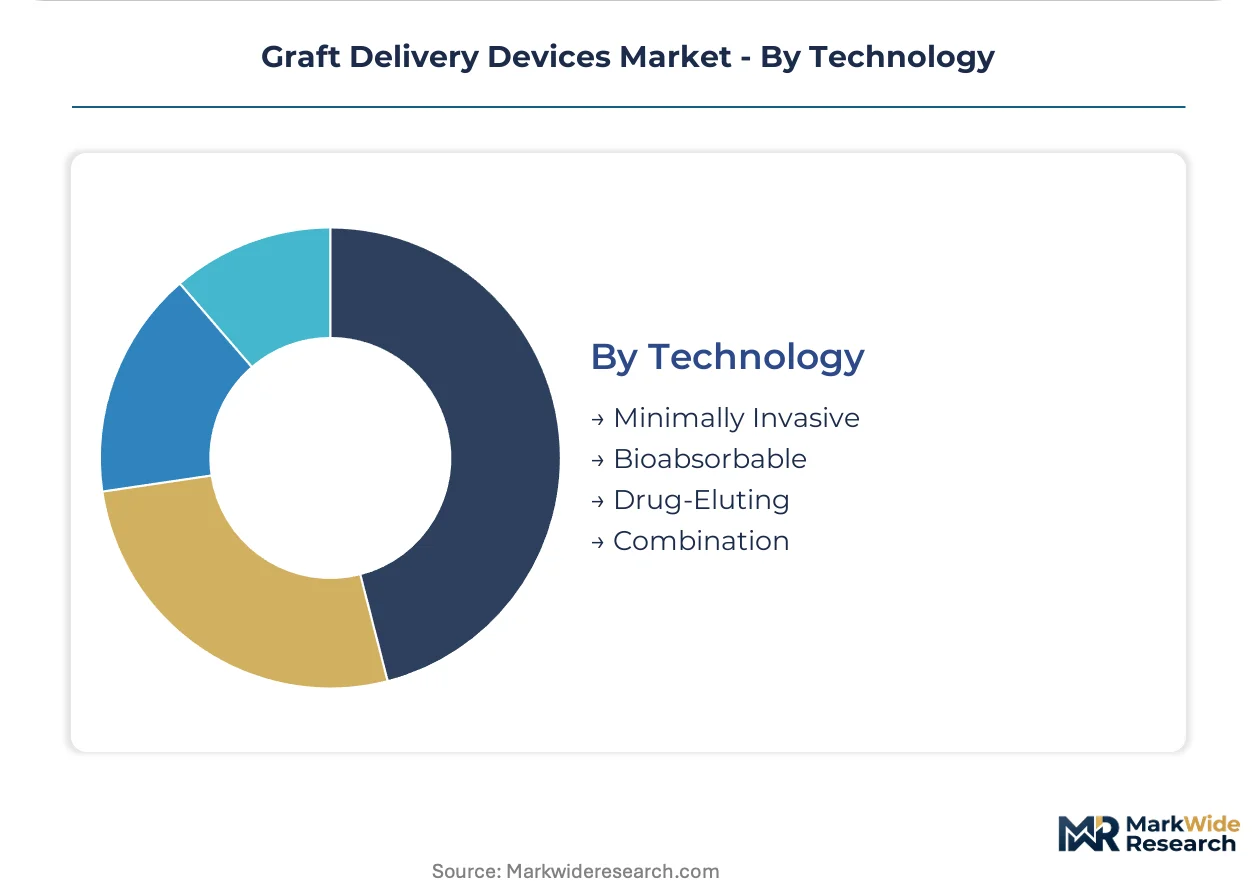
Development investment is compressing toward combination platforms as pure mechanical differentiation exhausts patent protection and surgeon preference data.
- Minimally Invasive:Percutaneous and endoscopic delivery architectures reducing tissue disruption and recovery timelines. German outpatient spine clinics are adopting these platforms ahead of reimbursement alignment.
- Bioabsorbable:Polylactic acid and polyglycolic acid matrices engineered for tunable degradation profiles that eliminate secondary retrieval procedures. Japan's PMDA streamlining is accelerating commercial entry for these systems.
- Drug-Eluting:Polymer matrices incorporating antiresorptive or osteoinductive agents for localized pharmacologic release at fusion sites.
- Combination:Integrated mechanical-biologic-pharmacologic platforms representing the convergence trajectory across all delivery categories.
Minimally invasive platforms hold current share leadership. Drug-eluting systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision orthopedic delivery systems to United States health systems, establishing the primary trade corridor in this medical device category. Japanese suppliers are expanding shipments to Southeast Asian surgical centers as regional procedural volumes climb.
United States
FDA 510(k) clearance streamlining for combination product devices is accelerating commercial entry timelines. Ambulatory surgery centers in Texas and Florida are installing dedicated graft delivery suites to capture migrating spine volumes from inpatient hospitals. The Southeast corridor from Atlanta to Orlando anchors ASC expansion.
Germany
EU MDR clinical evidence thresholds are extending development timelines for combination graft technologies. The Medical Device Regulation's expanded requirements are freezing pipeline commitments from mid-cap manufacturers lacking trial infrastructure. Bavaria's medical technology cluster around Munich concentrates sterilization validation expertise.
Japan
PMDA ministerial ordinance updates for combination product review are accelerating bioabsorbable graft system approvals. The world's fastest-aging orthopedic market is expanding procedural volumes in stroke centers and spine clinics. Tokyo-Osaka corridor hospitals are adopting flow-diverting delivery platforms for cerebral aneurysm management.
United Kingdom
MHRA post-Brexit regulatory alignment with EU MDR is creating dual compliance burdens for manufacturers. London academic medical centers are consolidating vendor relationships around full-procedure bundles. The Cambridge-Oxford-London triangle anchors biologic material research and delivery platform development.
Switzerland
Swissmedic certification requirements for combination devices are conditioning commercial eligibility for precision delivery systems. Basel's pharmaceutical-device convergence cluster is driving drug-eluting platform innovation. The country's quality management infrastructure supports ISO 13485 certification arbitrage for dual US-EU market sequencing.
Graft Delivery Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Orthopedic implant conglomerates leverage installed base relationships to bundle delivery tools with biologic materials. Pure-play instrument vendors face pressure to acquire pharmacologic capabilities or exit spine segments entirely. Dominant competitive moves include M&A activity targeting biologic material suppliers and strategic partnerships combining mechanical delivery with localized drug release platforms.
Within the orthopedic ecosystem tier, Stryker and Medtronic exemplify channel-controlling archetypes that anchor competitive positioning through application breadth. Arthrex, Inc. occupies a specialist position representing the sports medicine-focused configuration. These three entities illustrate the strategic divergence between integrated platform bundling and targeted procedural specialization.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Stryker |
| Medtronic |
| Nordson Corporation |
| MEDMIX SYSTEMS AG |
| SurGenTec |
| Pinnacle Spine Group |
| Kleiner Device Labs, LLC |
| Orthofix |
| Others |
Supply & Pricing Matrix
Undercapacity in German sterilization validation facilities is compressing contract manufacturing lead times and amplifying pricing power for ISO 13485-certified suppliers serving dual US-EU markets. This utilization squeeze forces mid-tier manufacturers to accept premium slot pricing or defer commercial launches, reshaping procurement economics across bioabsorbable polymer platforms.
Pricing Analysis
Current-generation drug-eluting delivery platforms command substantial premiums over prior-generation mechanical-only systems, while next-generation combination products are pricing at investigational-stage benchmarks. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA clearance tier and biologic material bundling depth. Pricing pressure stems from CMS narrowing coverage for fusion procedures without radiographic outcome differentiation. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while United States academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Contract manufacturing for bioabsorbable polymer matrices concentrates among Bavarian sterilization specialists and Swiss precision extrusion houses. Raw material sourcing draws from German polylactic acid compounders, Japanese ceramic matrix suppliers, and United States demineralized bone matrix tissue banks. Single-source vulnerability permeates the demineralized bone matrix tier where three tissue banks control biologic graft material supply. Distribution runs through orthopedic implant distributors with hospital system contracting authority, bypassing traditional device wholesaler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers possessing simultaneous catheter-based delivery mechanics and biologic material science expertise command compensation premiums that constrain R&D velocity, making talent acquisition and retention the decisive capability bottleneck for platform extension.
For Market Incumbents: Entrench market position through backward integration into biologic material supply and captive sterilization capacity in Germany's Bavaria cluster. Acquire mid-cap manufacturers frozen by EU MDR clinical evidence thresholds to capture pipeline assets without de novo trial investment. Prioritize ISO 13485 certification arbitrage to compress time-to-revenue across sequential US and EU market entries. For New Entrants and Emerging Players: German outpatient spine clinics represent underpenetrated demand where reimbursement alignment lags surgical volume potential. Target ambulatory surgical center instrument cost efficiency requirements with compact single-use delivery systems requiring minimal sterilization infrastructure. Pursue strategic partnerships with United States GPOs to bypass entrenched hospital procurement committee consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers bundling graft material, delivery mechanism, and postoperative monitoring into full-procedure solutions. Long-term viability favors acquisition targets with dual US-EU quality credentials and drug-device combination product pipelines. Monitor FDA 510(k) clearance velocity for combination graft technologies as inflection indicator for development investment redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biologic Material Supply | Captures margin pool previously allocated to demineralized bone matrix tissue banks. |
| FDA 510(k) Combination Product Pathway | Accelerates commercial entry for drug-eluting platforms versus PMA-track vascular devices. |
| ISO 13485 Certification Arbitrage | Enables sequential market entry leveraging 510(k) data for subsequent EU MDR documentation. |
| Ambulatory Surgical Center Partnership | Captures migrating spine volumes from inpatient settings through dedicated graft delivery suites. |
| German Outpatient Clinic Penetration | Exploits reimbursement misalignment ahead of policy catch-up in Europe's largest orthopedic market. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic spine surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up procedure volume modeling triangulated with top-down manufacturer revenue analysis across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation across product type, therapy area, end user, and technology dimensions modeled throughout the projection horizon. CAGRs were derived from procedure volume trajectories and ASP evolution patterns. Industry-specific inputs incorporated PMDA ministerial ordinance streamlining effects and EU MDR clinical evidence threshold impacts on pipeline commitments.
The forecast holds incumbent behavior within observed patterns; aggressive M&A moves by orthopedic implant conglomerates or mid-cap biologic material suppliers would shift outcomes beyond modeled ranges. Quarterly review of FDA 510(k) clearance velocity, CMS reimbursement classification updates, and German outpatient clinic reimbursement policy adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Bowel Stimulators Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Otoscope Devices Market
Medical Devices
United States Respiratory Devices Market
Medical Devices
Pocket Otoscope Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Eye Massage Device Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Global Automated Dispensing Machines Market