
 Herpes Marker Testing Market | 2026-2036
Herpes Marker Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Herpes Marker Testing Market Foresight
Multiplex PCR integration with automated sample-to-answer platforms is reconfiguring herpes marker testing workflows, compressing turnaround times from days to hours. Abbott Laboratories leverages its installed base of molecular diagnostics instruments to sustain high-throughput HSV testing in centralized laboratories. Thermo Fisher Scientific anchors its position through extensive PCR reagent portfolios that span research and clinical applications. F. Hoffmann-La Roche Ltd. competes on integrated platform stickiness, embedding herpes assays within broader infectious disease menus.
Herpes marker testing encompasses laboratory and point-of-care methods for detecting herpes simplex virus type 1 and type 2 through antigen, antibody, or nucleic acid targets, typically requiring specimen collection from active lesions, blood, or cerebrospinal fluid with sensitivity thresholds varying by modality. Antibody tests occupy the largest volume share due to lower per-test cost and broad screening utility, while nucleic acid tests capture premium positioning through superior sensitivity in neonatal and CNS infection diagnosis. Diagnostic laboratories concentrate the highest throughput volumes, though home care settings are expanding fastest as self-collection protocols gain regulatory clearance.
The FDA governs test complexity classification and premarket authorization pathways, while CLIA standards dictate laboratory operational requirements and personnel qualifications for herpes marker testing. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for HSV assays entering European markets. Stakeholders must monitor evolving payer coverage decisions for multiplex panels versus standalone HSV tests, as reimbursement granularity will determine platform investment returns and test menu prioritization across health systems.
Market Dynamics
Multiplex PCR automation is compressing turnaround times and forcing laboratory consolidation as hospitals retire legacy immunoassay platforms for integrated molecular diagnostics workflows.
Growth Catalysts
- CLIA Complexity Reclassification:The FDA's streamlined moderate-complexity pathway expands HSV testing access to physician office laboratories, decentralizing diagnostic capacity beyond centralized hospital labs.
- Neonatal Screening Protocols:Maternal-fetal medicine units in tertiary care centers are mandating PCR-based HSV detection for suspected encephalitis cases, driving nucleic acid test volume concentration.
- Self-Collection Regulatory Clearance:Home-based specimen collection kits with telehealth integration unlock demand from asymptomatic screening populations previously excluded from clinical workflows.
Market Restraints
- Reagent Supply Concentration:Taq polymerase and proprietary master mix formulations depend on a narrow supplier base concentrated in North American and European contract manufacturers.
- EU MDR Compliance Burden:The In Vitro Diagnostic Regulation imposes extended clinical evidence timelines and notified body bottlenecks for HSV assay market entry.
- Antibody Test Commoditization:ELISA-based serology faces pricing pressure from lateral flow alternatives with equivalent sensitivity thresholds for routine screening applications.
Strategic Opportunities
- Sub-Saharan Africa Laboratory Networks:PEPFAR-funded molecular diagnostics infrastructure creates installed base potential for HSV-2 screening integration within existing HIV/TB testing platforms.
- Digital PCR Differentiation:Absolute quantification capabilities address viral load monitoring needs in immunocompromised transplant populations underserved by qualitative methods.
- Pharmacy Channel Expansion:Retail clinic networks with CLIA-waived certification seek point-of-care HSV assays for same-day symptomatic patient management.
Industry Challenges
- Molecular Diagnostics Technologist Shortage:Specialized training requirements for PCR platform operation constrain laboratory expansion plans in community hospital settings.
- Interoperability with LIS Architectures:Proprietary data formats from automated sample-to-answer systems require costly middleware development for health system integration.
- Proficiency Testing Harmonization:Variable external quality assessment schemes across state laboratory licensure programs complicate multi-site quality management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herpes Marker Testing Market |
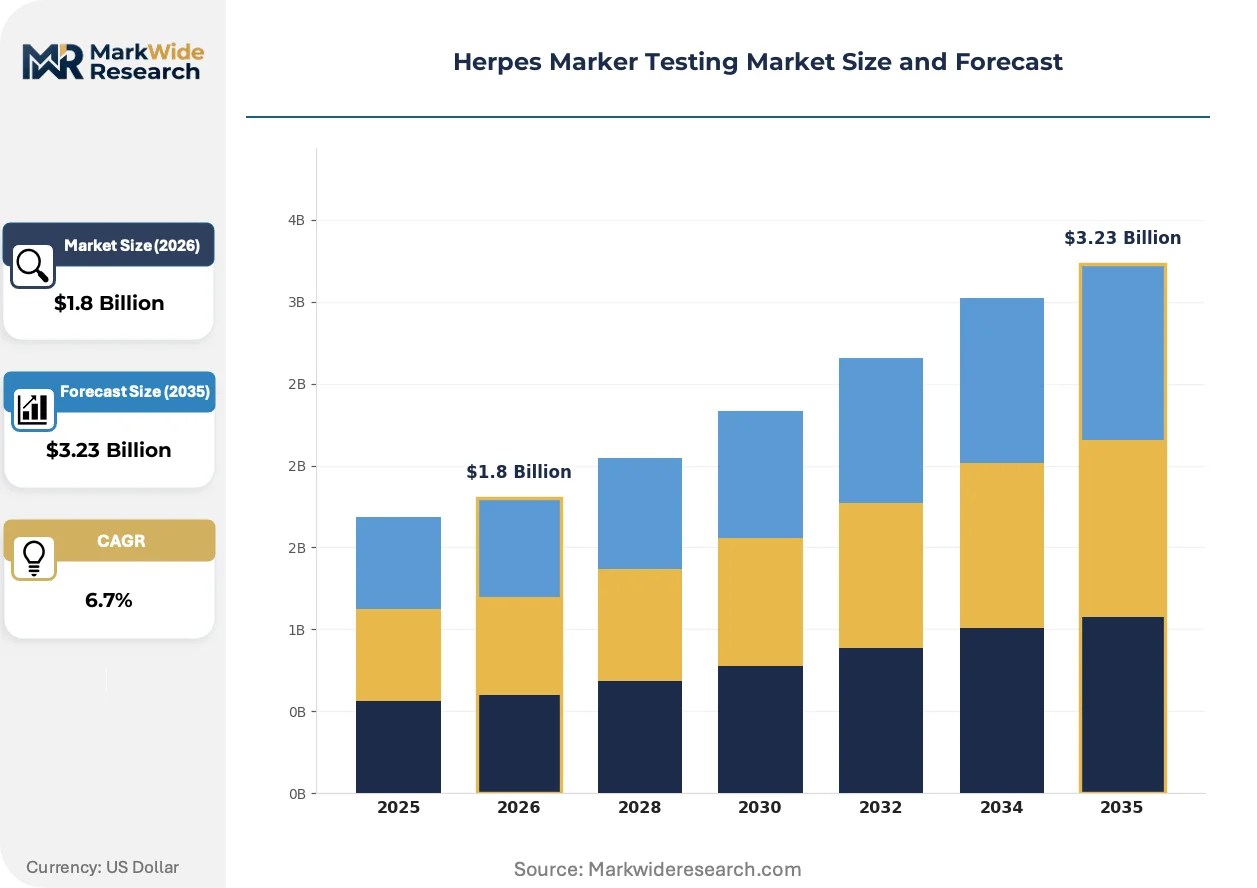
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Tests, Antibody Tests, Viral Culture, Nucleic Acid Tests End User: Hospitals, Diagnostic Laboratories, Clinics, Home Care Settings Technology: PCR, ELISA, Immunofluorescence, Rapid Testing Application: Screening, Diagnosis, Monitoring, Research |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd., DiaSorin S.p.A., BioMérieux SA, Quidel Corporation, Abcam Plc, Qiagen N.V., Meridian Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herpes Marker Testing Market Shifts & Advancements
Herpes marker testing is undergoing platform convergence as laboratories demand unified infectious disease menus rather than standalone HSV assays, compressing vendor specialization strategies.
CRISPR-based detection is hybridizing with conventional PCR workflows to enable isothermal amplification at reduced thermal cycling infrastructure requirements. Rural and resource-limited laboratories lacking real-time PCR capacity are piloting these systems for HSV-1/HSV-2 differentiation. The technology is hybridizing market segmentation by collapsing the cost barrier between reference laboratory accuracy and near-patient accessibility.
The EU In Vitro Diagnostic Regulation's performance evaluation requirements are extending HSV assay development timelines by mandating prospective clinical studies across diverse epidemiological cohorts. Manufacturers must demonstrate analytical sensitivity in neonatal, immunocompromised, and standard adult populations. European notified body capacity constraints are forcing prioritization of high-volume infectious disease panels over standalone herpes assays.
Reference laboratory networks are consolidating procurement decisions through centralized molecular diagnostics committees that evaluate total cost of ownership across platform, reagent, and service contracts. Independent community laboratories lose negotiating leverage as health system purchasing organizations aggregate HSV test volumes. The United States exhibits the most pronounced buyer concentration, with three national laboratory chains controlling the majority of nucleic acid test throughput.
Herpes Marker Testing Market Segmentation
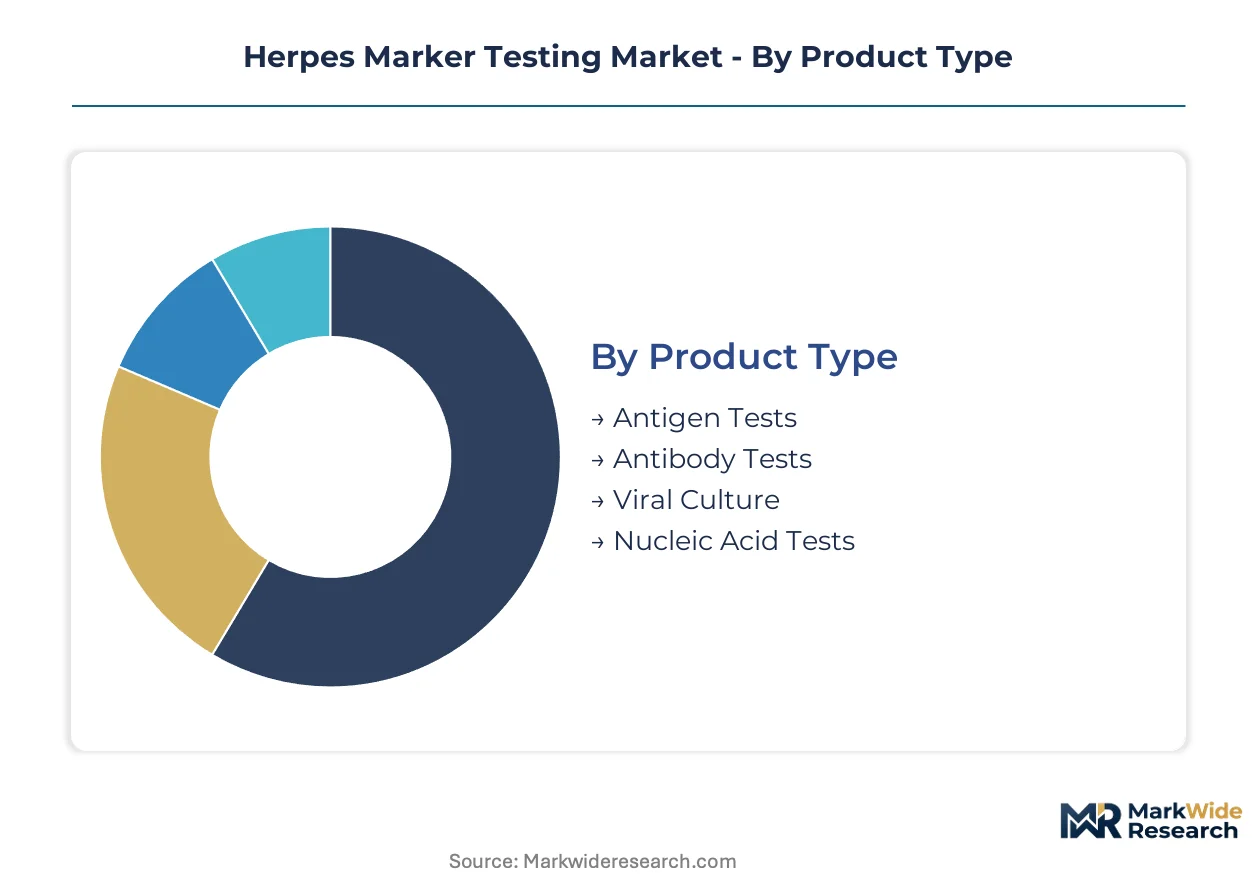
Herpes marker testing segments fragment across diagnostic modalities with starkly different service intensity profiles. Platform stickiness, reagent contract structures, and regulatory compliance burdens vary dramatically by product category, reshaping vendor-customer relationships and margin architectures across the value chain.
Product Type:
After-sales-service intensity diverges sharply across diagnostic modalities, with nucleic acid platforms demanding continuous technical support while serology formats operate with minimal vendor intervention.
- Nucleic Acid Tests:Real-time and digital PCR platforms detect HSV-1/HSV-2 DNA with analytical sensitivity thresholds critical for neonatal encephalitis and CNS infection diagnosis. Demand concentrates in United States reference laboratory networks where high-throughput automation justifies capital investment and specialized molecular diagnostics technologist staffing.
- Antibody Tests:ELISA and lateral flow immunoassays identify IgG and IgM seroconversion patterns for population screening and exposure history documentation. Volume leadership belongs to developing-market public health programs and United States occupational health screening where per-test cost minimization overrides sensitivity requirements.
- Antigen Tests:Direct viral protein detection from lesion swabs offers rapid turnaround without amplification infrastructure.
- Viral Culture:Traditional cell-based isolation methods retain niche utility for antiviral susceptibility testing in specialized reference centers.
By volume, Antibody Tests leads. By growth pace, Nucleic Acid Tests is expanding most quickly.
End User:
Customer concentration patterns shape procurement leverage, with consolidated laboratory networks extracting favorable reagent pricing against fragmented clinic purchasing.
- Diagnostic Laboratories:Centralized high-throughput facilities process thousands of HSV specimens daily through integrated molecular diagnostics menus spanning respiratory, STI, and encephalitis panels. United States national laboratory chains dominate nucleic acid test volume through multi-year exclusive platform contracts.
- Hospitals:Tertiary care centers with in-house molecular diagnostics capacity prioritize STAT turnaround for emergency department encephalitis rule-out and maternal-fetal medicine intrapartum screening protocols.
- Clinics:Physician office laboratories with CLIA moderate-complexity certification increasingly adopt sample-to-answer platforms for same-day symptomatic patient management.
- Home Care Settings:Self-collection kits with telehealth-integrated result delivery unlock asymptomatic screening demand from populations avoiding clinical encounters.
Diagnostic Laboratories command the highest absolute throughput. Home Care Settings is gaining share fastest.
Technology:
Capital intensity and workflow integration requirements stratify technology adoption across laboratory tiers and geographic markets.
- PCR:Real-time amplification with probe-based detection dominates reference laboratory HSV testing through superior sensitivity in cerebrospinal fluid and neonatal specimens. United States health system consolidation favors vendors offering unified infectious disease menus across respiratory, STI, and CNS applications.
- ELISA:Enzyme-linked immunosorbent assays for IgG/IgM detection sustain volume leadership in seroprevalence studies and blood donor screening where cost-per-test minimization outweighs turnaround requirements.
- Rapid Testing:Lateral flow immunochromatography enables point-of-care deployment without laboratory infrastructure.
- Immunofluorescence:Direct fluorescent antibody staining retains specialized application for lesion direct examination in dermatopathology reference settings.
PCR leads by revenue concentration. Rapid Testing shows the steepest expansion trajectory in retail clinic channels.
Application:
Reimbursement granularity and clinical utility evidence requirements segment demand by use case urgency and regulatory scrutiny intensity.
- Diagnosis:Acute infection confirmation from active lesions, cerebrospinal fluid, or neonatal specimens demands highest analytical sensitivity and drives nucleic acid test premium positioning. United States tertiary care centers mandate PCR-based protocols for suspected HSV encephalitis.
- Screening:Asymptomatic population testing for HSV-2 seroprevalence concentrates in public health programs and prenatal care protocols where antibody test cost efficiency outweighs sensitivity limitations.
- Monitoring:Viral load quantification in immunocompromised transplant recipients requires quantitative PCR or emerging digital PCR platforms.
- Research:Epidemiological studies and vaccine development programs generate specialized demand for multiplexed serological panels and sequencing-based strain differentiation.
Diagnosis commands the highest per-test value. Screening dominates by absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports PCR reagent systems to United States reference laboratories, anchoring transatlantic trade flows in molecular diagnostics infrastructure. This corridor shapes procurement patterns across high-throughput screening networks.
United States
Three national laboratory chains control the majority of nucleic acid test throughput through multi-year exclusive platform contracts. FDA CLIA complexity classifications determine which physician office laboratories can operate moderate-complexity HSV assays. The Boston-Cambridge biotech corridor concentrates digital PCR development activity for transplant viral load monitoring applications.
Germany
Specialized molecular diagnostics manufacturers supply automated sample-to-answer platforms to European hospital networks. EU MDR notified body bottlenecks extend HSV assay approval timelines and force prioritization of high-volume infectious disease panels. The Munich-Stuttgart industrial belt hosts precision engineering clusters producing thermal cycling instrumentation for PCR workflows.
China
Domestic IVD manufacturers scale production of real-time PCR platforms for hospital laboratory networks. NMPA regulatory pathways for Class III medical devices impose clinical trial requirements on novel HSV detection technologies. The Yangtze River Delta biotech zone concentrates reagent manufacturing capacity serving Asia-Pacific distribution channels.
Japan
PMDA quality management system inspections enforce stringent manufacturing standards for HSV diagnostic kits. METI industrial policy supports point-of-care molecular diagnostics development for aging population healthcare access. The Kansai region Osaka-Kobe medical device cluster specializes in miniaturized amplification instrumentation.
India
CDSCO medical device rules classify HSV assays by risk tier, determining registration pathway complexity for imported platforms. CDSCO's phased implementation of IVD-specific regulations creates transition uncertainty for multinational reagent suppliers. The Hyderabad-Genome Valley biotech corridor attracts contract research organizations conducting clinical validation studies for regional market entry.
Herpes Marker Testing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors with extensive infectious disease menus rather than standalone HSV assay specialists. Large diversified diagnostics corporations anchor the premium tier through multi-year hospital system contracts. Mid-scale reagent suppliers occupy a cost-competitive position in high-volume serology segments. Dominant competitive moves include strategic partnerships for sample-to-answer workflow integration and portfolio diversification into multiplex respiratory and STI panels.
Within the integrated platform tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd. exemplify vendors embedding herpes assays within broader molecular diagnostics menus. Thermo Fisher Scientific occupies a position spanning research-grade reagents and clinical applications. These three corporations represent the concentration of installed base advantages in high-throughput laboratory networks.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd. |
| DiaSorin S.p.A. |
| BioMérieux SA |
| Quidel Corporation |
| Abcam Plc |
| Qiagen N.V. |
| Meridian Bioscience |
| Others |
Supply & Pricing Matrix
German precision engineering clusters in the Munich-Stuttgart corridor anchor thermal cycling instrumentation manufacturing, concentrating upstream margin capture for PCR platform vendors while downstream reagent suppliers face commoditization pressure in high-volume serology segments.
Pricing Analysis
Real-time PCR platforms command three-tier pricing structure across premium, standard, and economy levels based on throughput capacity and automation integration, while legacy ELISA formats compete on per-test cost minimization. Price differentiation hinges on FDA premarket authorization tier and health system contract volume scale. Cost compression in antibody testing intensifies as lateral flow alternatives match ELISA sensitivity thresholds for routine screening. Public health programs in developing markets exhibit highest price sensitivity; tertiary care centers with neonatal encephalitis protocols demonstrate lowest sensitivity due to clinical specificity requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for thermal cycling instrumentation and proprietary master mix formulations. Manufacturing concentrates in Germany, the United States, and China for PCR platforms; reagent production clusters in the Yangtze River Delta and North American contract manufacturers. Taq polymerase supply rests on a narrow supplier base vulnerable to single-source disruption. Distribution runs through consolidated laboratory networks with multi-year exclusive platform contracts rather than fragmented clinic purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiplex PCR automation is disrupting herpes marker testing workflows, with FDA CLIA complexity reclassification creating a regulatory inflection that decentralizes diagnostic capacity beyond centralized hospital laboratories.
For Market Incumbents: Build installed base stickiness through unified infectious disease menus spanning respiratory, STI, and CNS applications rather than standalone HSV assays. Anchor multi-year exclusive platform contracts with United States national laboratory chains to defend against sample-to-answer entrants targeting physician office laboratories. Deepen backward integration into Taq polymerase production to secure reagent supply continuity amid contract manufacturer concentration. For New Entrants and Emerging Players: Establish a beachhead in CLIA-waived point-of-care channels serving retail clinic networks with same-day symptomatic patient management protocols. Target pharmacy channel expansion in the United States where CLIA moderate-complexity certification unlocks decentralized testing demand. Pursue telehealth-integrated self-collection kits with regulatory clearance for asymptomatic screening populations avoiding clinical encounters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital PCR development as miniaturized amplification instrumentation reduces thermal cycling infrastructure requirements. Prioritize acquisition targets with proprietary isothermal amplification technologies hybridizing CRISPR detection for resource-limited laboratory deployment. Monitor EU MDR notified body capacity constraints as a signal for European market entry timing and portfolio prioritization toward high-volume infectious disease panels.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Panel Integration | Abbott Laboratories embeds HSV assays within broader infectious disease menus to sustain platform stickiness. |
| Sample-to-Answer Platform Launch | Thermo Fisher Scientific compresses turnaround times from days to hours through automated workflow integration. |
| Digital PCR Differentiation | F. Hoffmann-La Roche Ltd. addresses viral load monitoring needs in immunocompromised transplant populations. |
| Self-Collection Regulatory Clearance | Home-based specimen kits with telehealth integration unlock demand from asymptomatic screening populations. |
| PEPFAR Laboratory Network Expansion | Sub-Saharan Africa molecular diagnostics infrastructure creates installed base potential for HSV-2 screening integration. |
Research Methodology
A standing panel of molecular diagnostics laboratory directors, FDA regulatory affairs specialists, hospital procurement committee members, and GPO contracts managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, hospital procurement databases, and CLIA complexity classification records. Bottom-up test volume modeling triangulated against top-down market sizing from platform installed base estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning diagnostic modality, end-user facility type, technology generation, and application urgency. CAGRs derived from test volume elasticity to reimbursement granularity and platform replacement cycles. Forecast inputs incorporated CLIA complexity reclassification timelines and EU MDR notified body capacity constraints.
Sensitivities concentrate around payer coverage decisions for multiplex panels versus standalone HSV tests, reagent supply disruption from contract manufacturer concentration, and molecular diagnostics technologist shortage constraints on laboratory expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Clinical Diagnostics Market