
 Cephalic Disorders Treatment Market | 2026-2036
Cephalic Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cephalic Disorders Treatment Market Analytics
Biologics are repositioning small-molecule neuropharmacology in cephalic disorder protocols. Medtronic Plc leverages its neuromodulation platform to anchor deep-brain stimulation applications for refractory cephalic conditions. AbbVie Inc. competes through immunology-derived biologic pipelines now explored for neuroinflammatory components of cranial malformations.
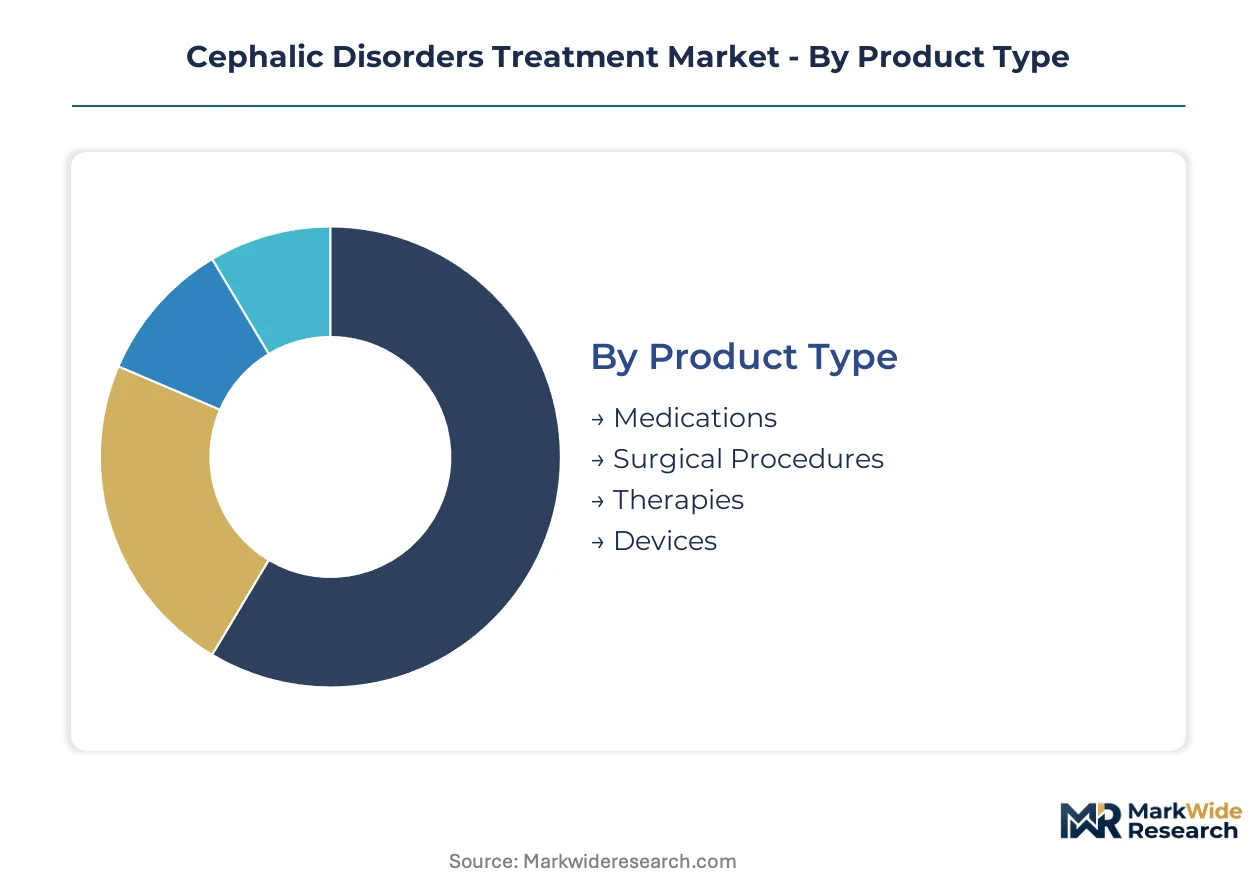
Cephalic disorders treatment encompasses interventions for congenital structural abnormalities of the head, brain, and cranial nerves, requiring multidisciplinary coordination across neurosurgery, genetics, and rehabilitative medicine. The field employs advanced imaging-guided surgical planning, targeted drug delivery across the blood-brain barrier, and customized cranial orthotic devices to manage intracranial pressure and support neurodevelopmental outcomes. Medications and devices together capture the dominant value share, with pharmacological segments drawing biologic investment while surgical procedures command premium reimbursement tied to specialized operative complexity. Home care delivery is expanding fastest among end-user categories as remote monitoring technologies enable post-surgical recovery and chronic management outside institutional settings.
FDA orphan drug incentives and EMA's paediatric investigation plans shape clinical trial investment and pediatric indication prioritization for developers. ISO 13485 quality management standards and MDR CE marking requirements govern device commercialization pathways across major markets, with notified body capacity constraining European market entry timelines. Stakeholders must track regulatory convergence on real-world evidence requirements for rare disease therapies, as payer acceptance of non-randomized data will determine reimbursement velocity for novel cephalic interventions.
Market Dynamics
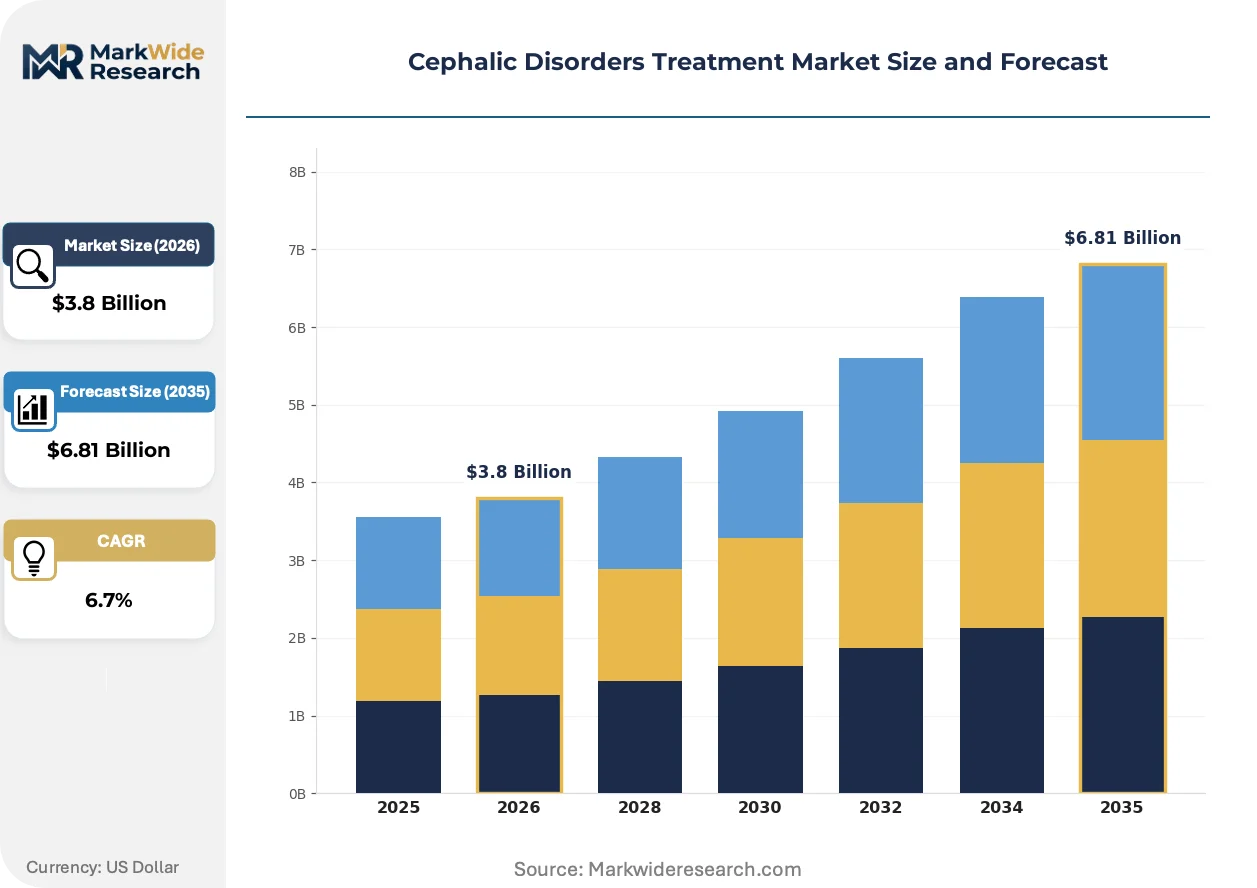
FDA orphan drug incentives and EMA paediatric investigation plans are redirecting clinical trial investment toward rare congenital conditions, while tertiary hospital consolidation concentrates specialized craniofacial surgical capacity in academic medical centers.
Growth Catalysts
- Orphan Drug Designation:FDA's accelerated approval pathway for rare diseases compresses development timelines for novel cephalic therapeutics. Pediatric neurologists gain earlier access to investigational compounds.
- Neuromodulation Platform Extension:Deep-brain stimulation hardware originally developed for movement disorders now anchors refractory cephalic condition protocols. Neurosurgical departments expand implantable device programs.
- Home Care Infrastructure:Remote intracranial pressure monitoring systems enable post-operative recovery outside hospital settings. Home health agencies build cranial orthotic fitting capabilities.
Market Restraints
- Notified Body Capacity Constraints:MDR CE marking backlogs in Europe delay cranial device commercialization. European market entry timelines extend substantially.
- Biologic Manufacturing Complexity:Blood-brain barrier targeting requires specialized formulation infrastructure. Contract development organizations with CNS expertise command premium pricing.
- Surgical Workforce Concentration:Pediatric craniofacial neurosurgeons cluster at select academic institutions. Community hospitals lack operative volume to sustain specialized programs.
Strategic Opportunities
- Real-World Evidence Pathways:Payer acceptance of non-randomized data for rare diseases creates reimbursement velocity for novel interventions. Regulators converge on pragmatic trial designs.
- Telemedicine Integration:Remote cranial imaging review connects rural patients to specialized centers. Teleradiology platforms expand into surgical planning consultation.
- Gene Therapy Convergence:Viral vector delivery systems combine with in-utero diagnostic advances. Fetal intervention programs at select institutions explore early correction protocols.
Industry Challenges
- Multidisciplinary Coordination Complexity:Craniofacial programs require synchronized neurosurgery, genetics, and rehabilitation medicine workflows. Electronic health record interoperability gaps fragment care coordination.
- ISO 13485 Certification Burden:Custom cranial orthotic manufacturers face quality management system implementation costs. Small device workshops struggle with notified body audit requirements.
- Reimbursement Coding Fragmentation:Surgical procedures for congenital cranial malformations span multiple billing categories. Payer prior authorization processes create administrative friction for novel interventions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cephalic Disorders Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
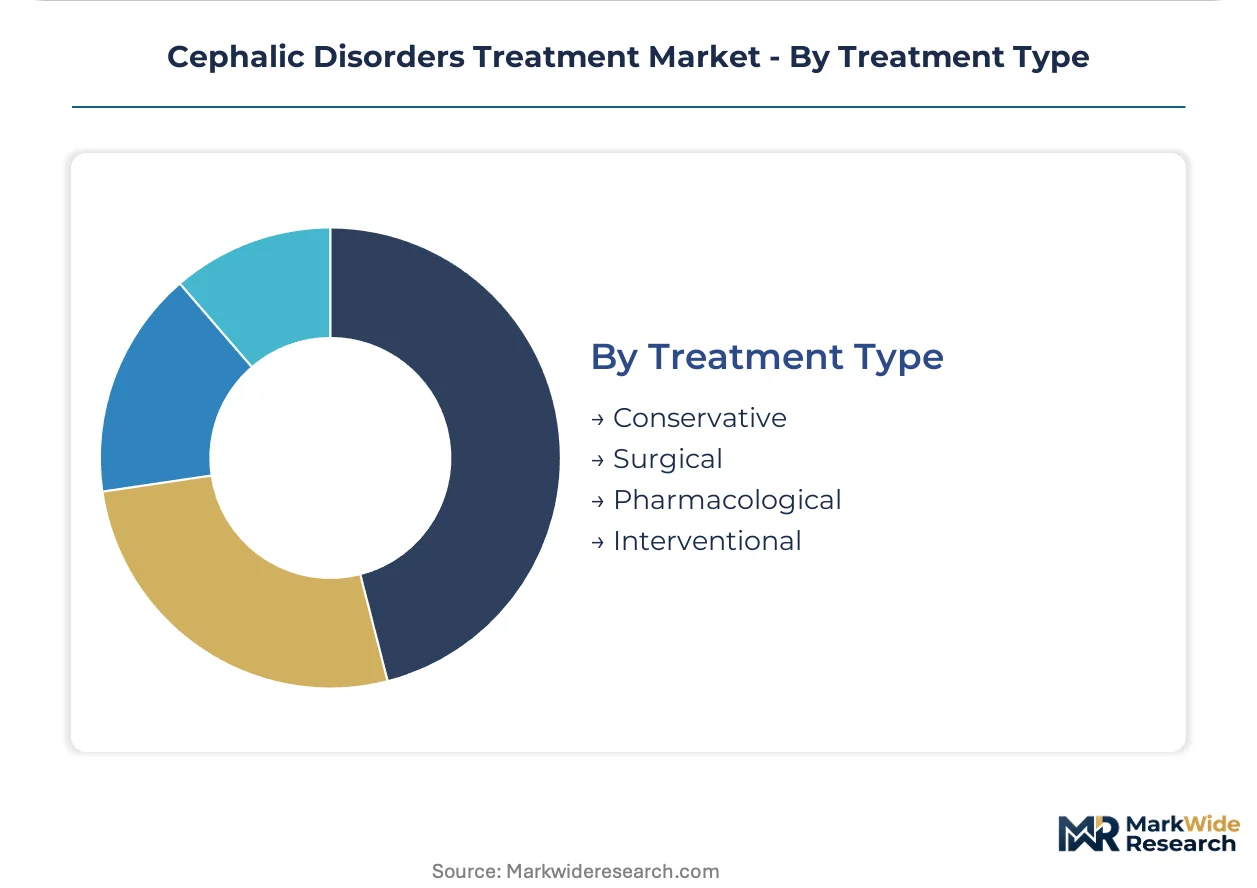
| Segmentation | Product Type: Medications, Surgical Procedures, Therapies, Devices End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Injectable, Intranasal, Topical Treatment Type: Conservative, Surgical, Pharmacological, Interventional |
| Companies Covered | Sonova Holding AG, Widex A/S, Oticon, Abbott Laboratories, Merz GmbH & Co. KGaA, AbbVie Inc., Teva Pharmaceutical Industries Ltd., Medtronic Plc, Integra Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cephalic Disorders Treatment Market Evolving Landscape
Advanced imaging-guided surgical planning is compressing operative timelines and improving neurodevelopmental outcomes. Three distinct shifts are restructuring how cephalic disorders are diagnosed, treated, and managed across care settings.
Intraoperative magnetic resonance imaging is overtaking conventional neuronavigation for complex cranial reconstructions. Pediatric neurosurgical departments at Boston Children's Hospital and Great Ormond Street Hospital deploy real-time imaging to verify anatomical corrections before closing. This capability is compressing revision surgery rates and shortening total operative sequences for severe craniosynostosis cases.
EMA's paediatric investigation plan mandates now require juvenile toxicity studies for all novel CNS-active compounds. Drug developers must submit pediatric study plans before adult indication approval, redirecting early-phase investment toward age-appropriate formulations. Biologic manufacturers with immunology pipelines are prioritizing neuroinflammatory mechanism exploration to satisfy these regulatory requirements.
Hospital-at-home programs for post-surgical cranial patients are displacing extended institutional recovery. Home health agencies in the United States deploy wearable intracranial pressure monitors and video-based neurological assessments. This model reduces readmission exposure while expanding geographic access to specialized follow-up care for families distant from academic medical centers.
Cephalic Disorders Treatment Market Segmentation
Cephalic disorder treatment protocols demand precise patient stratification across intervention intensity, care setting, and pharmacological delivery. Segmentation reveals where clinical workflows fragment and where integrated care models capture premium reimbursement.
Product Type:
Replacement cycles for implantable cranial devices and biologic formulation upgrades drive portfolio rebalancing across product categories.
- Medications:Small-molecule neuropharmacology and blood-brain barrier-targeted biologics address intracranial pressure modulation and neuroinflammatory components. Demand clusters at pediatric neurology departments within tertiary academic centers where FDA orphan drug incentives accelerate formulary adoption.
- Surgical Procedures:Cranial vault reconstruction, craniosynostosis correction, and decompressive craniectomy require specialized operative infrastructure. Reimbursement concentrates at designated craniofacial centers where case volume thresholds justify dedicated neurosurgical teams.
- Therapies:Neurodevelopmental rehabilitation and cranial orthotic fitting programs support post-surgical functional recovery.
- Devices:Intracranial pressure monitors, programmable shunt systems, and neuromodulation hardware enable chronic condition management.
Volume placements concentrate in Surgical Procedures; the faster expansion belongs to Devices.
End User:
Care site selection hinges on procedural complexity thresholds and remote monitoring technology maturity.
- Hospitals:Tertiary academic medical centers house the specialized neurosurgical suites and intraoperative imaging capabilities required for complex cranial reconstructions. Boston Children's Hospital and Great Ormond Street Hospital anchor referral networks spanning multiple states and nations.
- Home Care:Wearable intracranial pressure monitors and video-based neurological assessments now enable post-operative recovery outside institutional walls. Rural families distant from craniofacial centers drive adoption of hospital-at-home program expansion.
- Clinics:Outpatient settings handle stable chronic management and pre-operative consultation workflows.
- Rehabilitation Centers:Dedicated facilities coordinate neurodevelopmental therapy and cranial orthotic adjustment protocols.
Revenue gravity rests with Hospitals; Home Care is climbing the fastest.
Delivery Mode:
Formulation innovation and blood-brain barrier engineering reshape administration route economics.
- Injectable:Intravenous and intrathecal delivery enables precise cerebrospinal fluid concentration targeting for neuroactive compounds. Specialized infusion centers at academic medical institutions manage complex biologic administration protocols.
- Intranasal:Olfactory nerve pathway exploitation permits direct CNS access bypassing hepatic first-pass metabolism. Pediatric formulation developers prioritize this route for age-appropriate drug delivery where oral compliance proves challenging.
- Oral:Tablet and liquid formulations remain standard for chronic maintenance pharmacotherapy.
- Topical:Transdermal patches and scalp-applied agents address localized cranial conditions.
Injectable dominates current prescribing patterns; Intranasal formulations are gaining share fastest.
Treatment Type:
Clinical decision pathways stratify patients by malformation severity, age at presentation, and comorbidity burden.
- Surgical:Cranial vault expansion, craniofacial reconstruction, and implantable device placement demand multidisciplinary operative teams. Real-time intraoperative MRI verification at specialized centers compresses revision rates for severe craniosynostosis cases.
- Interventional:Minimally invasive endoscopic techniques and image-guided catheter procedures reduce operative trauma. Fetal intervention programs at select institutions explore in-utero correction protocols leveraging advancing prenatal diagnostic capabilities.
- Conservative:Observation protocols and cranial orthotic positioning address mild positional deformities.
- Pharmacological:Medical management targets intracranial hypertension and neuroinflammatory sequelae.
Surgical interventions capture the premium reimbursement tier; Interventional approaches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized craniofacial centers cluster around major academic medical institutions in the United States, where tertiary hospital consolidation and FDA orphan drug incentives concentrate advanced treatment capacity. Pediatric neurology departments at these centers anchor referral networks that draw patients from distant geographies, creating pronounced demand concentration in select metropolitan markets.
United States
Boston Children's Hospital and Children's Hospital of Philadelphia anchor the nation's largest craniofacial surgical programs, drawing interstate referral volumes. FDA orphan drug designation accelerates novel therapeutic development timelines for rare congenital conditions. The Greater Boston and Philadelphia metropolitan areas concentrate intraoperative MRI capabilities and dedicated pediatric neurosurgical suites.
Germany
University hospitals in Heidelberg and Munich maintain Europe's highest-volume craniosynostosis correction programs, serving cross-border patient flows from neighboring countries. EMA paediatric investigation plans mandate juvenile toxicity studies for CNS-active compounds, redirecting clinical trial investment toward pediatric formulations. The Baden-Württemberg and Bavaria regions cluster notified body-certified cranial device manufacturers.
United Kingdom
Great Ormond Street Hospital in London operates one of Europe's largest dedicated craniofacial units, with real-time intraoperative imaging capabilities. MHRA alignment with EMA pediatric regulatory pathways streamlines orphan drug market access. The Greater London area concentrates specialized rehabilitation medicine capacity for post-surgical neurodevelopmental support.
Switzerland
University Hospital Zurich and Geneva University Hospital coordinate multidisciplinary craniofacial programs serving alpine region patient populations. Swissmedic maintains accelerated review pathways for pediatric orphan indications, complementing EMA centralized procedures. The Zurich and Geneva metropolitan areas host precision manufacturing clusters for custom cranial orthotic devices.
Japan
National Center for Child Health and Development in Tokyo anchors domestic craniofacial surgical capacity, with regional hub hospitals in Osaka and Nagoya extending geographic access. PMDA's sakigake designation system provides priority review for innovative pediatric therapies. The Kanto and Kansai metropolitan regions concentrate pediatric neurology subspecialty training programs.
Cephalic Disorders Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as device manufacturers extend neuromodulation platforms into pediatric applications and pharmaceutical developers explore immunology-derived pipelines for neuroinflammatory components. The market structure reflects moderate consolidation around integrated medtech-pharma conglomerates with dedicated rare disease divisions, alongside specialized orthopedic and neurosurgical device workshops. Three strategic archetypes occupy distinct positions: diversified medtech conglomerates with neuromodulation hardware platforms, biologic manufacturers with blood-brain barrier targeting capabilities, and specialized cranial device fabricators with ISO 13485 certification. M&A activity and strategic partnerships concentrate competitive moves, with larger entities acquiring boutique orthotic manufacturers to secure custom device capabilities.
Within the diversified medtech tier, Medtronic Plc and Abbott Laboratories exemplify platform extension strategies, leveraging implantable device expertise developed in adjacent neurology indications. AbbVie Inc. occupies a position among biologic developers repurposing immunology pipelines for neuroinflammatory mechanism exploration. Among specialized device manufacturers, Integra Lifesciences represents the dedicated cranial reconstruction and orthotic fabrication archetype, while Sonova Holding AG and Widex A/S exemplify hearing technology specialists with adjacent cranial nerve intervention capabilities. Teva Pharmaceutical Industries Ltd. and Merz GmbH & Co. KGaA sit within the generic and specialty pharmaceutical tier, supplying established small-molecule neuropharmacology for chronic intracranial pressure management.
| Leading Market Players |
|---|
| Sonova Holding AG |
| Widex A/S |
| Oticon |
| Abbott Laboratories |
| Merz GmbH & Co. KGaA |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Medtronic Plc |
| Integra Lifesciences |
| Others |
Value Network & Pricing Analysis
Pediatric craniofacial neurosurgeon concentration at select United States academic medical centers compresses labor supply, driving wage premiums that widen pricing spreads between community hospital referrals and tertiary center direct admissions. This workforce scarcity in Boston and Philadelphia anchors premium reimbursement tiers while remote monitoring technologies enable cost-competitive home care alternatives.
Pricing Analysis
High-volume surgical procedures at designated craniofacial centers capture margin premiums through case complexity bundling, while chronic device management and pharmacotherapy segments compete on scale economics. Price differentiation hinges on FDA orphan drug designation tier and ISO 13485 certification status, with biologic formulations commanding substantial premiums over small-molecule alternatives. Cost compression in standard cranial orthotic manufacturing intensifies as notified body audit requirements consolidate supplier bases. Academic medical center procurement committees exhibit lowest price sensitivity given outcome-based reimbursement structures, whereas home health agencies face acute budget constraints driving generic preference.
Supply Chain Analysis
Biologic active pharmaceutical ingredient supply rests on specialized contract development organizations with blood-brain barrier formulation expertise concentrated in the United States, Germany, and Switzerland. Custom cranial orthotic fabrication draws from medical-grade polymer feedstocks and precision milling equipment, with titanium implantable hardware sourcing from Swiss and German precision manufacturers. Single-source vulnerability pervades neuromodulation device componentry, where proprietary electrode arrays lack qualified secondary suppliers. Distribution runs through GPO-negotiated hospital contracts for institutional segments, while direct-to-patient channels serve expanding home care orthotic fitting requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cephalic disorders treatment sector sits at a technology-transition inflection, with real-time intraoperative MRI verification displacing conventional neuronavigation as the standard of care for complex cranial reconstructions.
For Market Incumbents: Cement platform dominance by acquiring boutique ISO 13485-certified orthotic manufacturers to secure custom device capabilities and capture margin pool expansion. Expand neuromodulation hardware pediatric indication portfolios through FDA orphan drug pathway alignment, defending against biologic developers encroaching on neuroinflammatory mechanism territories. Prioritize backward integration into blood-brain barrier targeting formulation infrastructure to reduce reliance on premium-priced contract development organizations. For New Entrants and Emerging Players: FDA's accelerated approval pathway for rare diseases opens a window for gene therapy developers to establish fetal intervention program partnerships at select academic medical centers. Target home care delivery infrastructure gaps in rural geographies distant from Boston and Philadelphia referral hubs, where remote intracranial pressure monitoring adoption outpaces service provision. Pursue telemedicine-integrated teleradiology platforms as the go-to-market angle, connecting community hospitals to specialized surgical planning consultation. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cranial device fabricators possessing notified body certification and custom orthotic capabilities given consolidation momentum among diversified medtech conglomerates. The five-to-ten year viability window favors platforms spanning both implantable hardware and biologic delivery modalities. Watch EMA paediatric investigation plan enforcement patterns as the signal for pediatric formulation investment velocity and early-phase clinical trial location decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated approval compresses development timelines for novel cephalic therapeutics. |
| Intraoperative MRI Capability Deployment | Real-time imaging verification at Boston Children's Hospital and Great Ormond Street Hospital reduces revision rates. |
| Home Care Infrastructure Buildout | Wearable intracranial pressure monitors enable post-surgical recovery outside institutional settings. |
| ISO 13485 Certification Investment | Quality management system compliance secures European market access amid notified body capacity constraints. |
| Telemedicine Platform Integration | Remote cranial imaging review expands geographic access to specialized surgical planning consultation. |
Research Methodology
Multi-period observation of FDA orphan drug designations, EMA paediatric investigation plan submissions, and tertiary hospital craniofacial program expansions anchored the trend analysis, supplemented by interviews with pediatric neurosurgeons, regulatory affairs specialists at biologic manufacturers, hospital procurement managers, and home health agency operations directors. Secondary validation drew from FDA 510(k) and PMA filings, EMA centralized procedure outcomes, ClinicalTrials.gov pediatric CNS intervention records, and CMS Medicare reimbursement database extracts. Bottom-up procedure volume modeling and top-down pharmaceutical expenditure estimates underwent iterative reconciliation.
Input-output matrices structured demand forecasting across treatment type, product category, delivery mode, and care setting dimensions throughout the projection horizon. CAGRs were derived from segmented growth rate blending weighted by current revenue contribution. Forecast inputs incorporated intraoperative imaging adoption curves, blood-brain barrier targeting formulation pipeline progression, and home care regulatory reimbursement pathway evolution.
The model assumes a particular technology adoption path for real-time intraoperative MRI verification; alternative pathways for image-guided catheter-based interventions would alter the outlook for surgical procedure volume distribution. Forecasts reflect embedded assumptions regarding FDA orphan drug incentive continuity and EMA pediatric regulatory alignment. A small set of triggers—PMDA sakigake designation expansion, Swissmedic accelerated review pathway harmonization, and notified body capacity resolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Microwave Ablation Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market