
 Global Total Ankle Replacement Market | 2026-2036
Global Total Ankle Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Total Ankle Replacement Market Foresight
European implant manufacturers is pivoting toward cobalt-chromium and titanium alloy production to secure raw material access for total ankle replacement systems. Zimmer Biomet Holdings, Inc. anchors its position through proprietary mobile-bearing designs that reduce polyethylene wear rates. Stryker Corporation leverages integrated instrumentation platforms to streamline surgical workflows in high-volume orthopedic centers. Smith + Nephew differentiates via porous coating technologies that accelerate osseointegration timelines.
Total ankle replacement refers to the surgical implantation of artificial tibial and talar components to restore joint function in patients with end-stage ankle arthritis, typically using cobalt-chromium molybdenum alloy tibial trays and ultra-high molecular weight polyethylene inserts with thicknesses ranging from 6 to 15 millimeters. Its primary purpose is to preserve ankle motion and reduce adjacent joint stress compared to ankle arthrodesis. Fixed-bearing implants dominate current surgical volumes due to established long-term survivorship data and simpler instrumentation requirements. Mobile-bearing designs represent the fastest-expanding category as surgeons seek to minimize polyethylene wear debris and improve gait kinematics. Cementless fixation with hydroxyapatite coating captures premium pricing positions by promising faster bone ingrowth and reduced revision rates.
FDA 510(k) premarket notification pathways govern United States market entry, while EU MDR conformity assessment procedures and CE marking requirements determine European commercialization timelines for total ankle replacement systems. Japan's PMDA and Japan's MHLW enforce distinct clinical trial and quality management standards that shape regional product availability. Stakeholders must monitor evolving reimbursement thresholds for outpatient surgical procedures and track orthopedic surgeon training program expansion as decisive variables for implant penetration rates.
Market Dynamics
Mobile-bearing implant designs are compressing polyethylene wear rates and accelerating surgeon migration from fixed-bearing systems, reshaping competitive positioning across high-volume orthopedic centers in Germany, the United States, and Japan.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Accelerated premarket notification reviews in the United States reduce commercialization timelines for next-generation implant systems. Orthopedic manufacturers leverage this regulatory efficiency to compress product-to-market cycles.
- Cobalt-Chromium Molybdenum Alloys:European raw material suppliers are securing dedicated production lines for implant-grade metals. This supply assurance supports volume scaling for tibial tray manufacturing.
- Aging Surgical Demographics:Patient populations over 65 in Japan and Germany present expanding addressable pools for motion-preserving procedures. Ankle arthrodesis alternatives face displacement pressure from joint replacement demand.
Market Restraints
- EU MDR Conformity Costs:Enhanced clinical evidence requirements and notified body capacity constraints extend European certification timelines. Small and mid-sized manufacturers face disproportionate compliance burdens.
- Polyethylene Insert Supply Concentration:Ultra-high molecular weight polyethylene production concentrates among specialized polymer processors. Input cost volatility transmits directly to implant pricing structures.
- Ankle Arthrodesis Substitution:Fusion procedures retain preference among rural surgeons and cost-sensitive payers. Simpler instrumentation and established reimbursement codes sustain this competitive alternative.
Strategic Opportunities
- Outpatient Surgical Migration:Ambulatory surgery centers in the United States seek compact instrumentation platforms. Manufacturers bundling disposable trial components capture this channel expansion.
- Hydroxyapatite Coating Penetration:Cementless fixation systems command premium positioning through accelerated osseointegration claims. Porous titanium surfaces differentiate against conventional cemented alternatives.
- Japan PMDA Parallel Track:Expedited review pathways for orphan device indications create regulatory arbitrage. Early entrants establish clinical data moats before standard pathway competitors.
Industry Challenges
- Orthopedic Surgeon Training Bottlenecks:Fellowship programs produce insufficient ankle replacement specialists to match procedural demand growth. Simulator-based credentialing faces validation gaps against live surgical outcomes.
- Cross-Border CE Marking Transitions:Legacy MDD certificates expire without guaranteed MDR renewal timelines. Inventory positioning and market access continuity require dual-track regulatory investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Total Ankle Replacement Market |
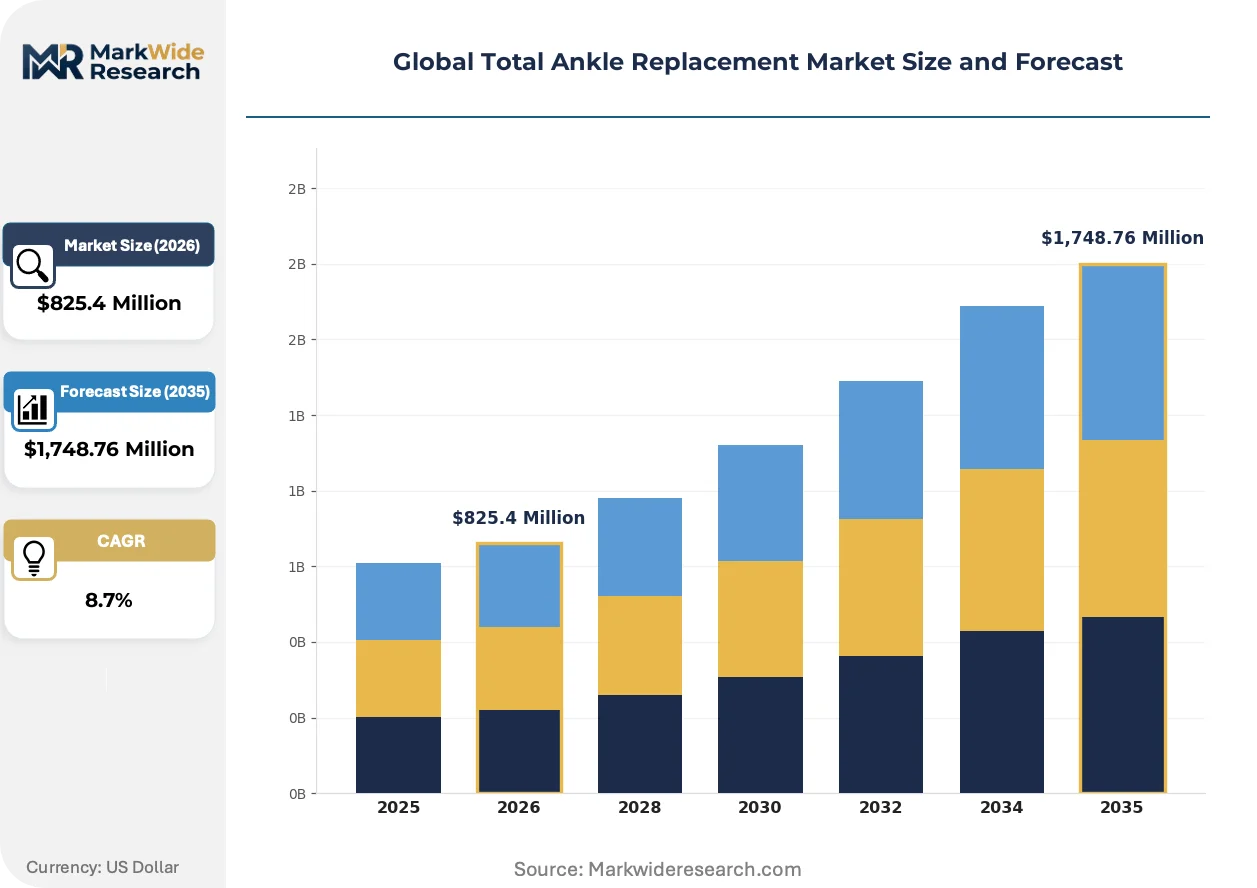
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bearing, Mobile Bearing, Cemented, Cementless Technology: Polyethylene Inserts, Metal Components, Porous Coating, Hydroxyapatite Coating Application: Osteoarthritis, Rheumatoid Arthritis, Post-Traumatic Arthritis, Ankle Fracture End User: Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers, Specialty Hospitals |
| Companies Covered | Exactech, Inc., Integra LifeSciences Corporation, Zimmer Biomet Holdings, Inc., Arthrex, Inc., Enovis Corporation, Stryker Corporation, Smith + Nephew, DePuy Synthes, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Total Ankle Replacement Market Shifts & Advancements
Three interconnected developments are restructuring total ankle replacement value chains: bearing surface materials evolution, regulatory evidence requirements intensification, and procurement centralization among integrated delivery networks.
Polyethylene cross-linking technologies are electrifying wear-resistance benchmarks in mobile-bearing inserts. High-volume orthopedic centers in Germany and the United States prioritize these advanced materials for younger, active patient cohorts. The technology is compressing revision rate differentials between fixed and mobile-bearing designs.
EU MDR post-market surveillance mandates now require systematic implant registry participation and periodic safety update reports. Manufacturers must restructure quality management systems to capture real-world performance data across distributed hospital networks. European commercialization strategies now embed registry infrastructure costs into pricing models.
Integrated delivery networks in the United States are consolidating implant procurement under value-analysis committees. Surgeon preference cards face standardization pressure as health systems negotiate volume-based implant agreements. This behavioral shift concentrates purchasing power among fewer decision-makers in metropolitan hospital clusters.
Global Total Ankle Replacement Market Segmentation
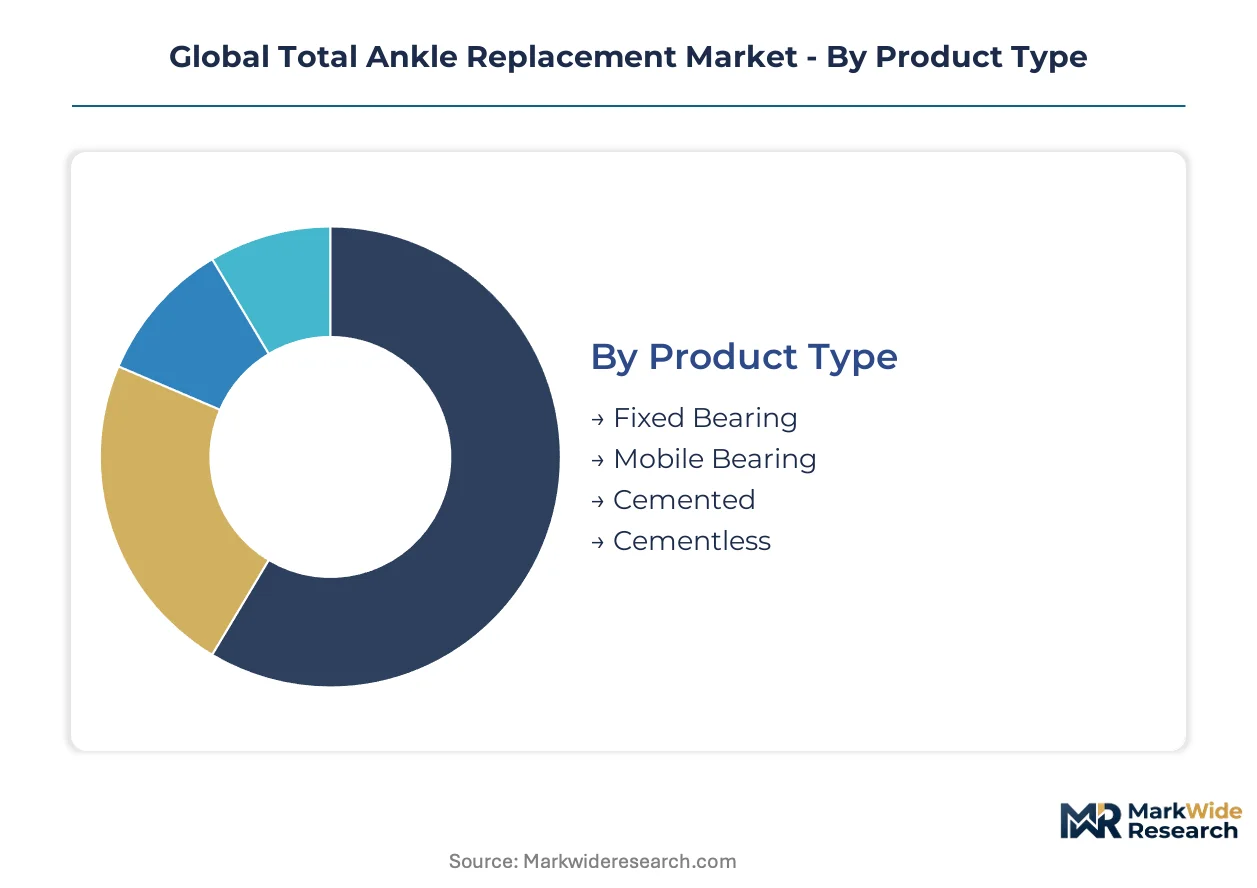
Total ankle replacement segmentation reveals how implant design choices, material specifications, and care delivery settings interact to determine patient outcomes and manufacturer revenue concentration. Surgeons select bearing configurations and fixation methods based on bone quality, activity level, and institutional instrumentation availability.
Product Type:
Upgrade cycles from fixed to mobile-bearing systems are compressing as polyethylene wear data matures and instrumentation platforms standardize across high-volume orthopedic centers.
- Fixed Bearing:Tibial and talar components lock into a single articulating surface with constrained motion paths. Demand concentrates in community hospitals across the United States and Germany where surgeons prioritize established survivorship data over kinematic optimization.
- Mobile Bearing:Unconstrained polyethylene inserts rotate and translate to reduce shear stress at the articulating interface. German and Japanese orthopedic clinics are migrating toward these designs for younger patients seeking preserved range of motion.
- Cemented:Polymethyl methacrylate fixation provides immediate mechanical stability for osteoporotic bone.
- Cementless:Porous or coated surfaces enable biological osseointegration without cement interposition.
Fixed Bearing sits at the top of the volume ranking, with Mobile Bearing climbing the fastest.
Technology:
Material cost tiers separate premium coating technologies from standard metal-polyethylene constructs, with reimbursement differentials determining hospital procurement patterns.
- Polyethylene Inserts:Ultra-high molecular weight polyethylene bearings with cross-linked molecular structures deliver wear rates below 0.1 millimeters per year. United States ambulatory surgery centers specify these inserts for outpatient procedure bundles targeting rapid discharge protocols.
- Metal Components:Cobalt-chromium-molybdenum tibial trays and talar domes provide fatigue resistance exceeding 200 megapascals. German manufacturers secure dedicated alloy supply lines to guarantee production continuity for high-volume implant series.
- Porous Coating:Sintered titanium beads or plasma-sprayed surfaces create 200-400 micrometer pore structures for bone ingrowth.
- Hydroxyapatite Coating:Bioceramic calcium phosphate layers accelerate osteoconduction timelines.
Metal Components dominate procurement volumes, though Hydroxyapatite Coating is gaining share fastest among academic medical centers.
Application:
Patient demographics and disease etiology determine implant selection criteria, with post-traumatic cases requiring more complex revision pathways than primary osteoarthritis presentations.
- Osteoarthritis:Degenerative cartilage loss with subchondral sclerosis and osteophyte formation represents the predominant surgical indication. Japanese orthopedic clinics report expanding surgical volumes among patients over 70 seeking alternatives to ankle arthrodesis.
- Post-Traumatic Arthritis:Accelerated joint degeneration following malleolar or pilon fractures demands specialized implant geometries. United States trauma centers prioritize three-component systems with extended tibial stems for compromised bone stock.
- Rheumatoid Arthritis:Inflammatory synovitis with symmetric joint involvement affects multiple tarsal articulations.
- Ankle Fracture:Acute traumatic disruption requiring immediate joint reconstruction rather than ORIF.
Osteoarthritis accounts for the largest procedure volume, while Post-Traumatic Arthritis shows the steepest expansion trajectory among younger surgical cohorts.
End User:
Procurement authority is shifting toward value-analysis committees as integrated delivery networks consolidate implant purchasing across previously autonomous surgical sites.
- Orthopedic Clinics:Dedicated musculoskeletal facilities with fellowship-trained foot and ankle specialists perform the majority of elective total ankle replacements. German orthopedic clinics in Bavaria and North Rhine-Westphalia anchor regional referral networks for complex revision cases.
- Ambulatory Surgical Centers:Freestanding facilities optimized for same-day discharge are capturing low-complexity primary replacements. United States ASC networks in Texas and Florida negotiate bundled payment rates that favor streamlined instrumentation sets.
- Rehabilitation Centers:Post-acute facilities coordinate prosthetic training and gait reeducation.
- Specialty Hospitals:Orthopedic-focused institutions maintain hybrid operating suites for complex deformity correction.
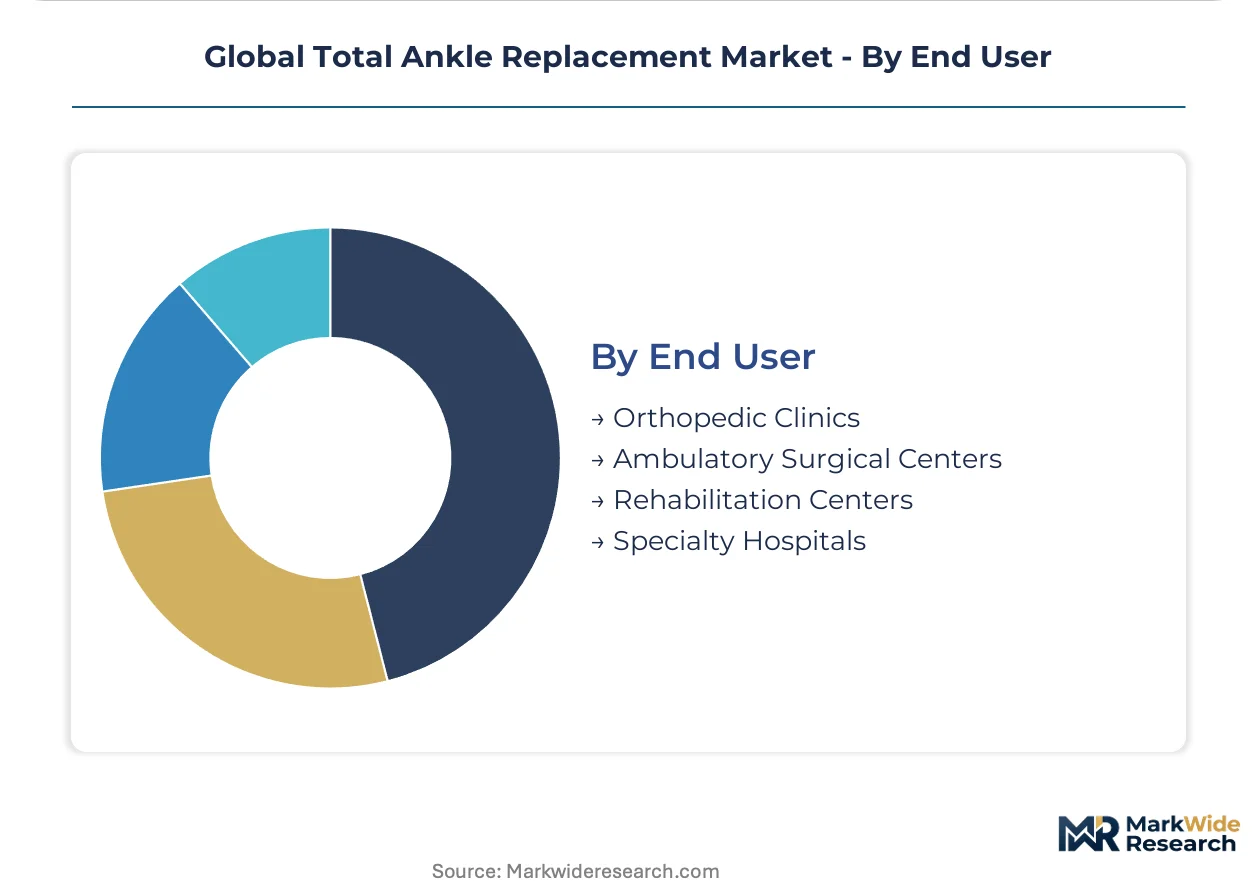
Orthopedic Clinics retain the highest procedure concentration, with Ambulatory Surgical Centers expanding most quickly in United States metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting total ankle replacement manufacturing toward jurisdictions with streamlined medical device pathways. FDA 510(k) premarket notification efficiency in the United States contrasts with EU MDR conformity assessment bottlenecks, creating arbitrage opportunities for implant producers seeking faster commercialization cycles.
United States
Ambulatory surgery centers in Texas and Florida are expanding total ankle replacement volumes through bundled payment contracts. FDA 510(k) pathway streamlining enables faster product-to-market cycles for next-generation mobile-bearing systems. Orthopedic clinics in metropolitan hospital clusters concentrate purchasing authority under value-analysis committees.
Germany
Bavarian and North Rhine-Westphalian orthopedic clinics anchor European referral networks for complex revision procedures. EU MDR conformity requirements and CE marking procedures extend certification timelines for implant manufacturers. Cobalt-chromium alloy suppliers in Baden-Württemberg secure dedicated production lines for tibial tray manufacturing.
Japan
Patients over 70 in Kanto and Kansai regions present expanding addressable pools for motion-preserving alternatives to ankle arthrodesis. PMDA and MHLW enforce distinct clinical trial standards that shape regional product availability. Tokyo-based orthopedic centers prioritize three-component systems with extended tibial stems for compromised bone stock.
United Kingdom
Post-traumatic arthritis cases in London and Southeast England drive demand for specialized implant geometries. MHRA regulations govern market entry following Brexit transition periods. Academic medical centers in the Midlands participate in systematic implant registries mandated by evolving surveillance frameworks.
Switzerland
Swissmedic certification requirements attract premium implant manufacturers seeking high-margin positioning. Zurich and Geneva orthopedic clusters emphasize hydroxyapatite-coated cementless fixation systems. Porous coating technologies command pricing premiums through accelerated osseointegration claims in alpine surgical networks.
Global Total Ankle Replacement Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions through alloy supply security and coating technologies. The vendor base concentrates among diversified orthopedic conglomerates with integrated instrumentation platforms. Three archetypes dominate: scale-driven implant manufacturers with broad foot-and-ankle portfolios, mid-cap specialists focused on bearing surface innovation, and coating technology licensors. Competitive moves center on M&A activity targeting complementary fixation technologies and capacity expansion into cobalt-chromium supply chains.
Among diversified orthopedic manufacturers, Zimmer Biomet Holdings, Inc., Stryker Corporation, and Smith + Nephew occupy positions defined by proprietary design philosophies. Zimmer Biomet represents the mobile-bearing innovation archetype through unconstrained polyethylene insert development. Stryker exemplifies integrated instrumentation platform strategy for surgical workflow efficiency. Smith + Nephew anchors the porous coating specialization vector with titanium surface technologies. These three entities collectively illustrate how competitive differentiation in total ankle replacement flows from material science capabilities and regulatory navigation expertise rather than scale alone.
| Leading Market Players |
|---|
| Exactech, Inc. |
| Integra LifeSciences Corporation |
| Zimmer Biomet Holdings, Inc. |
| Arthrex, Inc. |
| Enovis Corporation |
| Stryker Corporation |
| Smith + Nephew |
| DePuy Synthes |
| Johnson & Johnson Services, Inc. |
| Others |
Supply & Pricing Matrix
Integrated delivery network consolidation in the United States is compressing distributor margins and forcing manufacturers to absorb logistics costs, which in turn accelerates backward integration into cobalt-chromium alloy supply chains to preserve margin structures.
Pricing Analysis
Hospital value-analysis committee purchasing concentrates procurement authority and eliminates distributor markups in metropolitan clusters. Three-tier pricing structure across premium, standard, and economy levels separates hydroxyapatite-coated cementless systems from conventional cemented constructs and basic fixed-bearing alternatives. Cost compression in standard-tier mobile-bearing systems intensifies because polyethylene cross-linking technology diffuses across multiple suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to bundled payment constraints, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German cobalt-chromium molybdenum alloy foundries that anchor tibial tray production for European and North American implant manufacturers. Ultra-high molecular weight polyethylene resin draws from specialized polymer processors in the United States and Germany, with porous titanium bead stock sourced from Japanese metallurgical specialists. Tariff exposure on implant-grade metals threatens cost structures for manufacturers without captive smelting arrangements. Distribution runs through orthopedic-focused distributors with surgeon relationships, though direct-to-hospital contracts are gaining share among high-volume health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Total ankle replacement manufacturing presents a geographic-arbitrage play between FDA 510(k) pathway efficiency in the United States and EU MDR conformity bottlenecks in Europe, with regulatory cost differentials exceeding raw material labor advantages.
For Market Incumbents: Acquire cobalt-chromium alloy production capacity in Baden-Württemberg to secure input cost stability against commodity volatility. Cementless fixation technology represents a critical defensive asset as surgeon preference shifts toward osseointegration-optimized systems. Capacity addition in United States ambulatory surgery center corridors captures outpatient procedural migration before competitors establish instrumentation lock-in. For New Entrants and Emerging Players: FDA 510(k) pathway streamlining in the United States opens a window for mobile-bearing designs targeting younger, active patient cohorts underserved by legacy fixed-bearing portfolios. Post-traumatic arthritis applications in United States trauma centers present the most penetrable segment given specialized implant geometry requirements that favor nimble engineering teams. Hospital system partnership models bypass distributor relationships and accelerate credentialing through value-analysis committee direct engagement. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap coating technology specialists possessing hydroxyapatite application expertise transferable across joint reconstruction categories. Long-term viability across a 5-10 year window hinges on regulatory data moats rather than scale economies alone. PMDA parallel track utilization rates in Japan signal which portfolio companies have converted regulatory arbitrage into sustainable market access.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated premarket notification reviews compress product-to-market cycles for next-generation mobile-bearing systems. |
| CE Marking Pathway | EU MDR conformity assessment procedures require systematic registry participation that restructures quality management investments. |
| Hospital System Partnership | Value-analysis committee direct contracts concentrate purchasing power and eliminate traditional distributor margin layers. |
| Software Companion Development | Preoperative planning platforms differentiate instrumentation ecosystems in high-volume orthopedic centers. |
| Reimbursement Strategy | Outpatient procedure code expansion in United States ASC networks unlocks bundled payment capture for primary replacements. |
Research Methodology
Multiple input streams — surgeon interviews, hospital procurement database analysis, regulatory filing review, and alloy supply chain mapping — were reconciled to construct demand and supply estimates. Primary discussions with foot and ankle fellowship directors, GPO contracts managers, biomedical engineers, and orthopedic clinic administrators informed procedural volume assumptions. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body certificates, hospital implant registries, and CMS Medicare claims data. Bottom-up procedure counting and top-down implant production estimates were cross-referenced to anchor market sizing.
Data-stream reconciliation across the modeling period applied segmented growth rate derivation by bearing type, fixation method, coating technology, and care delivery setting. Mobile-bearing penetration curves, cementless fixation adoption thresholds, and ambulatory surgery center migration patterns served as industry-specific forecast inputs. CAGRs emerged from procedure volume elasticity to aging demographic projections and reimbursement policy scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity constraints and polyethylene supply disruptions. Orthopedic surgeon training pipeline bottlenecks and ankle arthrodesis substitution thresholds represent specific revision triggers for demand assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Global Hip Replacement Implants Market