
 Phototherapy Treatment Market | 2026-2036
Phototherapy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Phototherapy Treatment Market Analytics
Clinical-grade irradiance specifications is collapsing the gap between hospital phototherapy systems and home-use alternatives. GE Healthcare leverages its imaging equipment distribution networks to place phototherapy units within integrated health systems. Herbert Waldmann GmbH & Co. KG anchors its position through precision-engineered UV-A and UV-B lamp assemblies for dermatological suites. Philips Lighting Holding B.V. competes by extending its LED photonics expertise into narrowband wavelength devices for psoriasis management.
Phototherapy treatment employs controlled ultraviolet or visible light emissions at specific wavelengths and irradiance levels to modulate cellular immune responses and keratinocyte proliferation in skin disorders. LED devices now dominate new installations due to wavelength specificity and reduced thermal load, while ultraviolet lamps sustain significant installed-base replacement revenue across hospital phototherapy suites. Among indications, psoriasis commands the largest procedure volume, yet vitiligo represents the fastest-expanding addressable population as pigmentation restoration protocols gain protocol acceptance. Dermatology centers capture premium pricing for supervised multi-session regimens, whereas home care segments compete on device portability and patient self-administration compliance.
The FDA regulates phototherapy equipment as Class II medical devices requiring 510(k) premarket notification, while the CE marking framework under the EU MDR governs electromagnetic safety and clinical performance claims in Europe. ISO 13485 quality management standards shape contract manufacturer eligibility and OEM supply relationships for device brands. Stakeholders must monitor evolving photobiology evidence standards that determine insurer coverage decisions for at-home versus clinic-based treatment modalities.
Market Dynamics
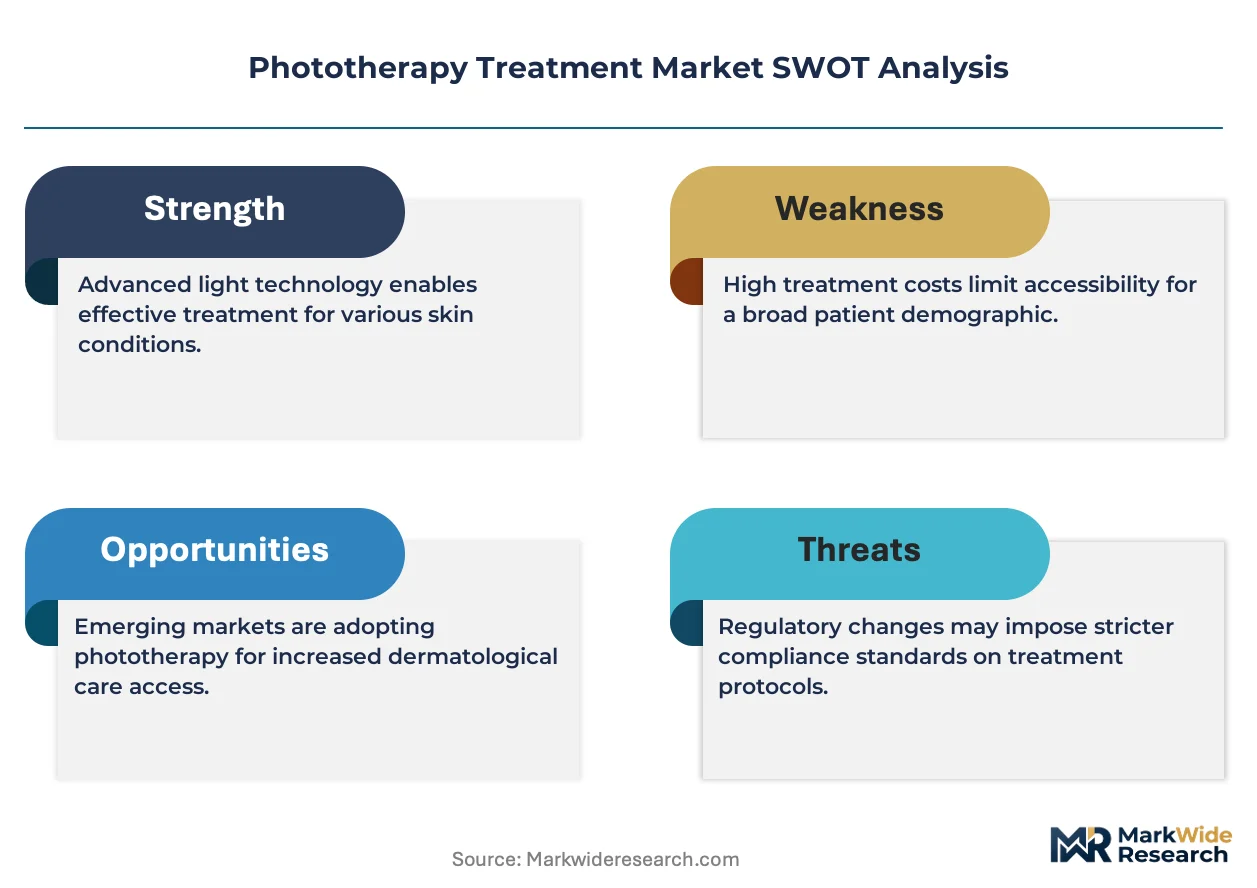
LED-based narrowband phototherapy systems are compressing treatment costs while expanding addressable patient populations beyond hospital settings. The FDA's streamlined 510(k) pathway for light-based devices accelerates commercialization timelines for manufacturers targeting home-use segments.
Growth Catalysts
- Reimbursement Framework Expansion:Outpatient phototherapy protocols now qualify for coverage under Medicare Part B in the United States, incentivizing dermatology centers to expand service capacity.
- Psoriasis Protocol Acceptance:Narrowband UV-B regimens have achieved standard-of-care status across major dermatological associations, anchoring procedure volume in clinical settings.
- CE Marking Harmonization:The EU MDR's consolidated electromagnetic safety requirements reduce regulatory fragmentation for device manufacturers seeking multi-country European placement.
Market Restraints
- Mercury Vapor Lamp Supply Concentration:Specialty UV lamp production clusters in Germany and Japan, creating single-source vulnerability for legacy system maintenance.
- Photocarcinogenesis Liability Exposure:Long-term safety litigation risk constrains aggressive marketing of high-dose home-use devices despite efficacy data.
- Device Cost Recovery Timelines:Capital equipment amortization stretches 36-48 months for independent dermatology practices purchasing multi-station phototherapy suites.
Strategic Opportunities
- Vitiligo Pigmentation Protocols:Excimer laser and targeted UV-B applications for melanocyte stimulation remain underpenetrated relative to psoriasis treatment volumes.
- Telemedicine-Integrated Home Devices:Remote irradiance monitoring and session logging create compliance-verification tools for payor-preferred at-home models.
- India's Dermatology Infrastructure Buildout:Tier-2 and Tier-3 city hospital expansions under Ayushman Bharat generate first-time equipment procurement demand.
Industry Challenges
- Photobiology Specialist Shortage:Certified medical physicists capable of calibrating spectral output and dosimetry protocols remain scarce outside academic medical centers.
- Legacy System Interoperability:Electronic health record integration for phototherapy session tracking requires custom API development that delays hospital procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phototherapy Treatment Market |
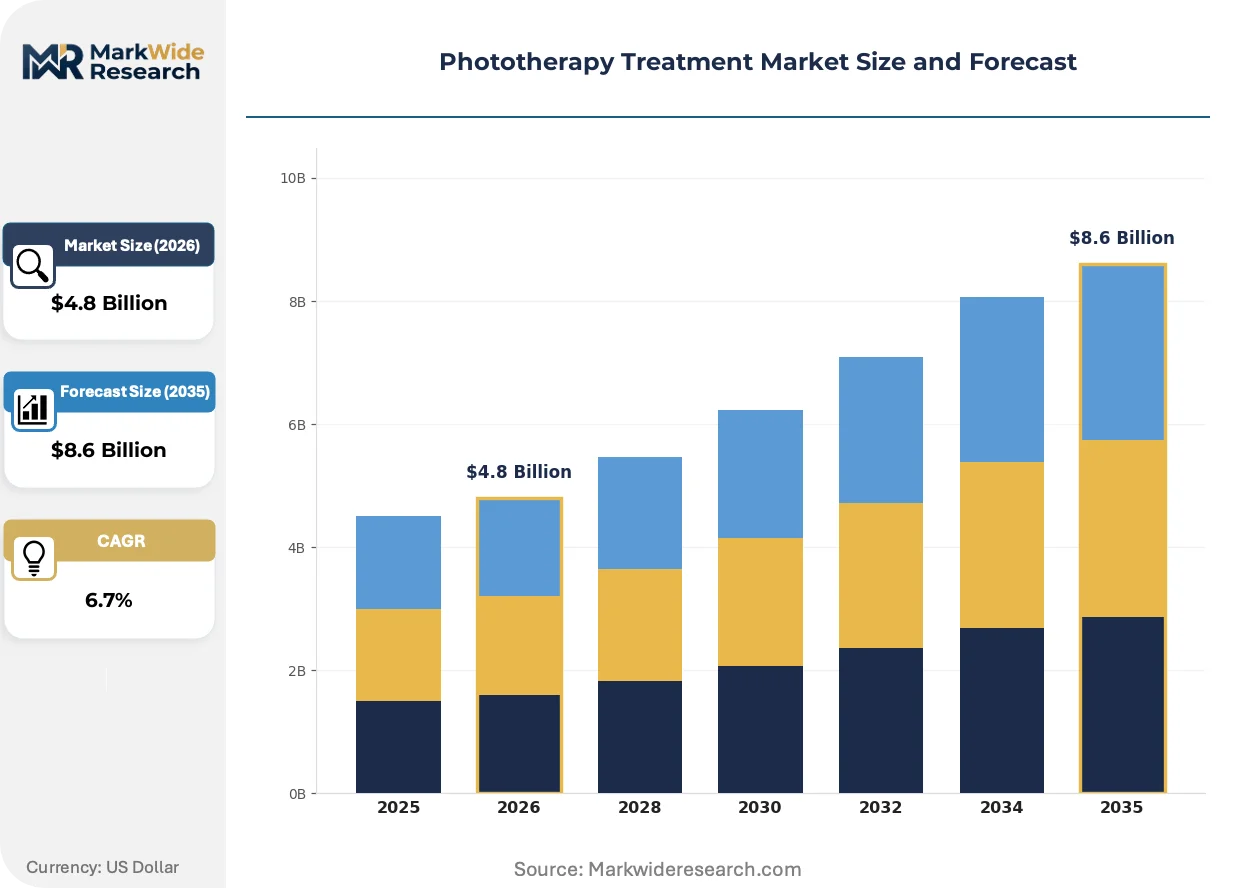
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Devices, Fluorescent Lights, Laser Systems, Ultraviolet Lamps Indication: Psoriasis, Eczema, Acne, Vitiligo End User: Clinics, Hospitals, Home Care, Dermatology Centers Delivery Mode: Handheld Devices, Fixed Systems, Portable Units, Light Panels |
| Companies Covered | GE Healthcare, Philips Lighting Holding B.V., Natus Medical Incorporated, Herbert Waldmann GmbH & Co. KG, Atom Medical Corporation, Phoenix Medical Systems Pvt. Ltd., Nice Neotech Medical Systems Pvt. Ltd., National Biological Corp., Solarc Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phototherapy Treatment Market Evolving Landscape
Wavelength-specific LED arrays are redefining device architecture while compressing the performance gap between clinical and consumer-grade equipment. Manufacturers now prioritize thermal management and dose-tracking software as primary differentiation vectors.
Micro-LED chip-on-board assemblies operating at 311 nm peak emission are displacing traditional mercury vapor lamps in new phototherapy installations. Dermatology centers in the United States and Germany are prioritizing these solid-state alternatives for their reduced warm-up latency and precise spectral control. The technology is displacing incumbent lamp vendors from the premium equipment tier while enabling portable device formats previously impossible with thermal-constrained arc sources.
The EU MDR's strengthened clinical evidence requirements for electromagnetic medical devices are extending premarket assessment timelines for phototherapy equipment. Manufacturers must now submit photobiological safety testing data beyond legacy CE marking documentation, compressing the competitive advantage of early-mover brands with established technical files. German and French notified bodies are applying the most stringent interpretation, forcing redesign cycles for devices targeting Western European hospital procurement.
Hospital procurement committees are unbundling phototherapy equipment from bundled capital equipment contracts previously dominated by imaging system vendors. Independent dermatology groups and ambulatory surgery centers now negotiate direct with specialized phototherapy manufacturers, bypassing integrated health system purchasing hierarchies. This channel fragmentation is most pronounced in the United States, where group purchasing organization consolidation had previously suppressed vendor direct access.
Phototherapy Treatment Market Segmentation
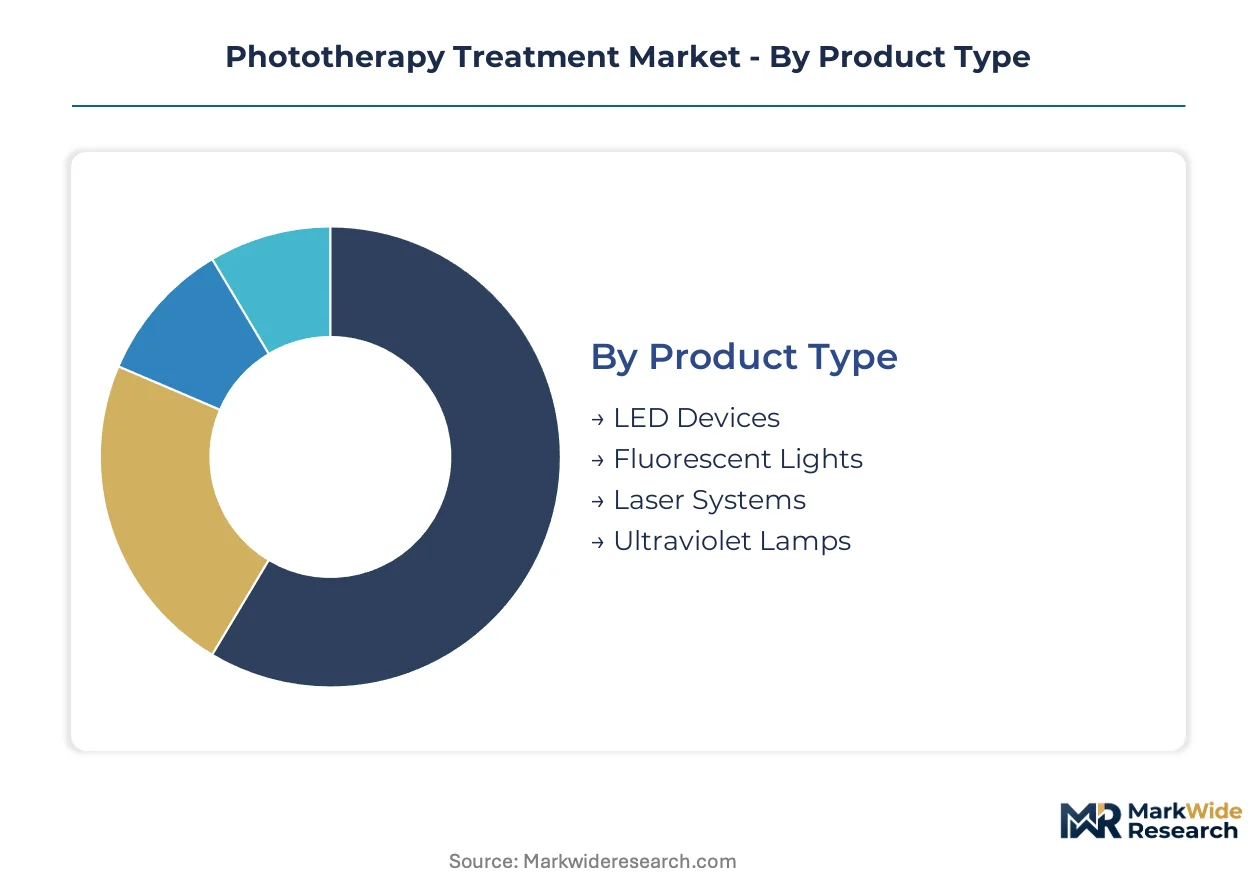
Phototherapy equipment manufacturers navigate distinct channel economics across product architectures, with LED-based systems penetrating home-use segments while legacy lamp technologies sustain hospital replacement cycles. Indication-specific protocols and reimbursement eligibility further stratify addressable populations between supervised clinical settings and patient-administered alternatives.
Product Type:
Channel flow diverges sharply between solid-state LED platforms targeting retail and direct-to-consumer routes versus lamp-based systems moving through medical device distributors serving institutional procurement.
- LED Devices:Solid-state arrays at 311 nm peak emission enable precise spectral control without thermal latency. Demand concentrates in United States home-use segments where FDA 510(k) clearances for narrowband UV-B devices support direct-to-consumer distribution, though photocarcinogenesis liability constrains dose marketing.
- Ultraviolet Lamps:Mercury vapor and excimer discharge lamps deliver high irradiance for multi-station clinical suites. Replacement demand clusters in German and Japanese hospital systems where legacy equipment amortization cycles extend equipment lifespans, creating concentrated supply vulnerability for specialty lamp sourcing.
- Fluorescent Lights:Broadband UV-A and UV-B tubes serve cost-sensitive dermatology practices in India and Southeast Asia.
- Laser Systems:Excimer laser platforms at 308 nm target vitiligo pigmentation protocols with premium pricing in academic medical centers.
Ultraviolet lamps dominate installed base. LED devices are where expansion concentrates.
Indication:
Protocol standardization and payer coverage determine which indications sustain premium clinical pricing versus commoditized home-use competition.
- Psoriasis:Narrowband UV-B regimens have achieved standard-of-care designation across American Academy of Dermatology guidelines. Procedure volume concentrates in United States dermatology centers where Medicare Part B reimbursement for outpatient phototherapy incentivizes capacity expansion.
- Vitiligo:Melanocyte stimulation protocols using targeted UV-B and excimer laser applications remain underpenetrated relative to psoriasis treatment volumes. Fastest-growing addressable population as pigmentation restoration gains protocol acceptance in European dermatological associations.
- Eczema:Atopic dermatitis phototherapy protocols face reimbursement variability across United States commercial payors.
- Acne:Blue-light phototherapy for Cutibacterium acnes suppression competes with topical and systemic alternatives in adolescent demographics.
Psoriasis commands largest procedure volume. Vitiligo is gaining share fastest.
End User:
Capital intensity and regulatory compliance requirements stratify equipment specifications across institutional versus consumer channels.
- Dermatology Centers:Independent and group practices in the United States capture premium pricing for supervised multi-session regimens. These facilities prioritize multi-station suites with integrated dosimetry tracking and electronic health record connectivity.
- Home Care:Patient self-administration segments compete on device portability and compliance verification tools. United States direct-to-consumer channels and European pharmacy distribution dominate volume.
- Hospitals:Academic medical centers in Germany and France anchor demand for high-irradiance excimer laser systems.
- Clinics:Ambulatory surgery centers in United States group purchasing organization networks negotiate unbundled procurement from specialized manufacturers.
Dermatology centers dominate revenue per procedure. Home care is where volume expansion concentrates.
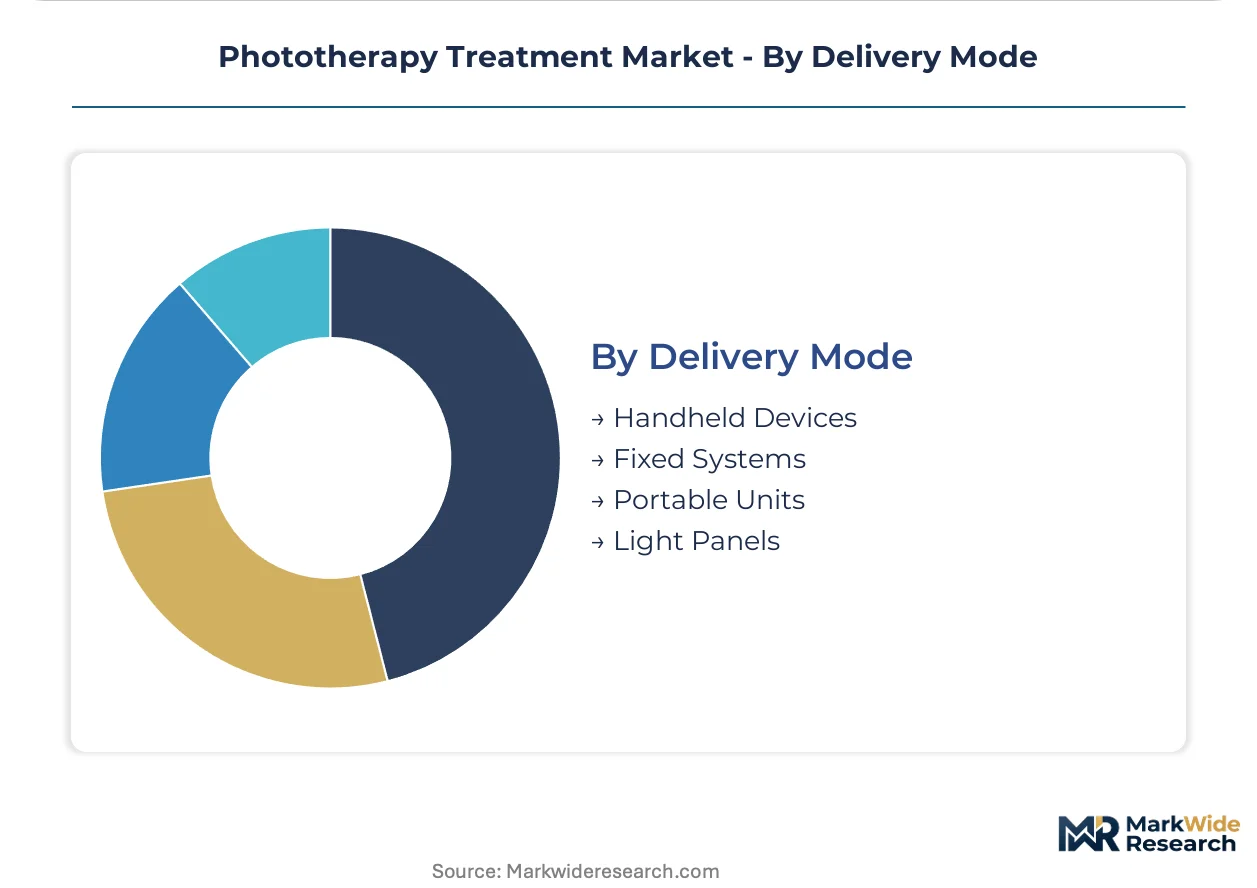
Delivery Mode:
Form factor determines thermal management complexity and wavelength precision, with handheld and portable formats enabling patient mobility at some cost to irradiance uniformity.
- Handheld Devices:Battery-powered narrowband UV-B units enable targeted spot treatment for localized plaques. United States and German home-use markets drive demand where patient compliance with self-administered protocols requires dose-logging software integration.
- Fixed Systems:Cabinet and booth architectures deliver whole-body irradiance with calibrated dosimetry for clinical settings. Hospital procurement in France and Switzerland prioritizes these configurations for psoriasis protocol standardization.
- Portable Units:Foldable light panel designs bridge clinical and home-use applications with moderate irradiance output.
- Light Panels:Wall-mounted and ceiling-suspended arrays serve multi-patient treatment rooms in high-volume dermatology centers.
Fixed systems dominate clinical installed base. Handheld devices are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. United States buyers absorb premium pricing for home-use devices, while Indian procurement prioritizes cost-per-treatment metrics in hospital tenders.
United States
Medicare Part B reimbursement for outpatient phototherapy protocols sustains dermatology center expansion. FDA 510(k) clearances for narrowband UV-B devices accelerate home-use segment commercialization. The Cleveland Clinic and Mayo Clinic anchor academic demand for excimer laser systems with integrated dosimetry tracking.
Germany
Precision-engineered UV lamp assemblies serve replacement cycles in multi-station hospital suites. EU MDR electromagnetic safety requirements extend premarket assessment timelines for LED device entrants. Herbert Waldmann GmbH & Co. KG anchors production in Villingen-Schwenningen, supplying dermatological suites across Western Europe.
India
Ayushman Bharat hospital infrastructure buildout in Tier-2 and Tier-3 cities generates first-time equipment procurement. CDSCO medical device registration requirements shape import substitution strategies for domestic manufacturers. Phoenix Medical Systems and Nice Neotech Medical Systems concentrate production in Chennai, serving cost-sensitive clinic segments.
Japan
Specialty mercury vapor lamp production clusters sustain legacy system maintenance revenue. PMDA Class II device approvals require photobiological safety documentation beyond legacy technical files. Tokyo and Osaka academic medical centers prioritize high-irradiance excimer platforms for vitiligo pigmentation protocols.
United Kingdom
NHS England commissioning frameworks cap reimbursement rates for phototherapy procedures in community dermatology settings. MHRA post-Brexit device regulations diverge from EU MDR timelines, creating parallel compliance pathways. London teaching hospitals anchor demand for multi-station suites with electronic health record connectivity.
Phototherapy Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the phototherapy equipment sector. The market structures around three tiers: imaging-system conglomerates with distribution reach, precision lamp specialists with legacy installed-base relationships, and emerging LED platform vendors targeting home-use price points. Dominant competitive moves include unbundling from hospital capital equipment contracts and direct procurement channel development for independent dermatology groups.
Among diversified health technology conglomerates, GE Healthcare and Philips Lighting Holding B.V. occupy positions leveraging imaging equipment networks and LED photonics expertise respectively. Herbert Waldmann GmbH & Co. KG exemplifies the precision-engineering specialist archetype, anchoring supply relationships through UV lamp assembly concentration. These three represent distinct strategic postures: conglomerate platform extension, component specialization, and solid-state technology transition.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Lighting Holding B.V. |
| Natus Medical Incorporated |
| Herbert Waldmann GmbH & Co. KG |
| Atom Medical Corporation |
| Phoenix Medical Systems Pvt. Ltd. |
| Nice Neotech Medical Systems Pvt. Ltd. |
| National Biological Corp. |
| Solarc Systems Inc. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with German and Japanese lamp manufacturers lock in supply access for hospital system procurement committees while anchoring price visibility across 36-48 month equipment amortization cycles. These arrangements concentrate pricing power with legacy UV-A and UV-B assembly specialists, forcing LED platform vendors to compete on spot-market component sourcing for home-use device production.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across clinical and home-use segments. Three-tier pricing separates excimer laser platforms from multi-station LED suites from portable narrowband UV-B devices, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the home-use tier intensifies because direct-to-consumer channels bypass institutional procurement markups. Independent dermatology practices show highest price sensitivity due to capital equipment amortization timelines, while academic medical centers absorb premium pricing for integrated dosimetry systems.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for micro-LED chip-on-board assemblies sourced from Taiwanese foundries. Manufacturing concentrates in Germany for precision-engineered mercury vapor lamps, Japan for excimer discharge tubes, and China for solid-state LED arrays. Component sourcing draws from specialty glass envelope suppliers, rare gas refiners, and semiconductor packaging houses. Single-source vulnerability pervades the 311 nm peak emission phosphor supply, with distribution running through medical device distributors serving institutional procurement and direct-to-consumer electronics channels for home-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified medical physicists capable of calibrating spectral output and dosimetry protocols remain scarce outside academic medical centers, constraining service expansion for phototherapy suite operators and creating acquisition premiums for trained technical teams.
For Market Incumbents: Compound defensive positioning through backward integration into micro-LED chip-on-board manufacturing and captive supply of 311 nm peak emission phosphors. Acquire photobiology specialist training programs to offset certified medical physicist scarcity. Threats from solid-state platform vendors and FDA 510(k) pathway acceleration for home-use devices demand channel control through direct procurement relationships with independent dermatology groups. For New Entrants and Emerging Players: Differentiate on telemedicine-integrated dose-logging software for compliance verification in United States Medicare Part B reimbursement frameworks. Target vitiligo pigmentation protocols as the most penetrable indication segment, where excimer laser and targeted UV-B applications remain underpenetrated relative to psoriasis volumes. Pursue pharmacy distribution partnerships in European markets as the primary go-to-market angle for portable narrowband UV-B devices. For Investors and Strategic Acquirers: Capital is best deployed toward precision-engineering specialists with legacy installed-base relationships and concentrated UV lamp assembly capabilities in Germany or Japan. Long-term viability hinges on technology transition optionality between mercury vapor platforms and solid-state alternatives. Watch for FDA 510(k) clearance acceleration for home-use narrowband UV-B devices as the inflection indicator signaling channel shift toward direct-to-consumer distribution models.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR electromagnetic safety requirements extend premarket timelines for LED device entrants targeting Western European hospital procurement. |
| Hospital System Partnership | Unbundled procurement negotiations with independent dermatology groups bypass integrated health system purchasing hierarchies in United States markets. |
| Software Companion Development | Remote irradiance monitoring and session logging create compliance-verification tools for payor-preferred at-home phototherapy models. |
| Reimbursement Strategy | Medicare Part B coverage for outpatient protocols anchors procedure volume and incentivizes dermatology center capacity expansion. |
| FDA Submission | Streamlined 510(k) pathway for light-based devices accelerates commercialization timelines for manufacturers targeting home-use segments. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical file documentation, and hospital procurement contract records preceded structured interviews with dermatology center administrators, biomedical equipment engineers, GPO contracts managers, and photobiology specialists. Primary fieldwork with device manufacturers and regulatory affairs consultants combined with secondary validation through ISO 13485 quality management audit reports and CMS Medicare reimbursement data. Bottom-up equipment shipment tracking and top-down addressable population modeling enabled triangulation across analysis approaches.
Variance decomposition across product architecture, indication protocol, and end-user channel dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated LED versus lamp-based technology transitions, psoriasis versus vitiligo procedure volume splits, and dermatology center versus home-use delivery mode penetration patterns. CAGRs derived from installed base replacement cycles and first-time procurement demand in India's Tier-2 and Tier-3 city hospital expansions. Forecast inputs included photobiology evidence standards evolution and insurer coverage decision timelines for at-home versus clinic-based modalities.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance velocity, EU MDR premarket assessment consistency, and Medicare Part B reimbursement stability would require recalibration. Forecasts reflect documented assumptions regarding narrowband UV-B protocol standardization and mercury vapor lamp supply concentration persistence. Photocarcinogenesis litigation exposure, legacy system interoperability delays, and specialty UV lamp single-source vulnerability represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market