
 Japan Radiotherapy Market | 2026-2036
Japan Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Radiotherapy Market Insights
The gap between proton-heavy ion systems and conventional linear accelerator installations is repositioning procurement patterns across Japanese cancer centers. Hitachi Ltd. leverages its superconducting synchrotron expertise to dominate proton therapy hardware, while Mitsubishi Electric Corporation anchors supply chains for compact cyclotron-based systems. Sumitomo Heavy Industries Ltd. competes through integrated particle therapy gantries that reduce facility footprint requirements.
Radiotherapy encompasses external beam and internal radiation modalities that deploy ionizing energy to destroy malignant cells with dose precision measured in Gray units, typically delivered via megavoltage photon or charged particle beams. Linear Accelerators occupy the largest installed base among product types, though Proton Therapy segments command premium pricing due to capital intensity and specialized shielding requirements. Intensity-Modulated Radiation Therapy leads technology penetration in Japan's hospital networks, while Stereotactic Radiosurgery segments show fastest adoption in outpatient oncology clinics seeking shorter treatment courses.
PMDA device approval pathways and JIS standards for medical electrical equipment shape product entry timelines and clinical trial obligations for domestic and imported systems. METI's healthcare technology assessment frameworks influence reimbursement rates for advanced modalities, directly impacting hospital capital allocation decisions. Stakeholders must monitor how Japan's aging demographic shifts toward lung and prostate cancer incidence will strain existing linear accelerator capacity against proton therapy expansion timelines.
Market Dynamics
Proton therapy capacity expansion is compressing conventional linear accelerator utilization rates across Japan's oncology networks, forcing capital allocation trade-offs between precision particle systems and photon-based infrastructure renewal cycles.
Growth Catalysts
- PMDA streamlined pathways:Japan's pharmaceutical and medical device agency accelerates approval timelines for next-generation beam delivery systems, reducing clinical trial burdens for domestic manufacturers.
- Lung cancer incidence:Japan's aging demographic concentrates demand for hypofractionated treatment protocols in the Kanto and Kansai regions, where elderly patient volumes strain existing photon capacity.
- Intensity-Modulated Radiation Therapy:IMRT penetration across hospital networks creates pull-through demand for integrated imaging and planning software that enables adaptive treatment workflows.
Market Restraints
- Superconducting magnet supply:Domestic reliance on limited cryogenic component suppliers concentrates procurement risk for synchrotron-based proton systems requiring specialized niobium-titanium coils.
- Shielding concrete costs:Proton and heavy-ion facilities require radiation barrier thicknesses exceeding conventional vault specifications, extending construction timelines and capital deployment cycles.
- Linear accelerator substitution ceiling:Conventional photon systems maintain cost advantages for high-volume palliative care, capping particle therapy addressable share in budget-constrained municipal hospitals.
Strategic Opportunities
- Compact cyclotron systems:Footprint-reduced proton platforms enable installation in suburban and regional cancer centers previously excluded by facility size constraints.
- METI technology assessment integration:Ministry of Economy, Trade and Industry frameworks for advanced modality reimbursement create policy tailwinds for hospitals qualifying under healthcare technology assessment criteria.
- Stereotactic Radiosurgery outpatient migration:Shorter treatment courses attract private clinic investment in dedicated SRS platforms, displacing fractionated photon protocols for brain and spine lesions.
Industry Challenges
- Medical physicist specialization:Particle therapy commissioning and quality assurance require expertise in beam optics and dosimetry calibration that outpaces domestic training program output.
- Legacy linac integration:Hospital IT infrastructure built around Varian and Elekta ecosystem architectures creates data interoperability friction with emerging proton planning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Radiotherapy Market |
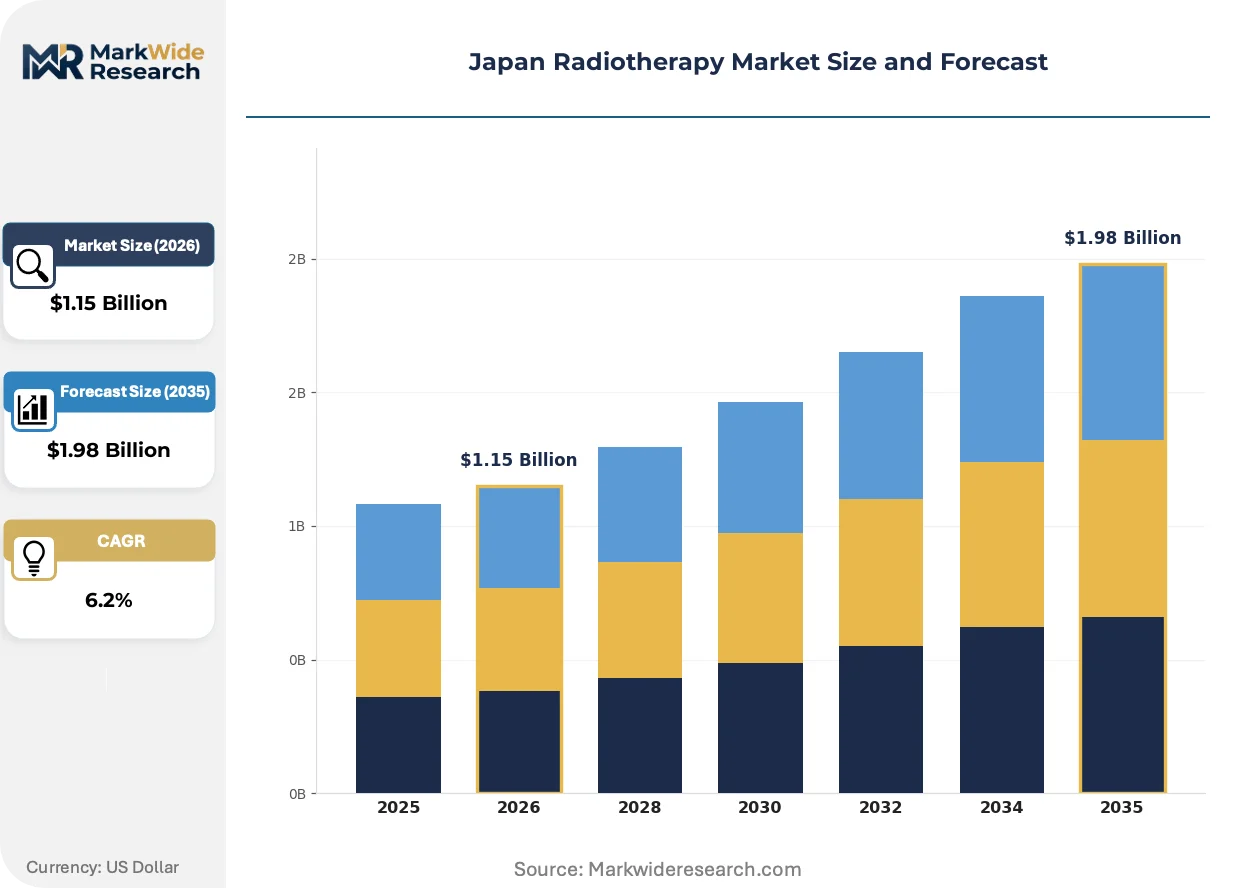
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $1.98 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy, Radiopharmaceuticals, Treatment Planning Systems Technology: External Beam Radiation Therapy, Intensity-Modulated Radiation Therapy, Stereotactic Radiosurgery, Proton Therapy End User: Hospitals, Oncology Clinics, Research Institutions, Diagnostic Centers Application: Breast Cancer, Prostate Cancer, Lung Cancer, Head and Neck Cancer |
| Companies Covered | Hitachi Ltd., Mitsubishi Electric Corporation, IHI Corporation, Elekta K.K., Sumitomo Heavy Industries Ltd., Toshiba Corporation, Shimadzu Corporation, Hamamatsu Photonics K.K., Osaka Heavy Ion Therapy Center, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Radiotherapy Market Trends and Innovations
Adaptive treatment planning and real-time imaging fusion are compressing margin for error in dose delivery, enabling narrower clinical target volume margins that reduce toxicity profiles for organs at risk.
Magnetic resonance-guided linear accelerator systems are automating soft-tissue visualization during beam delivery, allowing Tokyo-area university hospitals to track tumor motion without implanted fiducial markers. Adoption concentrates in prostate and abdominal sites where daily anatomical variation compromises static planning. This automation is compressing replanning cycles from weekly to daily intervals, shifting clinical workflow toward on-table adaptation.
METI's healthcare technology assessment revisions for fiscal year evaluation cycles now mandate cost-effectiveness thresholds for proton therapy reimbursement approvals, forcing manufacturers to submit real-world evidence from Japanese patient cohorts rather than extrapolated overseas data. Domestic cancer centers in Osaka and Nagoya are restructuring clinical trial designs to capture quality-adjusted life year metrics that satisfy assessment committee criteria. Heavy-ion facilities face heightened scrutiny under these frameworks due to capital intensity versus incremental outcome gains.
Hospital procurement committees are unbundling service contracts from hardware purchases, demanding separate pricing for maintenance, software upgrades, and physicist training. This fragmentation pressures vendors to disclose component-level cost structures previously buried in turnkey agreements. The shift is most visible in Kanto region academic medical centers where consolidated purchasing consortia negotiate multi-system installations across hospital networks.
Japan Radiotherapy Market Segmentation
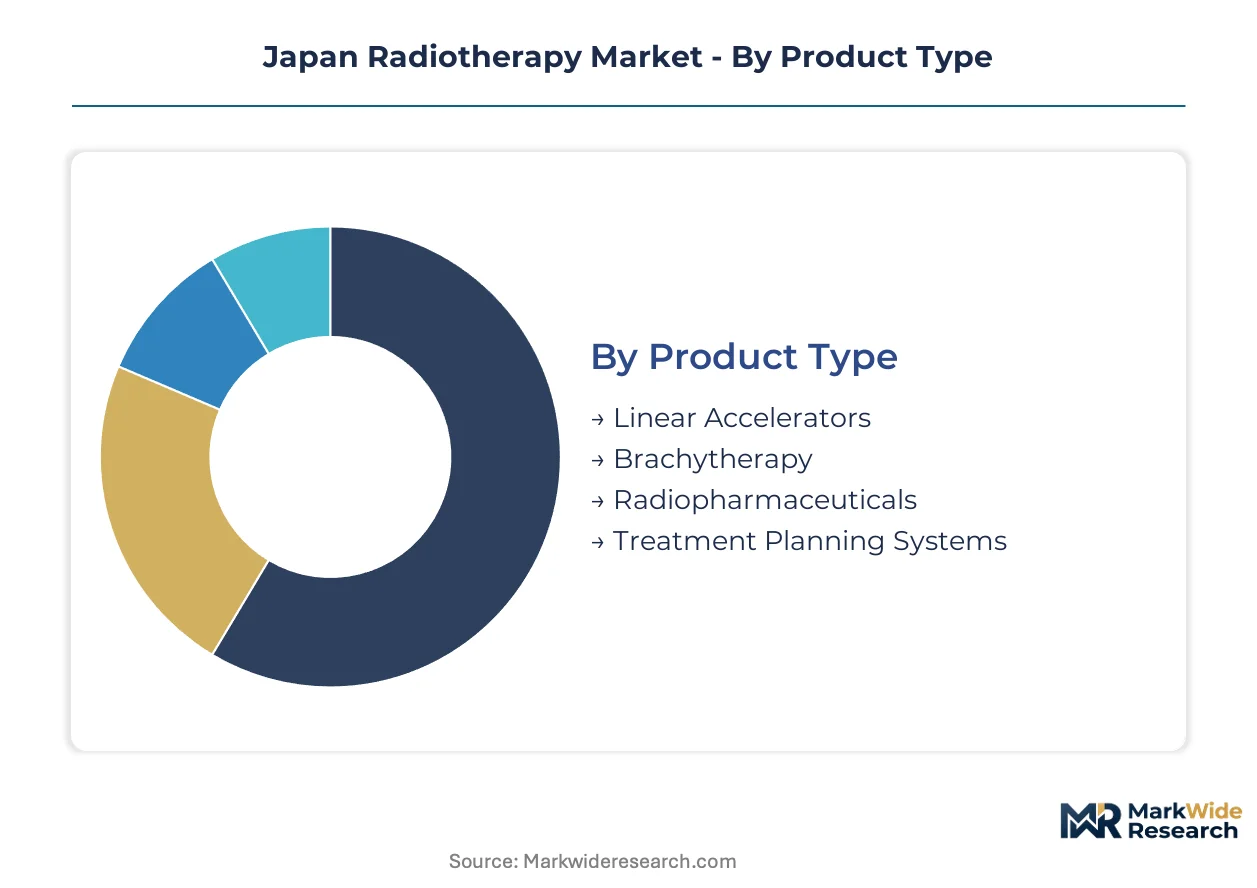
Segmentation in Japan's radiotherapy market reveals how capital allocation splits between precision particle systems and conventional photon infrastructure. Procurement committees weigh replacement cycles, reimbursement pathways, and facility constraints when prioritizing technology investments across oncology networks.
Product Type:
Replacement cycles for aging cobalt units and first-generation linacs are accelerating procurement decisions across Japan's hospital networks, with capital committees balancing upfront costs against operational lifespan and maintenance burdens.
- Linear Accelerators:Megavoltage photon systems generating X-ray beams through microwave-accelerated electrons remain the workhorse technology. Tokyo's National Cancer Center and Osaka University Hospital anchor demand for dual-energy platforms capable of both conventional and stereotactic delivery. The Kanto region concentrates installed base renewal as municipal hospitals phase out 15-year-old systems.
- Brachytherapy:Internal radiation modalities deploy sealed radioactive sources directly within tumor cavities or body lumens. Gynecological and prostate applications drive adoption in Nagoya-area academic centers seeking organ-sparing alternatives to external beam protocols. PMDA streamlines approval for automated afterloading systems that reduce staff radiation exposure.
- Radiopharmaceuticals:Systemic radionuclide therapies target metastatic disease through molecular carriers.
- Treatment Planning Systems:Software platforms integrating CT, MRI, and PET data for dose optimization algorithms.
Linear Accelerators sit at the top of the volume ranking, with Treatment Planning Systems climbing the fastest as adaptive workflows demand real-time imaging fusion.
Technology:
Cost tier differentiation separates capital-intensive particle systems from photon-based modalities, with reimbursement rates under METI assessment frameworks determining hospital upgrade feasibility.
- External Beam Radiation Therapy:Conventional photon delivery from fixed or rotating gantry angles constitutes the baseline modality. Municipal hospitals in Hokkaido and Kyushu maintain EBRT dominance for high-volume palliative care where capital constraints exclude precision alternatives. JIS standards for medical electrical equipment govern beam stability and safety interlock specifications.
- Intensity-Modulated Radiation Therapy:Computer-controlled multileaf collimators modulate beam intensity across treatment fields, sculpting dose distributions around organs at risk. IMRT penetration concentrates in Kansai region networks where prostate and head-and-neck caseloads justify planning complexity and extended treatment times.
- Stereotactic Radiosurgery:High-dose single-fraction or hypofractionated delivery with submillimeter precision targets intracranial and spinal lesions. Outpatient clinics in Tokyo's Shinjuku and Osaka's Umeda districts invest in dedicated CyberKnife and Gamma Knife platforms to capture brain metastasis referrals.
- Proton Therapy:Charged particle beams deposit energy at Bragg peak depths, sparing distal tissues.
External Beam Radiation Therapy dominates installed base volume, while Stereotactic Radiosurgery expands most quickly in private clinic settings seeking shorter treatment courses.
End User:
Customer type segmentation tracks how capital intensity and reimbursement eligibility split procurement authority between consolidated hospital systems and specialized outpatient operators.
- Hospitals:Academic medical centers and general hospitals with radiation oncology departments control proton therapy access and complex case referrals. The National Cancer Center Hospital East in Kashiwa and Osaka International Cancer Institute anchor heavy-ion and proton networks that regional facilities feed into for advanced protocols.
- Oncology Clinics:Specialized cancer treatment centers focus on high-throughput photon delivery and stereotactic procedures. Privately operated chains in Tokyo's 23 wards and Fukuoka City deploy compact linacs in retail medical real estate, competing on appointment availability and concierge service tiers.
- Research Institutions:University hospitals and national laboratories conduct clinical trials for next-generation beam delivery.
- Diagnostic Centers:Imaging-focused facilities without treatment authorization refer patients to affiliated radiation oncology partners.
Hospitals command the largest capital deployment, with Oncology Clinics gaining share fastest as stereotactic protocols enable outpatient business models.
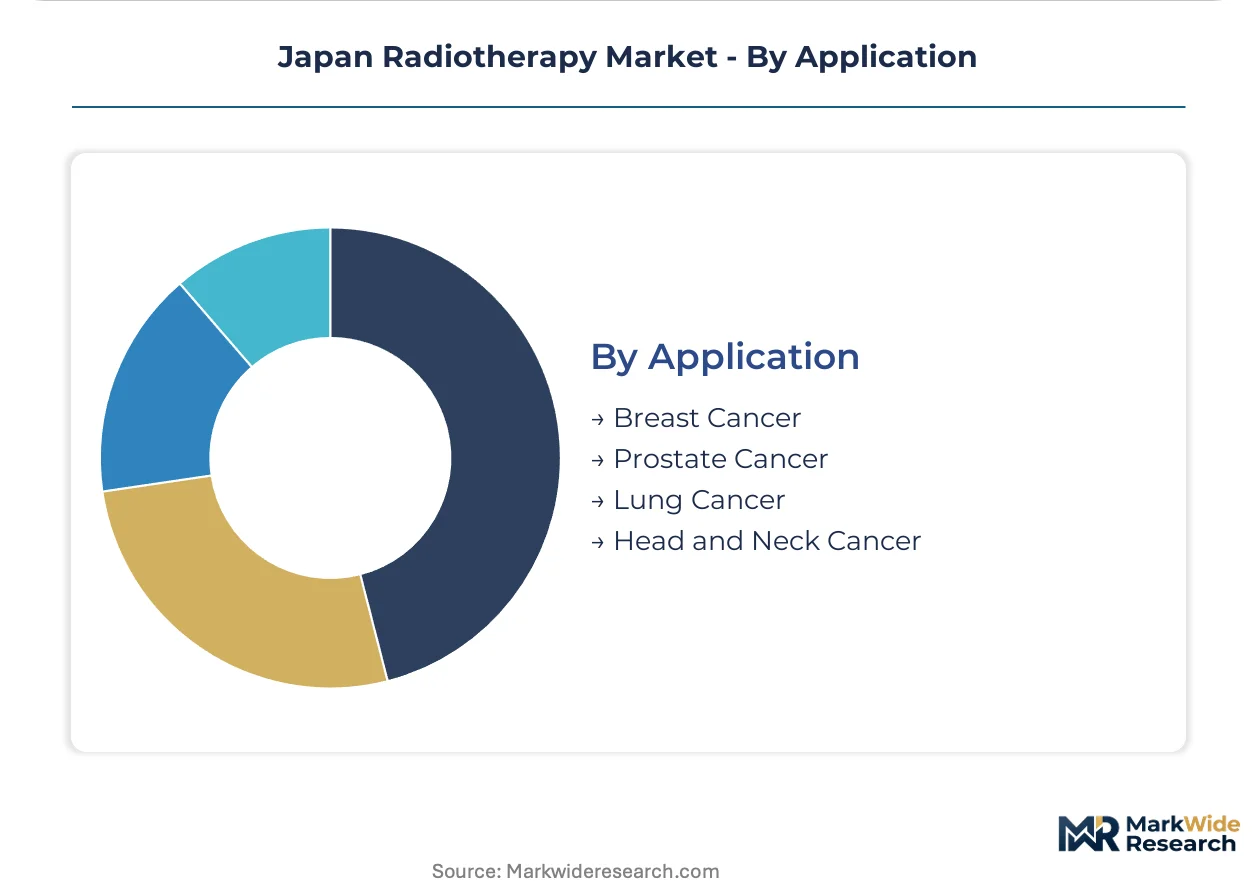
Application:
Geography of disease incidence shapes regional equipment mix, with lung and prostate prevalence in aging prefectures driving modality-specific investments.
- Breast Cancer:Partial breast irradiation and post-lumpectomy whole-breast protocols generate consistent linac utilization. Hyogo and Aichi prefectures show elevated screening uptake that feeds into radiation oncology queues, with Osaka-area centers pioneering intraoperative radiotherapy integration.
- Prostate Cancer:Hypofractionated and stereotactic body radiation therapy protocols reduce treatment courses from 40 to 5 fractions. Tokyo and Kanagawa prefectures concentrate demand as elderly male populations and elevated PSA screening rates expand addressable caseloads for precision modalities.
- Lung Cancer:Motion management challenges in thoracic sites favor advanced imaging and adaptive planning.
- Head and Neck Cancer:Organ-at-risk proximity demands IMRT or proton precision to spare salivary glands and optic structures.
Prostate Cancer leads volume ranking among precision-modality indications, with Lung Cancer expanding most quickly as hypofractionated protocols penetrate screening-detected early-stage cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's proton therapy infrastructure outpaces South Korea's installed base, yet both nations face similar constraints in medical physicist training pipelines that limit treatment capacity expansion. Germany and Switzerland anchor European particle therapy networks with comparable regulatory frameworks to Japan's PMDA pathways.
Kanto/Tokyo
Tokyo's National Cancer Center anchors the nation's heaviest concentration of proton and heavy-ion treatment capacity. METI technology assessment frameworks prioritize reimbursement for advanced modalities in this region. Chiba's Proton Medical Research Center and Tsukuba's carbon-ion facility feed referral networks across eastern Japan.
Kansai/Osaka
Osaka International Cancer Institute drives heavy-ion therapy demand for lung and prostate cases in western Japan. PMDA streamlined approval pathways accelerate next-generation beam delivery system installations here. The Osaka Heavy Ion Therapy Center anchors a regional network extending to Kobe and Kyoto academic hospitals.
Chubu/Nagoya
Nagoya University Hospital concentrates stereotactic radiosurgery adoption for brain metastasis protocols. JIS standards for medical electrical equipment govern linac procurement across Aichi prefecture's municipal hospital networks. Toyota-area manufacturing clusters supply precision components for gantry positioning systems.
Kyushu
Fukuoka City oncology clinics deploy compact linacs in retail medical real estate competing on appointment availability. Aging demographics in Saga and Nagasaki prefectures elevate lung cancer caseloads straining existing photon capacity. Regional hospitals face capital constraints excluding proton therapy participation.
Hokkaido
Sapporo's academic medical center maintains conventional linac dominance for high-volume palliative care. Budget-constrained municipal hospitals across northern Japan lack particle therapy access. Sapporo-area procurement committees prioritize EBRT infrastructure renewal over precision modality expansion.
Japan Radiotherapy Market Competitive Landscape
Top-tier vendors anchor proton therapy hardware supply, while mid-tier specialists concentrate on compact cyclotron systems and treatment planning software. The vendor base stratifies across synchrotron-based heavy-ion platforms, superconducting magnet suppliers, and integrated software-hardware bundles. Strategic archetypes include integrated industrial conglomerates with cryogenic expertise, precision engineering specialists, and imaging-software hybrid providers. Competitive moves center on unbundled service contract structures and multi-system purchasing consortia negotiations.
Among Japan-based industrial conglomerates, Hitachi Ltd. and Mitsubishi Electric Corporation occupy positions reflecting superconducting synchrotron and compact cyclotron specializations respectively. Sumitomo Heavy Industries Ltd. exemplifies the integrated particle therapy gantry archetype targeting facility footprint reduction. Elekta K.K. represents the imaging-software hybrid positioning within hospital IT infrastructure ecosystems.
| Leading Market Players |
|---|
| Hitachi Ltd. |
| Mitsubishi Electric Corporation |
| IHI Corporation |
| Elekta K.K. |
| Sumitomo Heavy Industries Ltd. |
| Toshiba Corporation |
| Shimadzu Corporation |
| Hamamatsu Photonics K.K. |
| Osaka Heavy Ion Therapy Center |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees unbundling service contracts from hardware purchases force vendors to disclose component-level cost structures and compress margins on turnkey agreements. This buyer-side restructuring concentrates pricing power with consolidated purchasing consortia in Kanto region academic medical centers while squeezing mid-tier suppliers.
Pricing Analysis
Capacity additions in Chiba and Tsukuba are reshaping price floors for proton therapy systems as Hitachi and Mitsubishi Electric compete for multi-installation contracts. Three-tier pricing structure across premium synchrotron, standard cyclotron, and economy refurbished linac levels reflects capital intensity and shielding requirements. Pricing pressure stems from METI cost-effectiveness thresholds demanding real-world evidence submissions. Municipal hospitals exhibit highest price sensitivity due to budget constraints, while National Cancer Center affiliates prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Tokyo and Osaka coordinate hub-and-spoke delivery of superconducting magnets and gantry positioning systems to installation sites. Japan, Germany, and the United States anchor supply for niobium-titanium cryogenic coils and precision radiation detectors. Domestic production draws from specialized steel foundries in Hiroshima and imported vacuum chamber components. Single-source vulnerability concentrates in superconducting wire supply. Distribution runs through manufacturer-direct field service teams with localized spare parts depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as Japan's aging demographic concentrates lung and prostate cancer incidence in Kanto and Kansai prefectures. METI reimbursement frameworks for advanced modalities institutionalize demand for precision particle systems.
For Market Incumbents: To counter compact cyclotron entrants from Mitsubishi Electric, Hitachi Ltd. should deepen backward integration into superconducting magnet production and lock academic medical centers into multi-system service contracts spanning hardware, software, and physicist training. PMDA streamlined approval pathways reward early clinical trial investment with faster market access. For New Entrants and Emerging Players: Direct-to-hospital software licensing routes bypass capital-intensive hardware manufacturing and capture pull-through demand from adaptive planning workflow adoption. White-space targets include suburban oncology clinics in Fukuoka and Sapporo seeking compact linac platforms, plus treatment planning system modules for legacy Varian and Elekta ecosystem integration. For Investors and Strategic Acquirers: Asymmetric upside sits with imaging-software hybrid providers positioned for MR-linac convergence and real-time adaptive planning automation. Long-term viability hinges on recurring revenue streams from software subscriptions and service contracts rather than lumpy hardware sales. Watch PMDA approval timelines for next-generation beam delivery systems as inflection indicators for capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Streamlined Approval Pathway | Accelerates market entry for domestic manufacturers submitting Japanese patient cohort data. |
| Hospital System Partnership | Consolidated purchasing consortia in Kanto negotiate multi-installation pricing and service bundles. |
| Software Companion Development | Adaptive planning modules integrate with existing Varian and Elekta infrastructure to reduce switching costs. |
| Reimbursement Strategy | METI healthcare technology assessment compliance secures premium reimbursement rates for proton therapy. |
| Backward Integration into Magnets | In-house superconducting coil production mitigates single-source supply risk from limited cryogenic component suppliers. |
Research Methodology
Multiple input streams — primary interviews with radiation oncologists and hospital procurement managers, secondary validation through PMDA device registration databases and METI healthcare technology assessment publications, plus trade data on superconducting component imports — were reconciled to construct market estimates. Conversations with medical physicists, biomedical engineers, and GPO contracts managers informed operational capacity assumptions. Bottom-up installation counts and top-down healthcare expenditure triangulation cross-checked volume and value outputs.
Data-stream reconciliation across product type, technology modality, end-user facility tier, and cancer application segments anchored the analytical framework. CAGRs were derived from fitted growth curves applied to historical procurement patterns and projected replacement cycles. Forecast inputs incorporated PMDA approval pipeline visibility and METI reimbursement schedule revisions throughout the projection horizon.
Regulatory delays, superconducting magnet supply disruptions, and linear accelerator substitution ceilings are the dominant revision risks to modeled outcomes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market