
 Meningococcal Meningitis Treatment Market | 2026-2036
Meningococcal Meningitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Meningococcal Meningitis Treatment Market Foresight
The capability gap between plasma-derived vaccine manufacturers and recombinant protein specialists is collapsing as platform technologies commoditize. Pfizer leverages its mRNA infrastructure to compress development timelines for serogroup B formulations. GlaxoSmithKline (GSK) sustains dominance in pentavalent conjugate supply through long-term procurement contracts with Gavi, the Vaccine Alliance. Serum Institute of India anchors affordable access in low-income markets through high-volume fill-finish capacity.
Meningococcal meningitis treatment encompasses pharmacological and biological interventions targeting Neisseria meningitidis infection, with conjugate vaccines containing capsular polysaccharides chemically bound to carrier proteins to induce T-cell-dependent immune memory in infants. Intravenous ceftriaxone and vancomycin remain first-line acute therapies, reducing mortality from septicemia and meningeal inflammation. Vaccines command the largest value pool due to recurring immunization schedules and outbreak stockpiling, while intramuscular delivery dominates in field settings where cold-chain reliability constrains subcutaneous alternatives. Hospitals absorb the majority of acute treatment volumes, though home care settings are gaining traction for post-exposure prophylaxis completion.
FDA and EMA serogroup-specific labeling requirements shape clinical trial endpoints and regional launch sequencing, while WHO prequalification determines eligibility for UN procurement and national program inclusion. India's CDSCO accelerates local manufacturing approvals under its PLI scheme for critical vaccines, tightening import substitution timelines. Stakeholders must monitor serogroup epidemiological shifts and regulatory convergence on combination vaccine pathways to preserve portfolio relevance.
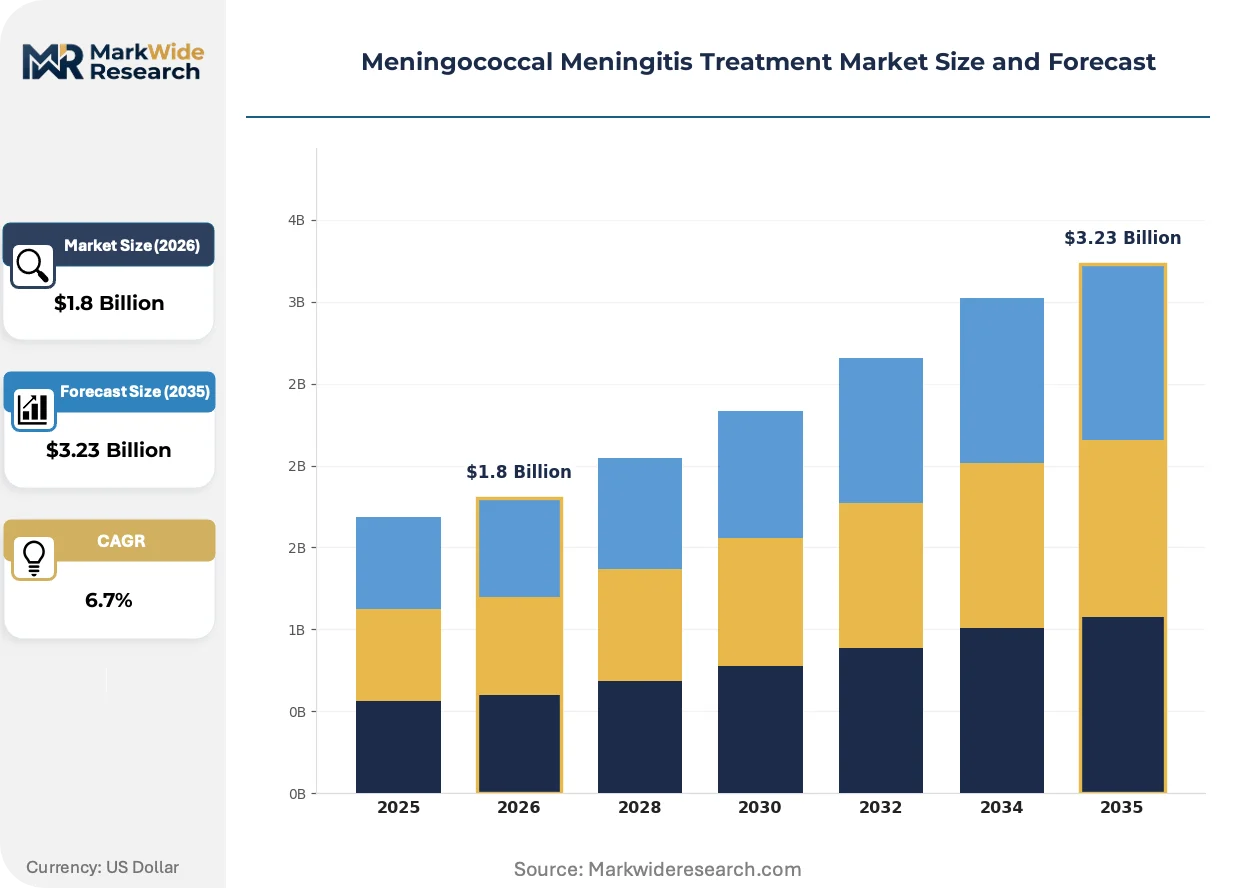
Market Dynamics
WHO prequalification standards are compressing supplier eligibility windows for endemic-country tenders, forcing manufacturers to accelerate serogroup coverage expansion or exit procurement pools entirely.
Growth Catalysts
- Gavi procurement contracts:Long-term volume commitments from the Vaccine Alliance de-risk manufacturing scale-up for pentavalent conjugate suppliers serving low-income markets.
- Sub-Saharan Africa immunization programs:Mass vaccination campaigns in Nigeria and neighboring belt countries consume donor-funded supplies at rates that sustain multi-year production planning.
- Recombinant protein platforms:mRNA infrastructure repurposing is collapsing development timelines for serogroup B formulations previously requiring complex plasma-derived processes.
Market Restraints
- Cold-chain infrastructure gaps:Field settings in remote districts lack reliable refrigeration, constraining subcutaneous delivery alternatives and raising wastage rates for temperature-sensitive conjugate doses.
- Serogroup epidemiological volatility:Shifting dominance between serogroups A, C, W, and Y forces manufacturers to maintain redundant production lines or risk inventory obsolescence.
- Plasma supply concentration:Dependence on specialized donor pools for polysaccharide raw materials creates input bottlenecks when collection centers face regional health disruptions.
Strategic Opportunities
- Combination vaccine pathways:Regulatory convergence on pentavalent-plus formulations creates white space for suppliers able to integrate pneumococcal or Hib antigens into single-dose presentations.
- Post-exposure prophylaxis home completion:Shifting acute treatment follow-through from hospital wards to community settings opens demand for simplified intramuscular delivery devices.
- India PLI scheme acceleration:CDSCO fast-track approvals under production-linked incentives tighten import substitution timelines for critical vaccine manufacturing.
Industry Challenges
- Fill-finish talent scarcity:Aseptic processing expertise concentrates at a handful of contract manufacturers, creating recruitment competition that delays capacity expansion timelines.
- Serogroup-specific labeling fragmentation:FDA and EMA divergent clinical trial endpoint requirements force parallel study designs that inflate regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meningococcal Meningitis Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Antivirals, Corticosteroids Delivery Mode: Intravenous, Oral, Intramuscular, Subcutaneous End User: Hospitals, Clinics, Research Laboratories, Home Care Settings Treatment Protocol: Prevention, Acute Treatment, Clinical Trial, Post-Exposure Prophylaxis |
| Companies Covered | Pfizer, GlaxoSmithKline (GSK), Sanofi, Merck & Co., Novartis, Serum Institute of India, Johnson & Johnson, CSL Limited, Bharat Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meningococcal Meningitis Treatment Market Shifts & Advancements
Platform technology commoditization is collapsing the capability gap between established plasma-derived manufacturers and recombinant specialists, redrawing competitive boundaries across conjugate and protein-based formulations.
Lyophilized vaccine presentations are miniaturizing cold-chain requirements for last-mile distribution in tropical climates. National immunization programs in Nigeria and Niger are adopting these stable formulations to reduce field wastage. This technology is miniaturizing the infrastructure footprint required for meningococcal belt campaigns, enabling subnational governments to run autonomous supplementary immunization activities without centralized refrigeration dependency.
EMA serogroup-specific labeling harmonization efforts are compressing regional launch sequencing timelines for multivalent candidates. Manufacturers now design pivotal trials to satisfy both FDA immunogenicity thresholds and EMA correlate-of-protection standards simultaneously. Pediatric indication holders face accelerated comparator arm requirements that favor sponsors with existing pentavalent approval dossiers.
Donor-funded procurement pools are consolidating tender specifications around WHO prequalified suppliers, squeezing non-prequalified manufacturers from national program inclusion. UNICEF Supply Division and PAHO Revolving Fund now coordinate serogroup demand forecasts across 26 countries, replacing fragmented bilateral purchasing. This concentration is most visible in Nigeria, where federal and state-level budgets align to Gavi co-financing schedules that prioritize prequalified pentavalent supply.
Meningococcal Meningitis Treatment Market Segmentation
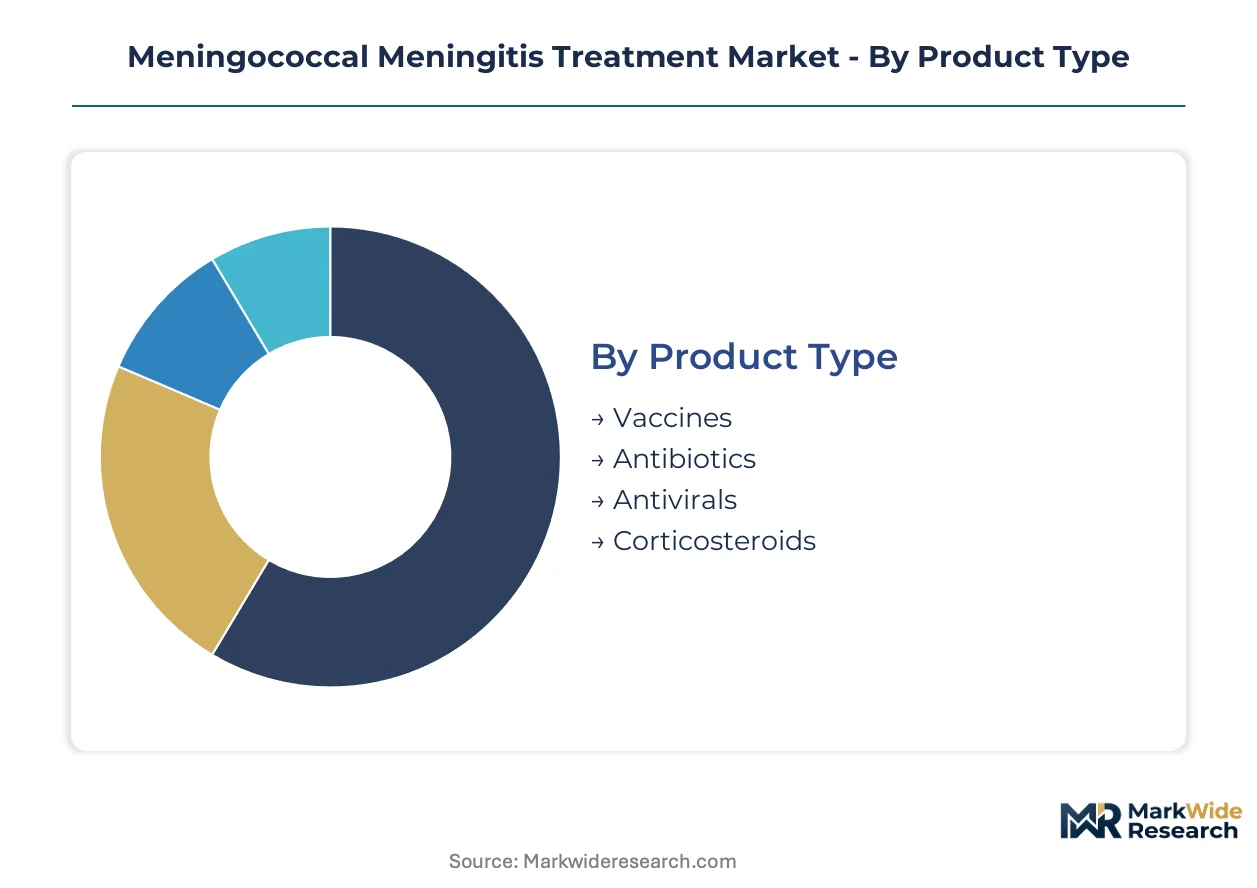
Meningococcal meningitis treatment segments diverge sharply in substitution vulnerability. Vaccines face recombinant platform displacement, while antibiotics confront resistance-driven protocol shifts. Understanding these pressure gradients shapes portfolio prioritization across manufacturers.
Product Type:
Conjugate vaccines absorb the strongest substitution pressure as mRNA platforms collapse development timelines for serogroup B coverage.
- Vaccines:Capsular polysaccharides chemically bound to carrier proteins induce T-cell-dependent immune memory in infants. Nigeria's federal immunization programs and Gavi co-financing schedules concentrate demand for pentavalent presentations, though cold-chain gaps in remote districts constrain field deployment.
- Antibiotics:Intravenous ceftriaxone and vancomycin remain first-line acute therapies for septicemia and meningeal inflammation. Hospital wards across sub-Saharan Africa's meningitis belt consume the largest volumes, yet rising resistance patterns in Neisseria meningitidis strains threaten protocol durability.
- Antivirals:Adjunctive agents targeting co-infections in immunocompromised patients.
- Corticosteroids:Anti-inflammatory adjuncts for cerebral edema management in severe presentations.
Vaccines retain volume leadership; antibiotics hold the steepest expansion curve as resistance surveillance intensifies.
Delivery Mode:
Cost tier stratification separates capital-intensive intravenous infrastructure from portable intramuscular alternatives.
- Intravenous:Continuous infusion systems for ceftriaxone and vancomycin in intensive care settings. Tertiary hospitals in Nigeria's urban centers anchor demand, though catheter-related infection risks complicate prolonged therapy courses.
- Intramuscular:Simplified devices enabling community-based post-exposure prophylaxis completion. Last-mile distribution networks in Niger and Chad favor these presentations where cold-chain reliability falters.
- Oral:Rifampin and ciprofloxacin tablets for household contact prophylaxis.
- Subcutaneous:Alternative vaccine delivery where refrigeration constraints limit conjugate dose viability.
Intravenous maintains revenue concentration; intramuscular gains share fastest as home care protocols expand.
End User:
Application intensity varies by acute versus preventive care orientation.
- Hospitals:Absorb the majority of acute treatment volumes through emergency departments and infectious disease wards. Nigeria's teaching hospitals and federal medical centers handle the highest case burdens during seasonal outbreak peaks.
- Clinics:Primary health centers conduct routine immunization and initial fever screening. Niger's district health systems rely on these facilities for vaccine cold-chain maintenance.
- Research Laboratories:Serogroup surveillance and antimicrobial susceptibility testing.
- Home Care Settings:Emerging traction for prophylaxis completion and recovery monitoring.
Hospitals dominate acute episode value; home care settings climb the fastest as follow-through protocols decentralize.
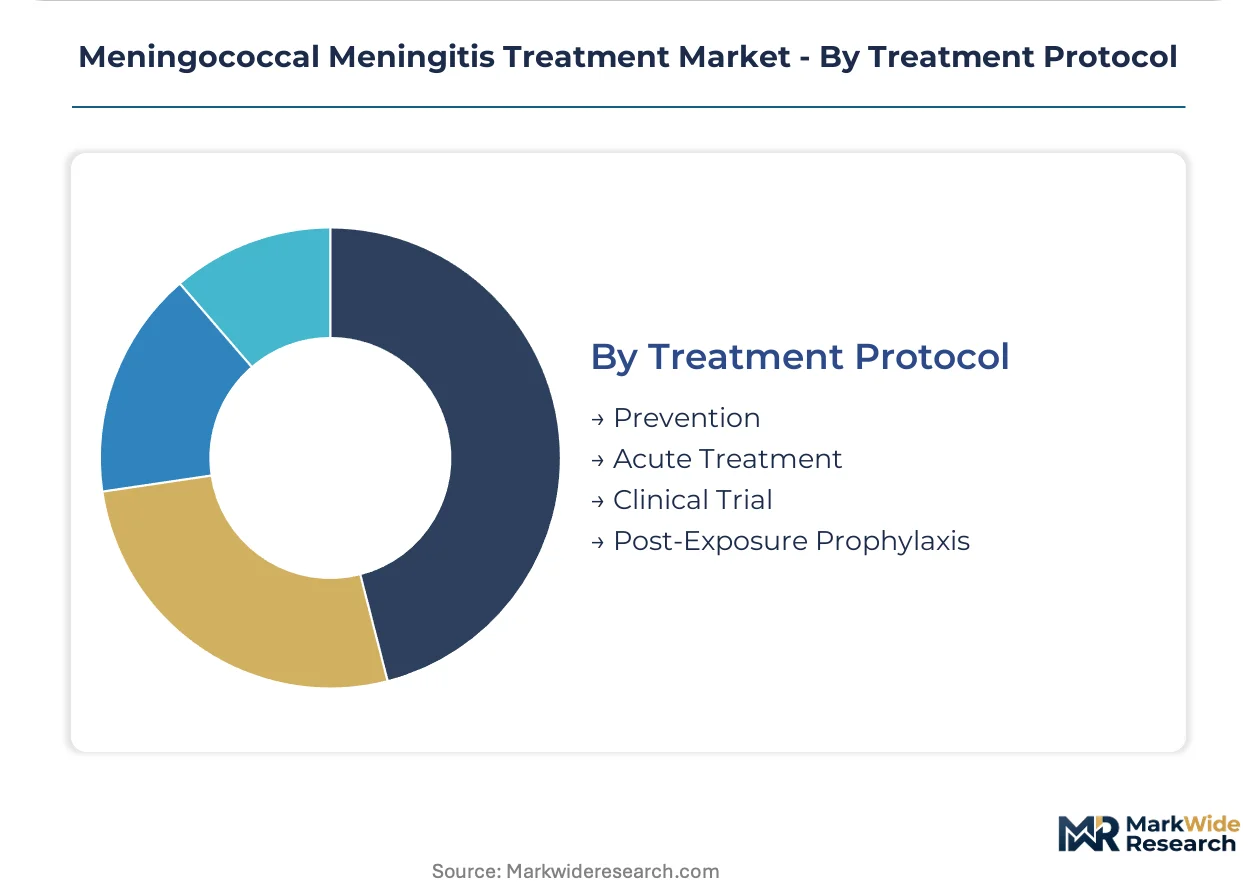
Treatment Protocol:
Volume concentration tracks outbreak response cycles versus routine immunization schedules.
- Prevention:Mass vaccination campaigns and routine pediatric schedules in endemic countries. Nigeria's national program inclusion criteria prioritize pentavalent conjugate procurement through Gavi-aligned tenders.
- Acute Treatment:Emergency antibiotic administration and supportive care during confirmed meningitis episodes. Seasonal surges across the African meningitis belt strain hospital capacity and drive surge procurement.
- Clinical Trial:Serogroup-specific immunogenicity studies for regulatory submissions.
- Post-Exposure Prophylaxis:Household and close-contact antibiotic courses following index case identification.
Prevention commands recurring revenue; acute treatment expands most quickly as surveillance networks shorten outbreak detection intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for conjugate vaccines concentrates in African meningitis belt countries, while export capacity clusters among Indian and European fill-finish specialists. Donor procurement pools now coordinate demand forecasts across twenty-six nations, replacing fragmented bilateral purchasing.
Nigeria
Federal and state-level immunization programs consume the largest share of Gavi co-financed pentavalent supplies. WHO prequalification standards determine eligibility for national program inclusion. Lagos and Abuja anchor cold-chain distribution networks that supply district health systems across the northern meningitis belt.
India
CDSCO fast-track approvals under the PLI scheme accelerate local manufacturing substitution for critical vaccines. Serum Institute of India anchors high-volume fill-finish capacity serving low-income markets. Pune and Hyderabad cluster aseptic processing expertise that supplies UNICEF procurement pools.
United States
FDA serogroup-specific labeling requirements shape clinical trial endpoints for multivalent candidates. Massachusetts and California concentrate mRNA infrastructure repurposing for serogroup B formulation development. Biotech corridors around Boston and San Francisco compress development timelines through platform technology integration.
Germany
EMA harmonization efforts on correlate-of-protection standards compress regional launch sequencing timelines. Bavaria and Baden-Württemberg host regulatory consulting clusters that guide parallel FDA-EMA submission strategies. Frankfurt anchors logistics coordination for pentavalent distribution across European reference markets.
Brazil
ANVISA alignment with WHO prequalification pathways streamlines national program inclusion for imported conjugate vaccines. São Paulo and Rio de Janeiro concentrate hospital procurement for acute antibiotic therapies. State-level immunization programs coordinate with PAHO Revolving Fund for outbreak response stockpiling.
Meningococcal Meningitis Treatment Market Competitive Landscape
Concentration sits with multinational vaccine specialists and high-volume emerging market suppliers. The supplier base stratifies across three tiers: platform technology leaders, fill-finish scale operators, and regional procurement specialists. Two archetypes dominate competitive positioning—mRNA infrastructure deployers and Gavi-contracted pentavalent suppliers. Capacity expansion and serogroup coverage diversification represent the dominant competitive moves reshaping procurement eligibility.
Within the platform technology tier, Pfizer and GlaxoSmithKline occupy positions that exemplify divergent scale strategies, while Serum Institute of India represents the high-volume, emerging-market archetype anchoring affordable access through production-linked incentive alignment. These three entities collectively illustrate how regulatory convergence on WHO prequalification standards and Gavi procurement contracts now determines supplier survival in endemic-country tenders.
| Leading Market Players |
|---|
| Pfizer |
| GlaxoSmithKline (GSK) |
| Sanofi |
| Merck & Co. |
| Novartis |
| Serum Institute of India |
| Johnson & Johnson |
| CSL Limited |
| Bharat Biotech |
| Others |
Supply & Pricing Matrix
High-volume fill-finish capacity utilization at Serum Institute of India and GSK's Belgian network compresses unit economics for pentavalent conjugate doses, concentrating pricing power among WHO-prequalified suppliers while squeezing non-prequalified manufacturers from Gavi co-financed tenders in Nigeria and Niger.
Pricing Analysis
Donor-funded procurement pools anchor contract-based long-term offtake structures, with UNICEF Supply Division and PAHO Revolving Fund consolidating tender specifications around prequalified pentavalent supply. Price differentiation separates Gavi-contracted volume tiers from commercial hospital procurement in urban Nigerian centers, where cold-chain reliability premiums apply. Cost compression in donor-funded segments intensifies as India's PLI scheme accelerates local manufacturing substitution. Government immunization programs exhibit highest price sensitivity; private hospital networks in Lagos and Abuja absorb modest premiums for lyophilized presentations.
Supply Chain Analysis
Aseptic processing expertise concentration in Pune, Hyderabad, and Bavaria underwrites global conjugate vaccine output, with fill-finish talent scarcity creating recruitment competition that delays capacity expansion timelines. Plasma-derived polysaccharide raw materials draw from specialized donor pools in the United States and Europe, while carrier protein production rests on recombinant fermentation capacity in India and Germany. Single-source vulnerability concentrates in mRNA lipid nanoparticle suppliers for serogroup B formulations. Distribution runs through UNICEF's Copenhagen hub and regional cold-chain depots in Lagos and Nairobi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of aseptic processing specialists capable of WHO-prequalified fill-finish operations constrains supplier expansion, rewarding incumbents with locked-in procurement eligibility while forcing new entrants toward platform technology differentiation or regional niche capture.
For Market Incumbents: Shield Gavi contract renewals through accelerated serogroup B coverage expansion using repurposed mRNA infrastructure, while securing backward integration into carrier protein fermentation to reduce plasma supply concentration exposure. Certification investment in CDSCO fast-track pathways under India's PLI scheme tightens import substitution timelines against emerging local competitors. For New Entrants and Emerging Players: Differentiate on lyophilized presentation miniaturization for last-mile distribution in Chad and Niger's district health systems, where cold-chain gaps constrain incumbent conjugate deployment. Target post-exposure prophylaxis home completion protocols with simplified intramuscular delivery devices, leveraging clinician training partnerships with Nigeria's federal medical centers as go-to-market anchor. For Investors and Strategic Acquirers: Emerging-market fill-finish specialists with existing WHO prequalification dossiers offer acquisition exposure to locked-in donor procurement pools. Long-term viability hinges on serogroup epidemiological surveillance integration and combination vaccine pathway readiness. Watch EMA-FDA labeling harmonization progress as inflection indicator for multivalent candidate launch sequencing compression.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks UNICEF and Gavi procurement eligibility across 26 endemic countries. |
| Recombinant Platform Repurposing | Collapses serogroup B development timelines using existing mRNA infrastructure. |
| Lyophilized Presentation Development | Miniaturizes cold-chain requirements for autonomous district-level campaigns in Niger. |
| CDSCO PLI Alignment | Accelerates Indian manufacturing substitution through production-linked incentive qualification. |
| Combination Vaccine Integration | Captures pentavalent-plus white space via pneumococcal or Hib antigen co-formulation. |
Research Methodology
A standing panel of vaccine development executives, regulatory affairs leads at EMA and FDA, Gavi procurement specialists, and Nigerian federal immunization program managers provided ongoing calibration across primary interview cycles. Secondary validation drew from WHO prequalification listings, ClinicalTrials.gov serogroup-specific immunogenicity studies, CDSCO approval databases under the PLI scheme, and UNICEF Supply Division tender archives. Bottom-up demand modeling across patient populations and treatment protocols triangulated against top-down epidemiological surveillance data from the African meningitis belt.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by product type, delivery mode, end user, and treatment protocol, with regional regulatory clusters modeled separately. CAGRs derived from epidemiological trend extrapolation, immunization program expansion schedules, and outbreak response stockpiling patterns. Forecast inputs incorporated serogroup shift probabilities and cold-chain infrastructure deployment timelines in sub-Saharan Africa.
The analysis sits within stated boundaries; outcomes outside sustained Gavi financing commitments, WHO prequalification standard stability, or serogroup epidemiological continuity would require recalibration. Forecasts reflect documented assumptions regarding donor procurement pool consolidation and platform technology commoditization trajectories. Practitioners should keep alternative scenarios live as EMA-FDA regulatory convergence and India's PLI scheme acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Angelman Syndrome Treatment Market