
 Global Gaucher Disease Market | 2026-2036
Global Gaucher Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gaucher Disease Market Foresight
EMA's updated orphan drug guidance is realigning reimbursement thresholds across European markets. Sanofi leverages its manufacturing scale to sustain supply continuity for imiglucerase. Takeda Pharmaceutical Company Limited anchors its position through substrate reduction therapy specialization. Pfizer competes via channel control across hospital pharmacy networks in established markets.
Gaucher disease constitutes a lysosomal storage disorder arising from glucocerebrosidase enzyme deficiency, characterized by lipid accumulation in macrophages that triggers hepatosplenomegaly, cytopenia, and skeletal complications. Enzyme replacement therapy dominates clinical protocols through intravenous infusions of recombinant glucocerebrosidase. Substrate reduction therapy captures expanding share among patients with milder Type 1 presentations who cannot tolerate infusion schedules. Gene therapy represents the fastest-growing segment as investigational programs advance through regulatory pipelines, though manufacturing complexity constrains near-term margin pools.
FDA orphan drug exclusivity provisions shape developer incentives by granting seven-year market protection for novel Gaucher therapies. EMA parallel scientific advice and WHO prequalification pathways influence trial design and access strategies for emerging-market entry. Stakeholders must monitor how payer consolidation in Germany and France reshapes pricing negotiations for chronic rare-disease treatments.
Market Dynamics
Gene therapy manufacturing scale-up is compressing development timelines while recombinant enzyme supply chains face yield constraints from mammalian cell culture dependencies. This structural tension between next-platform investment and incumbent production economics defines competitive positioning.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market protection provisions accelerate developer commitment to novel Gaucher modalities by de-risking commercialization timelines for first-in-class entrants.
- Israeli Founder-Population Screening:High carrier frequency in Ashkenazi Jewish communities generates diagnostic volume concentration that sustains specialized treatment center viability.
- Substrate Reduction Therapy Tolerability:Oral small-molecule protocols expand addressable patient pools among infusion-intolerant Type 1 cases who previously discontinued enzyme replacement.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector production for gene therapy candidates depends on contract manufacturing organizations clustered in the United States and Switzerland, creating single-source vulnerability.
- Reimbursement Compression in Germany:AMNOG health technology assessment protocols impose reference pricing that erodes net revenue for chronic rare-disease infusions.
- Gene Therapy Manufacturing Yields:Transfection efficiency limitations in HEK293 suspension systems constrain batch sizes and extend lead times for clinical-grade material.
Strategic Opportunities
- Brazilian Rare Disease Framework:ANVISA's expanded access pathways and patient advocacy mobilization create first-mover advantage for developers establishing Latin American commercial infrastructure.
- In-Utero Enzyme Delivery:Maternal-fetal medicine protocols represent unpenetrated application space where prenatal intervention could modify disease trajectory before organ damage manifests.
- Real-World Evidence Mandates:EMA's patient registry requirements for conditional approvals create data monetization pathways through longitudinal outcome tracking subscriptions.
Industry Challenges
- Gene Therapy Talent Scarcity:Viral vector process development and analytical characterization expertise concentrates among a limited cohort of biologics specialists, inflating compensation and extending hiring cycles.
- Multi-Jurisdictional Patent Thickets:Glucocerebrosidase formulation and delivery device IP estates create licensing complexity that fragments freedom-to-operate for next-generation developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gaucher Disease Market |
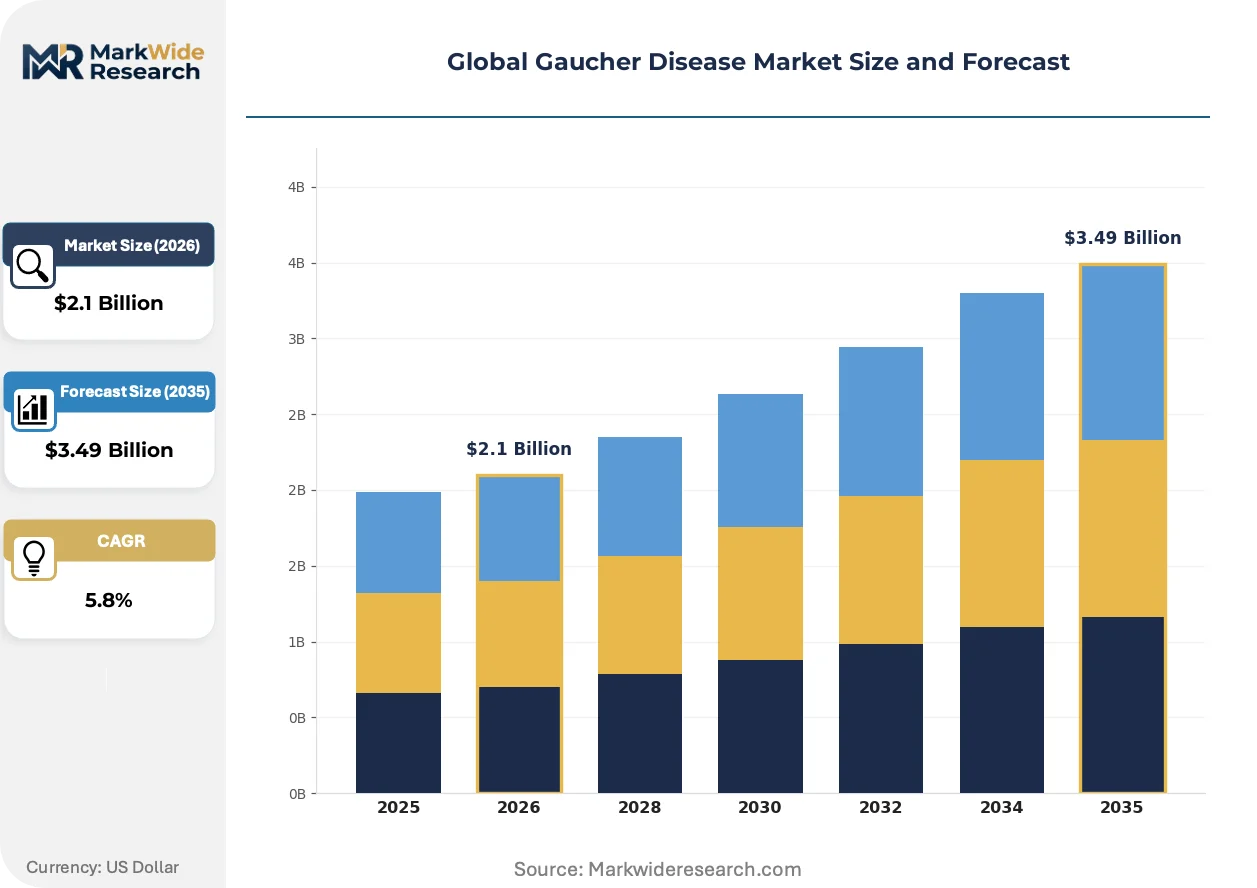
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Pharmacological Chaperones, Gene Therapy Therapy Area: Type 1 Gaucher, Type 2 Gaucher, Type 3 Gaucher, Perinatal Lethal Gaucher End User: Specialty Clinics, Research Institutes, Diagnostic Laboratories, Patient Support Organizations Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Sanofi, Takeda Pharmaceutical Company Limited, Johnson & Johnson, Pfizer, BioMarin Pharmaceutical, Amicus Therapeutics, Protalix BioTherapeutics, ISU Abxis, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gaucher Disease Market Shifts & Advancements
Next-generation sequencing integration with newborn screening programs is compressing diagnostic latency while redirecting patient flow toward preemptive intervention models. This shift from symptomatic detection to presymptomatic identification reconfigures treatment initiation protocols and long-term outcome measurement frameworks.
CRISPR-based in vivo gene editing is converging with lipid nanoparticle delivery systems to enable direct hepatic glucocerebrosidase correction without ex vivo cell manipulation. Academic medical centers in the United States and the Netherlands are advancing first-in-human protocols. This convergence is compressing the addressable gap between enzyme replacement palliation and definitive genetic cure.
EMA's updated orphan drug guidance tightens reimbursement thresholds by requiring comparative effectiveness evidence against existing standards of care rather than placebo-controlled superiority. Developers must now design head-to-head non-inferiority trials that extend regulatory timelines. Substrate reduction therapy sponsors face particular pressure as they target patient segments already stabilized on enzyme infusions.
Patient advocacy organizations are consolidating purchasing influence through centralized procurement negotiations that bypass traditional hospital pharmacy channels. Gaucher Disease International Collaborative's tender aggregation in European markets extracts volume discounts that reshape net pricing realization. This channel compression is most visible in France and Italy where regional health authority consolidation amplifies buyer leverage.
Global Gaucher Disease Market Segmentation
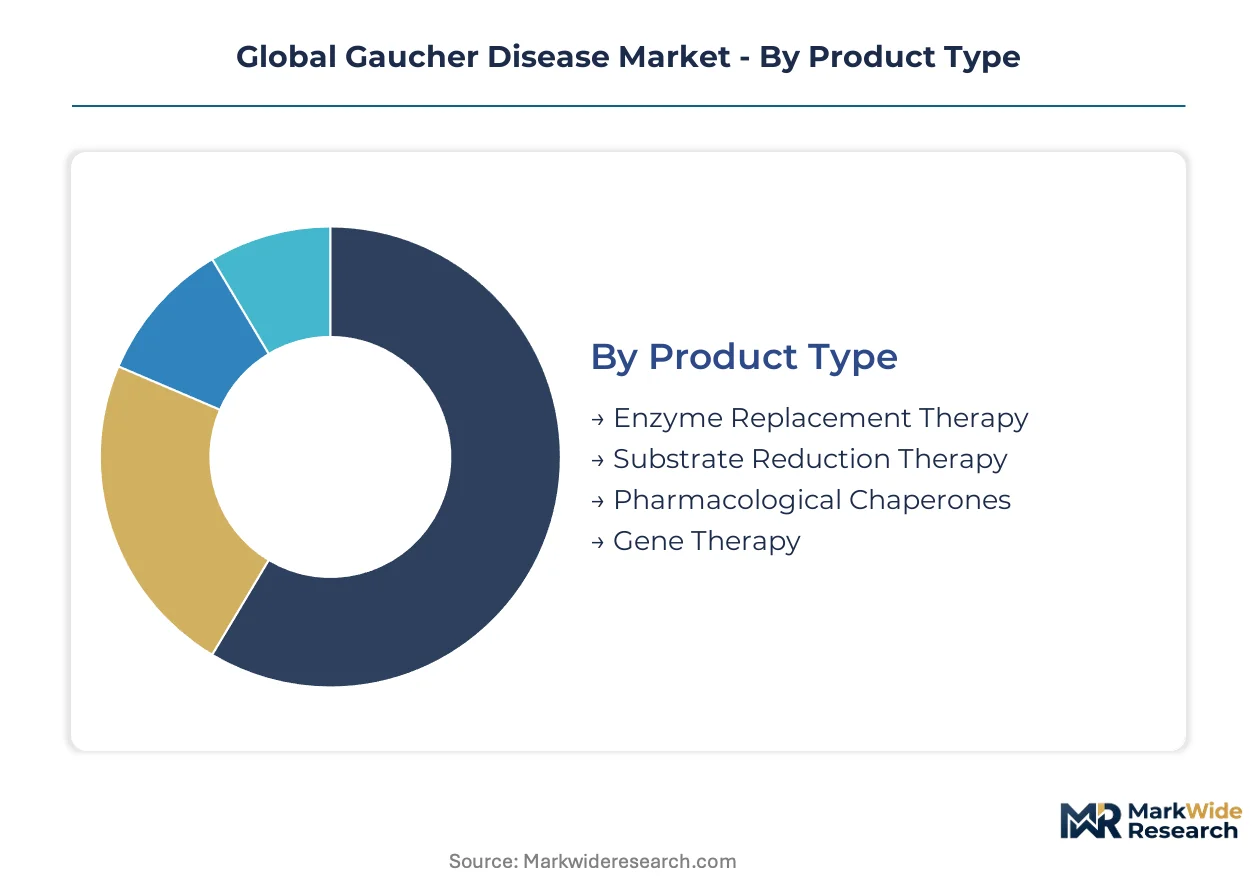
Segmentation in the Gaucher disease market reveals how regulatory pathways, clinical protocols, and patient access models diverge across treatment modalities. Understanding these divisions illuminates where development capital concentrates and which patient populations remain underserved by current commercial infrastructure.
Product Type:
FDA orphan drug designation and EMA parallel scientific advice requirements vary sharply across these segments, with gene therapy facing the steepest manufacturing validation burdens while small-molecule approaches navigate accelerated approval frameworks.
- Enzyme Replacement Therapy:Intravenous infusions of recombinant glucocerebrosidase remain the clinical standard, with imiglucerase and velaglucerase alfa dominating hospital pharmacy procurement in the United States and Israel. Specialty infusion centers in Tel Aviv and New York sustain the highest patient throughput volumes globally.
- Substrate Reduction Therapy:Oral eliglustat and miglustat target milder Type 1 presentations, expanding access among patients who cannot tolerate biweekly infusion schedules. Demand concentrates in Germany and France where AMNOG assessments have compressed reimbursement timelines for chronic rare-disease oral therapies.
- Pharmacological Chaperones:Small-molecule stabilizers of mutant glucocerebrosidase address residual enzyme activity in select genotypes, requiring companion diagnostic alignment with sequencing infrastructure.
- Gene Therapy:Lentiviral and AAV vector programs advancing through FDA IND-enabling studies face plasmid DNA supply constraints from concentrated contract manufacturing capacity in Switzerland and the United States.
Enzyme Replacement Therapy sits at the top of the volume ranking, with Gene Therapy climbing the fastest.
Therapy Area:
Clinical trial design and endpoint selection diverge across these phenotypic categories, with neuronopathic forms requiring neurodevelopmental outcome measures that extend regulatory timelines versus visceral-focused Type 1 protocols.
- Type 1 Gaucher:Non-neuronopathic presentations account for the largest addressable population, with hepatosplenomegaly and cytopenia driving treatment initiation. Israeli founder-population screening generates diagnostic concentration that supports specialized center viability in Jerusalem and Haifa.
- Type 2 Gaucher:Acute neuronopathic disease presents in infancy with rapid neurodegeneration, creating ethical complexity in trial design and limited commercial viability despite high unmet need.
- Type 3 Gaucher:Chronic neuronopathic forms require longitudinal cognitive and oculomotor assessment protocols that complicate endpoint standardization across FDA and EMA jurisdictions.
- Perinatal Lethal Gaucher:Collodion baby presentations and hydrops fetalis represent diagnostic challenges where prenatal enzyme delivery protocols remain investigational.
Type 1 Gaucher captures the dominant revenue share, though Type 3 Gaucher is gaining attention fastest as substrate reduction therapy sponsors seek expansion indications.
End User:
Procurement authority and reimbursement negotiation leverage distribute unevenly across these settings, with hospital-affiliated specialty clinics holding concentrated purchasing power versus fragmented patient advocacy channels.
- Specialty Clinics:Academic medical centers in the United States, Israel, and the Netherlands anchor treatment volume, with NIH-designated lysosomal storage disorder programs in Bethesda and Minnesota setting clinical protocol standards.
- Research Institutes:Academic centers advancing CRISPR-based gene editing and in-utero enzyme delivery protocols depend on NIH and EU Horizon funding cycles that shape translational timelines.
- Diagnostic Laboratories:Newborn screening expansion in New York, Illinois, and Israel drives glucocerebrosidase activity assay demand, with next-generation sequencing integration compressing diagnostic latency.
- Patient Support Organizations:Gaucher Disease International Collaborative aggregates European tender negotiations, extracting volume discounts that reshape net pricing realization in France and Italy.
Specialty Clinics command the highest procurement volume, while Patient Support Organizations are expanding their negotiating influence fastest.
Distribution Channel:
Cold-chain requirements and infusion supervision needs constrain channel flexibility, with hospital pharmacy capture rates highest for parenteral therapies and oral agents penetrating retail and direct channels.
- Hospital Pharmacies:Intravenous enzyme replacement concentrates in hospital outpatient departments where infusion supervision and adverse event management protocols are mandated. Procurement consolidation in Germany's university hospital networks amplifies buyer leverage.
- Retail Pharmacies:Oral substrate reduction therapies achieve limited retail penetration where specialty pharmacy carve-outs dominate rare-disease dispensing in the United States.
- Online Pharmacies:Direct-to-patient delivery models face reimbursement complexity for biologics requiring cold-chain integrity, though oral small molecules show expansion potential.
- Direct Sales:Manufacturer patient assistance programs and hub services bypass traditional pharmacy channels for uninsured or underinsured populations in Brazil and other emerging markets.
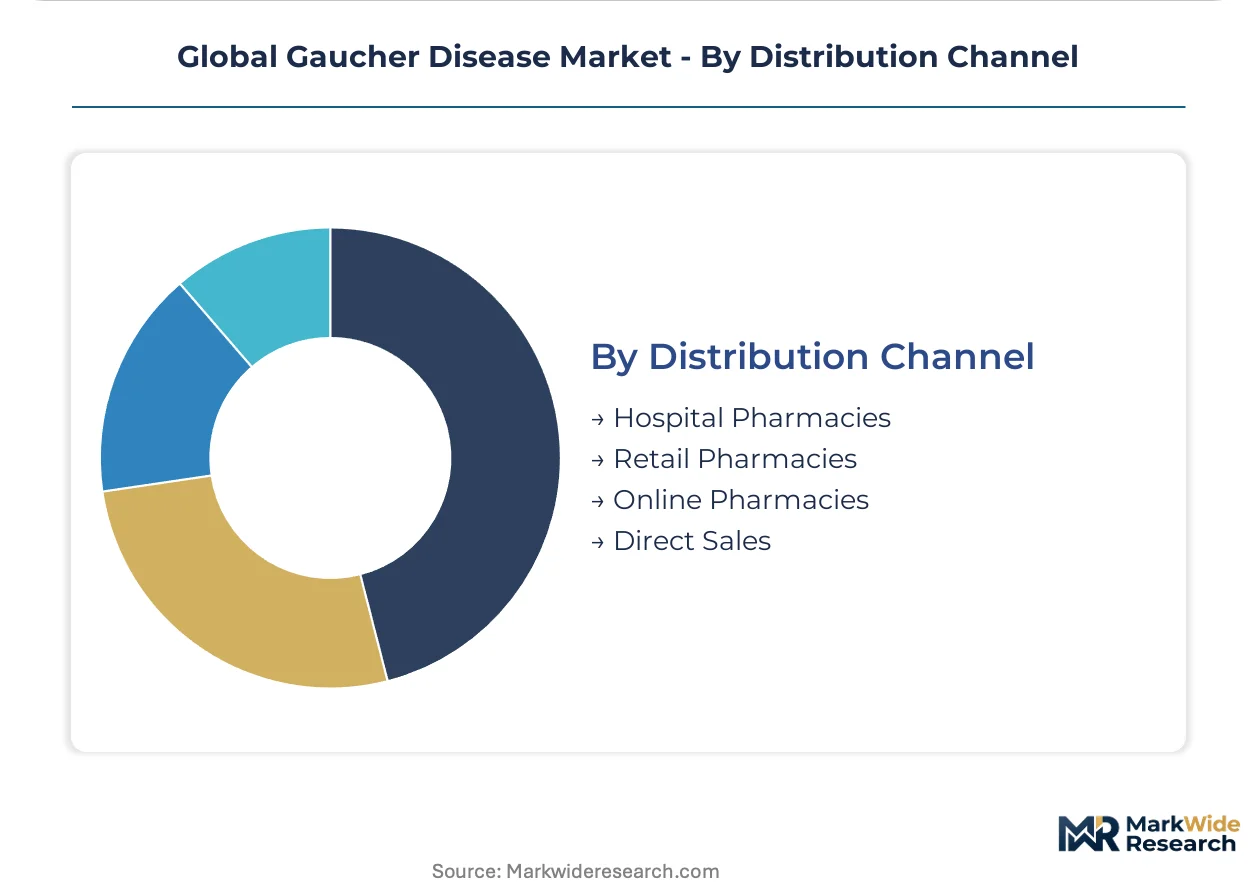
Hospital Pharmacies retain the dominant channel position, with Direct Sales expanding most quickly as manufacturers build emerging-market infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lysosomal storage disorder specialists cluster in academic medical centers across five countries that anchor clinical trial density and patient access infrastructure for Gaucher therapies.
United States
NIH-designated centers in Bethesda and Minnesota drive diagnostic throughput for Type 1 and neuronopathic variants. FDA orphan drug exclusivity provisions grant seven-year market protection that accelerates developer commitment to novel modalities. Specialty infusion networks in New York and California sustain the highest patient volumes globally for enzyme replacement protocols.
Israel
Founder-population screening in Ashkenazi Jewish communities generates diagnostic concentration unmatched elsewhere. The country's national health system mandates carrier testing that sustains specialized treatment center viability in Jerusalem and Haifa. Tel Aviv anchors biotechnology corridor development where preclinical gene therapy programs access venture funding.
Germany
AMNOG health technology assessment protocols impose reference pricing that compresses net revenue for chronic rare-disease infusions. University hospital networks in Munich and Heidelberg consolidate procurement authority that amplifies buyer leverage in pricing negotiations. The country's national pharmaceutical regulator enforces post-market surveillance requirements that extend compliance timelines.
Switzerland
Contract manufacturing organizations in Basel and Zurich concentrate plasmid DNA supply for viral vector production. Swissmedic maintains accelerated assessment pathways for gene therapy candidates that reduce regulatory latency. The country's precision medicine clusters attract talent from neighboring EU markets facing reimbursement constraints.
Brazil
ANVISA's expanded access pathways and patient advocacy mobilization create first-mover advantage for developers establishing Latin American commercial infrastructure. São Paulo anchors diagnostic laboratory expansion where newborn screening integration is compressing detection timelines. Direct sales models bypass traditional pharmacy channels for uninsured populations in southeastern states.
Global Gaucher Disease Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across enzyme replacement, substrate reduction, and gene therapy modalities. Sanofi and Takeda Pharmaceutical Company Limited anchor the consolidated tier through manufacturing scale and therapeutic specialization respectively. Johnson & Johnson and Pfizer leverage hospital pharmacy network control. Strategic moves concentrate on M&A for gene therapy platform acquisition and capacity expansion for mammalian cell culture yield improvement.
Among diversified pharmaceutical conglomerates, Sanofi and Pfizer occupy positions that exemplify scale-driven supply continuity and channel control archetypes respectively. Takeda Pharmaceutical Company Limited anchors the substrate reduction therapy specialization tier. Johnson & Johnson represents the hospital-affiliated diversified health products archetype. These three companies sit within competitive positions shaped by FDA and EMA regulatory pathway expertise rather than manufacturing technology differentiation alone.
| Leading Market Players |
|---|
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| Johnson & Johnson |
| Pfizer |
| BioMarin Pharmaceutical |
| Amicus Therapeutics |
| Protalix BioTherapeutics |
| ISU Abxis |
| AbbVie |
| Others |
Supply & Pricing Matrix
Gene therapy manufacturing scale-up is compressing cost economics while recombinant enzyme production dependencies sustain incumbent pricing power. This dual-platform dynamic concentrates supply leverage among mammalian cell culture specialists in Switzerland and the United States while fragmenting negotiation power across hospital pharmacy networks.
Pricing Analysis
Infusion supervision and cold-chain logistics bundle into enzyme replacement therapy pricing, separating premium hospital-administered protocols from unbundled oral substrate reduction alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from German university hospital networks. Price differentiation stems from after-sales service intensity and geographic delivery cost variation across Israeli specialty centers versus Brazilian direct-sales models. Cost compression in the oral therapy tier is intensifying because AMNOG reference pricing protocols erode net realization for chronic infusions. Patient advocacy organizations in France and Italy demonstrate highest price sensitivity through tender aggregation, while Swissmedic-accredited gene therapy candidates command least sensitivity due to manufacturing complexity barriers.
Supply Chain Analysis
Cold-chain freight costs for biologics concentrate distribution leverage among specialized logistics providers serving hospital pharmacy networks in the United States, Israel, and Germany. Plasmid DNA supply draws from contract manufacturing organizations clustered in Switzerland and the United States, with viral vector production feeding from HEK293 suspension culture systems. Raw material dependencies center on fetal bovine serum, specialized cell culture media, and GMP-grade plasmid DNA. Single-source vulnerability in plasmid DNA supply creates structural risk from concentrated contract manufacturing capacity. Distribution runs through hospital outpatient departments for parenteral therapies, with direct-to-patient channels emerging for oral small molecules in Brazilian southeastern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the Gaucher disease market rests on gene therapy manufacturing yield improvements and premium-tier pricing for neuronopathic indications. Substrate reduction therapy sponsors face compression from reference pricing protocols while enzyme replacement incumbents defend position through supply continuity investments.
For Market Incumbents: Anticipate gene therapy displacement pressure by securing mammalian cell culture yield improvements and expanding plasmid DNA supply partnerships in Switzerland. Defend channel control through hospital pharmacy network exclusivity arrangements in NIH-designated centers. Prioritize regulatory affairs investment for EMA parallel scientific advice to compress approval timelines for next-generation formulations. For New Entrants and Emerging Players: Launch via direct sales models in Brazilian southeastern states where ANVISA expanded access pathways bypass traditional procurement channels. Target in-utero enzyme delivery protocols as the most penetrable application space with unmet clinical need and limited incumbent presence. Establish Latin American commercial infrastructure ahead of competitor gene therapy scale-up to capture first-mover advantage in emerging-market access. For Investors and Strategic Acquirers: Valuations sit cheapest among substrate reduction therapy specialists facing AMNOG reimbursement compression and oral therapy commoditization. Long-term viability favors gene therapy platform developers with demonstrated transfection efficiency improvements and Swiss contract manufacturing relationships. Watch CRISPR-based in vivo editing program advancement through FDA IND-enabling studies as the primary inflection indicator for next-platform displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | HEK293 suspension system yield improvements compress cost economics for lentiviral vector production. |
| EMA Parallel Scientific Advice Engagement | Head-to-head trial design against imiglucercerase standard reduces regulatory latency for novel entrants. |
| Plasmid DNA Supply Partnership | Swiss and United States contract manufacturing concentration creates single-source vulnerability requiring diversification. |
| Patient Registry Data Monetization | EMA longitudinal outcome tracking mandates create subscription revenue pathways for real-world evidence platforms. |
| In-Utero Delivery Protocol Development | Prenatal intervention models redirect patient flow toward preemptive treatment before organ damage manifests. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative assessment of commercial infrastructure and reimbursement dynamics. Secondary validation drew from FDA orphan drug filings, EMA scientific advice minutes, ClinicalTrials.gov protocol registrations, and Israeli national health system formulary databases. Bottom-up patient volume modeling across Type 1, Type 2, and Type 3 phenotypes triangulated against top-down revenue estimates from hospital pharmacy procurement records and patient advocacy organization tender disclosures.
Bottom-up modeling segmented the analysis window by treatment modality, patient population severity, administration route, and regional regulatory cluster. Top-down verification anchored on specialty clinic throughput data from NIH-designated centers in Bethesda and Minnesota, plus diagnostic laboratory volume from Israeli founder-population screening programs. CAGRs derived from enrollment velocity in gene therapy IND-enabling studies and substrate reduction therapy expansion indication timelines. Forecast inputs incorporated AMNOG assessment protocol changes and ANVISA expanded access pathway utilization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gene therapy manufacturing yield breakthroughs or plasmid DNA supply disruptions. Forecasts reflect assumptions regarding EMA reimbursement threshold evolution and Brazilian rare disease framework implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market